
 Specialty Lubricants Market | 2026-2036
Specialty Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Lubricants Market Analysis
Germany is tilting toward expanded synthetic lubricant blending capacity to serve precision manufacturing and offshore wind clusters. Fuchs Petrolub SE leverages its Stuttgart headquarters to anchor European R&D for high-temperature industrial formulations. Shell plc competes through backward integration into Group III base oil production, while ExxonMobil Corporation extends its synthetic fluid portfolio across aerospace certification channels. TotalEnergies SE specializes in biodegradable marine lubricants that navigate stricter port-state discharge rules.
Specialty lubricants are formulated products engineered with precise viscosity indices, additive packages, and base stock selections to perform under extreme pressure, temperature, or chemical exposure conditions. Their primary purpose is to reduce friction, prevent wear, and extend equipment life in applications where commodity lubricants fail. Synthetic formulations command premium positioning due to thermal stability demands from aerospace turbine engines and wind turbine gearboxes. Biodegradable lubricants represent the fastest-expanding formulation category as port authorities and construction regulators tighten environmental discharge protocols. Mineral oil based products still occupy volume leadership in legacy industrial equipment across emerging manufacturing bases.
The EPA enforces Vessel General Permit standards that shape marine lubricant formulation requirements in United States waters. REACH and the EU Green Deal are forcing reformulation timelines across European supply chains, while China's MEE implements emission-linked manufacturing audits that affect base oil import flows. Stakeholders must monitor how regulatory divergence between Brussels and Beijing fragments product registration requirements and reshapes regional sourcing strategies.
Market Dynamics
REACH reformulation timelines and EPA Vessel General Permit standards are forcing simultaneous portfolio restructuring across European and North American supply chains, compressing product development cycles while biodegradable base stock availability lags specification tightening.
Growth Catalysts
- Aerospace turbine thermal stability demands:Next-generation geared turbofan architectures require synthetic ester formulations with oxidative resistance beyond Group III mineral capabilities. Maintenance program expansion across MRO networks in Singapore, Germany, and the United States concentrates consumption.
- EU Green Deal port discharge protocols:The European Commission's maritime decarbonization framework mandates biodegradable stern tube lubricants for vessels calling at Rotterdam, Hamburg, and Antwerp. Formulators with EAL certification capture preferential procurement from Scandinavian ferry operators.
- Wind turbine gearbox scaling:15 MW+ offshore units deploy PAO and PAG synthetic fluids for pitch bearing and main bearing applications. Installation clusters off Scotland, Taiwan, and Massachusetts drive specification harmonization toward 10-year fill intervals.
Market Restraints
- Group IV/V base oil supply concentration:Polyalphaolefin and ester feedstock production concentrates among integrated petrochemical complexes in Texas, Singapore, and Belgium. Specialty blenders face captive allocation risk during upstream turnaround cycles.
- Biodegradable additive package immaturity:Zinc-free anti-wear chemistries and ashless dispersants for EAL formulations exhibit hydrolytic instability versus conventional ZDDP systems. Performance gaps persist in high-pressure hydraulic applications.
- REACH registration cost escalation:ECHA substance evaluation dossiers for novel synthetic base stocks exceed EUR 500,000 per registration. Mid-tier formulators defer portfolio expansion, ceding position to multi-nationals with dedicated regulatory affairs infrastructure.
Strategic Opportunities
- India precision manufacturing emergence:The country's PLI scheme for machine tools and textile machinery creates first-mover positioning for synthetic cutting fluid and spindle oil suppliers. Domestic blending capacity remains underdeveloped versus demand from Gujarat and Tamil Nadu industrial corridors.
- Food-grade lubricant certification convergence:NSF H1 registration harmonization with ISO 21469 hygiene protocols opens pharmaceutical and beverage packaging machinery segments. Formulators with dual certification capture maintenance contract bundling opportunities.
- Carbon intensity disclosure requirements:EU CSRD scope 3 reporting mandates lubricant procurement decisions based on lifecycle emissions data. Suppliers with ISO 14040-compliant product carbon footprints secure preferred supplier status with automotive OEM sustainability programs.
Industry Challenges
- Tribochemistry modeling talent scarcity:Formulation chemistry roles requiring surface science and elastomer compatibility expertise remain unfilled across European R&D centers. Universities have de-prioritized lubrication engineering curricula since 2010.
- Legacy equipment compatibility validation:Synthetic fluid retrofits into mineral-oil-sealed gearboxes and compressors demand elastomer swap-out protocols. End-user risk aversion extends pilot trial durations beyond 24 months in process industries.
- Aerospace certification timeline compression:SAE AS5780 and MIL-PRF-23699 specification updates require re-qualification of entire additive packages. Test cell availability at FAA-designated facilities creates 18-month backlog for new synthetic ester submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Lubricants Market |
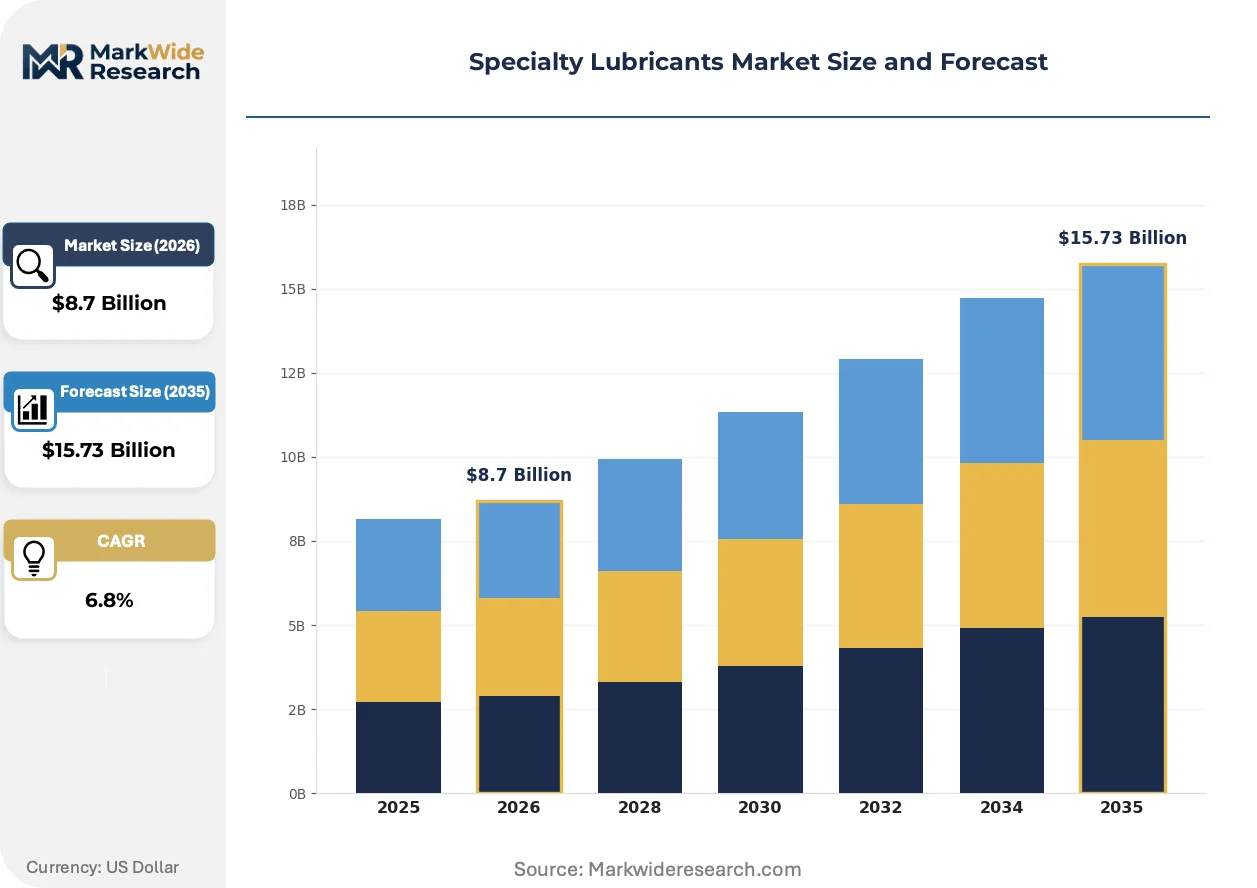
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greases, Oils, Molybdenum Disulfide, Synthetic Fluids Application: Aerospace, Automotive, Industrial Equipment, Marine End User: Manufacturing, Transportation, Energy, Construction Formulation: Biodegradable, Mineral Oil Based, Synthetic, Semi-Synthetic |
| Companies Covered | Chevron Corporation, Fuchs Petrolub SE, ExxonMobil Corporation, Valvoline Inc., Sinopec Corporation, Shell plc, BP p.l.c., Idemitsu Kosan Co. Ltd., TotalEnergies SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Lubricants Market Emerging Trajectories
Digital condition monitoring integration and predictive maintenance platforms are restructuring how lubricant value is captured, shifting revenue models from product volume toward performance guarantees tied to equipment uptime.
Online particle counters and dielectric sensors embedded in wind turbine gearboxes and steel mill hydraulic systems transmit viscosity degradation and contamination data to cloud analytics platforms. Equipment operators in Germany and Denmark now specify lubricant supply contracts with predictive drain interval optimization. This sensor-to-action architecture is digitizing traditional time-based maintenance schedules into condition-responsive lubricant logistics.
EPA Vessel General Permit 2013 standards and subsequent state-level California and Washington ballast water discharge rules mandate environmentally acceptable lubricants for all oil-to-sea interfaces. Marine operators face port state control detention risk for non-compliant stern tube fluids. The regulatory cascade is accelerating EAL formulation investment among suppliers serving Pacific Northwest and Gulf Coast shipping lanes.
After-sales service unbundling is fragmenting traditional distributor relationships in North American industrial maintenance. End-users now procure base lubricants through integrated supply contracts while sourcing technical field support separately from independent reliability consultants. This purchasing bifurcation is most advanced among pulp and paper mills in Wisconsin and chemical processors along the Texas Gulf Coast, where in-house tribology teams specify directly from blenders.
Specialty Lubricants Market Segmentation
Specialty lubricant procurement decisions hinge on equipment criticality, regulatory exposure, and fill interval economics. Formulation chemistry and application environment together determine pricing tiers and supplier qualification requirements across industrial end-use segments.
Product Type:
Cost tier positioning separates commodity-adjacent mineral formulations from synthetic premium grades engineered for extreme operating windows.
- Synthetic Fluids:Engineered from Group IV/V base stocks with precisely calibrated viscosity indices and oxidative stability packages. Demand concentrates in aerospace turbine maintenance programs across Germany, Singapore, and the United States where thermal degradation resistance dictates specification compliance.
- Oils:Spanning hydraulic, compressor, and turbine fluid categories with additive architectures tailored to contamination tolerance and elastomer compatibility requirements. Wind turbine gearbox scaling off Scotland and Taiwan drives specification harmonization toward decade-long fill intervals.
- Greases:Thickened lubricants delivering boundary lubrication under shock loads and slow-speed conditions.
- Molybdenum Disulfide:Solid-film lubricants for extreme pressure applications beyond fluid film capabilities.
Synthetic fluids command the established base. The steepest expansion runs through biodegradable formulation oils.
Application:
Application environment dictates regulatory exposure severity and technical specification complexity across end-use verticals.
- Aerospace:Synthetic ester formulations meeting SAE AS5780 and MIL-PRF-23699 thermal stability thresholds for geared turbofan architectures. Maintenance program expansion across MRO networks in Singapore, Germany, and the United States concentrates consumption growth.
- Marine:Environmentally acceptable lubricants navigating EPA Vessel General Permit and EU port discharge protocols. Rotterdam, Hamburg, and Antwerp procurement specifications mandate biodegradable stern tube fluids for vessel operators.
- Automotive:Precision manufacturing fluids for powertrain assembly and electric vehicle thermal management systems.
- Industrial Equipment:General machinery lubricants spanning hydraulic, gear, and bearing applications across legacy manufacturing bases.
Industrial equipment anchors volume leadership. Aerospace applications climb the fastest on thermal stability specification premiums.
End User:
Customer type determines procurement sophistication, with integrated operators specifying directly versus distributor-mediated purchasing.
- Energy:Offshore wind and power generation operators specifying decade-interval synthetic fills for turbine gearboxes and transformer systems. Installation clusters off Scotland, Taiwan, and Massachusetts drive predictive maintenance contract bundling.
- Manufacturing:Precision machinery and automotive OEMs sourcing through integrated supply contracts with carbon intensity disclosure requirements under EU CSRD scope 3 mandates.
- Transportation:Fleet operators and marine shipping companies facing port state control detention risk for non-compliant lubricant specifications.
- Construction:Mobile equipment fleets operating under biodegradable hydraulic fluid mandates for environmentally sensitive project sites.
Manufacturing holds the deepest specification expertise. Energy sector procurement gains share fastest on renewable infrastructure scaling.
Formulation:
Base stock chemistry determines biodegradability credentials, thermal performance ceilings, and regulatory compliance positioning.
- Biodegradable:Vegetable oil and synthetic ester base stocks with zinc-free additive packages achieving EU Ecolabel and VGP compliance. Port authorities at Rotterdam and Hamburg enforce mandatory procurement for oil-to-sea interfaces.
- Synthetic:PAO, PAG, and ester formulations delivering oxidative resistance beyond Group III mineral capabilities for high-temperature industrial and aerospace applications.
- Mineral Oil Based:Conventional Group I/II/III base stocks occupying cost-sensitive legacy equipment segments.
- Semi-Synthetic:Blended formulations balancing performance upgrade paths with mineral oil compatibility constraints.
Mineral oil formulations retain volume leadership in emerging manufacturing bases. Biodegradable grades expand most quickly on regulatory cascade acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's stern tube lubricant procurement specifications shape European marine demand. Germany's offshore wind clusters in the North Sea drive synthetic fluid consumption for turbine gearboxes. Singapore's MRO network concentration anchors aerospace maintenance programs across Southeast Asia.
United States
EPA Vessel General Permit enforcement at Gulf Coast and Pacific Northwest ports mandates biodegradable lubricants for oil-to-sea interfaces. The FAA's aerospace certification requirements concentrate synthetic ester demand around Dallas-Fort Worth and Seattle-Tacoma maintenance hubs. Texas petrochemical complexes supply Group IV/V base stocks to domestic blenders.
Germany
REACH substance evaluation timelines force reformulation investments among Stuttgart-based lubricant formulators. The EU Green Deal's maritime decarbonization framework requires EAL-certified stern tube fluids for vessels calling at Hamburg. Offshore wind installation clusters off Schleswig-Holstein specify decade-interval synthetic fills for 15 MW+ turbine gearboxes.
China
MEE emission-linked manufacturing audits affect base oil import flows for domestic blending operations. The country's dual carbon goals accelerate biodegradable hydraulic fluid mandates for construction equipment in environmentally sensitive zones. Yangtze River Delta precision machinery manufacturers source advanced lubrication for textile and machine tool applications.
Singapore
Port state control detention risk for non-compliant marine lubricants drives EAL procurement from regional shipping operators. The city-state's MRO network expansion concentrates aerospace synthetic ester consumption for geared turbofan maintenance. Jurong Island petrochemical infrastructure supports regional base stock supply.
India
PLI scheme incentives for machine tools and textile machinery create demand for synthetic cutting fluids and spindle oils. BIS standards for industrial lubricants tighten specification requirements across Gujarat and Tamil Nadu manufacturing corridors. Domestic blending capacity remains underdeveloped versus demand from precision manufacturing clusters.
Specialty Lubricants Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on formulation chemistry. The market structure consolidates around integrated petrochemical majors with captive base oil production and dedicated regulatory affairs infrastructure. Three archetypes dominate: backward-integrated majors controlling Group III/IV supply chains, specialty blenders with aerospace certification channels, and regional distributors with predictive maintenance service bundling. Capacity expansion and portfolio diversification toward biodegradable formulations represent the primary competitive vectors.
Among European majors, Fuchs Petrolub SE and TotalEnergies SE exemplify divergent specialization strategies. Fuchs anchors high-temperature industrial formulation R&D from its Stuttgart headquarters. TotalEnergies occupies the marine biodegradable tier with EAL-certified stern tube lubricants. ExxonMobil Corporation represents the integrated archetype with synthetic fluid portfolios extending across aerospace certification channels.
| Leading Market Players |
|---|
| Chevron Corporation |
| Fuchs Petrolub SE |
| ExxonMobil Corporation |
| Valvoline Inc. |
| Sinopec Corporation |
| Shell plc |
| BP p.l.c. |
| Idemitsu Kosan Co. Ltd. |
| TotalEnergies SE |
| Others |
Supply Flow & Price Mechanics
Jurong Island's petrochemical infrastructure anchors Group IV/V base oil supply for Asia-Pacific blenders, concentrating pricing power among integrated producers while specialty formulators face allocation risk during upstream turnaround cycles. This supply hub dynamic transmits downstream into three-tier pricing structures that separate aerospace-certified synthetics from industrial mineral grades and emerging biodegradable formulations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates specialty lubricant procurement, with aerospace-certified synthetic esters commanding substantial premiums over industrial mineral formulations and biodegradable marine grades occupying a mid-tier position. Price differentiation hinges on certification tier—SAE AS5780 and MIL-PRF-23699 compliance versus industrial specifications—and volume scale with integrated energy operators. Cost compression in mineral-based industrial tiers is intensifying because of Group III base oil oversupply from Middle Eastern expansions. Small and mid-sized maintenance contractors exhibit highest price sensitivity, while offshore wind developers and aerospace MRO networks prioritize performance guarantees over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced polyalphaolefin catalyst technologies limit capacity expansion outside integrated petrochemical majors in Texas, Singapore, and Belgium. Geographic supply concentration centers on the United States, Belgium, and Singapore for Group IV/V base stocks, with China and South Korea supplying Group III feedstocks. Raw material dependencies include ethylene alpha-olefin co-monomers, synthetic ester alcohols, and zinc-free additive packages. Single-source vulnerability persists for PAO feedstock during planned and unplanned refinery maintenance. Distribution runs through regional blending terminals with direct-to-OEM contracts displacing traditional distributor networks in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tribochemistry modeling expertise has become the constraining asset in specialty lubricant formulation, with university programs de-prioritizing lubrication engineering curricula since 2010 and European R&D centers posting unfilled surface science roles.
For Market Incumbents: Insulate aerospace certification channels through dedicated test cell reservations at FAA-designated facilities, compressing 18-month qualification backlogs that threaten synthetic ester portfolio refresh cycles. Deepen backward integration into Group III base oil production to defend margin position against Middle Eastern supply expansions. Prioritize regulatory affairs infrastructure investment to manage REACH registration cost escalation exceeding EUR 500,000 per novel synthetic base stock substance evaluation. For New Entrants and Emerging Players: Pursue India's precision manufacturing corridor as the most penetrable geography, where PLI scheme incentives for machine tools and textile machinery outpace domestic blending capacity development in Gujarat and Tamil Nadu. Target biodegradable hydraulic fluid mandates for construction equipment in China's environmentally sensitive zones under dual carbon goals. Establish technical field support capabilities separate from product supply to capture unbundled after-sales service procurement patterns advancing among North American pulp and paper mills. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among predictive maintenance contract bundlers serving offshore wind installation clusters off Scotland and Taiwan, where decade-interval synthetic fill specifications lock in long-term offtake relationships. Mid-tier formulators with EAL certification and dedicated regulatory affairs teams represent priority acquisition archetypes over commodity blenders exposed to mineral oil margin compression. Monitor port state control detention enforcement intensity at Rotterdam and Hamburg as the inflection indicator for biodegradable marine lubricant demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Production | Shell plc's captive supply chain insulates margin position against Middle Eastern feedstock expansions. |
| EAL Certification Investment | TotalEnergies SE's biodegradable marine portfolio captures preferential procurement from Scandinavian ferry operators at Rotterdam. |
| Predictive Maintenance Contract Bundling | Energy sector operators in Germany and Denmark now specify sensor-integrated lubricant logistics with uptime guarantees. |
| Aerospace Test Cell Reservation | FAA-designated facility backlog creates 18-month qualification risk for new synthetic ester submissions under SAE AS5780 updates. |
| Regional Blending Capacity Expansion | Fuchs Petrolub SE's Stuttgart headquarters anchors European R&D for high-temperature industrial formulations serving precision machinery. |
Methodological Framework
A standing panel of lubricant formulators, aerospace MRO procurement directors, offshore wind maintenance managers, and marine fleet technical superintendents provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA substance evaluation dossiers, EPA Vessel General Permit enforcement records, EU Ecolabel certification databases, and customs trade data on base oil flows. Bottom-up demand modeling across end-use segments triangulated against top-down petrochemical capacity assessments.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation dimensions spanning formulation chemistry, application environment, end-user procurement sophistication, and regional regulatory cluster intensity. CAGRs were derived from equipment installation forecasts for 15 MW+ offshore wind turbines, aerospace MRO network expansion trajectories, and biodegradable mandate implementation timelines. Forecast inputs included REACH registration cost trajectories and base oil capacity addition schedules from integrated majors.
Sensitivities concentrate around regulatory divergence between Brussels and Beijing fragmenting product registration requirements, and biodegradable additive package performance gaps in high-pressure hydraulic applications. Forecasts reflect assumptions on EAL enforcement consistency at major European ports and aerospace certification timeline compression under updated military specifications. Material shifts in EPA Vessel General Permit state-level adoption or EU Green Deal maritime decarbonization acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Compressor Oil Market
Lubricants
Brazil Automotive Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
Industrial Gear Oil Market
Lubricants
United Kingdom Lubricants Market
Lubricants
ASEAN Lubricants Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Technical Fluids Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Global Refrigeration Lubricants Market