
 Kenya Lubricants Market | 2026-2036
Kenya Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Kenya Lubricants Market Outlook
KEBS KS 1830 certification for automotive lubricants is reorganizing competitive access in Kenya, filtering out informal blenders and elevating quality benchmarks nationwide. Vivo Energy leverages its Shell-branded distribution network to sustain retail dominance across 47 counties. TotalEnergies Marketing Kenya PLC anchors industrial supply through direct sales contracts with cement and agriculture processors. OLA Energy competes on price in the wholesale channel, targeting independent transport operators in the Northern Corridor.
Lubricants are formulated base oil and additive packages engineered to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades and total base number determining performance under thermal and oxidative stress. Engine oil occupies the largest volume share given Kenya's expanding commercial vehicle parc and motorcycle taxi fleet density in urban centers. Hydraulic oil leads margin pools through mining and construction machinery applications in the Rift Valley, while grease demand accelerates in agricultural equipment maintenance cycles. The product mix tilts toward mineral-based formulations in price-sensitive rural markets, though synthetic blends gain traction among fleet operators prioritizing extended drain intervals.
Kenya Bureau of Standards enforces KS 1830 and KS 2245 specifications that mandate viscosity stability and emissions compatibility, while the Energy and Petroleum Regulatory Authority monitors import licensing and petroleum product quality at Mombasa port of entry. National Environment Management Authority regulations on used oil disposal are reshaping collection infrastructure and reverse logistics requirements for distributors. Stakeholders must monitor KEBS alignment with evolving API and ACEA specifications, as premature specification upgrades could strand inventory and accelerate blender consolidation.
Market Dynamics
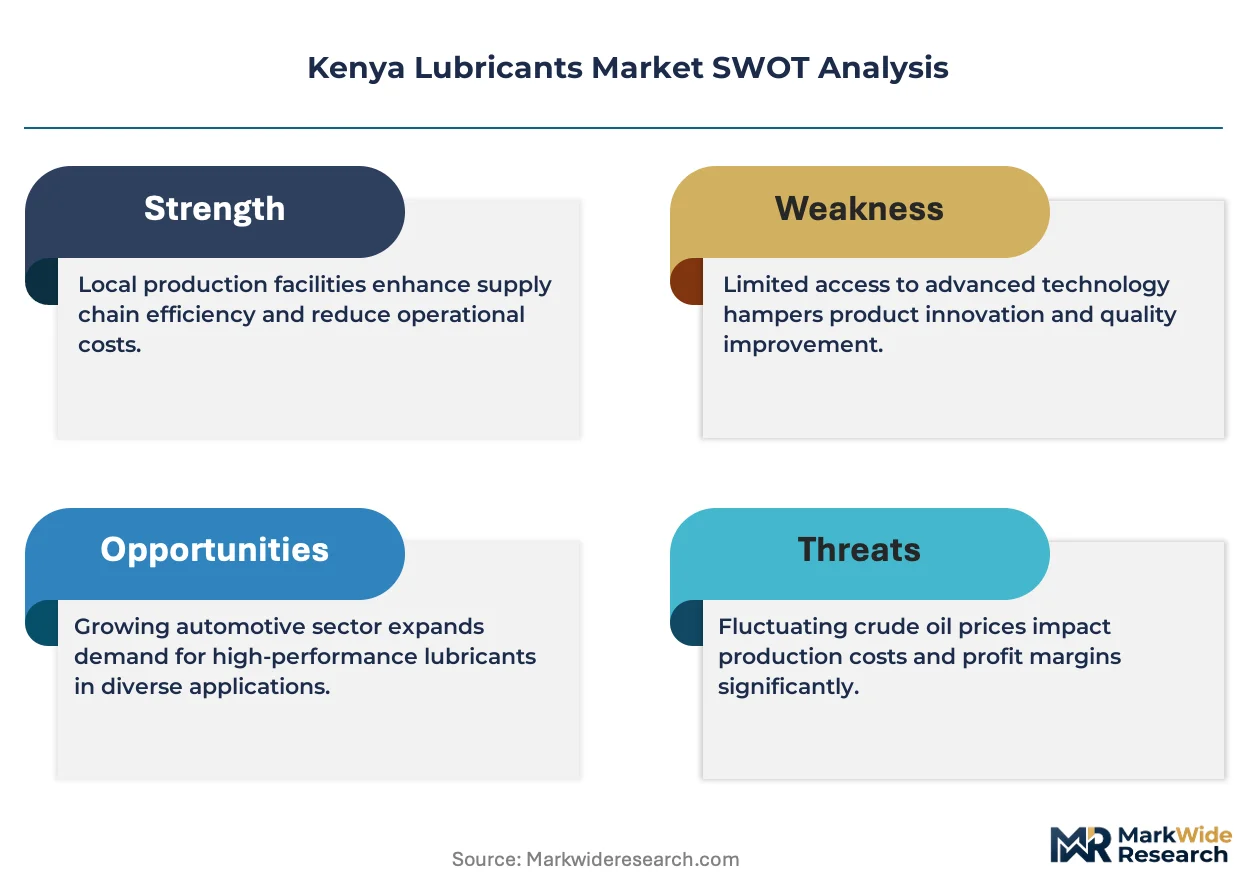
KEBS enforcement of KS 1830 specifications is compressing the informal blender segment while elevating quality barriers that favor distributors with laboratory testing capabilities and certified supply chains.
Growth Catalysts
- Commercial vehicle parc expansion:Fleet operators in Nairobi and Mombasa are extending drain intervals through synthetic formulations. Transport corridors generate recurring bulk offtake from long-haul operators.
- KS 1830 certification mandate:KEBS quality enforcement is eliminating substandard products from retail channels. Certified distributors gain shelf space previously occupied by informal blenders.
- Rift Valley mining corridor:Heavy-duty equipment maintenance cycles at cement and aggregate operations drive hydraulic oil and grease consumption. Mining contractors specify high-TBN formulations for severe service conditions.
Market Restraints
- Base oil import dependency:Kenya sources Group II and III base stocks through Mombasa port, exposing blenders to currency volatility and shipping disruptions.
- Used oil collection infrastructure gaps:NEMA regulations mandate reverse logistics, but collection network density remains insufficient outside Nairobi and Mombasa.
- Synthetic price premiums:Mineral formulations retain dominant share in rural markets where smallholder equipment operators prioritize upfront cost over lifecycle value.
Strategic Opportunities
- Northern Corridor logistics nodes:Isiolo and Nakuru transport hubs remain underserved by certified lubricant distributors. Independent operators in these corridors purchase through informal channels.
- Agricultural mechanization:Tractor and combine harvester penetration in Trans Nzoia and Uasin Gishu counties is expanding grease and transmission fluid demand beyond traditional manual equipment.
- API specification alignment:KEBS trajectory toward API SP and CK-4 adoption creates first-mover advantage for blenders with testing laboratory partnerships.
Industry Challenges
- Laboratory certification timelines:KEBS product registration requires extended testing protocols that delay new formulation launches by 6-12 months.
- Technical service workforce scarcity:Equipment-specific lubricant recommendation expertise concentrates with multinational distributor technical teams, limiting independent blender competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kenya Lubricants Market |
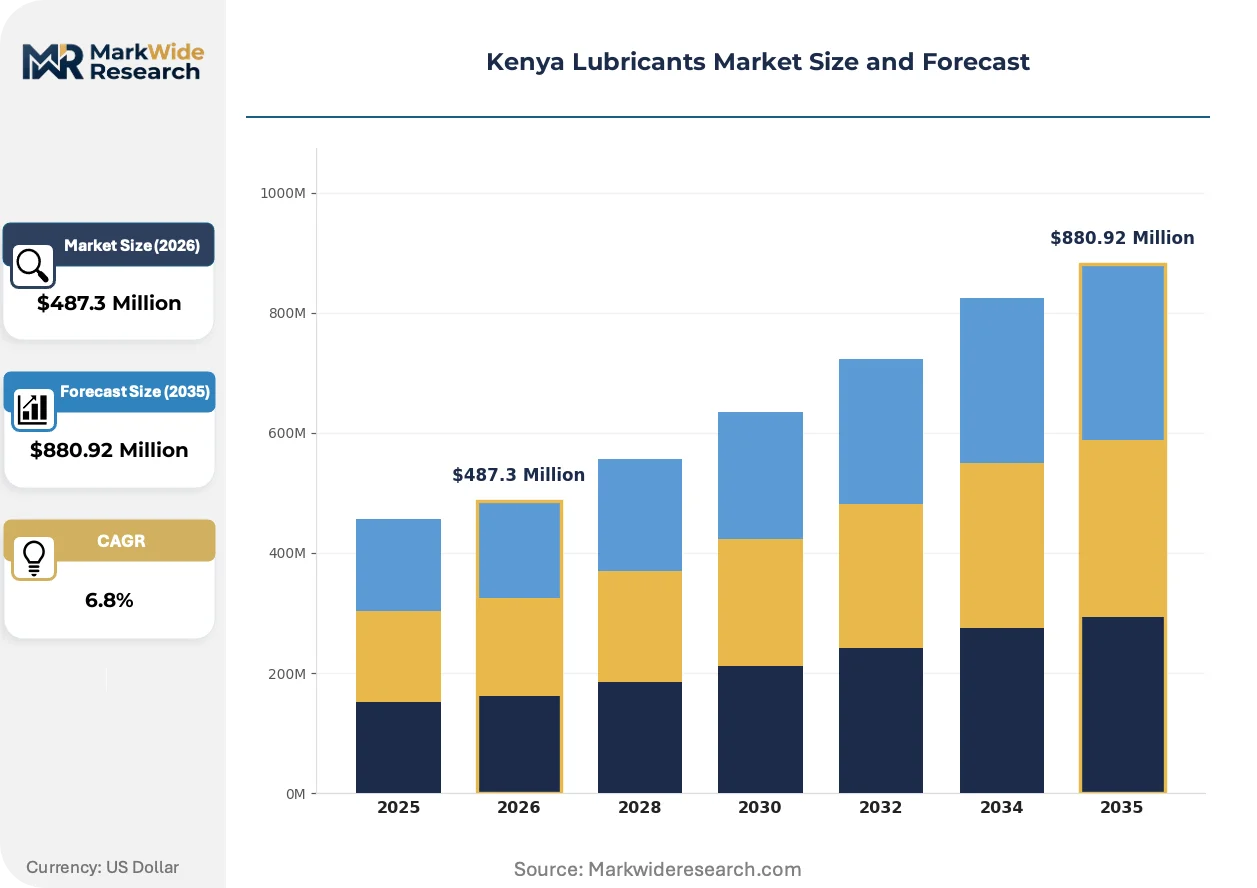
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Hydraulic Oil, Grease End User: Automotive, Industrial, Marine, Aviation Distribution Channel: Retail, Direct Sales, Online, Wholesalers Application: Automotive Maintenance, Machinery, Marine Operations, Heavy-Duty Equipment |
| Companies Covered | Kenol & Kobil, Galana Energies Limited, Vivo Energy (Shell), Oryx Energies, Hass Petroleum, TotalEnergies Marketing Kenya PLC, National Oil Corporation of Kenya, Sinopec, OLA Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kenya Lubricants Market Strategic Shifts
Synthetic formulation technology and digital fleet management tools are restructuring procurement relationships between lubricant suppliers and commercial vehicle operators across Kenyan transport corridors.
High-viscosity synthetic blends incorporating Group III base stocks and advanced detergent packages are bifurcating the engine oil category. Nairobi-based fleet operators with telematics-enabled maintenance scheduling are adopting these formulations for extended drain intervals. The technology is compressing service revenue for traditional oil change workshops while shifting volume toward direct distributor contracts.
KEBS alignment with API SP specifications for gasoline engines and API CK-4 for diesel applications is accelerating product portfolio upgrades. Blenders must reformulate existing SKUs or risk inventory stranding as retail channels enforce new labeling requirements. Commercial vehicle segments operating Euro IV and V engines are driving specification migration fastest in the Nairobi metropolitan area.
Fleet operators are consolidating lubricant procurement through direct distributor agreements rather than fragmented retail purchases. Large transport companies in Mombasa and Nairobi are negotiating annual volume contracts with technical support attachments. This concentration is most visible among cement and logistics fleets operating scheduled maintenance programs with digitized service records.
Kenya Lubricants Market Segmentation
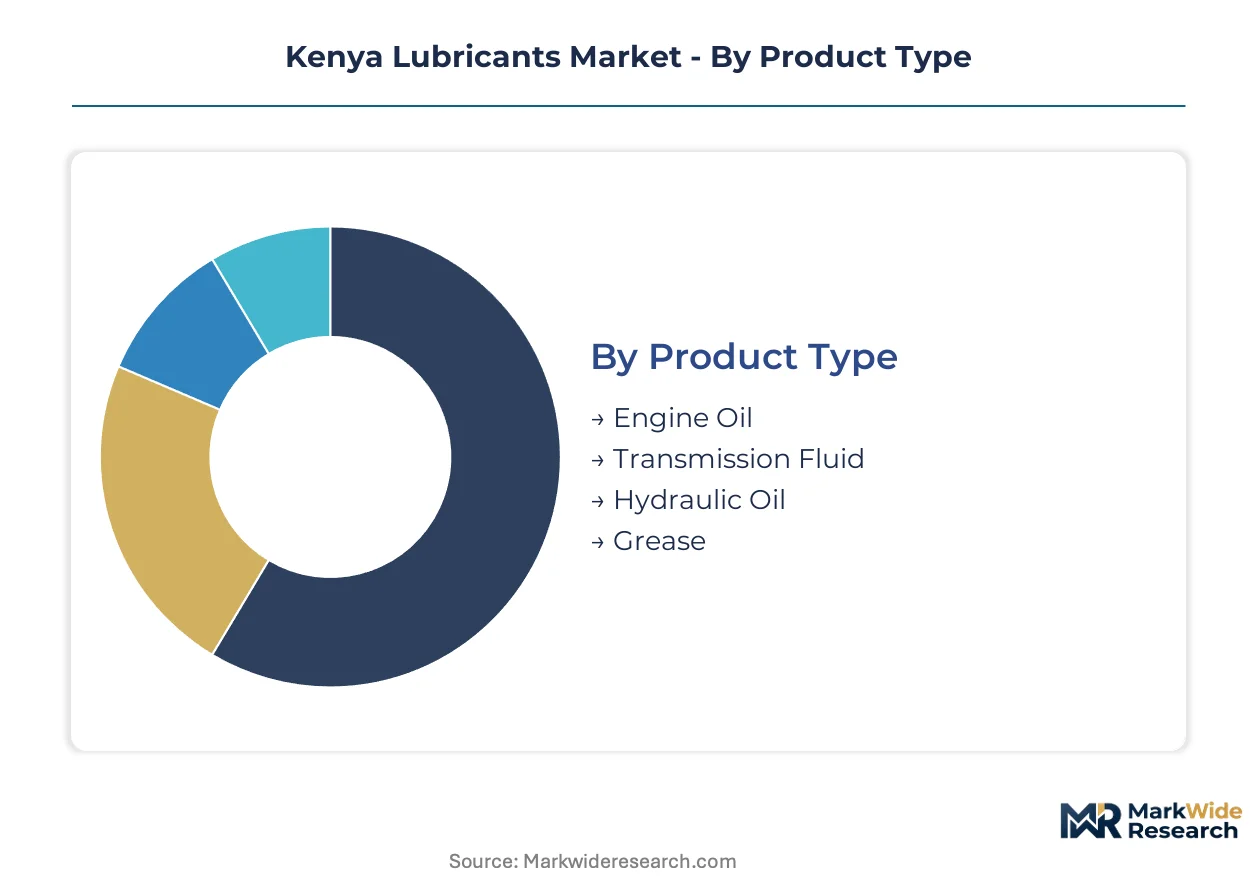
Kenya's lubricant segmentation reflects divergent compliance capabilities across the value chain. KEBS KS 1830 enforcement has fragmented channels and concentrated procurement among certified suppliers.
Product Type:
KEBS KS 1830 viscosity and TBN specifications differentiate formulation tiers, with synthetic blends commanding premium positioning against mineral-based alternatives in price-sensitive segments.
- Engine Oil:Formulated base oil and additive packages with viscosity grades calibrated for thermal stress in commercial vehicle engines. Demand concentrates in Nairobi and Mombasa fleet operations where extended drain intervals justify synthetic premiums. KEBS API SP alignment is accelerating specification migration among transport operators.
- Hydraulic Oil:High-TBN formulations engineered for severe service conditions in mining and construction machinery. Rift Valley cement and aggregate operations drive bulk offtake, with contractors specifying premium grades for equipment uptime in dust-intensive environments.
- Transmission Fluid:Specialized lubricants for gear systems and powertrain components in agricultural and commercial vehicles.
- Grease:Semi-solid lubricants for chassis, bearings, and agricultural equipment maintenance cycles in mechanizing counties.
Engine Oil handles the majority of throughput; Hydraulic Oil is the fastest mover on share.
End User:
Customer procurement scale determines contract structure, with direct distributor agreements replacing fragmented retail purchases among volume buyers.
- Automotive:Fleet operators and independent transport companies purchasing through certified retail or direct sales channels. Nairobi-based telematics-enabled fleets are consolidating annual volume contracts with technical support attachments, compressing workshop service revenue.
- Industrial:Cement processors, agriculture aggregators, and manufacturing facilities sourcing through direct sales with scheduled delivery terms. TotalEnergies anchors this segment through long-term supply agreements with Rift Valley operations.
- Marine:Coastal logistics and fishing vessel operators procuring through Mombasa port-based distributors.
- Aviation:Specialized jet engine and hydraulic system lubricants for commercial and cargo aircraft at Jomo Kenyatta International Airport.
Automotive commands the volume base; Industrial is expanding most quickly on contract consolidation.
Distribution Channel:
Channel access correlates with laboratory certification investment, filtering informal blenders from formal retail and direct sales networks.
- Retail:Branded service stations and auto parts outlets across 47 counties. Vivo Energy's Shell network dominates shelf space, with KEBS enforcement eliminating substandard competitors from consumer-facing locations.
- Direct Sales:Volume contracts between blenders and fleet operators, cement plants, or agricultural processors. This channel is displacing retail for scheduled maintenance programs with digitized service records.
- Online:Emerging e-commerce platforms and distributor portals for independent operators in secondary cities.
- Wholesalers:Bulk distributors serving Northern Corridor transport hubs and rural markets where price sensitivity sustains mineral formulation demand.
Retail maintains the widest geographic footprint; Direct Sales is climbing the fastest on fleet procurement consolidation.
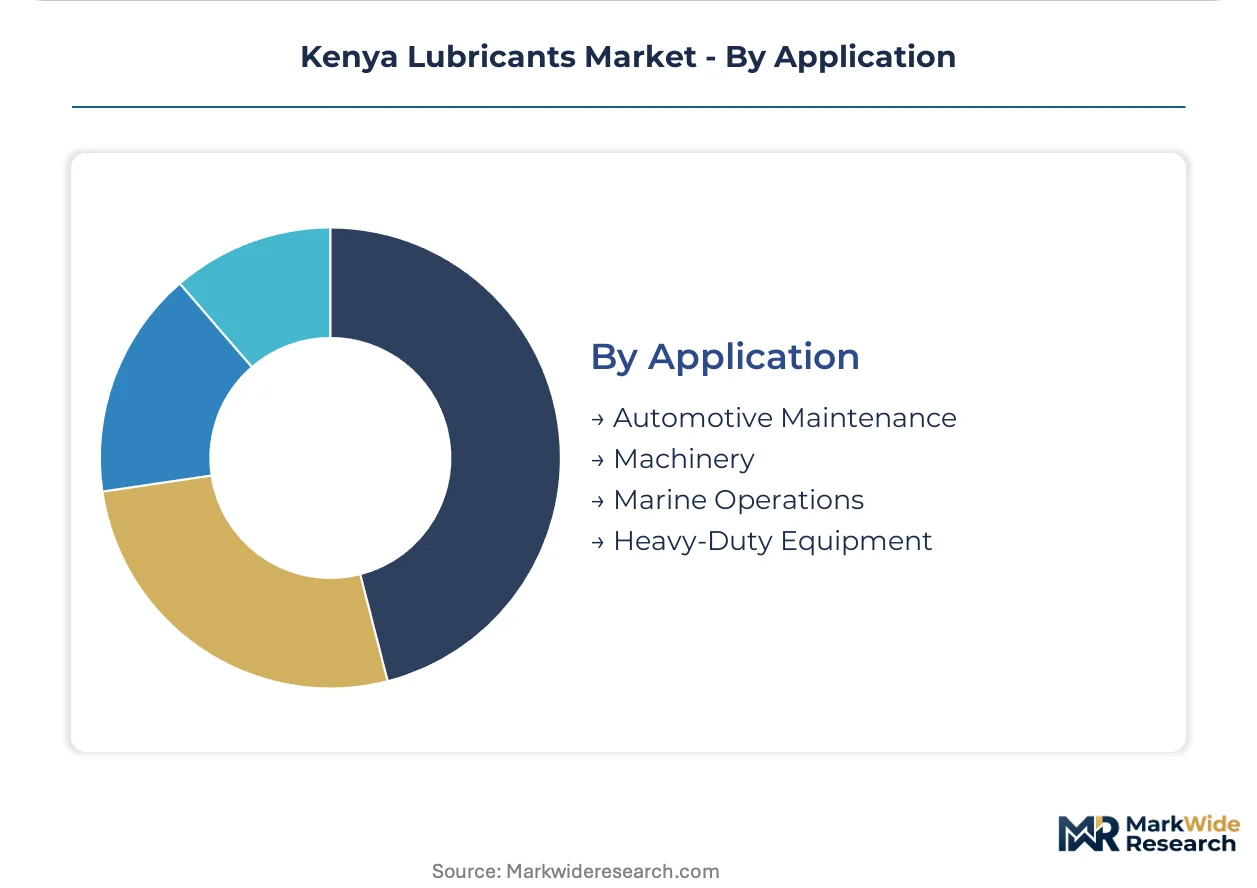
Application:
Equipment duty cycles and operating environments dictate formulation selection, with severe service conditions justifying premium synthetic investments.
- Automotive Maintenance:Scheduled oil changes and preventive servicing for commercial vehicles, motorcycles, and passenger cars. Drain interval extension through synthetic adoption is restructuring workshop economics in urban centers.
- Machinery:Industrial equipment lubrication in processing plants and manufacturing facilities. Uasin Gishu and Trans Nzoia agricultural mechanization is expanding transmission fluid and grease demand beyond traditional manual equipment.
- Marine Operations:Engine and auxiliary system lubrication for coastal and inland waterway vessels.
- Heavy-Duty Equipment:Mining excavators, construction loaders, and aggregate processing machinery operating in Rift Valley dust and temperature extremes. High-TBN hydraulic oils and specialized greases dominate this specification-intensive segment.
Automotive Maintenance generates the highest transaction frequency; Heavy-Duty Equipment shows the steepest expansion trajectory on mining corridor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KEBS quality enforcement and Northern Corridor infrastructure investments are redistributing lubricant demand across Kenya's economic corridors. Regional procurement patterns now track transport density and mining activity rather than population distribution alone.
Nairobi Metropolitan Area
Commercial fleet operators dominate lubricant offtake through telematics-enabled maintenance contracts. KEBS API SP specification alignment is accelerating fastest in this corridor. Industrial zones in Athi River and Mombasa Road host cement processors sourcing hydraulic oils through direct sales agreements.
Mombasa Coastal Region
Port logistics and marine operations concentrate demand for high-TBN marine lubricants and heavy-duty engine oils. Energy and Petroleum Regulatory Authority import licensing at Kilindini Harbour filters product quality at point of entry. Transport operators serving the Northern Corridor originate procurement from Mombasa-based distributors.
Rift Valley Mining Belt
Cement and aggregate operations in Baringo, Nakuru, and Kericho counties drive severe-service hydraulic oil consumption. National Environment Management Authority used oil regulations are reshaping collection infrastructure around mining camps. Equipment contractors specify premium greases for dust-intensive operating conditions.
Western Agricultural Zone
Mechanization in Trans Nzoia and Uasin Gishu counties is expanding transmission fluid and grease demand beyond manual equipment maintenance cycles. Smallholder cooperatives retain price sensitivity toward mineral formulations. Independent distributors serve this corridor through wholesale channels bypassing retail markup.
Northern Corridor Transit Hubs
Isiolo and Nakuru transport nodes remain underserved by certified lubricant distributors. Independent operators purchase through informal channels despite KEBS enforcement tightening in primary cities. Agricultural processors in Meru and Nanyuki are consolidating procurement through direct blender contracts.
Kenya Lubricants Market Competitive Environment
Player mix skews toward multinational petroleum marketers with integrated supply chains and national laboratory certification capabilities. Market access now correlates directly with KEBS testing infrastructure investment. Three strategic archetypes dominate: international majors with retail networks, regional African specialists competing on wholesale price, and state-affiliated distributors securing public sector contracts. Competitive moves center on direct sales contract consolidation with fleet operators and backward integration into base oil storage at Mombasa.
Among the integrated multinational tier, Vivo Energy and TotalEnergies Marketing Kenya PLC exemplify archetypes with divergent channel strategies. Vivo Energy occupies a position anchored in retail network density across all 47 counties. TotalEnergies represents the industrial-direct sales vector with long-term supply agreements. OLA Energy sits within the price-competitive wholesale segment targeting independent transport operators. These three illustrate how certification capabilities and channel focus now determine competitive access more than brand recognition alone.
| Leading Market Players |
|---|
| Kenol & Kobil |
| Galana Energies Limited |
| Vivo Energy (Shell) |
| Oryx Energies |
| Hass Petroleum |
| TotalEnergies Marketing Kenya PLC |
| National Oil Corporation of Kenya |
| Sinopec |
| OLA Energy |
| Others |
Value Chain & Pricing Dynamics
Base oil storage capacity at Mombasa port anchors supply-side scale economies, concentrating procurement leverage among blenders with dedicated tankage while compressing price floors for independent operators lacking volume commitments. This infrastructure asymmetry forces smaller competitors toward mineral-based formulations where import cost pass-through is steepest.
Pricing Analysis
Certification level under KEBS KS 1830 creates the primary spread between formulation tiers. Three-tier pricing structure across premium synthetic, certified mineral, and uncertified mineral levels dominates the market. Synthetic blends command 40-60% premiums over mineral alternatives. Cost compression in the mineral tier is intensifying because informal blenders face KEBS enforcement stranding. Smallholder cooperatives in Western Agricultural Zone exhibit highest price sensitivity; fleet operators with telematics-enabled maintenance programs demonstrate lowest.
Supply Chain Analysis
Singapore and the United Arab Emirates anchor base oil supply into Kenya through Mombasa port. Group II and III base stocks draw from Asian refineries, while additive packages rest on European and North American specialty chemical producers. Single-source vulnerability concentrates around Mombasa port logistics chokepoints. Distribution runs through Vivo Energy's retail network, TotalEnergies' direct sales contracts, and OLA Energy's wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
KEBS quality enforcement fragments competitive access, creating white-space opportunities for certified operators in underserved Northern Corridor nodes where informal supply persists.
For Market Incumbents: Consolidate laboratory certification capabilities to accelerate KEBS product registration timelines. Expand dedicated base oil storage at Mombasa to secure supply continuity against shipping disruptions. Acquire independent distributors in Isiolo and Nakuru to preempt regional specialists from capturing Northern Corridor fleet contracts. For New Entrants and Emerging Players: Differentiate on technical service workforce development targeting agricultural mechanization in Trans Nzoia and Uasin Gishu. Penetrate the Western Agricultural Zone through independent wholesale channels bypassing retail markup. Pursue direct sales contracts with cement processors seeking API CK-4 aligned hydraulic oils. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet operators with digitized maintenance programs and annual volume contracts. Long-term viability hinges on backward integration into base oil storage and testing laboratory infrastructure. Monitor KEBS specification alignment with API SP and ACEA timelines as inflection indicator for inventory stranding risk among mineral-focused blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Storage | Dedicated Mombasa tankage secures supply continuity against currency volatility and port congestion. |
| Testing Laboratory Certification Investment | KEBS registration capabilities compress product launch timelines from 12 months toward competitive benchmarks. |
| Direct Sales Contract Consolidation | Annual volume agreements with cement and logistics fleets displace fragmented retail procurement. |
| Technical Service Workforce Development | Equipment-specific expertise addresses scarcity constraining independent blender competitiveness in Rift Valley mining. |
| Used Oil Collection Network Expansion | NEMA-compliant reverse logistics infrastructure addresses regulatory enforcement gaps outside Nairobi and Mombasa. |
Study Parameters
The analysis maps engine oil, hydraulic oil, transmission fluid, and grease segments, each validated through blender technical directors, fleet procurement managers, mining equipment contractors, and agricultural cooperative supply officers. Primary interviews combined with KEBS regulatory filings, Energy and Petroleum Regulatory Authority import licensing records, National Environment Management Authority compliance databases, and cement processor procurement disclosures. Bottom-up volume estimates triangulated against top-down economic activity indices across the analysis window.
Consistency checks against base oil import volumes through Mombasa port validated segment-level projections. The analytical framework models product type, end-user industry, distribution channel, and regional corridor dimensions throughout the forecast period. CAGRs derived from equipment parc expansion rates, drain interval extension trends, and mining activity indices in the Rift Valley corridor.
Material uncertainties — KEBS specification alignment timing, base oil shipping disruptions, currency volatility — sit outside the modeled envelope. Forecasts reflect assumptions about enforcement continuity and infrastructure investment pacing. Recalibration cycles align with material shifts in KEBS regulatory trajectory and Northern Corridor transport density.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Firearm Lubricants Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
North America and Europe Forestry Lubricants Market
Lubricants
Polyurea-Based Greases Market
Lubricants
Lubricity Improvers Market
Lubricants
Lubricated Tracks Market
Lubricants
Iran Passenger Vehicles Lubricants Market
Lubricants
China Lubricants Market
Lubricants
Bio-Based Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
ASEAN Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Open Gear Lubricants Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
Neat Cutting Oil Market