
 India Industrial Lubricants Market | 2026-2036
India Industrial Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
India Industrial Lubricants Market Foresight
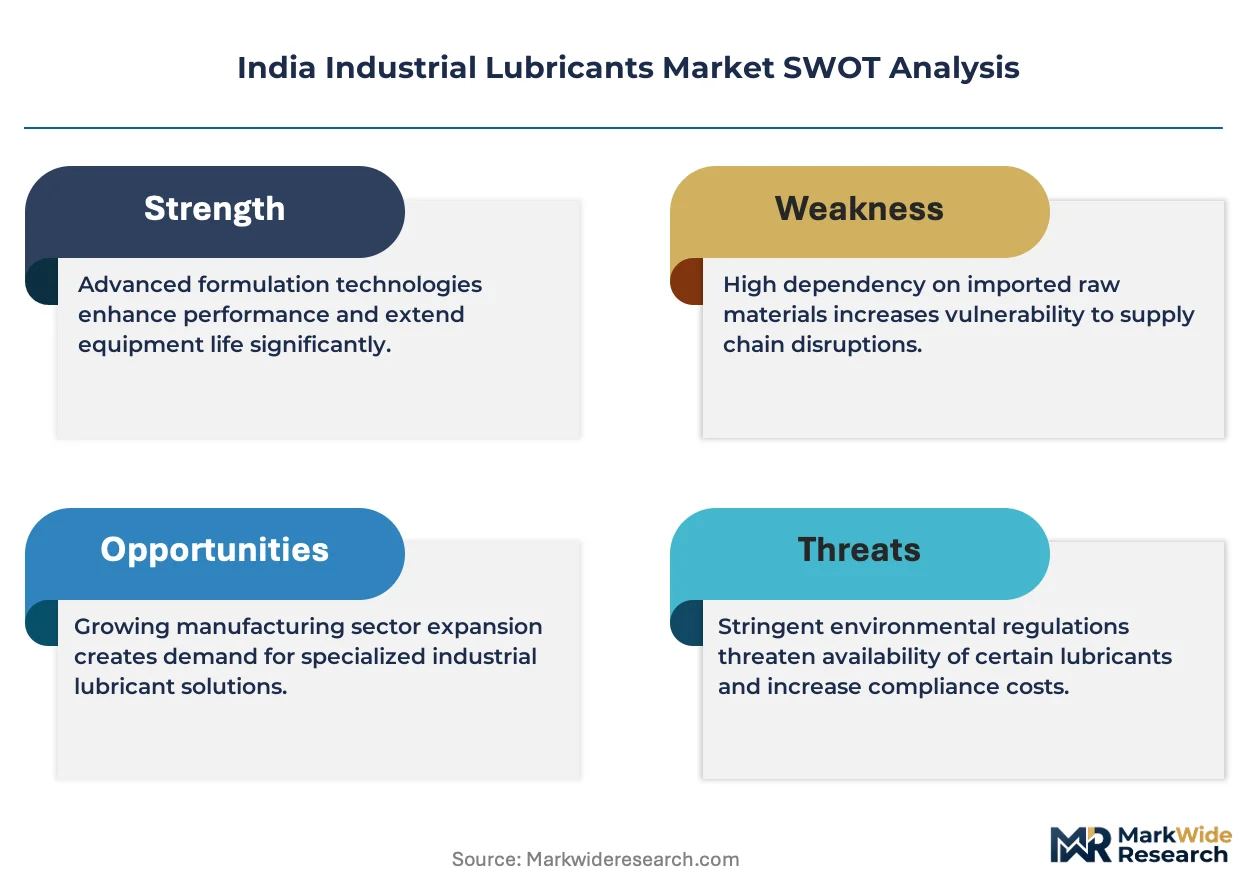
Asset-light leasing models for lubricant storage and dispensing infrastructure are reshaping competitive entry barriers for mid-sized distributors. Indian Oil Corporation Limited leverages its nationwide refinery network to sustain bulk supply advantages in power generation and mining accounts. Castrol India Limited differentiates through specialized metalworking fluid formulations for automotive component suppliers. Gulf Oil Lubricants India Limited competes on channel control, with dense distributor coverage across western and southern manufacturing belts.
India industrial lubricants comprise formulated oils, greases, and functional fluids engineered with viscosity grades typically ranging from ISO VG 32 to 680, designed to reduce friction, dissipate heat, and prevent corrosion in mechanical systems operating under extreme load and temperature conditions. Hydraulic fluids dominate volume consumption due to pervasive deployment in construction equipment and steel rolling mills, while metalworking fluids capture concentrated margin pools from precision engineering clusters in Pune and Chennai. Engine oils within the industrial category anchor replacement demand from captive power plants and genset fleets, with direct sales channels commanding stronger pricing power than fragmented retail networks.
BIS lubricant standards, CEA efficiency mandates for power sector equipment, and state-level pollution control board discharge regulations collectively dictate formulation chemistry and drain-interval claims across the market. The EPA-aligned MEE guidelines on used oil handling are pressuring large consumers toward contracted reclamation services rather than spot purchasing. Stakeholders must monitor how PLI scheme expansions for capital goods manufacturing redirect lubricant procurement specifications toward higher-performance synthetic grades.
Market Dynamics
PLI scheme expansions for capital goods manufacturing are redirecting lubricant procurement specifications toward higher-performance synthetic grades, compressing replacement cycles and reformulating margin structures across Maharashtra and Gujarat industrial corridors.
Growth Catalysts
- BIS Certification Tightening:The Bureau of Indian Standards is elevating quality benchmarks for hydraulic fluids and metalworking formulations, forcing formulation upgrades that capture premium pricing in precision engineering clusters.
- Captive Power Plant Expansion:Engine oil replacement demand from genset fleets and industrial power units is accelerating drain-interval compression, with direct sales channels commanding stronger pricing power than fragmented retail networks.
- Western Manufacturing Corridor Concentration:Chemical and textile manufacturing belts across Maharashtra and Gujarat are expanding lubricant consumption for heavy machinery maintenance, anchoring volume growth in ISO VG 46 to 680 viscosity grades.
Market Restraints
- Base Oil Import Dependence:Group II and Group III base stock supply concentrates in Middle Eastern and Southeast Asian refineries, exposing blenders to freight volatility and currency fluctuation risks.
- Used Oil Reclamation Mandates:EPA-aligned MEE guidelines on used oil handling are pressuring large consumers toward contracted reclamation services rather than spot purchasing, constraining spot market liquidity.
- Synthetic Grade Cost Premium:Polyalphaolefin and ester-based formulations carry 40-60% raw material cost premiums over mineral equivalents, limiting penetration in price-sensitive small and medium manufacturing units.
Strategic Opportunities
- Southern Precision Engineering Expansion:Metalworking fluid demand from automotive component suppliers in Chennai and Bengaluru is outpacing national averages, creating concentrated margin pools for specialized formulations.
- Asset-Light Infrastructure Leasing:Leasing models for lubricant storage and dispensing systems are lowering capital barriers for mid-sized distributors seeking entry into western India manufacturing belts.
- CEA Efficiency Mandate Alignment:Central Electricity Authority equipment efficiency regulations are creating specification pull for thermally stable hydraulic fluids in power generation rotating machinery.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Synthetic lubricant development requires specialized tribology and additive chemistry expertise that remains concentrated with legacy public sector research institutions.
- Drain-Interval Validation Timelines:Extended drain claims require 12-18 month field trials under BIS testing protocols, compressing product launch windows against faster-moving unorganized competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Industrial Lubricants Market |
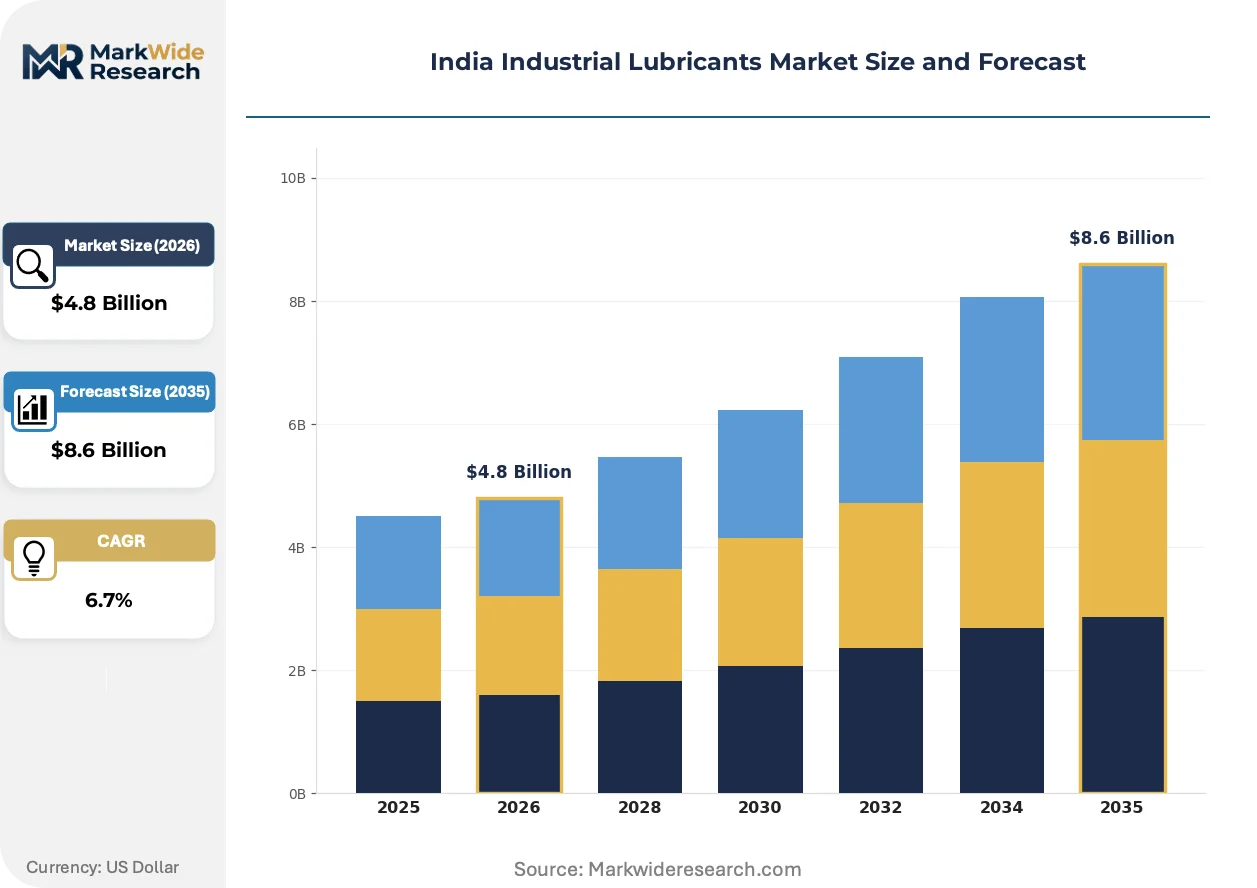
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grease, Hydraulic Fluids, Engine Oils, Metalworking Fluids End Use Industry: Manufacturing, Mining, Automotive, Power Generation Application: Machinery, Equipment, Compressors, Gear Systems Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Indian Oil Corporation Limited, Castrol India Limited, Bharat Petroleum Corporation Limited, Hindustan Petroleum Corporation Limited, Gulf Oil Lubricants India Limited, Shell India, Valvoline Cummins Private Limited, Total Oil India Private Limited, Exxon Mobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Industrial Lubricants Market Shifts & Advancements
Digital fluid monitoring systems and predictive maintenance platforms are compressing traditional replacement cycles while elevating specification complexity for lubricant suppliers serving automated manufacturing environments.
Condition-based monitoring sensors embedded in hydraulic reservoirs and gearbox housings are virtualizing the traditional time-based maintenance model. Steel rolling mills and cement plants in Rajasthan and Madhya Pradesh are deploying these systems at pilot scale. Real-time viscosity and particle count data is virtualizing inventory planning, enabling just-in-time lubricant delivery contracts that displace bulk tankage investments.
BIS lubricant standards and CEA efficiency mandates are collectively dictating formulation chemistry across power sector and heavy machinery applications. State-level pollution control board discharge regulations are constraining additive selections for metalworking fluids in Pune and Ahmedabad precision clusters. Compliance documentation requirements are extending procurement cycles by 30-45 days for first-time synthetic grade approvals.
Direct technical service engagement is displacing traditional distributor-led specification setting in large manufacturing accounts. Automotive component suppliers in Tamil Nadu and Karnataka are demanding on-site tribology support and drain analysis as standard contract terms. This service bundling is visible most acutely in OEM-aligned supply agreements where lubricant selection is locked at equipment commissioning stage.
India Industrial Lubricants Market Segmentation
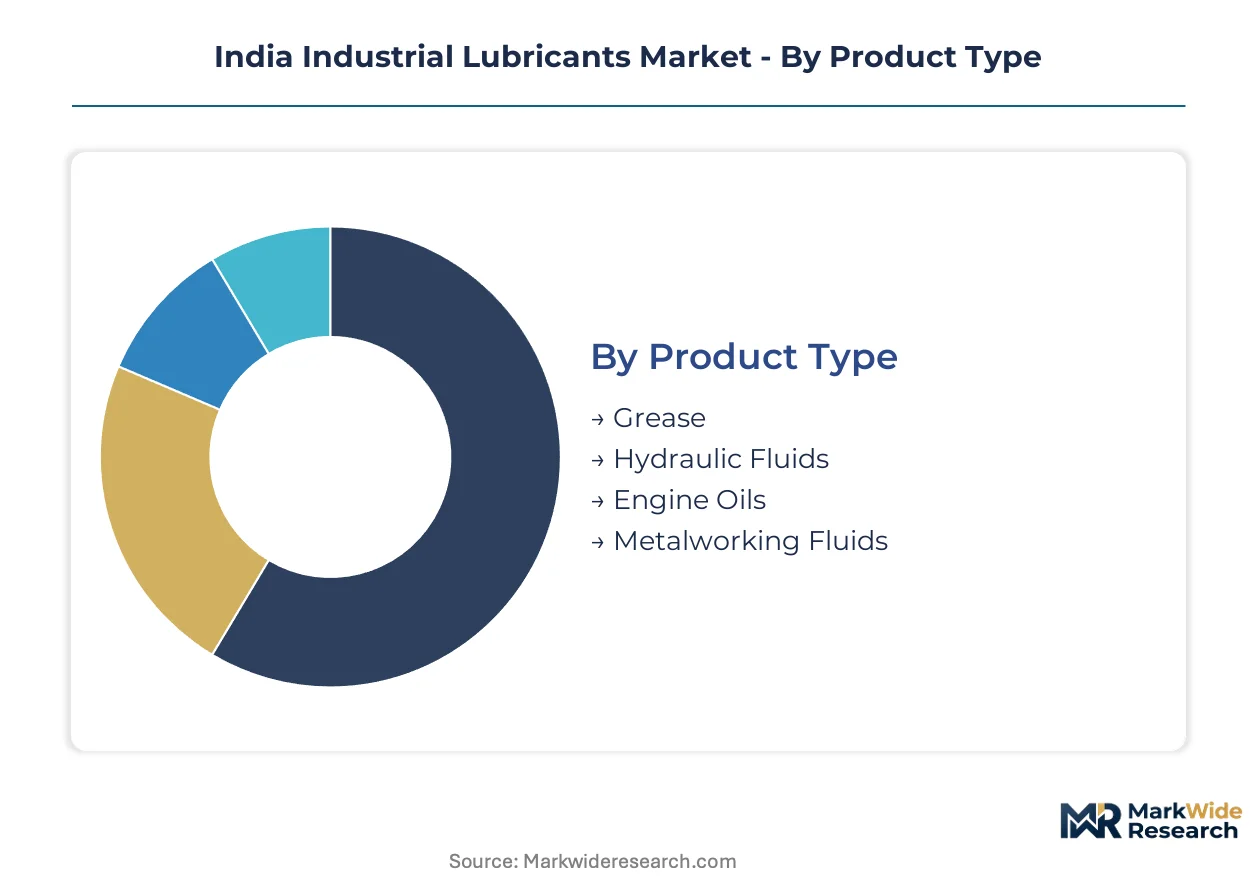
Segmentation in the India industrial lubricants market reveals how after-sales service intensity varies dramatically across product categories. Hydraulic fluids and metalworking formulations demand continuous technical support, while commodity greases operate through transactional channels. Understanding these service-tier distinctions shapes distributor investment priorities and margin capture strategies.
Product Type:
After-sales service intensity separates lubricant categories into distinct commercial models, with fluid monitoring and drain analysis commanding premium positioning.
- Hydraulic Fluids:Formulated with anti-wear additives and oxidation inhibitors across ISO VG 32 to 680 viscosity grades. Demand concentrates in Maharashtra and Gujarat steel rolling mills and construction equipment fleets, driven by CEA efficiency mandates for power sector rotating machinery.
- Metalworking Fluids:Emulsion-based and synthetic coolants engineered for precision machining operations. Pune and Chennai automotive component clusters anchor consumption, with BIS certification tightening forcing formulation upgrades that capture premium pricing.
- Engine Oils:High-detergency formulations for captive power plants and genset fleets requiring extended drain intervals.
- Grease:Lithium and calcium soap-thickened lubricants for bearing applications in mining and heavy machinery maintenance.
By volume, hydraulic fluids lead. By growth pace, metalworking fluids are expanding most quickly.
End Use Industry:
Customer procurement sophistication creates tiered margin structures, with direct technical engagement displacing distributor-led specification setting in advanced manufacturing accounts.
- Manufacturing:Chemical and textile production belts across western India anchor ISO VG 46 to 680 consumption for heavy machinery maintenance. PLI scheme expansions for capital goods manufacturing redirect procurement specifications toward higher-performance synthetic grades.
- Power Generation:Captive plants and genset fleets drive engine oil replacement demand with compressed drain intervals. Central Electricity Authority equipment efficiency regulations create specification pull for thermally stable hydraulic fluids.
- Mining:Open-pit and underground operations in Rajasthan and Madhya Pradesh deploy condition-based monitoring sensors at pilot scale.
- Automotive:Component suppliers in Tamil Nadu and Karnataka demand on-site tribology support and drain analysis as standard contract terms.
Manufacturing commands the largest volume share. Power generation shows the steepest specification upgrade trajectory.
Application:
Equipment criticality determines lubricant performance tier, with continuous-process machinery justifying synthetic formulations despite cost premiums.
- Machinery:General industrial equipment spanning conveyors, presses, and material handling systems. Small and medium manufacturing units dominate, constrained by polyalphaolefin and ester-based formulation cost premiums of 40-60% over mineral equivalents.
- Gear Systems:Closed and open gearing in cement plants and steel mills requiring extreme pressure additives. Rajasthan and Madhya Pradesh deployment of real-time viscosity monitoring is virtualizing inventory planning.
- Equipment:Mobile and stationary assets in construction and material processing operations.
- Compressors:Rotary screw and reciprocating units in pneumatic systems across precision engineering clusters.
Machinery applications lead by unit volume. Gear systems are gaining share fastest through predictive maintenance platform adoption.
Distribution Channel:
Channel control intensity correlates with account size, with direct sales commanding stronger pricing power than fragmented retail networks in large manufacturing accounts.
- Direct Sales:Technical service teams engage automotive component suppliers and power sector accounts at equipment commissioning stage. On-site tribology support and drain analysis are standard contract terms in OEM-aligned supply agreements.
- Distributors:Dense coverage across western and southern manufacturing belts enables mid-sized blender market access. Asset-light leasing models for storage and dispensing infrastructure are lowering capital barriers for new entrants.
- Retail:Fragmented network serving small and medium manufacturing units with commodity lubricant grades.
- Online:Emerging platform for standardized product procurement with extended documentation cycles for first-time synthetic grade approvals.
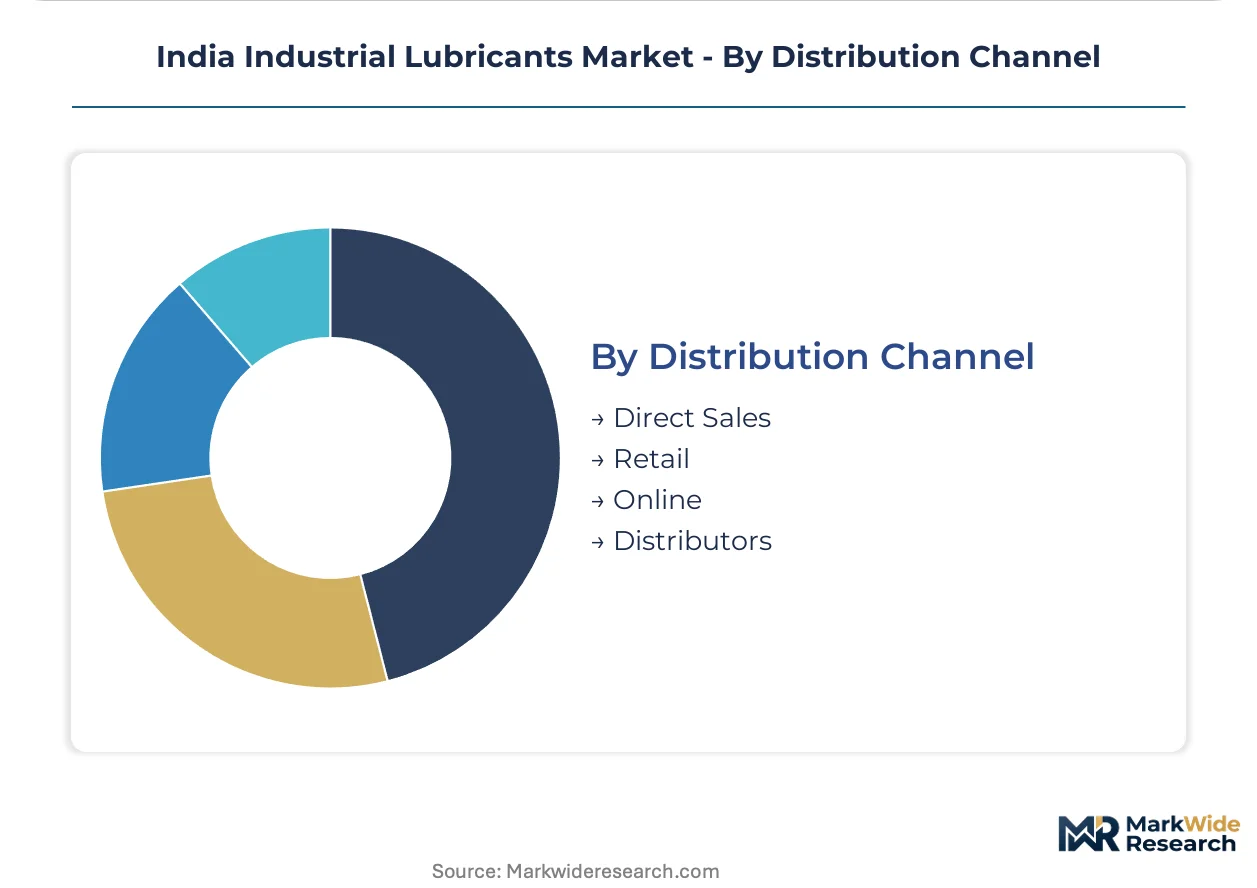
Distributors handle the greatest volume throughput. Direct sales channels are climbing the fastest as technical bundling displaces transactional purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives for capital goods manufacturing are redistributing lubricant demand toward western and southern industrial corridors. State-level pollution control mandates and BIS certification tightening are compressing procurement cycles for synthetic-grade approvals.
Maharashtra
Steel rolling mills and chemical manufacturing clusters in Pune and Mumbai consume ISO VG 46 to 680 hydraulic fluids for heavy machinery maintenance. BIS certification requirements for hydraulic fluid specifications are forcing formulation upgrades among precision engineering suppliers. The Pune automotive component belt anchors metalworking fluid demand with concentrated margin pools for specialized coolants.
Gujarat
Textile manufacturing belts and petrochemical complexes in Ahmedabad and Vadodara drive grease and engine oil replacement cycles. CEA efficiency mandates for power sector equipment create specification pull for thermally stable hydraulic fluids in captive generation units. The Dahej chemical corridor is expanding lubricant storage infrastructure through asset-light leasing models.
Tamil Nadu
Automotive component suppliers in Chennai and Coimbatore demand on-site tribology support and drain analysis as standard contract terms. State-level pollution control board discharge regulations constrain additive selections for metalworking fluids in precision machining operations. The Sriperumbudur automotive cluster is locking lubricant specifications at equipment commissioning stage through OEM-aligned supply agreements.
Karnataka
Bengaluru precision engineering and aerospace component manufacturing is outpacing national averages in synthetic metalworking fluid consumption. PLI scheme expansions for capital goods manufacturing redirect procurement specifications toward polyalphaolefin-based formulations. The Peenya industrial area is deploying condition-based monitoring sensors at pilot scale for hydraulic reservoir management.
Rajasthan
Cement plants and mining operations in Udaipur and Jaipur are virtualizing inventory planning through real-time viscosity monitoring systems. EPA-aligned MEE guidelines on used oil handling pressure large consumers toward contracted reclamation services. The Bhilwara textile machinery belt maintains concentrated demand for lithium soap-thickened bearing greases.
India Industrial Lubricants Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct competitive tiers. Public sector refiners leverage captive crude access and nationwide distribution infrastructure. Private blenders compete through specialized formulations and channel density. Multinational lubricant divisions anchor premium positioning through technical service bundling. Strategic moves concentrate on backward integration into base oil supply and direct technical engagement displacing distributor-led specification setting.
Among public sector incumbents, Indian Oil Corporation Limited and Bharat Petroleum Corporation Limited exemplify the scale-driven archetype through refinery-integrated supply networks. Castrol India Limited occupies a position within the premium formulation tier, representing specialized metalworking fluid development for automotive component clusters. Gulf Oil Lubricants India Limited sits within the channel-control archetype, anchoring distributor density across western and southern manufacturing belts.
| Leading Market Players |
|---|
| Indian Oil Corporation Limited |
| Castrol India Limited |
| Bharat Petroleum Corporation Limited |
| Hindustan Petroleum Corporation Limited |
| Gulf Oil Lubricants India Limited |
| Shell India |
| Valvoline Cummins Private Limited |
| Total Oil India Private Limited |
| Exxon Mobil Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in Middle Eastern Group II and Group III base oil refineries is tightening feedstock availability for Indian blenders, compressing margins and forcing selective premiumization strategies among formulation houses serving Maharashtra and Gujarat manufacturing corridors.
Pricing Analysis
Certification level under BIS lubricant standards creates the primary spread between commodity mineral grades and synthetic formulations. Three-tier pricing structure across premium synthetic, certified mineral, and unorganized economy grades reflects the 40-60% raw material cost premium for polyalphaolefin and ester-based chemistries. Pricing pressure stems from import-dependent base stock exposure to freight volatility and currency fluctuation. Small and medium manufacturing units in western India show highest price sensitivity, while captive power plants and automotive component suppliers accept premium positioning for drain-interval extension and equipment warranty compliance.
Supply Chain Analysis
Upstream feedstock supply draws from Saudi Arabia, Singapore, and South Korea for Group II and Group III base stocks, with Indian blenders lacking domestic catalytic dewaxing capacity. Additive packages for anti-wear and oxidation inhibition hinge on imports from Germany and the United States. Single-source vulnerability concentrates in hydraulic fluid viscosity modifiers and metalworking fluid emulsifier chemistries. Distribution runs through refinery-integrated public sector networks for bulk power and mining accounts, while specialized formulations reach precision engineering clusters via distributor-led technical service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as PLI scheme capital goods incentives accelerate specification upgrades toward synthetic grades, compressing replacement intervals and elevating technical service intensity across western and southern manufacturing belts.
For Market Incumbents: Insulate formulation chemistry capabilities through captive R&D partnerships with legacy public sector research institutions, countering talent scarcity that constrains synthetic grade development. Deepen channel control in Tamil Nadu and Karnataka automotive corridors before technical service bundling locks specifications at equipment commissioning stage. Prioritize backward integration into additive package blending to reduce import exposure.
For New Entrants and Emerging Players: Establish a beachhead in southern precision engineering clusters where metalworking fluid demand outpaces national averages and specialized formulation gaps persist. Target asset-light leasing models for lubricant storage infrastructure in Gujarat chemical corridors where capital barriers have historically blocked mid-sized distributor entry. Lead with on-site tribology support and drain analysis capabilities to displace transactional distributor relationships in automotive component accounts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-sized blender operations as asset-light infrastructure models proliferate, improving return thresholds for private equity deployment. Acquisition candidates should demonstrate established BIS certification pipelines and locked OEM-aligned supply agreements at commissioning stage. Monitor PLI scheme disbursement velocity as the inflection signal for synthetic grade penetration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Reduces import dependency on German and US additive packages for hydraulic fluid formulations. |
| Asset-Light Storage Infrastructure Leasing | Lowers capital barriers for distributor entry into Gujarat and Maharashtra chemical manufacturing belts. |
| Direct Technical Service Expansion | Locks lubricant specifications at equipment commissioning in Tamil Nadu automotive component clusters. |
| Synthetic Grade Certification Investment | Captures PLI scheme-driven specification upgrades in capital goods manufacturing corridors. |
| Condition-Based Monitoring Platform Partnership | Enables just-in-time delivery contracts displacing bulk tankage in Rajasthan cement plants. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BIS certification databases, CEA equipment efficiency directives, customs import records for base oil and additive shipments, and state pollution control board discharge filings. Input sources span maintenance directors at steel rolling mills and cement plants, procurement leads at automotive component suppliers, distributor principals across western and southern manufacturing belts, and technical R&D heads at formulation houses. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down supply-side capacity assessments from refinery and blending plant disclosures.
Forecast inputs incorporate product type segmentation across hydraulic fluids, metalworking fluids, engine oils, and greases; end-use industry splits across manufacturing, power generation, mining, and automotive; application tiers from general machinery to gear systems; and distribution channel dynamics between direct sales, distributors, retail, and emerging online procurement. CAGRs derive from elasticity modeling against industrial production indices, equipment installed base growth, and regulatory-driven specification upgrade timelines. Industry-specific inputs include PLI scheme capital goods disbursement trajectories and BIS certification pipeline velocity for synthetic grade approvals.
Stress conditions across base oil import cost volatility, currency fluctuation bands, and regulatory enforcement intensity for used oil reclamation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PLI scheme continuity, BIS certification tightening pace, and CEA efficiency mandate adoption curves. Cross-checking against industrial production statistics from the Ministry of Statistics and Programme Implementation is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
North America Automotive Lubricants Market
Lubricants
Japan Lubricants Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Russia Lubricants Market
Lubricants
Iran Passenger Vehicles Lubricants Market
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Industrial Lubricants Market
Lubricants
Global Process Oil Market
Lubricants
Polyurea Greases Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Poland Lubricants Market