
 Automotive Ambient Lighting Market | 2026-2036
Automotive Ambient Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ambient Lighting Market Intelligence
OEM-grade programmable LED systems is rotating the Automotive Ambient Lighting Market toward higher-margin configurations. FORVIA (HELLA) leverages its vertical integration into optical electronics to dominate dashboard illumination supply chains. ams OSRAM anchors the premium LED chip segment through its specialized semiconductor manufacturing in European automotive corridors. Valeo competes on dynamic lighting intelligence, embedding voice-controlled interfaces into center console architectures for French and German OEM programs.
Automotive ambient lighting encompasses electroluminescent and solid-state illumination systems engineered to 5,000-6,500 Kelvin color temperatures, deployed across vehicle cabins to enhance driver orientation and brand differentiation. Fiber optic light guides and OLED panels constitute the fastest-growing product categories, with OLED capturing margin pools in roof liner applications where conformal surfaces eliminate visible source points. Static lighting retains volume leadership in footwell illumination, while dynamic lighting systems—synchronized to vehicle state and infotainment—represent the technology segment where Tier-1 suppliers concentrate R&D investment.
NHTSA glare standards in the United States, ECE R48 in Europe, and China's GB standards on interior illumination collectively shape product certification pathways and market access timelines. ECHA REACH compliance for phosphor and rare-earth materials in LED packaging adds cost complexity for suppliers sourcing from non-European chemical processors. Stakeholders must monitor regulatory divergence between safety-centric American standards and Europe's emerging CSRD-linked sustainability disclosure requirements for automotive interior materials.
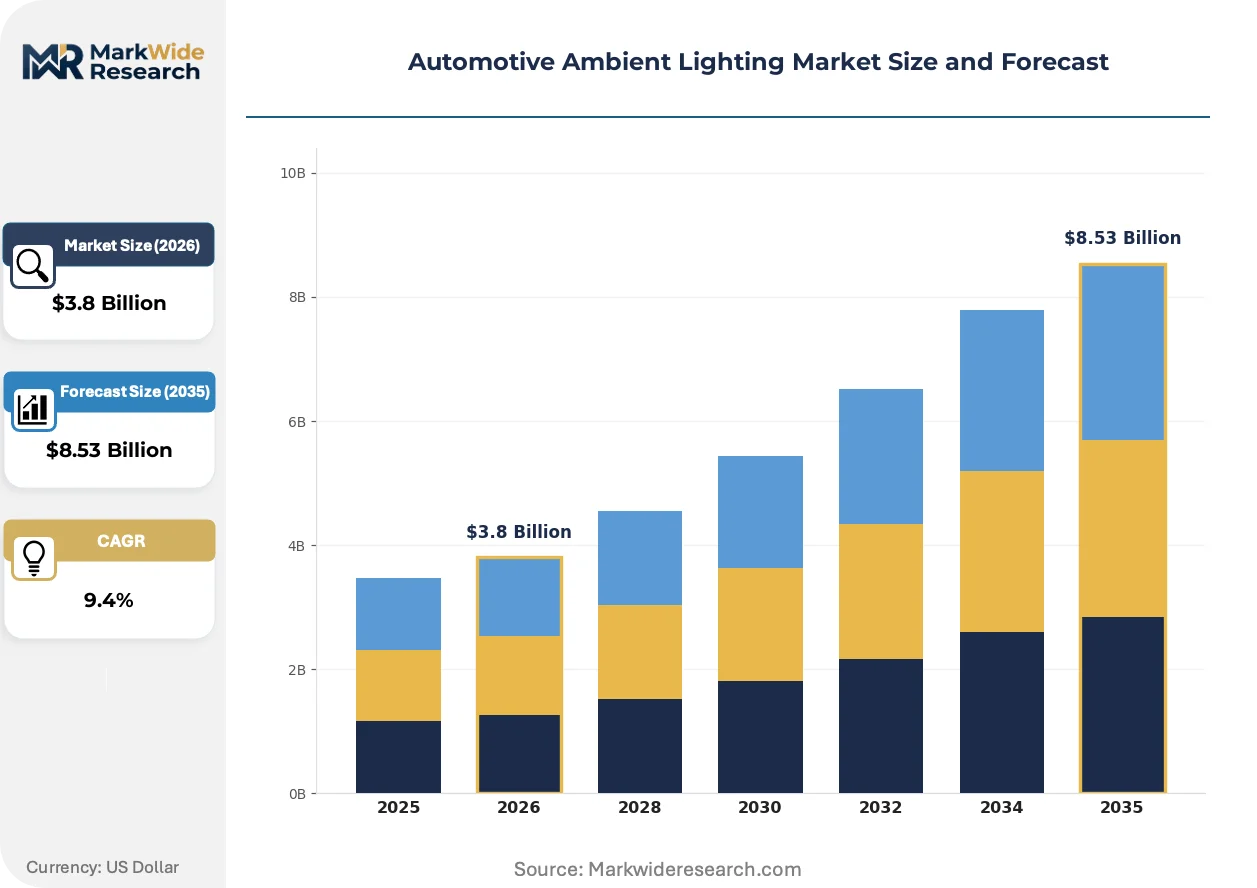
Market Dynamics
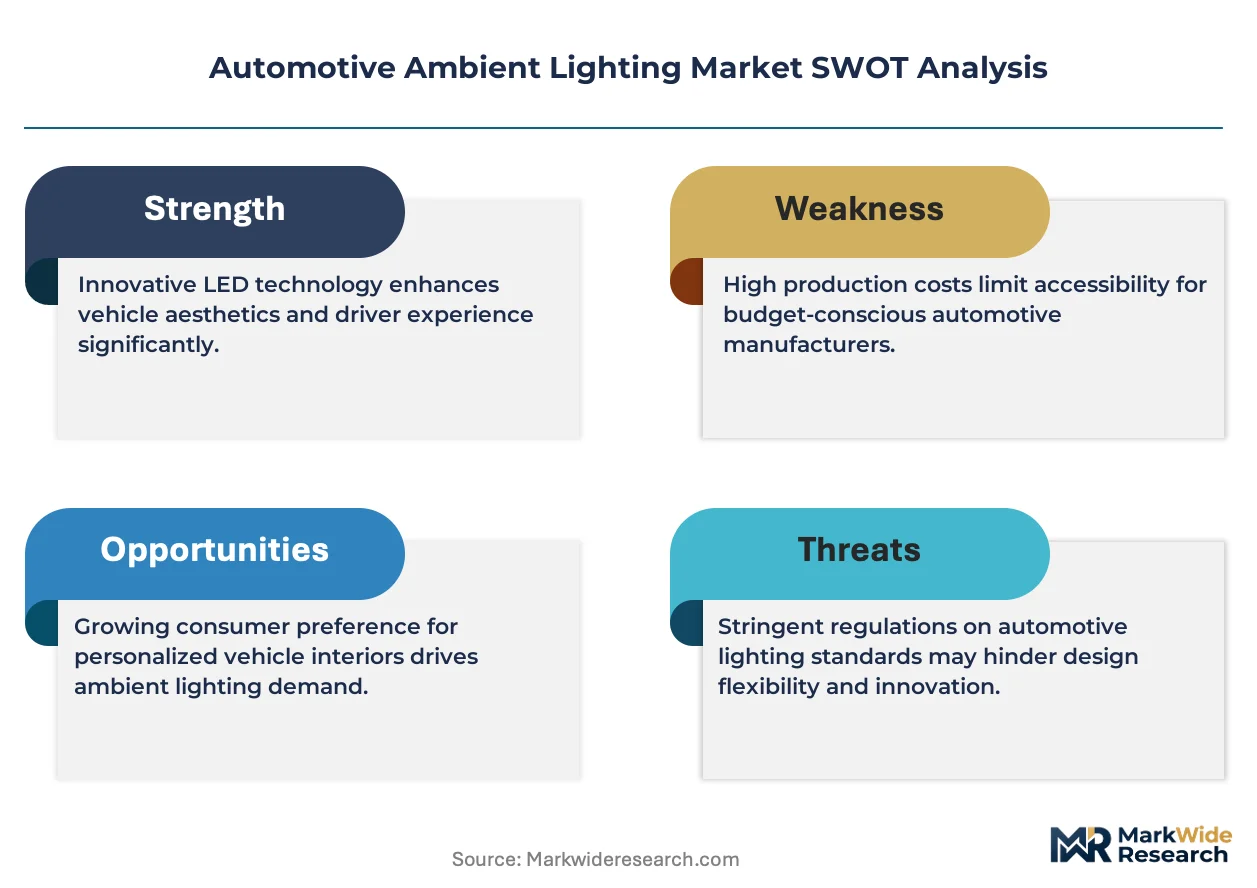
OEMs are consolidating dashboard illumination supply chains around programmable LED architectures that synchronize with vehicle state and infotainment systems, compressing procurement timelines for static lighting suppliers.
Growth Catalysts
- ECE R48 compliance mandates:European regulators are tightening interior light distraction standards, forcing OEMs to upgrade to certified dynamic systems that adjust intensity based on driving mode.
- Luxury EV interior differentiation:Premium electric vehicle programs in Germany's Stuttgart and Munich corridors are specifying roof liner OLED panels to eliminate visible source points and create brand-distinctive cabin signatures.
- Fiber optic light guide adoption:Conformal surface illumination is displacing rigid LED strips in center console architectures, enabling curved dashboard designs previously unachievable with point-source lighting.
Market Restraints
- Phosphor and rare-earth material cost volatility:ECHA REACH compliance requirements for LED packaging chemicals are adding cost complexity for suppliers sourcing from non-European chemical processors, compressing margin pools.
- Optical electronics supply concentration:Captive production of specialized semiconductor components for automotive-grade LED chips concentrates in European automotive corridors, creating single-source vulnerability.
- Static lighting substitution pressure:Footwell illumination systems face displacement risk as dynamic lighting architectures expand downward through vehicle cabin zones.
Strategic Opportunities
- Voice-controlled interface integration:French and German OEM programs are embedding intelligent lighting control into center console architectures, opening white space for human-machine interface convergence.
- CSRD-linked sustainability disclosure:Europe's emerging corporate sustainability reporting requirements for automotive interior materials create competitive advantage for suppliers with verified supply chain transparency.
- Aftermarket retrofit channels:Independent service networks in premium vehicle segments are developing certified installation capabilities for programmable LED system upgrades.
Industry Challenges
- Optical design talent scarcity:The intersection of semiconductor physics and automotive safety certification requires specialists fluent in both ECE regulation interpretation and solid-state illumination engineering.
- Legacy vehicle electrical architecture integration:Dynamic lighting systems must interface with existing CAN bus protocols and power distribution modules, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ambient Lighting Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Strips, Fiber Optic Lights, Neon Tubes, OLED Panels, Electro-Luminescent Wire Technology: Static Lighting, Dynamic Lighting, Touch Sensor, Voice Controlled, Ambient Light Sensors Application: Dashboard Illumination, Door Panel Lighting, Footwell Illumination, Center Console, Roof Liner Lighting End User: OEM Manufacturers, Vehicle Dealers, Customization Shops, Tier-1 Suppliers |
| Companies Covered | FORVIA (HELLA), Valeo, ams OSRAM, Koito Manufacturing, Stanley Electric, Signify (Philips Lighting), Grupo Antolin, DRÄXLMAIER Group, Magneti Marelli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ambient Lighting Market Strategic Shifts & Innovations
Automotive ambient lighting is undergoing a fundamental shift from static decorative elements to programmable systems that communicate vehicle status and enable personalization. This transformation is compressing supplier margins while opening new value pools in software-defined illumination.
OLED panel technology for roof liner applications is fragmenting the premium segment away from fiber optic and LED point-source alternatives. Luxury OEM programs are specifying conformal surface illumination to eliminate visible hotspots and enable seamless design integration. This technology is fragmenting established supply relationships as panel suppliers compete directly with traditional lighting Tier-1s for dashboard and overhead programs.
ECHA REACH compliance for phosphor materials in LED packaging is reshaping chemical sourcing requirements across European automotive supply chains. The regulation mandates traceability for rare-earth elements and restricts certain hazardous substances in semiconductor manufacturing. German and French OEMs are responding by qualifying alternative phosphor formulations and consolidating supplier bases to reduce certification burden.
Buyer procurement patterns are compressing development cycles for lighting system integration. OEMs are unbundling hardware supply from software development, awarding illumination control algorithms to electronics specialists separate from optical component sourcing. This bifurcation is most visible in German premium vehicle programs, where interior lighting specifications now separate LED chip supply from dynamic control system integration.
Automotive Ambient Lighting Market Segmentation
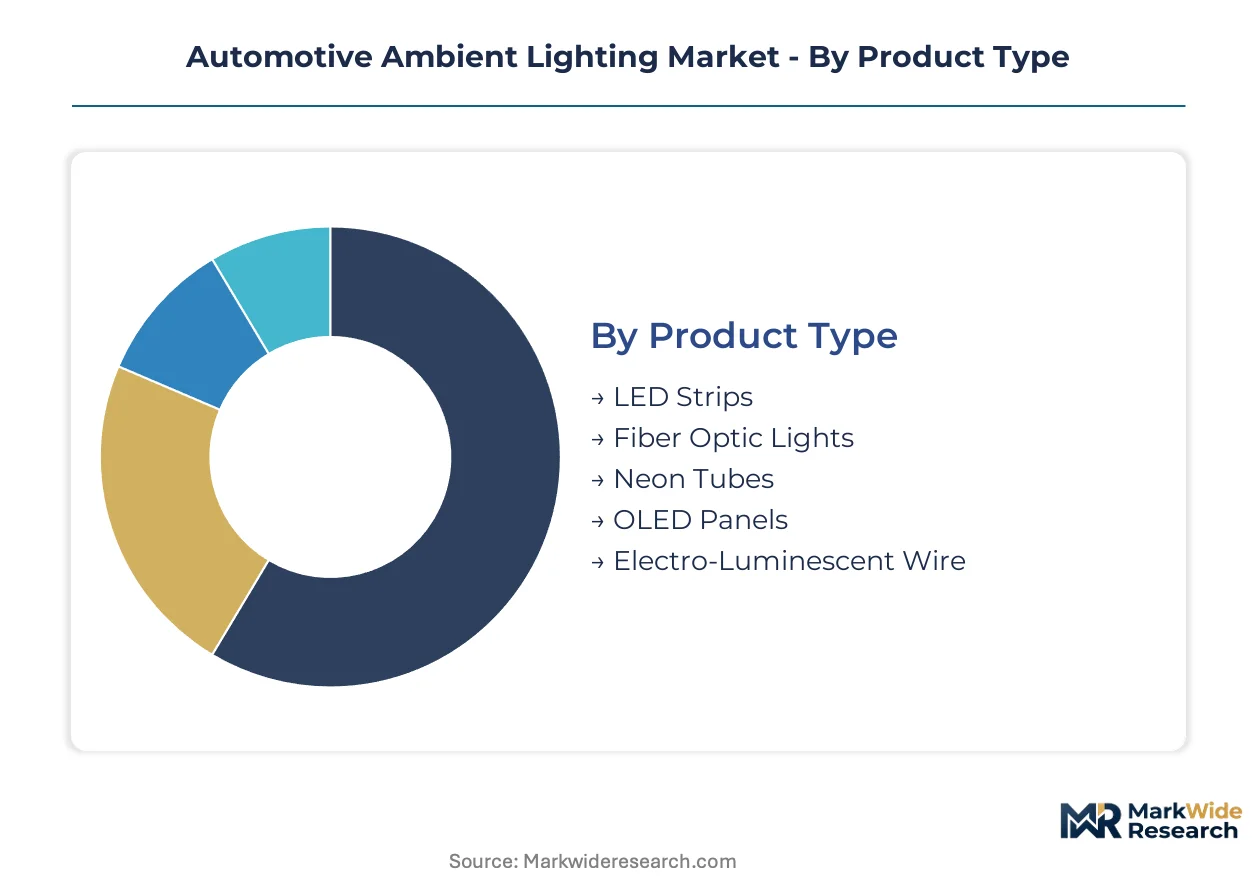
Automotive ambient lighting segments fragment along technical capability and supply chain position. Product architecture determines margin capture, while end-user channel dictates certification requirements and volume scale.
Product Type:
LED strips and fiber optic systems concentrate in domestic European supply chains serving Stuttgart and Munich OEM clusters, while OLED panels and electro-luminescent wire flow through export-oriented Asian manufacturing corridors.
- LED Strips:Point-source semiconductor arrays operating at 5,000-6,500 Kelvin dominate footwell and dashboard applications. German premium OEM programs specify programmable variants synchronized to vehicle state, compressing procurement timelines for static alternatives.
- Fiber Optic Lights:Polymer light guides enable conformal surface illumination across curved center console architectures. French and German Tier-1 suppliers source these for roof liner programs where hotspot elimination commands design priority.
- Neon Tubes:Gas-discharge illumination retains aftermarket presence in customization channels.
- OLED Panels:Organic semiconductor conformal surfaces capture margin pools in luxury EV roof liner applications.
- Electro-Luminescent Wire:Thin-film phosphor technology serves accent lighting in limited production runs.
LED strips command the established base. The steepest expansion runs through OLED panels.
Technology:
Cost tier separation splits this category: static systems occupy economy vehicle programs while dynamic and sensor-integrated architectures penetrate premium segments with 3-4x hardware cost multiples.
- Static Lighting:Fixed-intensity illumination without vehicle-state synchronization retains volume leadership in entry-level footwell applications. ECE R48 compliance pressure is forcing upgrade cycles in European markets.
- Dynamic Lighting:Programmable intensity and color temperature synchronized to driving mode, infotainment, and vehicle status. OEM-grade implementations require CAN bus integration and safety certification, extending development timelines.
- Touch Sensor:Capacitive interface integration enables manual override of automated lighting states.
- Voice Controlled:Natural language processing interfaces embedded through center console electronics architectures.
- Ambient Light Sensors:Photodiode arrays enabling automatic intensity adjustment based on cabin luminance.
Static lighting retains the volume base. Dynamic systems are climbing the fastest on value expansion.
Application:
Customer type differentiation separates this category: OEM direct programs favor dashboard and roof liner integration while dealer and aftermarket channels concentrate in footwell and door panel retrofits.
- Dashboard Illumination:Instrument panel backlighting and accent strips requiring optical precision to prevent driver distraction. ECE R48 and NHTSA glare standards impose certification burdens that favor established Tier-1 suppliers.
- Roof Liner Lighting:Overhead conformal surface illumination eliminating visible source points. OLED panel adoption is fragmenting supply relationships as display specialists compete with traditional lighting Tier-1s.
- Door Panel Lighting:Handle and storage compartment accent illumination.
- Footwell Illumination:Entry-level zone lighting facing displacement pressure from downward-expanding dynamic architectures.
- Center Console:Gear selector and cup holder accent lighting with emerging voice-control integration.
Dashboard illumination commands the established base. Roof liner lighting shows the steepest trajectory on premium EV penetration.
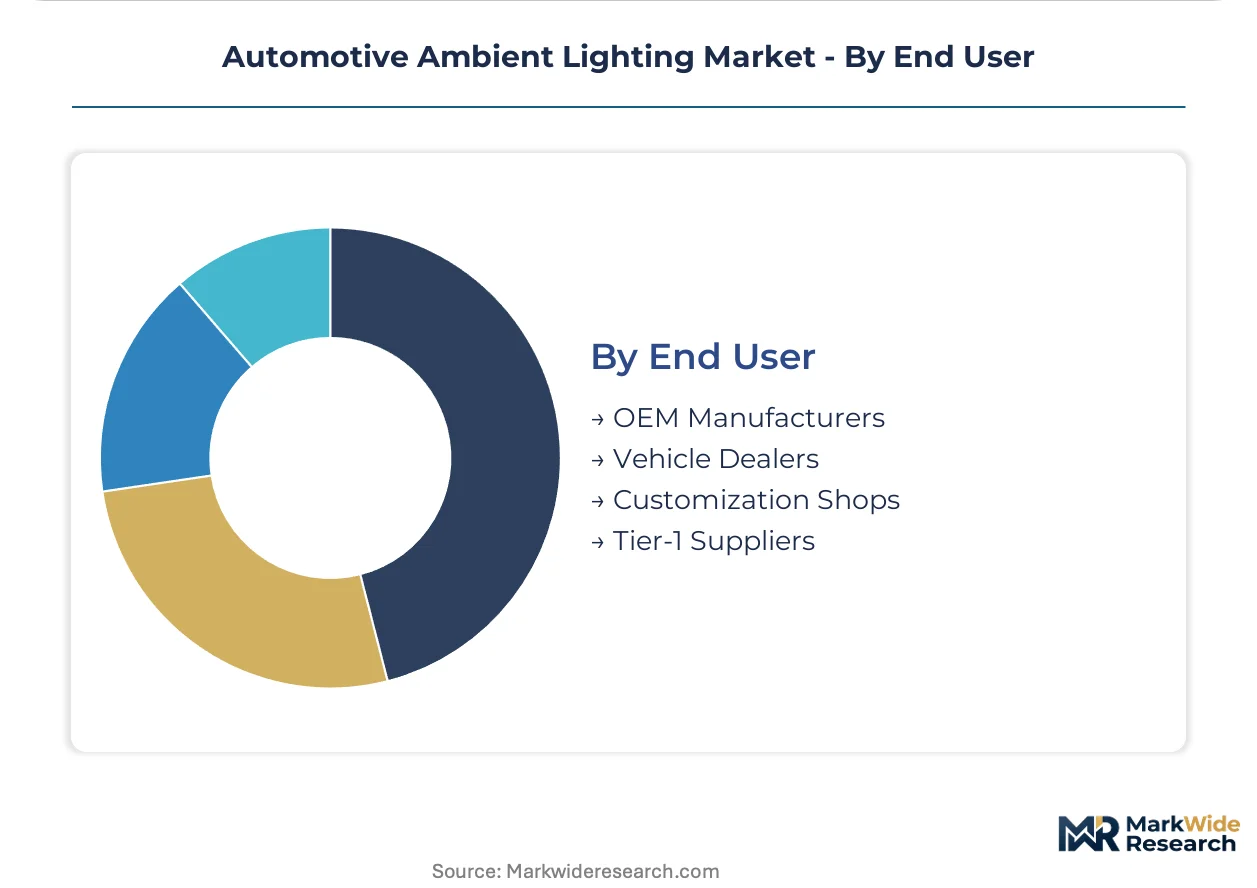
End User:
Supply concentration shapes this category: OEM manufacturers and Tier-1 suppliers cluster around European automotive corridors while dealers and customization shops distribute through fragmented aftermarket networks.
- OEM Manufacturers:Vehicle brand owners specifying interior lighting as brand differentiation element. German luxury programs unbundle hardware from software, awarding LED chip supply separately from dynamic control integration.
- Tier-1 Suppliers:FORVIA, Valeo, and ams OSRAM anchor dashboard and roof liner supply chains through captive optical electronics production.
- Vehicle Dealers:Authorized service networks developing certified installation capabilities for programmable system upgrades.
- Customization Shops:Independent aftermarket channels serving enthusiast segments with non-certified retrofit installations.
OEM manufacturers command the established base. Tier-1 suppliers are gaining share fastest on supply chain consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German Tier-1 suppliers export dashboard illumination systems to premium vehicle assembly plants across North America and Asia-Pacific. Stuttgart and Munich OEM clusters drive specification standards that cascade through global supply chains.
Germany
Luxury EV programs in Stuttgart and Munich corridors specify roof liner OLED panels for brand differentiation. ECE R48 compliance mandates force upgrade cycles from static to dynamic lighting architectures. Baden-Württemberg's automotive corridor concentrates FORVIA and Valeo production facilities serving Mercedes-Benz and Porsche.
United States
Premium electric vehicle assembly in California and Texas imports German-designed programmable LED systems. NHTSA glare standards impose certification burdens distinct from European ECE frameworks. Detroit's traditional OEM engineering centers face pressure to match German interior lighting sophistication.
China
Domestic EV brands specify GB-standard interior illumination for local market differentiation. MIIT regulations on vehicle electronics create parallel certification pathways from European ECE compliance. Yangtze River Delta manufacturing clusters assemble LED strips for both domestic consumption and export.
Japan
Premium hybrid programs source fiber optic light guides for curved dashboard architectures. METI industrial standards shape semiconductor component specifications for automotive-grade LED chips. Nagoya's automotive corridor hosts Koito Manufacturing and Stanley Electric production serving Toyota and Honda.
South Korea
Hyundai-Kia luxury EV platforms specify dynamic lighting synchronized to vehicle state and infotainment. MFDS automotive electronics standards align with European ECE frameworks for export market access. Seoul Capital Area engineering centers develop voice-controlled lighting interfaces.
Automotive Ambient Lighting Market Key Industry Players
Listed leaders compete with private specialists across optical electronics and semiconductor manufacturing dimensions. The vendor base concentrates around four to six dominant Tier-1 suppliers with captive LED chip production, while mid-scale specialists occupy niche application segments. Three strategic archetypes emerge: vertically integrated optical electronics manufacturers, display panel specialists pivoting into automotive, and electronics integrators bundling lighting control with infotainment systems. M&A activity targets software-defined illumination capabilities, while capacity expansion concentrates in European automotive corridors serving German OEM clusters.
Within the vertically integrated tier, FORVIA (HELLA) and Valeo occupy positions anchored in European automotive supply chains, with FORVIA representing backward integration into optical electronics and Valeo exemplifying dynamic lighting intelligence. ams OSRAM sits within the semiconductor specialist archetype, supplying LED chip components from Austrian manufacturing bases. These three companies collectively illustrate how supply chain control over specialized components determines margin capture in programmable lighting architectures.
| Leading Market Players |
|---|
| FORVIA (HELLA) |
| Valeo |
| ams OSRAM |
| Koito Manufacturing |
| Stanley Electric |
| Signify (Philips Lighting) |
| Grupo Antolin |
| DRÄXLMAIER Group |
| Magneti Marelli |
| Others |
Cost & Logistics Intelligence
ECE R48 certification gates both supplier qualification and price differentiation simultaneously, forcing OEMs to pay premiums for compliant dynamic systems while excluding uncertified static alternatives from European programs. This regulatory barrier creates a bifurcated market where certified suppliers capture margin pools in German premium vehicle corridors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ECE certification grade and volume scale, with dynamic systems commanding multiples over static alternatives. Cost compression in economy tiers is intensifying because phosphor material sourcing faces ECHA REACH compliance burdens. Tier-1 suppliers show least price sensitivity; aftermarket retrofit channels exhibit highest sensitivity.
Supply Chain Analysis
Just-in-time inventory strategies dominate German and French Tier-1 production facilities, while strategic stockpiling of rare-earth phosphors occurs in Austrian semiconductor corridors. Supply concentrates in Germany, China, and South Korea for LED chips and optical electronics. Raw material dependencies include rare-earth phosphors, gallium nitride substrates, and polymer light guide resins. Single-source vulnerability persists in specialized semiconductor components. Distribution runs through captive OEM supply chains and authorized dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ECE certification requirements create switching costs that lock OEMs into qualified supplier relationships across vehicle program lifecycles.
For Market Incumbents: Secure captive supply of specialized LED semiconductors through backward integration into optical electronics manufacturing. Expand certification engineering capacity to capture emerging CSRD-linked sustainability disclosure requirements. OLED panel specialists represent the primary emerging entrant threat to traditional fiber optic supply relationships.
For New Entrants and Emerging Players: Differentiate on voice-controlled interface integration for center console architectures, where software-defined illumination creates white space outside established Tier-1 relationships. Target aftermarket retrofit channels in premium vehicle segments as the most penetrable entry point. Pursue certified installation partnerships with authorized dealer networks as the primary go-to-market angle.
For Investors and Strategic Acquirers: ECE R48 compliance deadlines reshape the acquisition landscape toward suppliers with established certification pathways and OEM program relationships. Long-term viability favors vertically integrated specialists with captive semiconductor production. The signal to watch is OEM unbundling of hardware supply from software development, which fragments value capture and creates rollup opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Electronics | Captive LED chip production secures margin pools in programmable lighting architectures for German OEM programs. |
| ECE R48 Certification Investment | Regulatory compliance opens access to Stuttgart and Munich premium vehicle corridors. |
| OLED Panel Manufacturing Scale-Up | Conformal surface capability captures roof liner applications displacing fiber optic alternatives. |
| Voice-Control Interface Development | Human-machine interface convergence creates differentiation in French and German center console programs. |
| CSRD Supply Chain Transparency Program | Verified rare-earth traceability meets emerging European sustainability disclosure requirements. |
Research Approach
Initial hypotheses were tested against primary input from Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and optical electronics R&D heads and refined through secondary validation. Sources included vehicle production databases, IHS Markit registration data, ECE regulatory filings, and customs trade records. Bottom-up segment sizing triangulated against top-down market value estimates.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster shaped the analytical framework. CAGRs were derived from modeled segment trajectories across the projection horizon. Key inputs included LED penetration rates by vehicle tier and OLED adoption curves in premium EV programs.
The analysis sits within stated boundaries; outcomes outside sustained German luxury EV production growth or ECE regulatory stability would require recalibration. Forecasts reflect documented assumptions on phosphor material cost trajectories and OEM unbundling trends. Revision becomes warranted when rare-earth supply disruption or regulatory divergence crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive 3D Surface Display Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Center Stack Display Market