
 Automotive Active Spoiler Market | 2026-2036
Automotive Active Spoiler Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Spoiler Market Analysis
Performance-grade active spoiler specifications is collapsing into mainstream vehicle architectures as OEMs chase aerodynamic efficiency gains. Magna International Inc. leverages its integrated mechatronics capabilities to supply full active spoiler modules with embedded actuators and control logic. BMW Group sustains engineering leadership through proprietary adaptive aerodynamics systems deployed across its M Performance and electric vehicle portfolios. Aisin Seiki Co., Ltd. anchors Japanese supply chains with precision motor and sensor integration for deployable spoiler mechanisms.
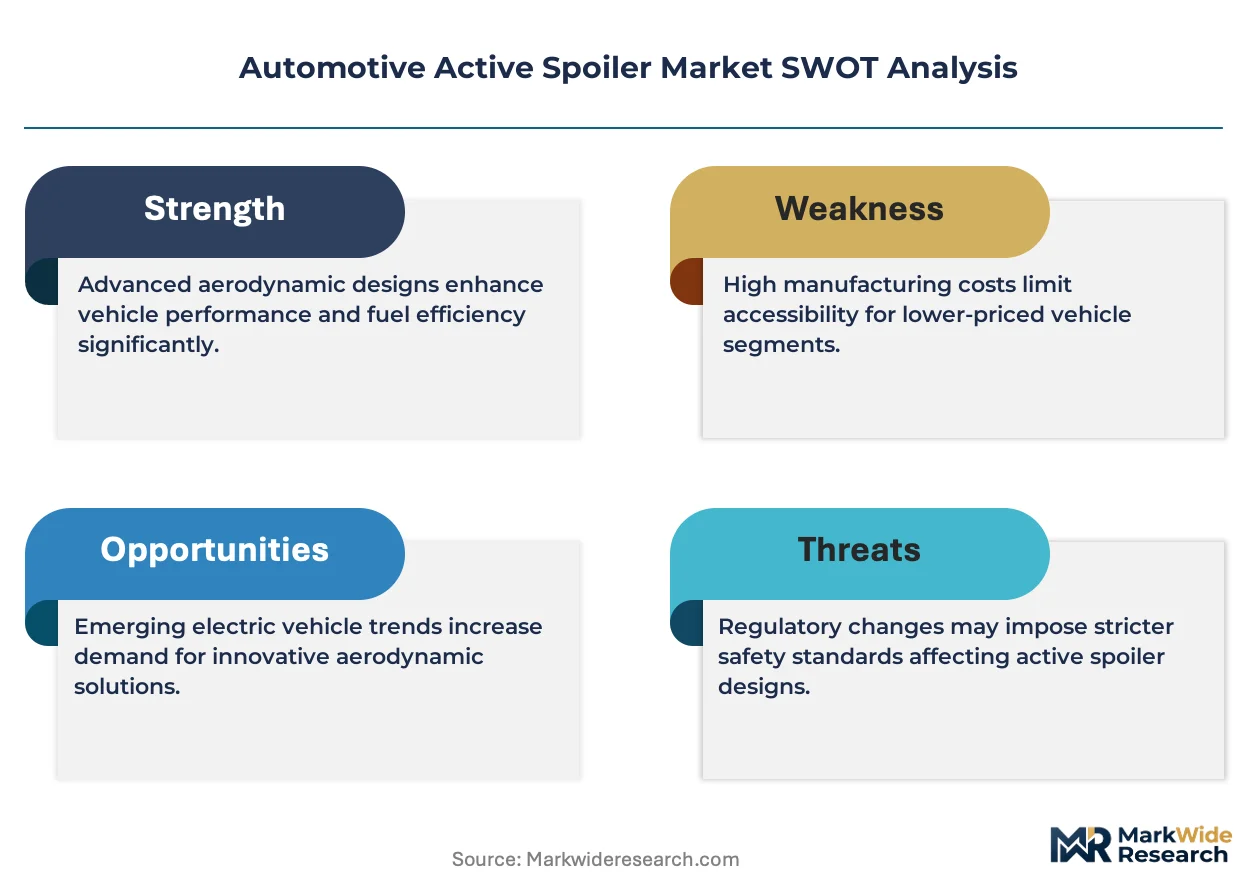
An automotive active spoiler is an electromechanically actuated aerodynamic device, typically manufactured from carbon fiber reinforced polymer or injection-molded thermoplastic composites, that dynamically adjusts its angle and profile in response to vehicle speed, braking events, and handling loads to reduce drag coefficient or increase downforce. Rear spoiler configurations dominate value capture given their integration with trunk lid assemblies and higher actuator complexity, while front spoiler segments are gaining structural importance as electric vehicle platforms prioritize underbody airflow management. Carbon fiber material grades command premium positioning in motorsport-derived and ultra-luxury applications, whereas aluminum and advanced plastic compounds occupy volume production tiers where cost efficiency governs procurement decisions.
NHTSA fuel economy standards and EPA emissions regulations in the United States compel OEMs to adopt active aerodynamics as a certified compliance pathway, while EU Green Deal carbon neutrality targets and ECE vehicle type-approval frameworks in Europe mandate verifiable drag reduction technologies across new vehicle fleets. Japan's METI energy efficiency directives and corresponding JIS quality standards shape domestic supplier qualification requirements for electromechanical automotive components. Stakeholders must monitor evolving battery-electric vehicle platform architectures, where cooling airflow needs and extended-range efficiency targets are redefining active spoiler functional specifications and integration protocols.
Market Dynamics
Active spoiler system complexity is concentrating procurement power among tier-one integrators capable of delivering embedded actuator-control modules, compressing supplier margins and forcing mid-tier manufacturers toward specialized subcomponent niches.
Growth Catalysts
- EU Green Deal fleet mandates:Binding carbon neutrality targets for 2035 vehicle fleets require verifiable drag reduction technologies, positioning active aerodynamics as a certified compliance pathway for European OEMs.
- Carbon fiber composite advances:Automated fiber placement and resin transfer molding processes are reducing cycle times for spoiler shell production, enabling cost-efficient scaling from motorsport to volume passenger car platforms.
- Electric vehicle thermal management:Battery-electric architectures demand active underbody airflow control for cooling optimization, extending spoiler functionality beyond downforce into thermal regulation systems.
Market Restraints
- Actuator motor supply concentration:Precision brushless DC motor production for spoiler mechanisms clusters in Japanese and German supplier networks, creating vulnerability to regional production disruptions.
- Carbon fiber raw material volatility:Polyacrylonitrile precursor supply constraints and energy-intensive oxidation processes generate input cost instability for composite spoiler manufacturers.
- Homologation timeline friction:ECE R79 steering equipment regulations and NHTSA FMVSS 126 stability control mandates impose extended validation periods for new active spoiler deployments.
Strategic Opportunities
- India premium vehicle segment:Luxury car sales expansion and domestic PLI scheme incentives for automotive component manufacturing create white space for active spoiler system localization.
- Software-defined aerodynamics:Convergence of edge computing and vehicle-to-cloud connectivity enables over-the-air spoiler calibration updates and predictive deployment algorithms.
- Aftermarket retrofit channels:Motorsport enthusiast segments and classic vehicle electrification projects are generating demand for modular active spoiler upgrade kits through specialized distributors.
Industry Challenges
- Mechatronics systems integration:Synchronizing spoiler actuation with braking, stability control, and powertrain management requires cross-functional engineering coordination that strains traditional organizational silos.
- Functional safety certification:ISO 26262 ASIL-D compliance for safety-critical spoiler deployment mechanisms demands specialized verification expertise and extended development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Spoiler Market |
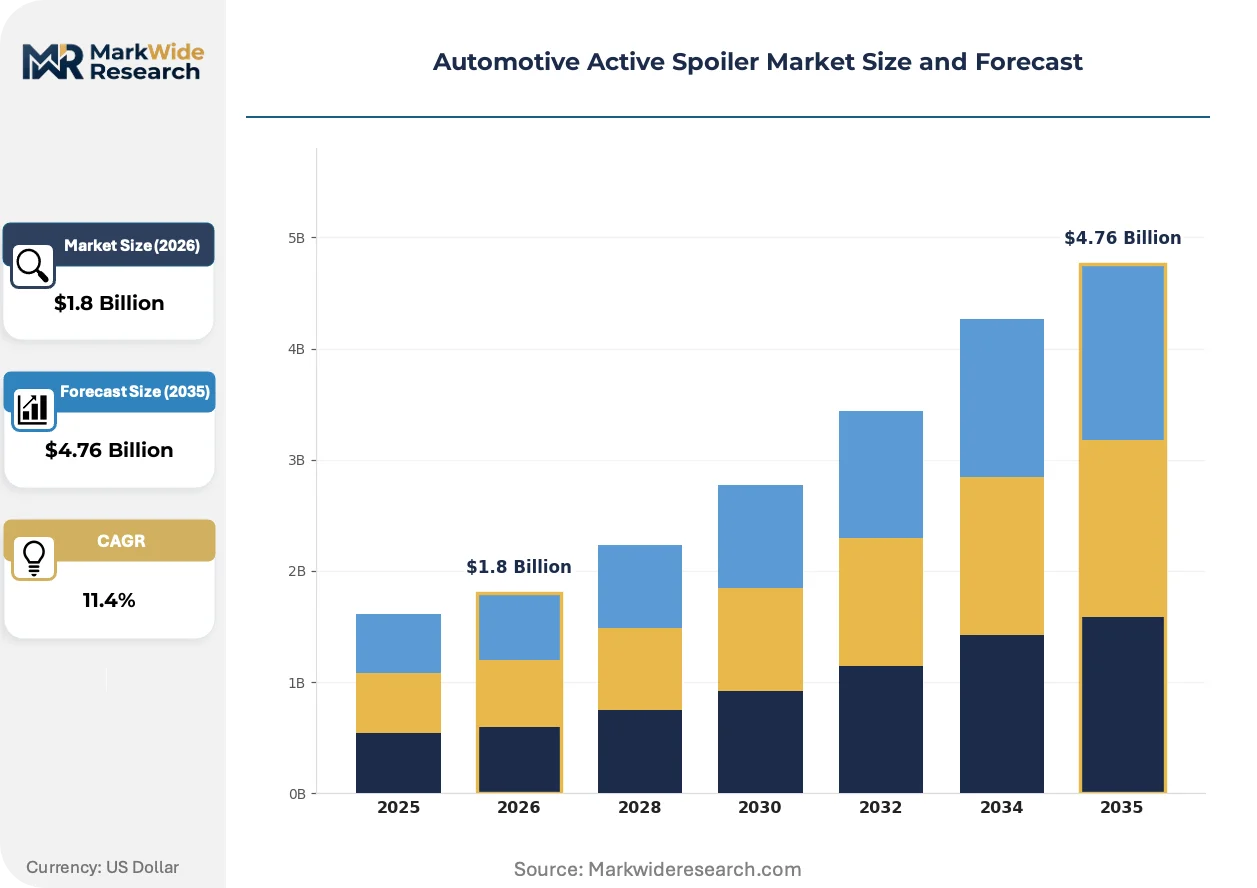
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rear Spoiler, Front Spoiler, Liftgate Spoiler, Roof Spoiler Installation Type: OEM, Aftermarket, Integrated, Standalone Material: Plastic, Carbon Fiber, Aluminum, Fiberglass Vehicle Type: Sedan, SUV, Hatchback, Coupe |
| Companies Covered | Magna International Inc., Aisin Seiki Co., Ltd., Polytec Holdings AG, OPmobility SE, SMP Deutschland GmbH, Porsche AG, Mercedes-Benz Group AG, BMW Group, Ferrari S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Spoiler Market Emerging Trajectories
Intelligent material systems and predictive control algorithms are redefining active spoiler value propositions, shifting competitive differentiation from mechanical reliability toward software-enabled aerodynamic optimization.
Shape-memory alloy actuation mechanisms are supplanting conventional electric motor-driven hinge systems in next-generation spoiler designs. Ultra-luxury and motorsport-derived vehicle programs at Porsche AG and Mercedes-AMG are piloting nickel-titanium actuator configurations that reduce component count and eliminate backlash. This transition is compressing the traditional electromechanical supplier base while elevating materials science capabilities as a primary vendor selection criterion.
EPA emissions certification pathways now explicitly recognize active aerodynamic devices as fuel economy improvement technologies under off-cycle credit provisions. United States-based OEMs are restructuring engineering workflows to document spoiler-induced drag reduction during standardized test cycles. Light truck and full-size SUV segments, historically aerodynamically indifferent, are now prioritizing active spoiler integration to offset frontal area penalties.
Fleet procurement of active aerodynamic packages is consolidating around full-system integrators rather than discrete component sourcing. Volume passenger car manufacturers are awarding multi-year spoiler module contracts to tier-one suppliers with captive actuator and sensor production. Germany anchors this consolidation pattern, where BMW Group and Mercedes-Benz Group AG have standardized on single-source active spoiler architectures across platform derivatives.
Automotive Active Spoiler Market Segmentation
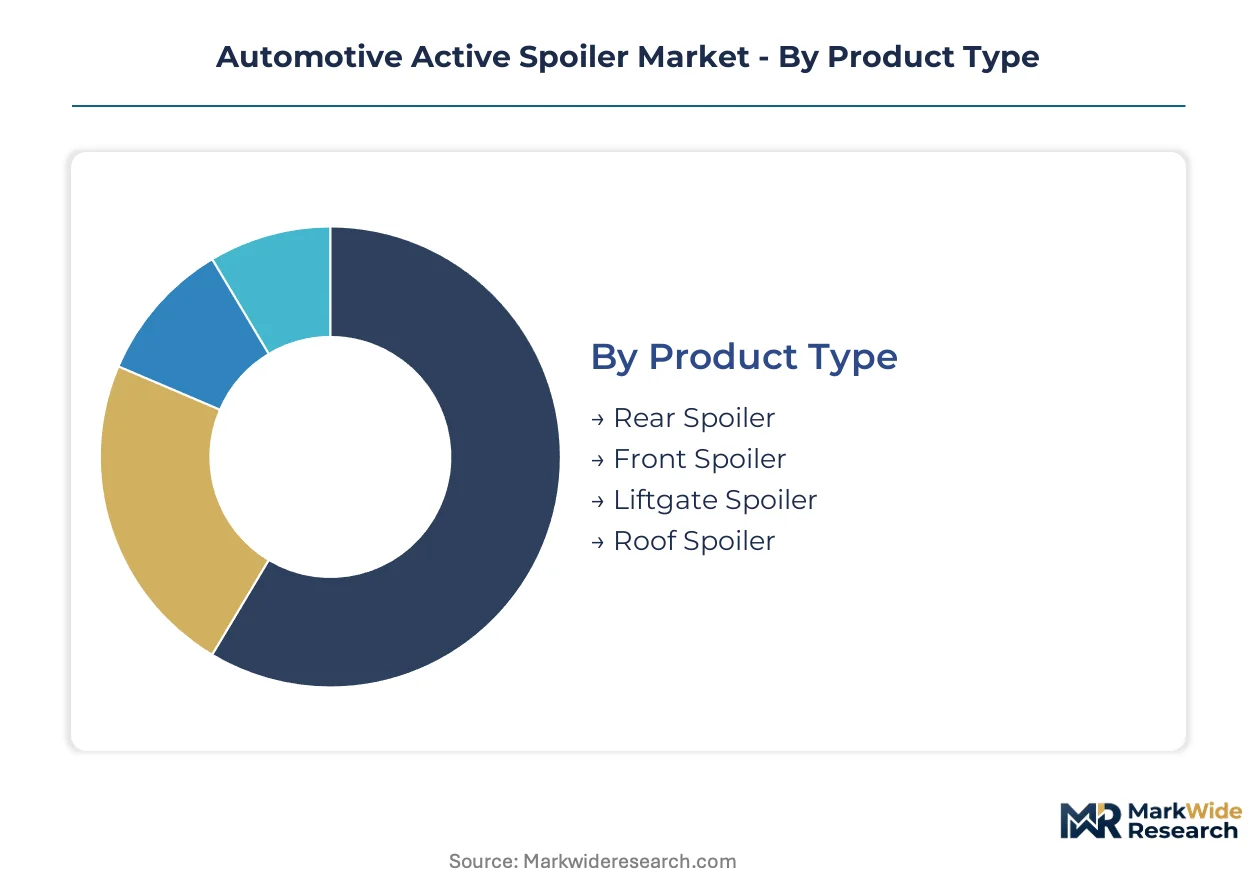
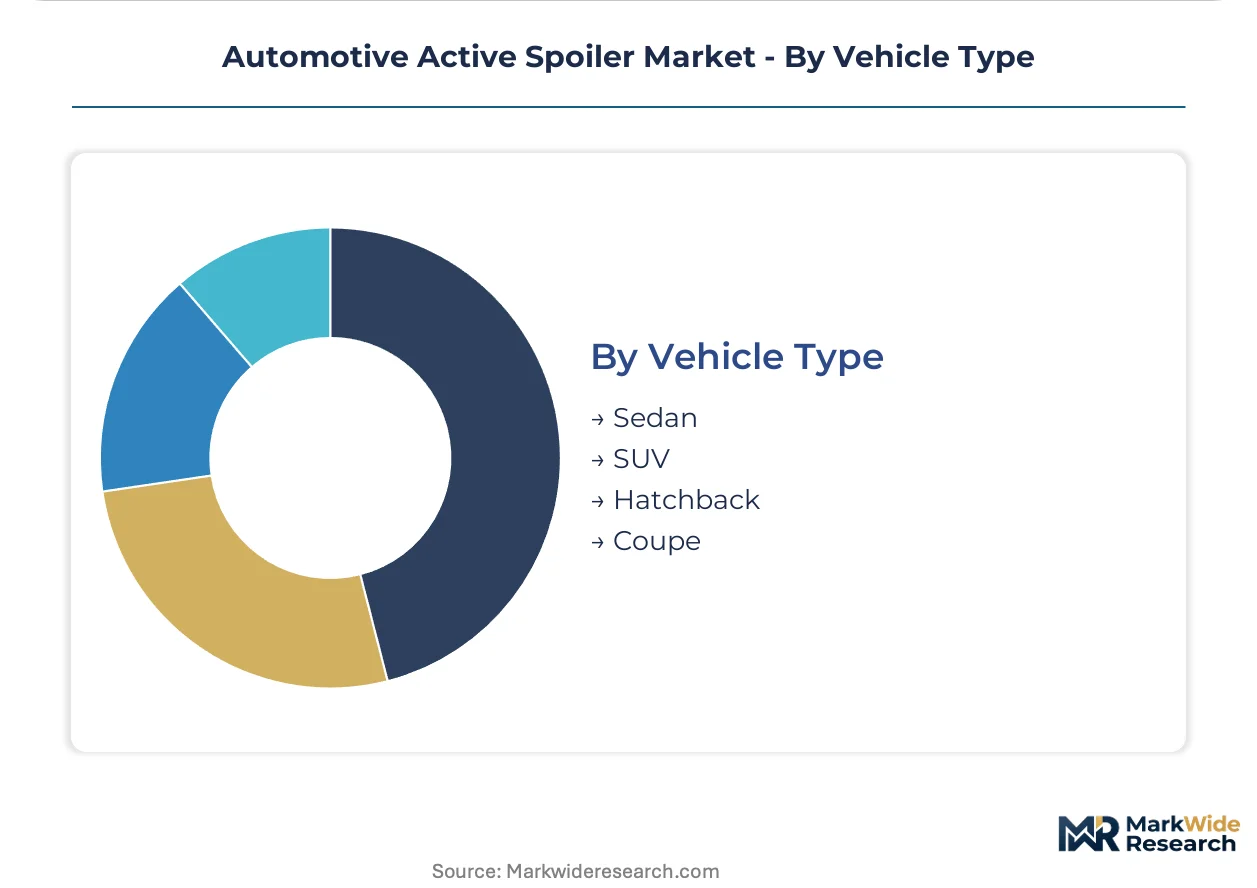
Active spoiler procurement patterns diverge sharply across material grades, installation channels, and vehicle architectures. OEM engineering teams calibrate specification tiers to platform positioning, creating distinct margin pools that reward suppliers with cross-category integration capabilities.
Product Type:
EPA off-cycle credit provisions and ECE R79 steering equipment regulations impose differentiated homologation burdens on spoiler positioning relative to vehicle center of gravity.
- Rear Spoiler:Electromechanically actuated trunk-integrated systems deploy multi-position profiles for drag reduction or downforce generation. Demand concentrates in Germany, where Porsche AG and Mercedes-AMG anchor development of intelligent rear mechanisms for high-performance platforms; EU Green Deal fleet mandates compel verifiable aerodynamic efficiency documentation.
- Front Spoiler:Active underbody airflow management devices extend spoiler functionality into thermal regulation for battery-electric architectures. Adoption is climbing fastest among electric vehicle platforms prioritizing extended-range efficiency targets over downforce generation.
- Liftgate Spoiler:Rear-hatch integrated actuators serve compact SUV and hatchback segments with simplified hinge mechanisms.
- Roof Spoiler:Cabin-top mounted profiles manage airflow separation for van and wagon architectures with extended rear overhangs.
Established volume favors Rear Spoiler; emerging adoption favors Front Spoiler.
Installation Type:
Margin structures compress from integrated module contracts toward discrete component supply, with tier-one integrators capturing value through captive actuator production.
- OEM:Factory-installed active spoiler modules with embedded control logic and vehicle network integration command premium positioning. BMW Group and Mercedes-Benz Group AG have standardized on single-source architectures across platform derivatives, consolidating procurement power among full-system integrators.
- Aftermarket:Modular retrofit kits serve motorsport enthusiast segments and classic vehicle electrification projects through specialized distributors. This channel is expanding most quickly as software-defined aerodynamics enables over-the-air calibration updates for non-factory installations.
- Integrated:Spoiler-actuator assemblies molded into body-in-white structures during assembly line sequencing.
- Standalone:Bolt-on replacement units for collision repair and fleet refurbishment operations.
Procurement concentration favors OEM; margin expansion favors Aftermarket.
Material:
Raw material volatility and automated manufacturing advances are repositioning cost-performance tradeoffs across composite and metallic grades.
- Carbon Fiber:Automated fiber placement and resin transfer molding processes are reducing cycle times for spoiler shell production. Polyacrylonitrile precursor supply constraints generate input cost instability that constrains scaling from motorsport to volume passenger car platforms.
- Plastic:Injection-molded thermoplastic composites occupy volume production tiers where cost efficiency governs procurement decisions; this segment is gaining share fastest as OEMs chase aerodynamic efficiency gains in mainstream vehicle architectures.
- Aluminum:Cast and extruded alloys balance weight reduction with impact durability for mid-market SUV applications.
- Fiberglass:Chopped strand mat constructions serve aftermarket price-sensitive segments with simplified tooling requirements.
Performance positioning favors Carbon Fiber; cost-driven scaling favors Plastic.
Vehicle Type:
Platform electrification and thermal management requirements are redefining spoiler functional specifications across body style categories.
- SUV:Full-size and compact sport utility platforms now prioritize active spoiler integration to offset frontal area penalties. Light truck segments, historically aerodynamically indifferent, are restructuring engineering workflows to document drag reduction during standardized EPA test cycles.
- Sedan:Three-box architectures with dedicated trunk volumes retain the most mature active spoiler penetration; this segment holds established volume as traditional luxury manufacturers sustain engineering leadership through proprietary adaptive aerodynamics systems.
- Hatchback:Liftgate-integrated mechanisms serve European and Asian volume manufacturers with simplified actuator configurations.
- Coupe:Two-door performance platforms anchor ultra-luxury and motorsport-derived programs piloting nickel-titanium shape-memory alloy actuation.
Volume concentration favors Sedan; specification intensity favors SUV.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports active spoiler modules to premium vehicle assembly plants across the United States, China, and the United Kingdom, anchoring the dominant trade-flow corridor in intelligent aerodynamic systems.
Germany
Porsche AG and Mercedes-Benz Group AG sustain engineering leadership through proprietary adaptive aerodynamics deployed across high-performance platforms. EU Green Deal fleet mandates for 2035 carbon neutrality compel verifiable drag reduction documentation. Stuttgart and Munich anchor development clusters where tier-one integrators deliver full active spoiler modules with embedded actuators.
United States
Light truck and full-size SUV segments now prioritize active spoiler integration to offset frontal area penalties under tightening efficiency standards. NHTSA fuel economy standards and EPA emissions regulations explicitly recognize active aerodynamics as certified compliance pathways. Detroit engineering centers restructure workflows to document spoiler-induced drag reduction during standardized EPA test cycles.
Japan
Aisin Seiki Co., Ltd. anchors domestic supply chains with precision motor and sensor integration for deployable spoiler mechanisms. METI energy efficiency directives and corresponding JIS quality standards shape supplier qualification requirements for electromechanical automotive components. Nagoya and Tokyo metropolitan areas concentrate brushless DC motor production for spoiler actuation systems.
China
Battery-electric vehicle platforms prioritize active underbody airflow control for cooling optimization and extended-range efficiency targets. MIIT new energy vehicle regulations and GB standards mandate aerodynamic performance verification for domestic EV certification. Shanghai and Shenzhen engineering hubs drive localization of composite spoiler manufacturing for volume passenger car platforms.
India
Luxury car sales expansion and domestic PLI scheme incentives for automotive component manufacturing create white space for active spoiler system localization. BIS quality standards and DGFT import substitution policies favor domestic sourcing of electromechanical aerodynamic devices. Maharashtra and Gujarat industrial corridors attract tier-one spoiler module assembly investments from global suppliers.
Automotive Active Spoiler Market Vendor Landscape
Listed leaders compete with private specialists across integrated mechatronics capabilities, creating a tiered structure where full-system integrators capture procurement power from mid-tier component suppliers. Tier-one automotive suppliers with captive actuator production dominate factory-installed module contracts. Three archetypes define competitive positioning: integrated module specialists, precision motor and sensor fabricators, and OEM-captive engineering divisions. Market consolidation accelerates through multi-year spoiler platform contracts and backward integration into carbon fiber composite manufacturing.
Within the integrated module tier, Magna International Inc. and OPmobility SE exemplify full-system suppliers delivering spoiler-actuator assemblies with embedded control logic. Aisin Seiki Co., Ltd. occupies a specialist position in precision electromechanical components for deployable mechanisms. Porsche AG, Mercedes-Benz Group AG, and BMW Group anchor the OEM-captive tier, sustaining proprietary adaptive aerodynamics development through in-house engineering divisions that standardize architectures across platform derivatives.
| Leading Market Players |
|---|
| Magna International Inc. |
| Aisin Seiki Co., Ltd. |
| Polytec Holdings AG |
| OPmobility SE |
| SMP Deutschland GmbH |
| Porsche AG |
| Mercedes-Benz Group AG |
| BMW Group |
| Ferrari S.p.A. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal fleet mandates and ECE R79 steering equipment regulations gate both supplier qualification and price differentiation simultaneously, compressing margins for non-certified manufacturers while elevating premium positioning for compliant full-system integrators. Industrial OEM buyers anchor contract-based long-term offtake pricing, with three-tier pricing structure across premium, standard, and economy levels separating carbon fiber motorsport-grade systems from aluminum mid-market configurations and injection-molded plastic volume tiers. Price differentiation rests on ISO 26262 ASIL-D certification level and captive actuator production capabilities. Pricing pressure stems from polyacrylonitrile precursor cost volatility in composite grades. Aftermarket retrofit buyers exhibit highest price sensitivity; OEM-captive engineering divisions show lowest.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing structures, with three-tier pricing structure across premium, standard, and economy levels separating carbon fiber motorsport-grade systems from aluminum mid-market configurations and injection-molded plastic volume tiers. Price differentiation rests on ISO 26262 ASIL-D certification level and captive actuator production capabilities. Pricing pressure stems from polyacrylonitrile precursor cost volatility in composite grades. Aftermarket retrofit buyers exhibit highest price sensitivity; OEM-captive engineering divisions show lowest.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for carbon fiber precursor shipments from Japan and Taiwan. Manufacturing concentrates in Germany, China, and Japan, drawing from polyacrylonitrile fiber, rare-earth magnet materials, and precision-machined aluminum castings. Single-source vulnerability clusters in Japanese brushless DC motor production. Distribution runs through tier-one integrator direct-to-OEM channels with embedded control logic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined aerodynamics services and over-the-air calibration subscriptions expand faster than hardware sales, creating recurring-revenue layers that outperform one-time module transactions.
For Market Incumbents: Secure captive carbon fiber composite manufacturing through backward integration into automated fiber placement capabilities to defend against emerging Asian volume suppliers. Lock in multi-year platform contracts with BMW Group and Mercedes-Benz Group AG before EU Green Deal compliance deadlines force supplier consolidation. Certification investment in ISO 26262 ASIL-D verification expertise remains the critical lever. For New Entrants and Emerging Players: Aftermarket software retrofit gaps where incumbents under-serve classic vehicle electrification projects offer the most penetrable entry vector. Target India premium vehicle segment through PLI scheme-qualified local assembly partnerships. Motorsport enthusiast channels provide lowest competitive density for modular active spoiler upgrade kits with cloud-connected calibration services. For Investors and Strategic Acquirers: EU Green Deal 2035 carbon neutrality mandates reshape the acquisition landscape toward full-system integrators with embedded actuator-control modules. Five-to-ten-year viability favors tier-one suppliers with captive mechatronics capabilities over discrete component fabricators. Watch for EPA off-cycle credit rulemaking expansion into light truck segments as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | BMW Group and Mercedes-Benz Group AG single-source architectures reduce engineering validation costs across derivatives. |
| Backward Integration into Carbon Fiber | Magna International Inc. and OPmobility SE captive composite production insulates against polyacrylonitrile volatility. |
| Software-Defined Vehicle Investment | Edge computing and vehicle-to-cloud connectivity enable predictive spoiler deployment algorithms and subscription calibration. |
| Geographic Manufacturing Footprint | India PLI scheme incentives attract tier-one spoiler module assembly investments in Maharashtra and Gujarat corridors. |
| Battery Supply Agreement | Electric vehicle thermal management partnerships extend spoiler functionality into cooling optimization systems. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership operations anchored the qualitative base. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs/trade records. Bottom-up and top-down triangulation cross-checked segment assumptions.
Sensitivity analysis tested input variations across the analysis window, with segmentation dimensions covering vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from regression-based modeling of historical penetration rates against regulatory mandate timelines. Forecast inputs incorporated battery-electric platform rollout schedules and carbon fiber composite manufacturing scale curves.
Underlying assumptions cover EU Green Deal compliance adherence, polyacrylonitrile supply stability, and brushless DC motor production continuity, with deviation risk concentrated in homologation timeline extensions and raw material cost spikes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Automotive Door Frame Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Automotive Baggage Handling System Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Laser Headlight Market