
 China Automotive Seats Market | 2026-2036
China Automotive Seats Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Seats Market Outlook
Multi-source procurement among domestic EV brands is realigning supplier relationships across the China Automotive Seats Market. Yanfeng Adient Seating leverages its joint-venture structure to dominate premium passenger car programs. Lear Corporation anchors North American transplant production networks operating within China. Faurecia competes through specialized sustainable material portfolios targeting carbon-neutral cabin ambitions.
Automotive seats are engineered assemblies comprising steel frames, polyurethane foam cushioning, suspension systems, and trim covers designed to provide occupant support, safety restraint integration, and thermal comfort during vehicle operation. Bucket seats lead passenger car configurations while powered seats with adjustable lumbar represent the fastest-growing feature category as Chinese consumers prioritize ergonomic customization. Fabric materials sustain mass-market volume dominance though leather and synthetic segments capture disproportionate margin pools in premium electric vehicle lineups.
China's MIIT enforces GB standards governing seat strength, flammability, and head restraint geometry that directly shape supplier qualification thresholds. SAMR administers market access protocols and quality certification requirements affecting both domestic producers and import brands. The country's dual carbon goals are forcing foam suppliers and frame manufacturers to reformulate materials and processes. Stakeholders must monitor regulatory evolution around recycled content mandates and smart seat integration standards to preserve positioning.
Market Dynamics
China's dual carbon goals are compressing foam supplier margins and forcing frame manufacturers to reformulate steel alloys and polyurethane chemistries across the Yangtze River Delta manufacturing cluster.
Growth Catalysts
- GB Standard Tightening:MIIT-enforced flammability and head restraint geometry rules are raising qualification thresholds that filter out low-capability suppliers and consolidate procurement toward certified tier-ones.
- EV Platform Expansion:Domestic electric vehicle OEMs are expanding seat customization programs across model lines, pulling demand for powered lumbar and thermal comfort features.
- Yangtze River Delta Concentration:Shanghai and Jiangsu province manufacturing bases anchor 60-plus percent of national seat assembly capacity, creating supplier ecosystem density that accelerates prototype-to-production cycles.
Market Restraints
- Steel and Polyurethane Volatility:Input cost swings for cold-rolled steel and MDI-based foam chemicals compress assembler margins during contract renegotiation windows.
- Joint-Venture Supply Lock-in:Yanfeng Adient Seating and similar JVs control premium passenger car program access, creating barrier-to-entry for independent domestic challengers.
- Recycled Content Technical Ceiling:Current mechanical recycling processes for seat textiles and foams cannot yet meet GB strength specifications at commercial scale.
Strategic Opportunities
- Smart Seat Integration:Convergence of pressure sensors, occupancy detection, and thermal management hardware creates white space for electronics-integrated seating modules.
- Western China Logistics:Chongqing and Sichuan province vehicle assembly growth remains underpenetrated by tier-one seating suppliers relative to coastal density.
- SAMR Carbon Labeling:Pending market access protocols for carbon-neutral cabin materials will favor suppliers with validated lifecycle data and recycled feedstock chains.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Integration of software, sensor hardware, and traditional seating mechanics requires skill sets concentrated in consumer electronics, not automotive supply bases.
- GB Certification Timeline Compression:Seat strength and flammability testing protocols now run concurrent with vehicle development cycles, eliminating buffer periods for design iteration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Seats Market |
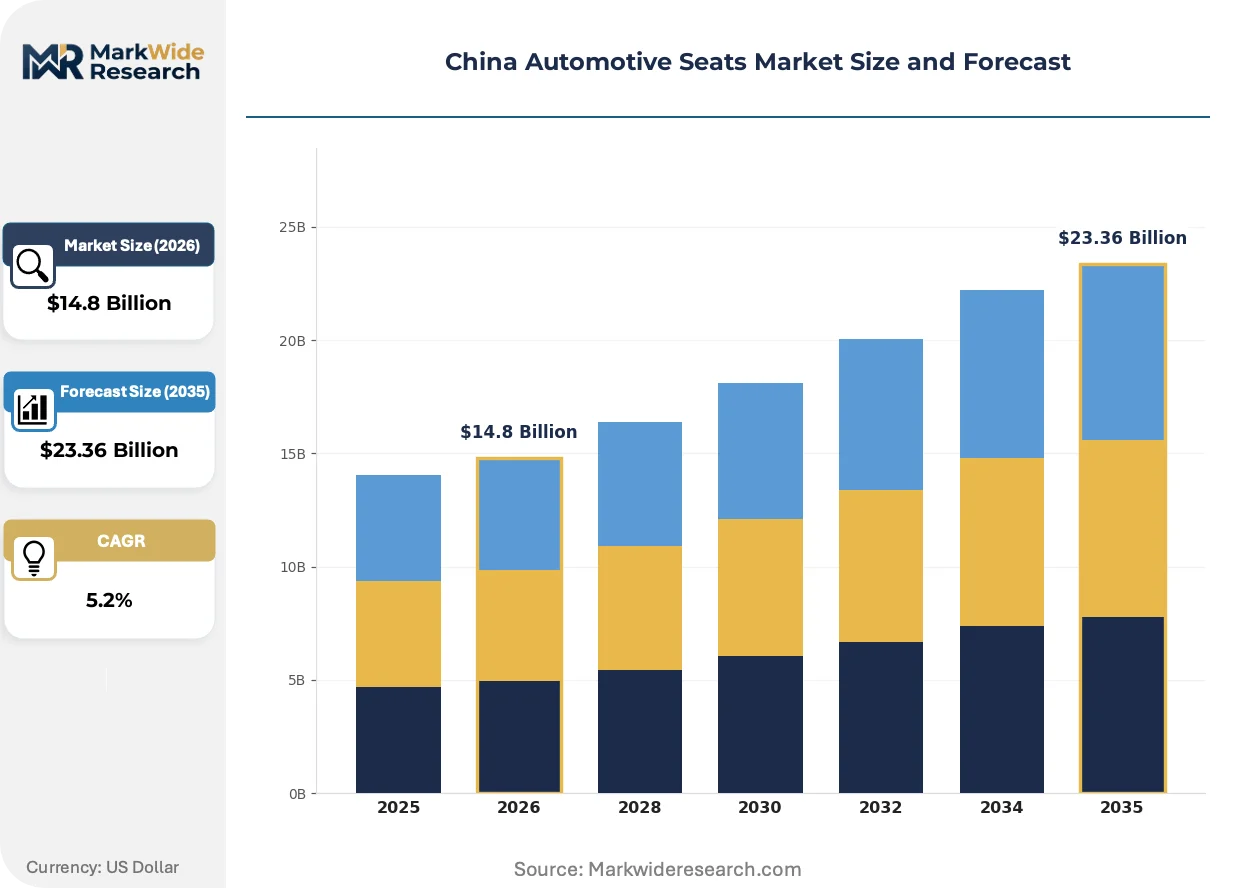
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.36 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket Seats, Bench Seats, Reclining Seats, Powered Seats Material: Fabric, Leather, Synthetic, Foam End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Features: Heated Seats, Ventilated Seats, Adjustable Lumbar, Integrated Safety |
| Companies Covered | Lear Corporation, Yanfeng Adient Seating, Faurecia, Magna International, Toyota Boshoku, TS Tech, Brose, Adient, Hyundai Transys, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Seats Market Strategic Shifts
Active materials and embedded electronics are redefining what automotive seating assemblies deliver beyond passive occupant support.
Structural foams derived from bio-based polyols are overtaking conventional petroleum-derived cushioning in premium EV lineups. NIO and Li Auto specify these materials for weight reduction and carbon accounting transparency. The shift is overtaking traditional MDI foam formulations in segments where OEM sustainability reporting is mandatory.
MIIT's evolving GB standards for vehicle interior air quality and flammability are mandating material disclosure down to additive level. Suppliers must now submit complete chemical composition data for seat foams, textiles, and adhesives to maintain market access. Premium electric vehicle programs are responding fastest, using compliance as a competitive positioning tool against mass-market competitors.
Direct OEM procurement of seat sub-assemblies is fragmenting traditional tier-one relationships. Domestic EV brands now source frames from steel stampers, foam from chemical specialists, and trim from textile mills separately, then integrate through contract manufacturers. This pattern is most visible in Guangdong province, where BYD and XPeng operate parallel supplier development programs that bypass legacy seating JVs.
China Automotive Seats Market Segmentation
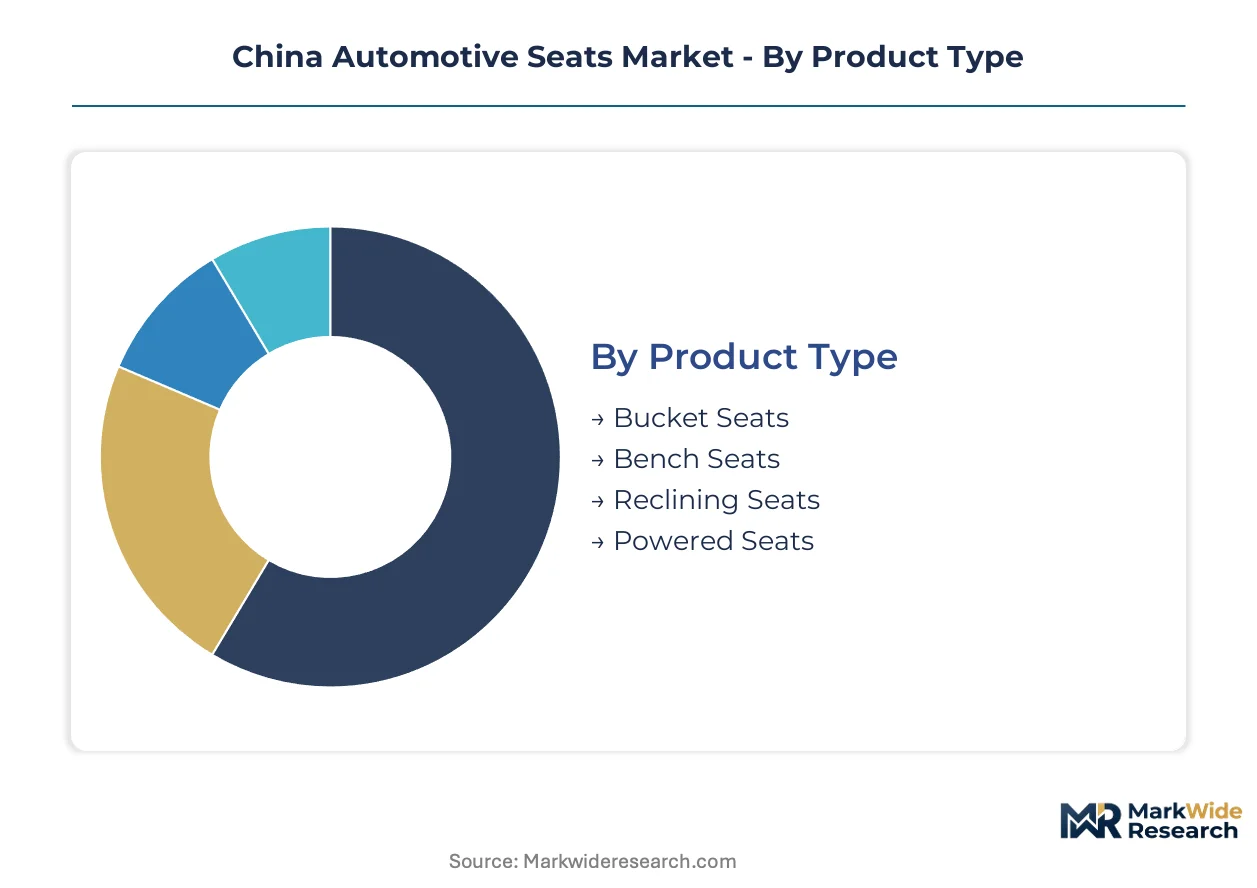
Seat configuration choices in China track directly with platform electrification cycles and interior upgrade cadences. Material and feature specifications diverge sharply between mass-market compliance-driven programs and premium EV customization initiatives.
Product Type:
Replacement cycles for seat architectures accelerate as EV platforms refresh interiors faster than legacy ICE vehicles.
- Bucket Seats:Individual bucket configurations dominate passenger car architectures with integrated head restraints and side bolstering. Yangtze River Delta assembly plants specify these for 60-plus percent of sedan and SUV output, driven by consumer preference for personalized space definition.
- Powered Seats:Motorized adjustment mechanisms with memory positioning and programmable lumbar support represent the steepest expansion trajectory. Domestic EV brands specify these across mid-tier and above model lines as standard equipment, compressing upgrade cycles from premium to mass-market penetration.
- Bench Seats:Continuous bench configurations persist in commercial vehicle and entry-level passenger applications. Fleet operators in Jiangsu province specify these for durability and simplified maintenance protocols.
- Reclining Seats:Articulating backrest mechanisms with extended travel ranges serve luxury and MPV segments. Li Auto and NIO programs specify these for second-row comfort positioning.
Bucket seats sit at the top of the volume ranking, with powered seats climbing the fastest.
Material:
Cost tier differentiation in seating materials separates compliance-grade programs from carbon-accounting premium offerings.
- Fabric:Woven textile coverings with polyester or nylon substrates sustain mass-market volume leadership. Shanghai-based assemblers specify these for fleet and entry-level retail channels where procurement cost sensitivity dominates specification decisions.
- Foam:Polyurethane cushioning systems with density-calibrated layering determine occupant comfort and crash performance. MDI-based formulations face margin compression from dual carbon goals, while bio-based polyols gain specification share in NIO and Li Auto lineups.
- Leather:Full-grain and corrected-grain hides command specification in premium passenger car programs. Yanfeng Adient Seating sources these through controlled tannery partnerships for joint-venture vehicle lines.
- Synthetic:PU-coated and microfiber alternatives bridge leather aesthetics with sustainability positioning. BYD and XPeng specify these for mid-tier EV interiors requiring carbon footprint transparency.
Foam underpins every seat assembly by volume, with synthetic materials gaining specification share fastest.
End User:
Supply chain configuration determines which end-user channels control specification authority and procurement timing.
- OEMs:Brand-holding manufacturers with direct platform development authority. Domestic EV OEMs in Guangdong province increasingly fragment procurement across sub-assembly specialists rather than legacy tier-one integrators.
- Tier-1 Suppliers:Full-system integrators managing frame, foam, and trim sourcing. Yanfeng Adient Seating and Lear Corporation anchor this channel through joint-venture and transplant manufacturing networks.
- Vehicle Assemblers:Contract manufacturing operations assembling complete vehicles from sourced modules. Western China expansion in Chongqing and Sichuan province pulls demand for localized seat logistics.
- Aftermarket Providers:Independent distributors serving replacement and customization demand. This channel concentrates in coastal provinces with established automotive service infrastructure.
Tier-1 suppliers command the specification authority ranking, with OEM direct procurement climbing fastest.
Features:
Feature bundling patterns separate thermal comfort specifications from safety-integrated mandates under GB standards.
- Adjustable Lumbar:Pneumatic or motorized lumbar support mechanisms with multi-position programming. Domestic EV brands specify these as standard across model lines, displacing fixed-support configurations.
- Integrated Safety:Seat-embedded pretensioners, load limiters, and occupancy sensors meeting MIIT GB strength requirements. These features carry mandatory specification status for market access certification.
- Heated Seats:Resistive element warming systems with zone control. Mass-market programs specify these for cold-climate regional variants.
- Ventilated Seats:Forced-air cooling through perforated trim surfaces. Premium EV lineups specify these for thermal comfort differentiation in southern China markets.
Integrated safety sits at the top of the mandatory specification ranking, with adjustable lumbar climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing cluster anchors national seat assembly capacity through Shanghai and Jiangsu province production bases. Provincial industrial policies and MIIT-enforced GB standards shape supplier qualification thresholds across sub-regional manufacturing networks.
Shanghai
Shanghai-based vehicle assemblers specify powered lumbar and thermal comfort features as standard equipment across mid-tier EV lineups. SAMR market access protocols require complete chemical composition disclosure for seat foams and textiles. The Pudong and Jiading industrial zones concentrate prototype-to-production cycles for premium passenger car programs.
Jiangsu Province
Jiangsu province fleet operators drive demand for durable bench seat configurations in commercial vehicle applications. Dual carbon goals compel foam suppliers to reformulate polyurethane chemistries and steel alloy specifications. Changzhou and Suzhou manufacturing bases host 60-plus percent of national seat frame stamping capacity.
Guangdong Province
Guangdong province domestic EV brands fragment procurement across sub-assembly specialists rather than legacy tier-one integrators. GB standards for vehicle interior air quality mandate additive-level material disclosure for market access. Shenzhen and Guangzhou anchor parallel supplier development programs for BYD and XPeng model lines.
Sichuan-Chongqing
Sichuan-Chongqing vehicle assembly growth remains underpenetrated by tier-one seating suppliers relative to coastal density. Western China logistics expansion pulls demand for localized seat module delivery networks. Chongqing municipality hosts emerging contract manufacturing operations assembling complete vehicles from sourced modules.
Beijing-Tianjin-Hebei
Beijing-Tianjin-Hebei corridor OEMs prioritize carbon-neutral cabin materials for sustainability reporting compliance. MIIT-enforced head restraint geometry and flammability rules filter procurement toward certified tier-one suppliers. Tianjin port infrastructure supports import of specialized tannery partnerships for premium leather specifications.
China Automotive Seats Market Competitive Environment
Global majors compete with regional champions across qualification thresholds and procurement fragmentation patterns. The supplier base organizes around joint-venture structures controlling premium program access and independent domestic challengers penetrating EV direct procurement channels. Three archetypes dominate: legacy seating joint-ventures with transplant manufacturing networks, chemical specialists supplying bio-based foam formulations, and contract manufacturers integrating fragmented sub-assembly sourcing. Consolidation pressure operates through M&A targeting electronics integration capabilities and capacity expansion into western China logistics corridors.
Within the joint-venture tier, Yanfeng Adient Seating exemplifies the premium passenger car program archetype through its combined Chinese-American corporate structure. Lear Corporation anchors North American transplant production networks operating within China, representing the multinational scale-driven position. Faurecia occupies a sustainability-specialist niche targeting carbon-neutral cabin ambitions through its European S.A. corporate form.
| Leading Market Players |
|---|
| Lear Corporation |
| Yanfeng Adient Seating |
| Faurecia |
| Magna International |
| Toyota Boshoku |
| TS Tech |
| Brose |
| Adient |
| Hyundai Transys |
| Others |
Value Chain & Pricing Dynamics
Domestic EV OEMs in Guangdong province concentrate specification authority and fragment procurement across sub-assembly specialists, compressing tier-one integrator pricing power while elevating direct negotiation leverage on frame, foam, and trim components.
Pricing Analysis
Cold-rolled steel and MDI-based foam chemical pass-through clauses dominate contract structures, with assemblers bearing 60-90 day lag exposure to commodity swings. Price differentiation separates GB-certified premium programs from compliance-grade mass-market offerings, with carbon-accounting transparency commanding measurable premiums in NIO and Li Auto lineups. Pricing pressure stems from dual carbon goal compliance costs and recycled content technical ceilings that prevent cost-down material substitution. Fleet operators in Jiangsu province exhibit highest price sensitivity, while premium EV brands prioritize specification over procurement cost.
Supply Chain Analysis
Polyurethane foam chemistry supply rests on German and Japanese specialty chemical producers with limited qualified alternative sources for bio-based polyol formulations. Steel frame stamping draws from domestic Chinese cold-rolled capacity concentrated in Changzhou and Suzhou, with trim textile sourcing split between domestic polyester weavers and controlled European tannery partnerships. Single-source vulnerability runs through MDI foam precursor supply chains exposed to regional logistics disruptions. Distribution runs through Yangtze River Delta assembly hubs with emerging Chongqing-Sichuan corridor expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT's evolving GB standards for vehicle interior air quality and flammability compound procurement complexity, with chemical disclosure mandates driving supplier consolidation and compliance investment requirements.
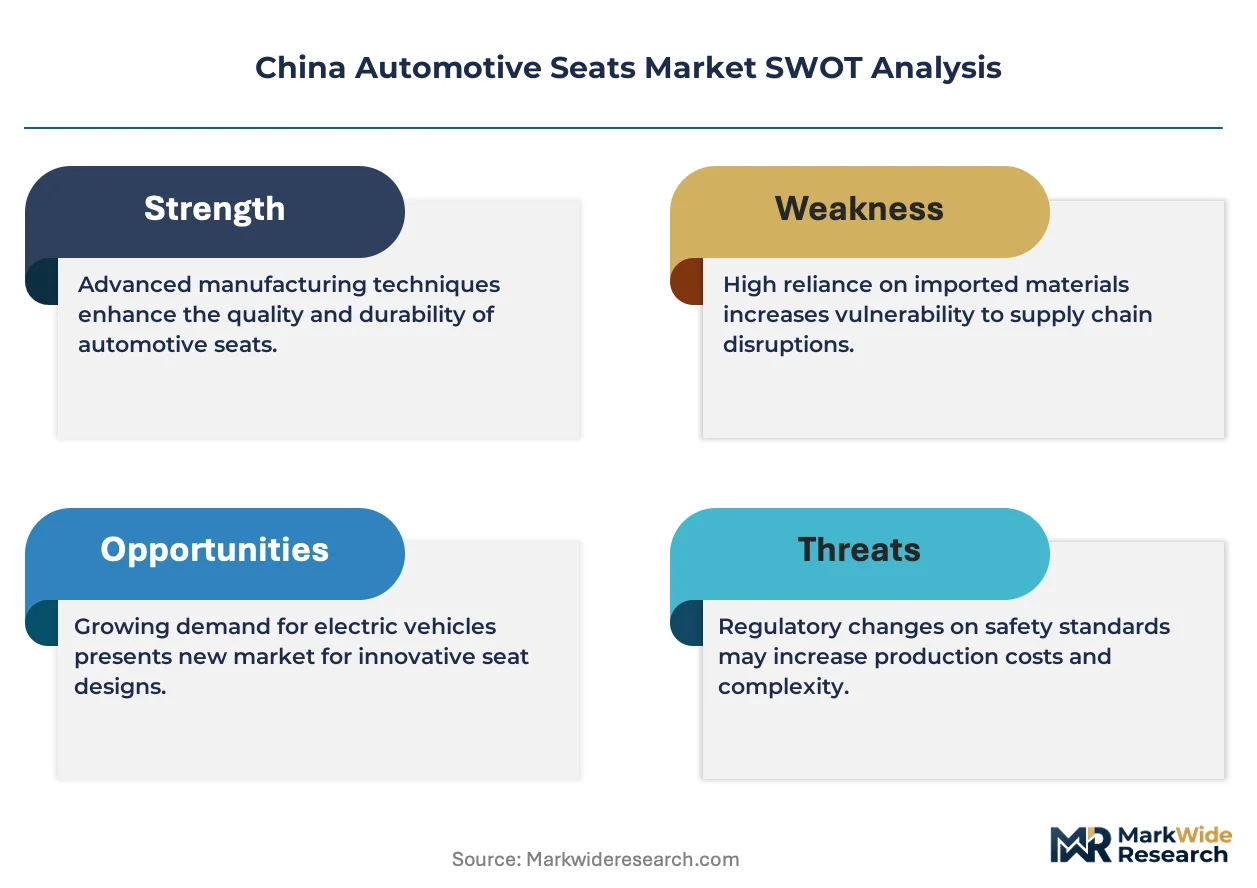
For Market Incumbents: Acquire electronics integration capabilities to capture smart seat module white space as pressure sensors and occupancy detection converge with traditional seating mechanics. Backward integration into bio-based polyol formulation secures carbon-accounting positioning against dual carbon goal enforcement. Threat substitution from domestic EV direct procurement bypassing legacy JVs demands channel control reinforcement through sub-assembly partnership structures. For New Entrants and Emerging Players: The premium-to-economy price-point gap in powered lumbar and thermal comfort features offers penetrable entry terrain for mid-tier specification challengers. Western China logistics corridors in Sichuan-Chongqing remain underpenetrated by tier-one seating suppliers relative to coastal density. Go-to-market through contract manufacturer integration partnerships bypasses joint-venture supply lock-in controlling premium passenger car program access. For Investors and Strategic Acquirers: Chemical specialists with validated lifecycle data and recycled feedstock chains are the most active acquirer targets in this space as SAMR carbon labeling protocols approach implementation. Long-term viability centers on suppliers positioned for GB standard tightening and smart seat convergence over the next decade. Watch bio-based polyol specification share in NIO and Li Auto lineups as inflection indicator for sustainable material transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Seat Electronics Integration | Pressure sensor and thermal management convergence creates module differentiation beyond passive support. |
| Bio-Based Polyol Capacity Expansion | NIO and Li Auto sustainability mandates pull specification share from petroleum-derived MDI formulations. |
| Western China Logistics Footprint | Chongqing and Sichuan vehicle assembly growth outpaces tier-one supplier penetration density. |
| GB Certification Pre-Positioning | MIIT flammability and head restraint geometry rules filter procurement toward certified tier-ones. |
| Sub-Assembly Partnership Structures | BYD and XPeng direct procurement patterns reward modular suppliers with bypass integration capabilities. |
Study Parameters
Bottom-up EV platform modeling reconciled against top-down steel and polyurethane supply tracking forms the analytical core. Primary interviews with OEM platform engineers, tier-one supplier procurement leads, foam chemical R&D directors, and aftermarket distributors combined with secondary validation against MIIT GB standard filings, vehicle production databases, and customs trade records. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrices map seat content per vehicle across propulsion architecture, vehicle class, and OEM tier dimensions over the projection horizon. CAGRs derive from segment-level volume trajectories weighted by regional production cluster concentration and feature penetration curves. Forecast inputs include EV platform refresh cadences, GB certification timeline compression effects, and dual carbon goal enforcement schedules.
Caveats apply where recycled content technical ceiling breakthroughs or smart seat standardization protocols could materially shift the outlook. Forecasts reflect assumptions around MIIT enforcement consistency and Yangtze River Delta manufacturing cluster stability. A small set of triggers—bio-based polyol cost parity achievement, western China logistics infrastructure completion, and SAMR carbon labeling implementation timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Europe Automotive Seat Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market