
 Automotive Window and Exterior Sealing Systems Market | 2026-2036
Automotive Window and Exterior Sealing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Window and Exterior Sealing Systems Market Analysis
Aftermarket service revenue is fragmenting as OEMs extend warranty-backed sealing performance guarantees and captive parts programs. Cooper Standard Automotive leverages its vertical integration into rubber compounding to sustain margin control across weatherstrip and adhesive seal lines. Sumitomo Riko anchors its position through R&D intensity in acoustic-dampening TPE formulations for premium electric vehicle platforms. Magna International dominates module-integrated sealing assemblies by controlling design-to-manufacture workflows with major vehicle assemblers.
Automotive window and exterior sealing systems comprise elastomeric profiles, adhesive-bonded seals, and compression-molded gaskets engineered to maintain cabin pressurization, exclude moisture, and reduce wind noise at highway speeds. EPDM weatherstrips remain the volume leader due to ozone resistance and cost-efficient extrusion processing, though TPE materials are capturing fastest growth as recyclability mandates intensify across OEM supply chains. The end-user structure concentrates margin pools with Tier-1 suppliers who co-develop sealing architectures during vehicle platform definition, while aftermarket providers compete on price for replacement weatherstrips in aging vehicle parcs.
The EPA regulates volatile organic compound emissions from adhesive seal manufacturing processes under National Emission Standards for Hazardous Air Pollutants, while NHTSA crashworthiness standards implicitly govern seal retention during structural deformation. REACH chemical restrictions in Europe are forcing reformulation of plasticizer-dependent PVC seals toward bio-based alternatives. Stakeholders must monitor evolving collision-repair protocols as adhesive bonding technologies displace mechanical fasteners in sealing system attachment, reshaping aftermarket installation training and tooling requirements.
Market Dynamics
Electric vehicle platform engineering is compressing development cycles for sealing architectures, forcing simultaneous optimization of aerodynamic drag coefficients and acoustic cabin isolation during vehicle definition phases rather than sequential refinement.
Growth Catalysts
- REACH chemical restrictions:European OEMs are accelerating material transitions from plasticizer-dependent PVC toward recyclable TPE formulations to maintain market access.
- Adhesive bonding displacement:Crashworthiness standards from NHTSA implicitly govern seal retention during structural deformation, validating advanced attachment chemistries over mechanical fasteners.
- Germany's manufacturing corridor:Co-location of Tier-1 sealing development with vehicle platform engineering concentrates knowledge spillovers and reduces iteration latency.
Market Restraints
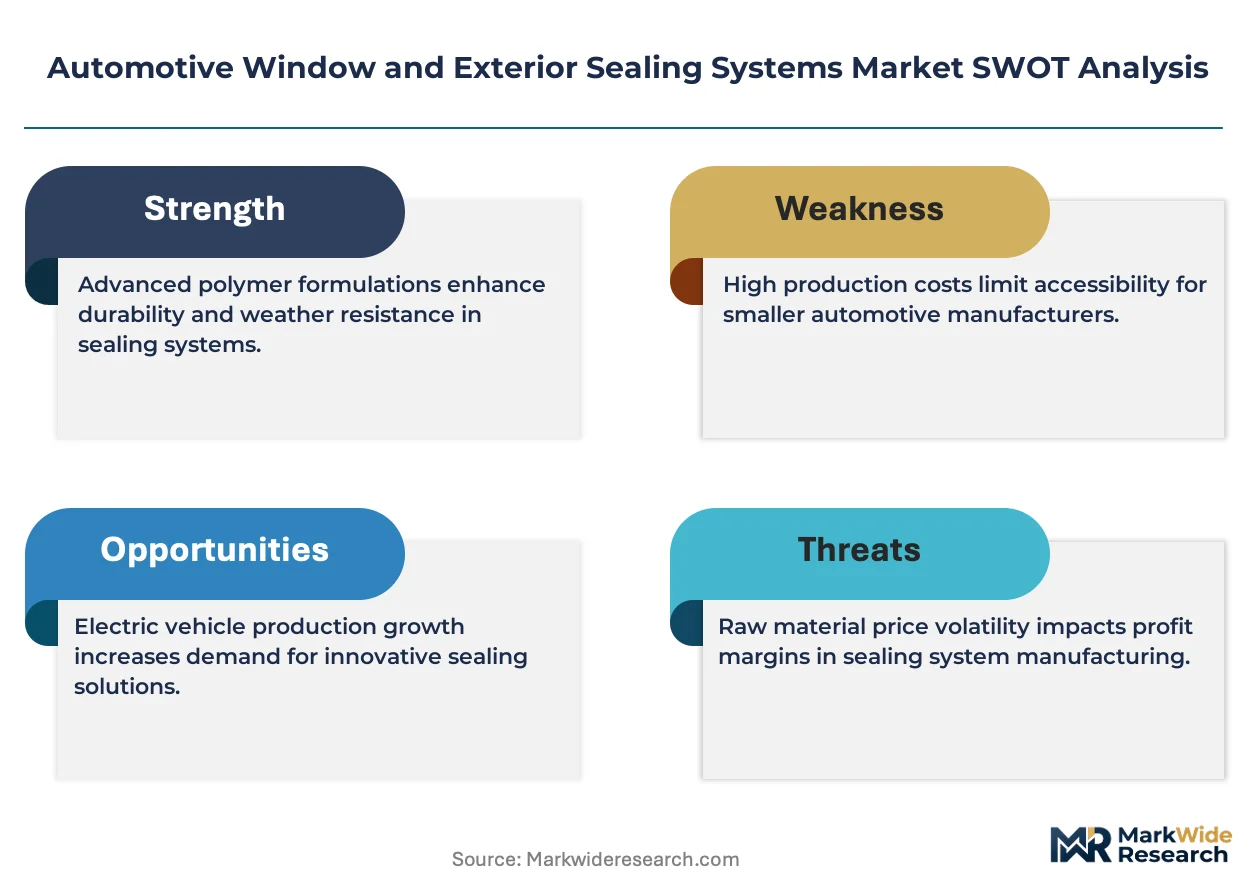
- EPDM feedstock volatility:Ethylene and propylene monomer pricing tied to naphtha cracking economics creates margin compression for weatherstrip producers without captive petrochemical supply.
- Tooling capex concentration:Compression-molded gasket production requires dedicated high-tonnage presses, locking capital in single-purpose equipment with limited alternative utilization.
- Collision-repair protocol lag:Adhesive bonding certification requirements from OEMs create aftermarket installation barriers, fragmenting service revenue toward dealer networks.
Strategic Opportunities
- India's PLI scheme:Automotive component localization incentives attract sealing system investment to serve emerging domestic EV production clusters.
- Acoustic-dampening TPE convergence:Integration of vibration-dampening additives with recyclable base polymers opens premium EV platform specifications previously reserved for multi-material assemblies.
- Warranty-backed performance guarantees:OEM captive parts programs displace independent aftermarket channels, creating recurring revenue streams through vehicle lifecycle coverage.
Industry Challenges
- Adhesive bonding technician certification:Collision repair networks face retraining bottlenecks as surface preparation and curing protocols displace conventional mechanical fastening skill bases.
- Multi-material recycling complexity:Co-extruded profiles combining EPDM substrates with TPE sealing lips complicate end-of-life material separation, threatening circular economy compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Window and Exterior Sealing Systems Market |
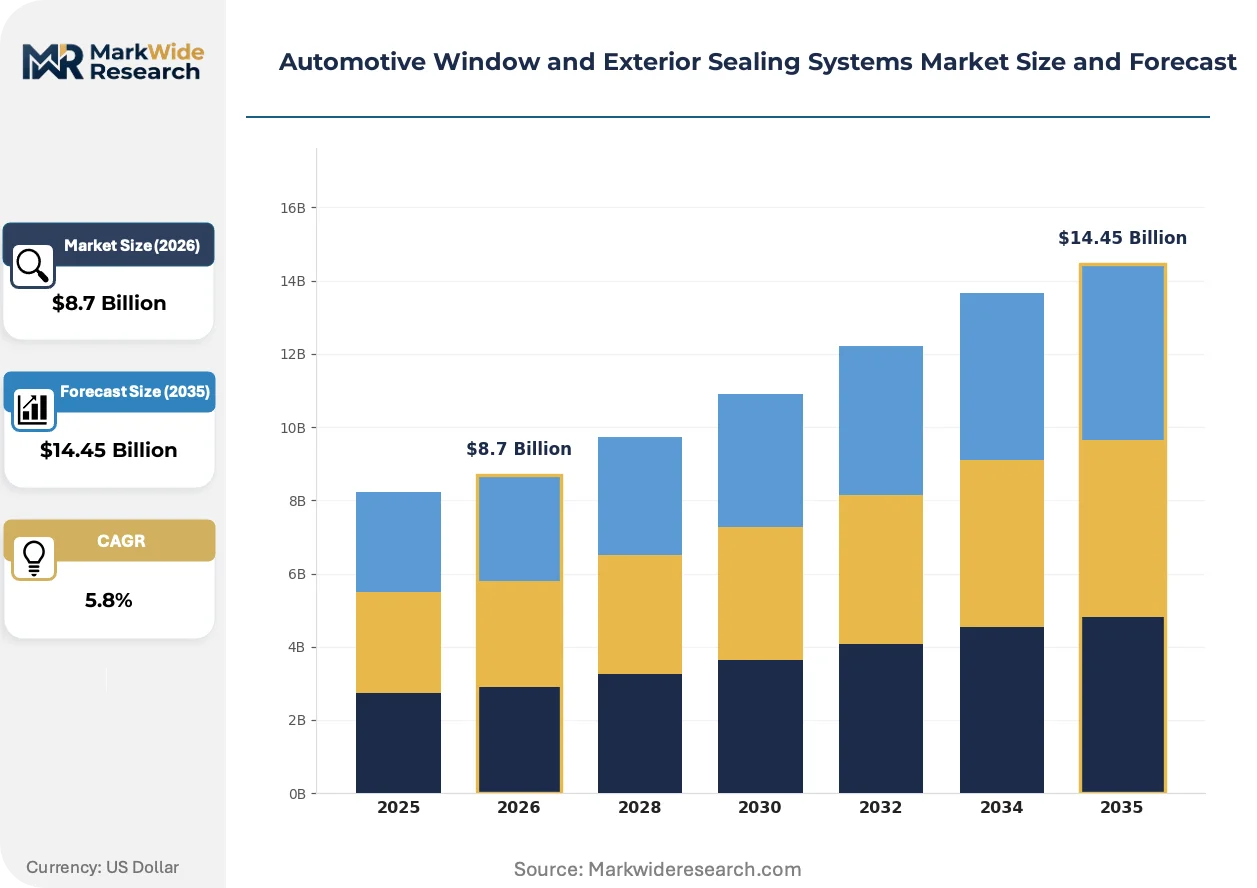
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weatherstrips, Adhesive Seals, Molding, Gaskets Material: EPDM, TPE, PVC, Silicone End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation Type: In-Line, Retrofitting, Assembly, Module Integration |
| Companies Covered | Magna International, Sumitomo Riko, Cooper Standard Automotive, Rehau, Freudenberg, Hutchinson, Trelleborg, ElringKlinger, Toyoda Gosei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Window and Exterior Sealing Systems Market Emerging Trajectories
Sealing system engineering is migrating from component supply toward module-integrated development, compressing supplier-OEM interface points and transferring design accountability upstream to Tier-1 specialists.
Thermoplastic elastomer formulations are collapsing the traditional separation between structural weatherstrips and acoustic management layers. Premium electric vehicle manufacturers specify single-profile solutions that simultaneously manage compression set, airflow sealing, and road noise attenuation. This convergence eliminates assembly steps and reduces part count per door aperture by consolidating functions previously distributed across EPDM and foam-backed assemblies.
Europe's F-Gas Regulation and REACH authorization procedures are accelerating bio-based plasticizer development for PVC seal alternatives. Compounders must demonstrate reduced toxicity profiles while maintaining low-temperature flexibility and UV stability. German OEMs are driving the tightest compliance timelines, requiring supply chain documentation of renewable content percentages and recyclate incorporation rates by vehicle platform launch.
Service contract bundling is restructuring aftermarket revenue capture. OEMs extend warranty-backed sealing performance guarantees that tether replacement parts to authorized installation networks. Independent repair shops face exclusion from software-enabled calibration procedures for sensor-integrated sealing modules, compressing their addressable market to aging vehicle parcs outside warranty coverage.
Automotive Window and Exterior Sealing Systems Market Segmentation
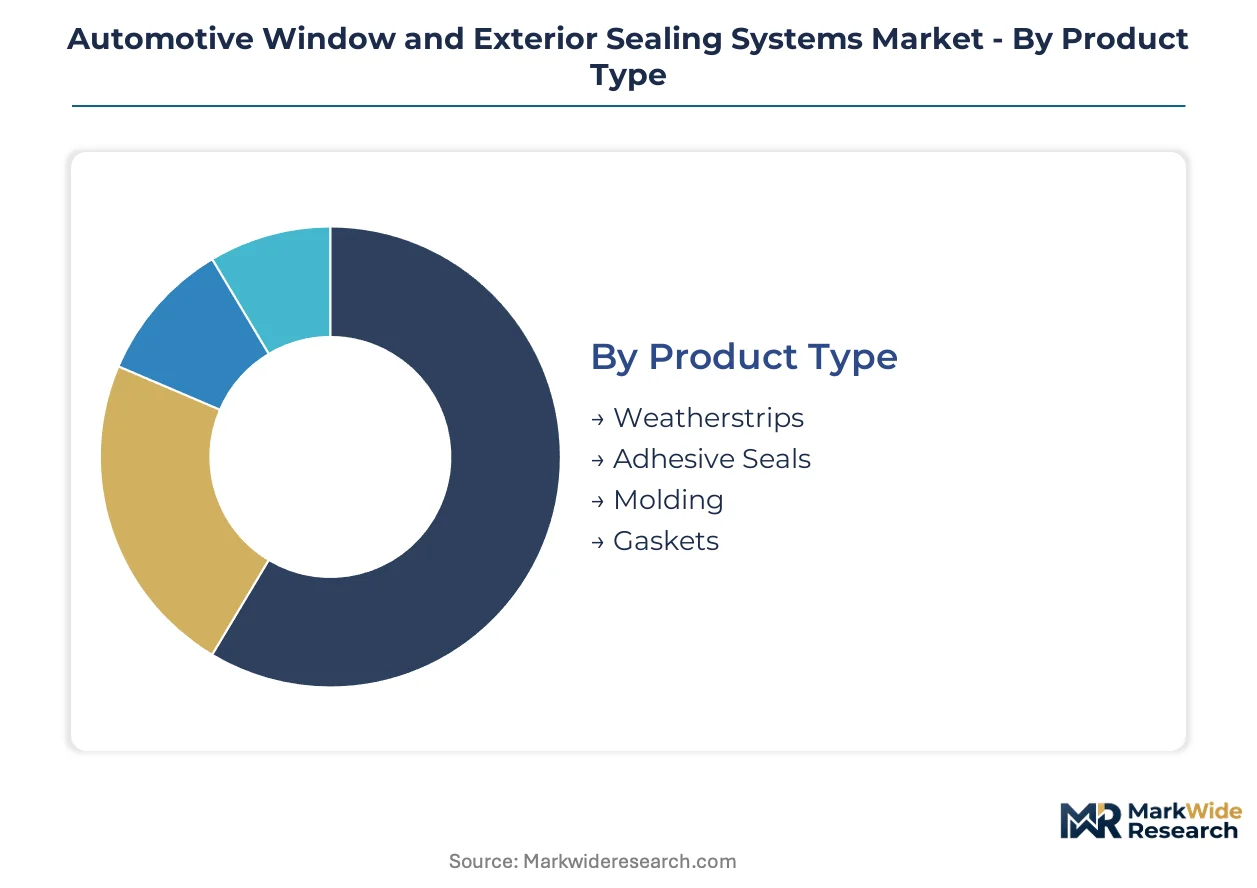
Segmentation in automotive sealing systems reveals how value migrates across material technologies and supply chain tiers. Each dimension exposes distinct margin pressures, from captive OEM programs to aftermarket price competition.
Product Type:
Aftermarket service intensity varies dramatically by product complexity, with adhesive-bonded solutions requiring specialized tooling and technician certification that fragments revenue capture.
- Weatherstrips:Extruded EPDM profiles dominate volume production due to ozone resistance and cost-efficient processing. Demand concentrates with Germany's vehicle assemblers seeking aerodynamic optimization for electric platforms.
- Adhesive Seals:Chemically cured bonding systems replace mechanical fasteners in crash-critical joints. Premium EV manufacturers specify these for structural integrity during deformation, validating advanced attachment chemistries under NHTSA protocols.
- Molding:Compression-molded decorative and functional trim requires dedicated high-tonnage presses.
- Gaskets:Static compression seals for fixed glass and body panel interfaces.
Weatherstrips hold the largest share; momentum sits with adhesive seals.
Material:
Cost tier stratification separates commodity formulations from premium recyclable grades that command specification premiums.
- EPDM:Ethylene-propylene-diene monomer remains the volume leader for weatherstrip extrusion. Feedstock volatility tied to naphtha cracking economics squeezes margins for producers without captive petrochemical supply.
- TPE:Thermoplastic elastomer formulations collapse the traditional separation between structural sealing and acoustic management. Europe's REACH restrictions accelerate substitution for plasticizer-dependent alternatives.
- PVC:Legacy formulations face regulatory pressure from bio-based plasticizer mandates.
- Silicone:High-temperature stability applications in powertrain-adjacent sealing.
EPDM retains volume dominance; TPE climbs the fastest on recyclability mandates.
End User:
Customer type determines interface complexity, with direct OEM relationships transferring design accountability upstream.
- OEMs:Vehicle manufacturers specify sealing architectures during platform definition, capturing warranty-backed performance guarantees that tether replacement parts to authorized networks.
- Tier-1 Suppliers:Co-development specialists manage module-integrated assemblies. Germany's manufacturing corridor concentrates knowledge spillovers between sealing development and vehicle engineering teams.
- Aftermarket Providers:Independent channels compete on price for aging vehicle parcs outside warranty coverage.
- Vehicle Assemblers:Contract manufacturers rely on supplier-designed sealing modules.
Tier-1 suppliers capture the specification premium; aftermarket providers face margin compression.
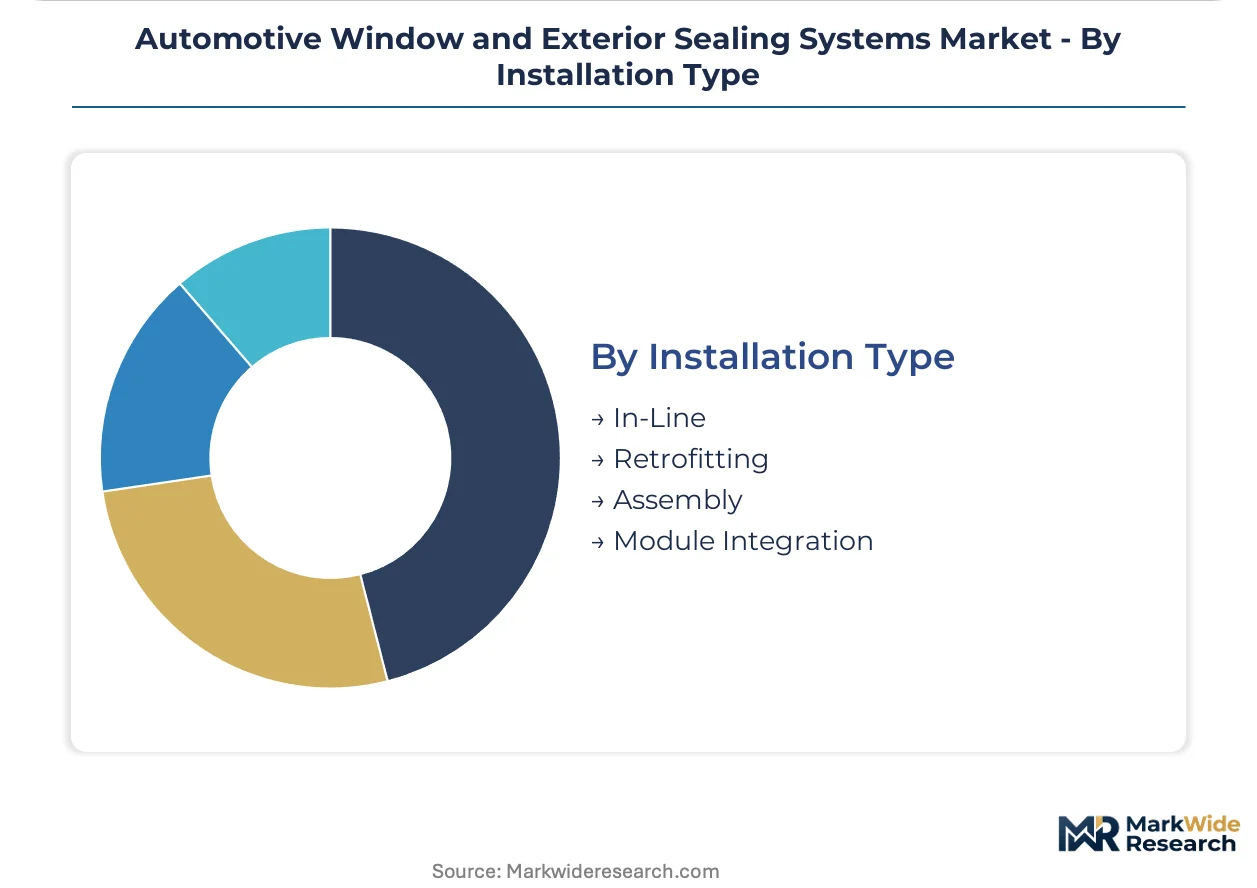
Installation Type:
Maturity gradients separate factory-integrated processes from retrofit applications with divergent skill and tooling requirements.
- In-Line:Continuous extrusion and automated placement during vehicle assembly. OEMs optimize throughput rates with robotic sealing application systems.
- Module Integration:Pre-assembled door and glass modules delivered sequenced to assembly lines. This format transfers complexity upstream to Tier-1 suppliers who control design-to-manufacture workflows.
- Retrofitting:Post-assembly replacement and repair applications.
- Assembly:Discrete component attachment operations.
In-line installation holds the largest share; module integration expands most quickly on platform consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German OEMs exhibit lowest price sensitivity for acoustic-optimized sealing specifications, while Indian domestic producers prioritize cost-efficient EPDM formulations. China's EV platform engineering commands premium module-integrated assemblies, compressing development cycle tolerance.
Germany
BMW and Mercedes-Benz specify integrated sealing modules during vehicle platform definition, transferring design accountability upstream. REACH chemical restrictions from ECHA accelerate PVC-to-TPE material transitions across supplier networks. The Stuttgart-Munich manufacturing corridor concentrates co-development activity between Tier-1 sealing specialists and vehicle engineering teams.
United States
Detroit-based OEMs optimize aerodynamic drag coefficients for electric truck platforms, demanding simultaneous acoustic and sealing performance. NHTSA crashworthiness standards validate adhesive bonding chemistries over mechanical fasteners in structural joints. The Michigan-Ohio supplier belt hosts module-integrated sealing assembly operations sequenced to final vehicle production.
China
Domestic EV manufacturers specify single-profile TPE solutions consolidating weatherstrip and acoustic functions. MIIT new energy vehicle mandates drive platform consolidation, compressing sealing architecture development cycles. The Yangtze River Delta clusters module suppliers with battery and electric drivetrain producers under unified platform engineering.
India
Maruti Suzuki and Tata Motors localize sealing system production under PLI scheme automotive component incentives. BIS quality certifications govern material specifications for domestic vehicle assembly. The Tamil Nadu-Gujarat manufacturing belt attracts Tier-1 sealing investment to serve emerging EV production clusters.
Japan
Toyota and Honda integrate sealing development with lightweight body-in-white engineering for hybrid platforms. METI carbon neutrality roadmaps pressure material suppliers toward recyclable formulation documentation. The Aichi Prefecture supplier network maintains co-located R&D facilities with vehicle assemblers for iteration velocity.
Automotive Window and Exterior Sealing Systems Market Vendor Landscape
Capability concentration sits with module-integrated specialists who control design-to-manufacture workflows; scale advantage sits with diversified automotive suppliers leveraging cross-product manufacturing infrastructure. The vendor base organizes into three strategic archetypes: rubber compounders with captive material science, module integrators managing OEM design interfaces, and diversified Tier-1s spanning multiple vehicle systems. Dominant competitive moves include backward integration into polymer compounding and strategic co-location with OEM platform engineering centers.
Within the diversified Tier-1 tier, Magna International and Cooper Standard Automotive exemplify module-integrated positioning through control of OEM design workflows. Sumitomo Riko anchors the rubber compounder archetype with Japanese material science heritage. These three entities collectively represent the competitive structure: diversified integrators capturing specification premiums, compounders defending margin through upstream material control, and specialists occupying acoustic-dampening niches for premium electric vehicle platforms.
| Leading Market Players |
|---|
| Magna International |
| Sumitomo Riko |
| Cooper Standard Automotive |
| Rehau |
| Freudenberg |
| Hutchinson |
| Trelleborg |
| ElringKlinger |
| Toyoda Gosei |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European TPE compounding facilities is compressing supplier pricing power while accelerating contract renegotiations for automotive sealing manufacturers. This utilization squeeze forces Tier-1 suppliers toward backward integration into polymer production or premium-tier specification capture to defend margin structures against feedstock volatility.
Pricing Analysis
Aftermarket service revenue tiers now drive lifetime value capture as OEMs extend warranty-backed performance guarantees that tether replacement parts to authorized installation networks. Three-tier pricing structure across premium, standard, and economy levels separates acoustic-optimized TPE formulations from commodity EPDM weatherstrips and generic PVC alternatives. Pricing pressure stems from EPDM feedstock volatility tied to naphtha cracking economics, squeezing producers without captive petrochemical supply. Independent aftermarket providers exhibit highest price sensitivity, while German OEMs demonstrate lowest elasticity for acoustic-optimized sealing specifications.
Supply Chain Analysis
Extended payment terms from German vehicle assemblers are reshaping supplier financing structures across Tier-1 sealing networks. Raw material sourcing draws from Saudi ethylene crackers, South Korean propylene derivatives, and Belgian specialty chemical additives for TPE formulations. Single-source vulnerability concentrates in high-tonnage compression molding presses with limited alternative utilization. Distribution runs through sequenced module delivery direct to vehicle assembly lines, bypassing traditional warehousing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where module-integrated sealing architectures are collapsing traditional component supply interfaces. The interoperability shift toward single-profile TPE solutions consolidating weatherstrip and acoustic functions is transferring design accountability upstream to Tier-1 specialists.
For Market Incumbents: Insulate specification premiums by deepening backward integration into rubber compounding and securing co-location agreements with OEM platform engineering centers in Germany's manufacturing corridor. Defend against margin compression from EPDM feedstock volatility through captive petrochemical supply or long-term offtake contracts with Middle Eastern ethylene producers.
For New Entrants and Emerging Players: Build out acoustic-dampening TPE capabilities targeting premium electric vehicle platforms where incumbent capacity constraints create specification openings. India's PLI scheme automotive component incentives offer the most penetrable geography for sealing system localization serving emerging domestic EV production clusters. Pursue joint development agreements with domestic vehicle assemblers seeking module-integrated door and glass assemblies.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across module-integrated sealing assembly operations as high-tonnage press requirements lock capital in single-purpose equipment. Long-term viability favors compounders with demonstrated REACH compliance documentation and recyclable formulation portfolios. Watch for MIIT new energy vehicle mandate acceleration in China as the signal indicating platform consolidation velocity and development cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive EPDM and TPE production defends margin structures against naphtha cracking volatility. |
| Co-location with OEM Platform Engineering | Germany's Stuttgart-Munich corridor compresses iteration latency for module-integrated sealing development. |
| REACH-Compliant TPE Formulation Investment | Bio-based plasticizer development maintains European market access under ECHA authorization timelines. |
| Module-Integrated Assembly Capacity Expansion | Pre-assembled door and glass modules transfer design accountability upstream from vehicle assemblers. |
| Acoustic-Dampening Additive R&D Partnership | Vibration-dampening TPE convergence opens premium EV specifications previously reserved for multi-material assemblies. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering teams, Tier-1 sealing supplier procurement, aftermarket distribution networks, and polymer compounding technical directors. Secondary validation drew from vehicle production databases, IHS Markit registration data, ECHA REACH authorization filings, and SEC 10-K disclosures from diversified automotive suppliers. Bottom-up segment sizing triangulated against top-down market aggregation across material technologies and installation formats.
Calibration against historical volume trajectories and elasticity assumptions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle propulsion architecture, content per vehicle by sealing system complexity, OEM tier stratification, and regional production cluster concentration. CAGRs derived from installed base evolution and replacement cycle dynamics, with specific inputs for electric vehicle platform penetration and adhesive bonding displacement rates in structural joints.
Sensitivities concentrate around EPDM feedstock pricing volatility, REACH authorization timeline acceleration, and collision-repair technician certification bottlenecks. Forecasts reflect documented assumptions on material substitution velocity and module integration adoption curves. Macroeconomic contraction, regulatory delay, or adhesive bonding protocol standardization deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
Automotive Body-In-White Market