
 Automotive Fascia Market | 2026-2036
Automotive Fascia Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fascia Market Analysis
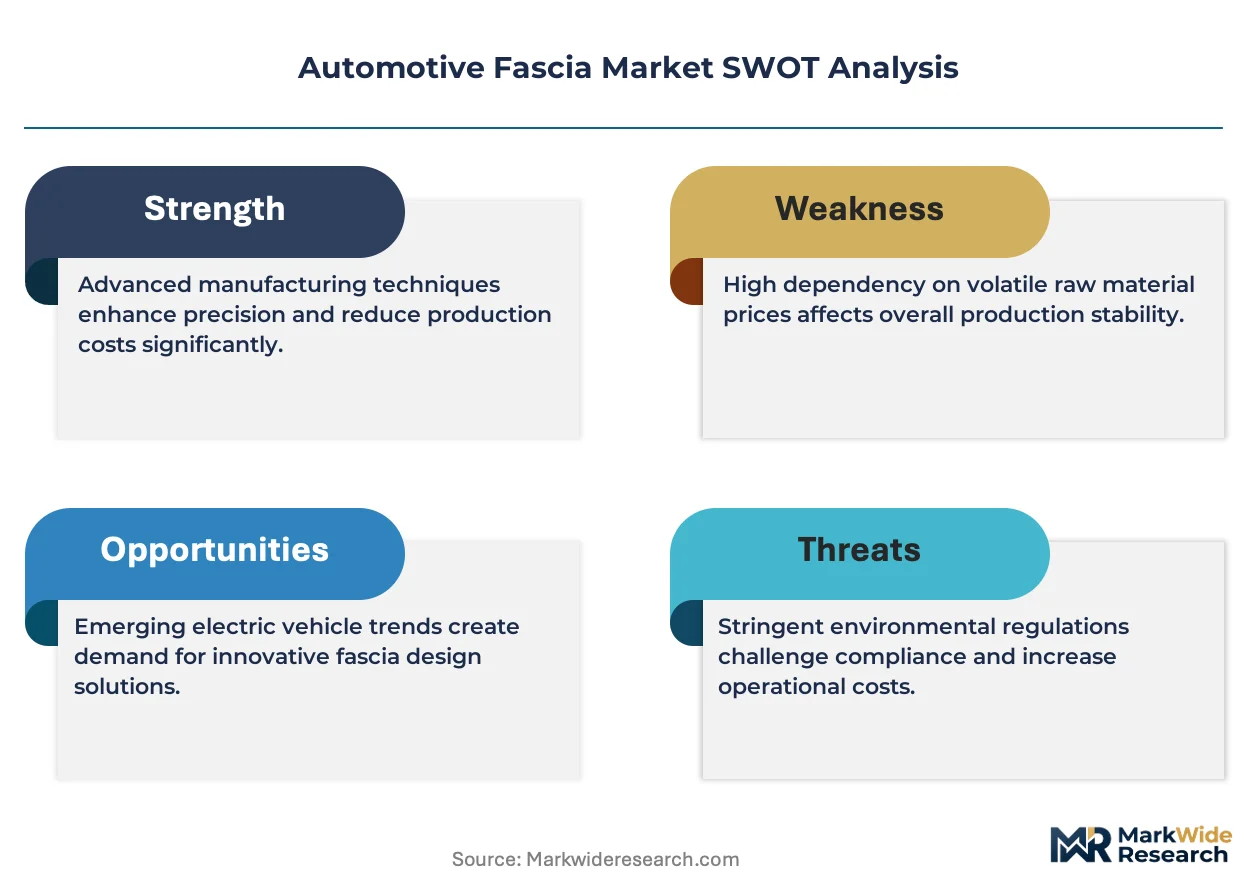
REACH compliance is consolidating the supplier base for European automakers. Magna International leverages its injection molding scale to serve premium OEM programs across multiple continents. Flex-N-Gate Corporation anchors its competitiveness through backward integration into thermoplastic resin compounding. Plastic Omnium differentiates via active grille shutter technology that reduces drag coefficients for electric vehicle platforms.
An automotive fascia is the exterior panel assembly mounted at the front or rear of a vehicle, typically comprising polypropylene or thermoplastic olefin substrates with Class A painted or textured surfaces, designed to house lighting modules, sensors, and cooling apertures while managing aerodynamic performance and pedestrian impact criteria. Front fascia assemblies command the largest value share due to sensor integration complexity and crashworthiness requirements. Composite materials represent the fastest-expanding material category as OEMs pursue mass reduction targets without sacrificing stiffness. Injection molding dominates manufacturing output for high-volume programs, though 3D printing is gaining traction for low-volume aftermarket body kit production.
The EPA enforces Corporate Average Fuel Economy standards that directly influence fascia aerodynamic design in the United States. EMA and ECHA jointly shape European material compliance through REACH substance restrictions and end-of-life vehicle directives. China's MIIT mandates GB standards for pedestrian protection that alter fascia geometric requirements for vehicles sold domestically. Stakeholders must monitor how divergent regional safety and environmental standards fragment tooling investments across manufacturing footprints.
Market Dynamics
Electric vehicle platform proliferation is compressing fascia development cycles as OEMs simultaneously integrate LiDAR housings, active grille shutters, and pedestrian impact absorption zones into single-module architectures.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:These mandates force aerodynamic optimization of front-end geometries, accelerating demand for active grille shutter systems that reduce drag coefficients at highway speeds.
- Sensor fusion requirements:Autonomous driving development is electrifying fascia specification intensity as tier-1 suppliers engineer Class A surfaces that maintain optical transparency for embedded radar and camera modules.
- Germany's premium OEM cluster:Concentrated engineering demand from Stuttgart and Munich headquarters drives specification leadership for lightweight composite fascia systems across global vehicle programs.
Market Restraints
- Polypropylene resin volatility:Feedstock cost fluctuations tied to propylene monomer markets compress margin predictability for high-volume injection molding programs serving mass-market platforms.
- Tooling concentration in Lower Saxony:Dependence on a narrow corridor of German mold-making specialists creates bottleneck risk for new program launches requiring complex multi-cavity dies.
- ECHA REACH substance restrictions:Phased prohibitions on specific plasticizers and flame retardants force reformulation cycles that extend material qualification timelines by 18-24 months.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced manufacturing create first-mover advantage for suppliers establishing localized thermoplastic composite compounding capacity.
- Thermoplastic-thermoset hybrid processing:Convergence of injection molding speed with continuous fiber reinforcement enables structural fascia integration previously requiring metal substructures.
- Aftermarket digital distribution:Direct-to-consumer 3D-printed body kit channels bypass traditional tier-2 distributors, capturing margin from enthusiast segments seeking geometric customization.
Industry Challenges
- Multi-physics simulation talent scarcity:Concurrent engineering of pedestrian impact, aerodynamic, and thermal performance requires specialized CAE expertise concentrated among a handful of engineering consultancies.
- Homologation timeline compression:Parallel validation against divergent GB standards in China, FMVSS in the United States, and UNECE regulations in Europe fragments testing resources across regional certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fascia Market |
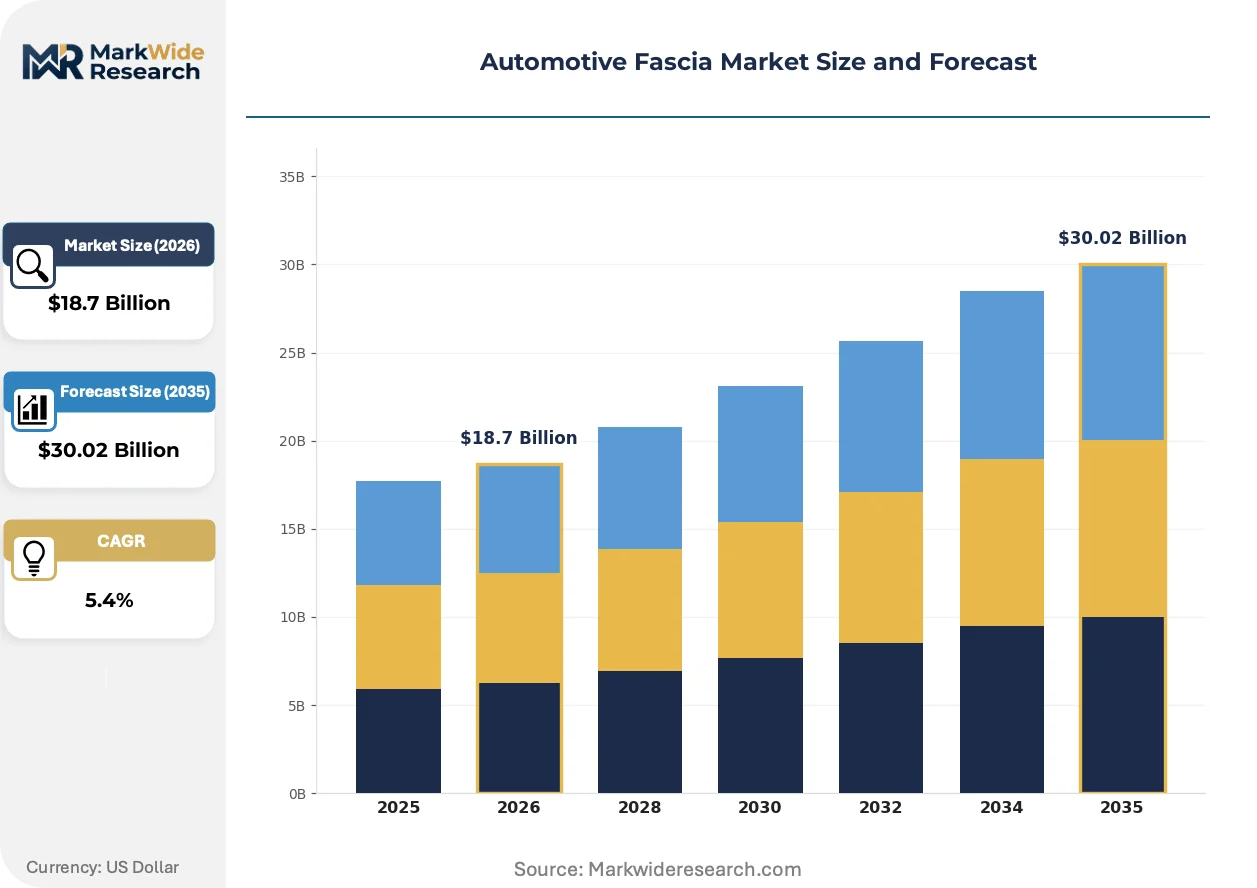
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Fascia, Rear Fascia, Body Kit, Trim Pieces Material: Plastic, Metal, Composite, Carbon Fiber Vehicle Type: Passenger Cars, Trucks, SUVs, Motorcycles Manufacturing Process: Injection Molding, Extrusion, CNC Machining, 3D Printing |
| Companies Covered | Magna International, Flex-N-Gate Corporation, Plastic Omnium, Faurecia SE, Samvardhana Motherson, Gestamp Automoción, Hyundai Mobis, Toyoda Gosei, Chiyoda Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fascia Market Emerging Trajectories
Material-process-design convergence is collapsing traditional boundaries between styling studios, simulation teams, and manufacturing engineering as fascia complexity exceeds sequential development timelines.
Long-fiber thermoplastic injection molding is electrifying structural performance in front-end carriers, enabling direct metal replacement for bumper beam integration. Premium EV platforms from German and Korean OEMs are adopting these compounds for 40% mass reduction versus steel assemblies. This technology is electrifying supplier tier restructuring as compounders acquire downstream molding capability to capture integrated system value.
REACH substance restrictions are forcing systematic substitution of legacy flame retardants and UV stabilizers across European supply chains. ECHA's SVHC candidate list expansion triggers mandatory supply chain disclosures that extend material qualification protocols. Tier-1 suppliers serving Stuttgart-based OEMs are responding by establishing dedicated regulatory intelligence functions to anticipate restriction trajectories.
Platform-sharing strategies among volume OEMs are consolidating fascia specification authority at headquarters engineering centers, displacing regional customization historically negotiated with local manufacturing affiliates. This concentration compresses supplier sales cycles while elevating technical gatekeeping power of platform chief engineers. The shift is most visible in Japanese and Korean OEMs centralizing exterior system decisions at domestic technical centers.
Automotive Fascia Market Segmentation
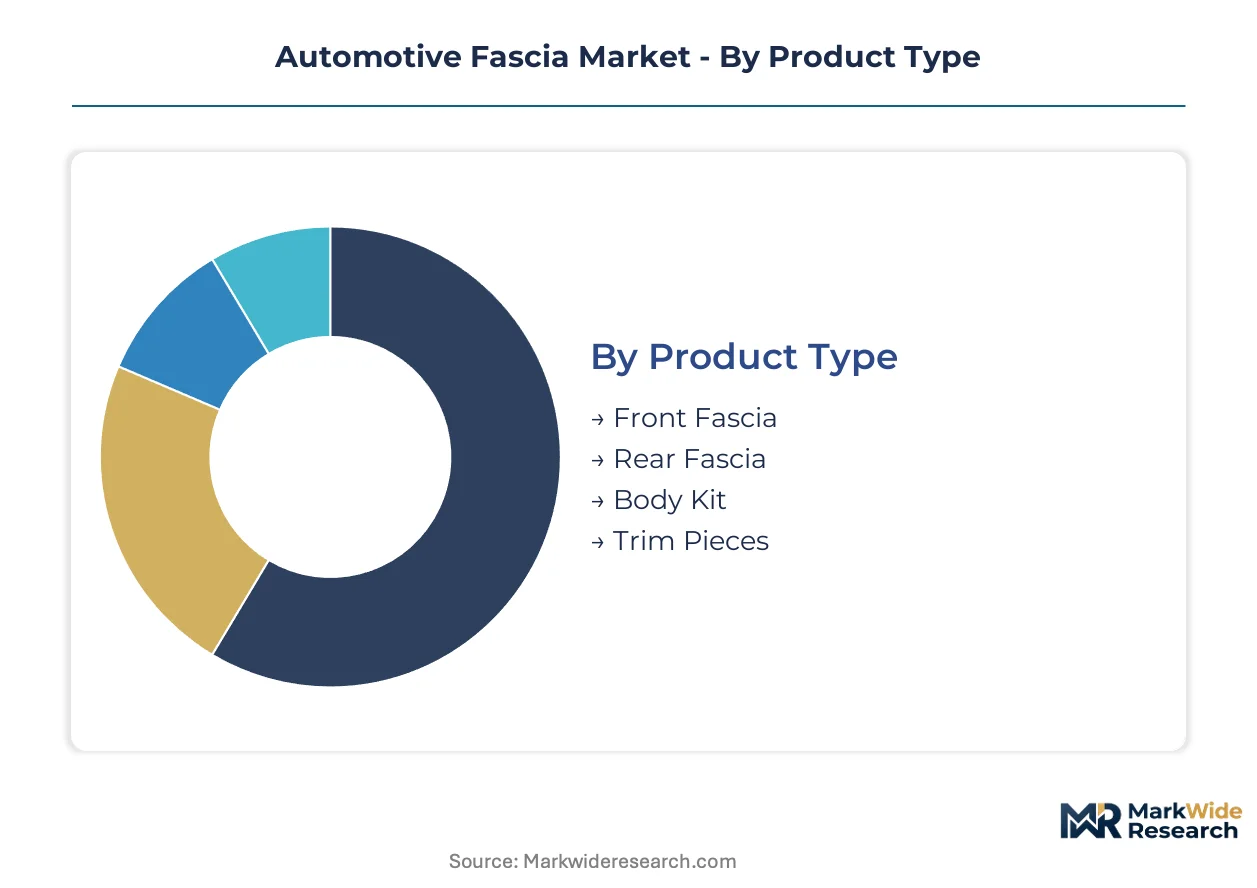
Segmentation in automotive fascia markets determines tooling investments, material qualification pathways, and regulatory compliance burdens. Distinct product architectures, material specifications, and manufacturing processes each carry unique homologation requirements across EPA, ECHA REACH, and MIIT GB standards.
Product Type:
Certification intensity varies sharply across fascia positions, with front-end assemblies facing the most stringent pedestrian protection and sensor integration mandates from NHTSA FMVSS and UNECE regulations.
- Front Fascia:These assemblies integrate radar-transparent Class A surfaces, active grille shutters, and energy-absorbing crush zones. Demand concentrates among German premium OEMs engineering electric vehicle platforms with embedded LiDAR housings, driven by aerodynamic optimization mandates under EPA Corporate Average Fuel Economy standards.
- Rear Fascia:Rear panels prioritize styling differentiation and parking sensor integration over aerodynamic performance. Specification authority is consolidating at Korean and Japanese OEM headquarters as platform-sharing strategies reduce regional customization.
- Body Kit:Aftermarket aerodynamic add-ons serve enthusiast segments seeking geometric customization. 3D-printed direct-to-consumer channels are bypassing traditional tier-2 distributors.
- Trim Pieces:Decorative fascia accents require shorter tooling lead times and lower capital investment than structural assemblies.
Leading the category by volume: Front Fascia. Growing fastest: Body Kit.
Material:
Material selection dictates REACH SVHC disclosure obligations, end-of-life vehicle directive compliance, and carbon accounting under EU Green Deal frameworks.
- Plastic:Polypropylene and thermoplastic olefin substrates dominate high-volume production through injection molding economies. ECHA restrictions on legacy plasticizers are forcing 18-24 month reformulation cycles for European supply chains.
- Composite:Long-fiber thermoplastic compounds enable 40% mass reduction versus steel in structural front-end carriers. Korean and German premium EV platforms are adopting these materials for bumper beam integration.
- Metal:Aluminum and steel substructures persist in heavy-duty truck applications where impact resistance requirements exceed polymer capabilities.
- Carbon Fiber:Ultra-lightweight prepreg materials serve low-volume motorsport and hypercar programs where cost tolerance accommodates aerospace-grade processing.
Volume leadership: Plastic. Steepest expansion trajectory: Composite.
Vehicle Type:
Platform architecture determines fascia system complexity, with electric vehicle skateboard designs compressing development cycles for integrated front-end modules.
- Passenger Cars:Sedan and hatchback platforms prioritize aerodynamic efficiency and pedestrian safety ratings. German engineering centers in Stuttgart and Munich drive specification intensity for lightweight composite systems.
- SUVs:Higher ride heights and larger frontal areas increase material requirements while accommodating more extensive sensor arrays for advanced driver assistance systems.
- Trucks:Commercial and heavy-duty applications demand enhanced impact resistance and repairability, favoring metal-reinforced designs over pure polymer solutions.
- Motorcycles:Two-wheeler fascias emphasize styling differentiation and weather protection with minimal structural load requirements.
Dominant by unit volume: Passenger Cars. Fastest specification evolution: SUVs.
Manufacturing Process:
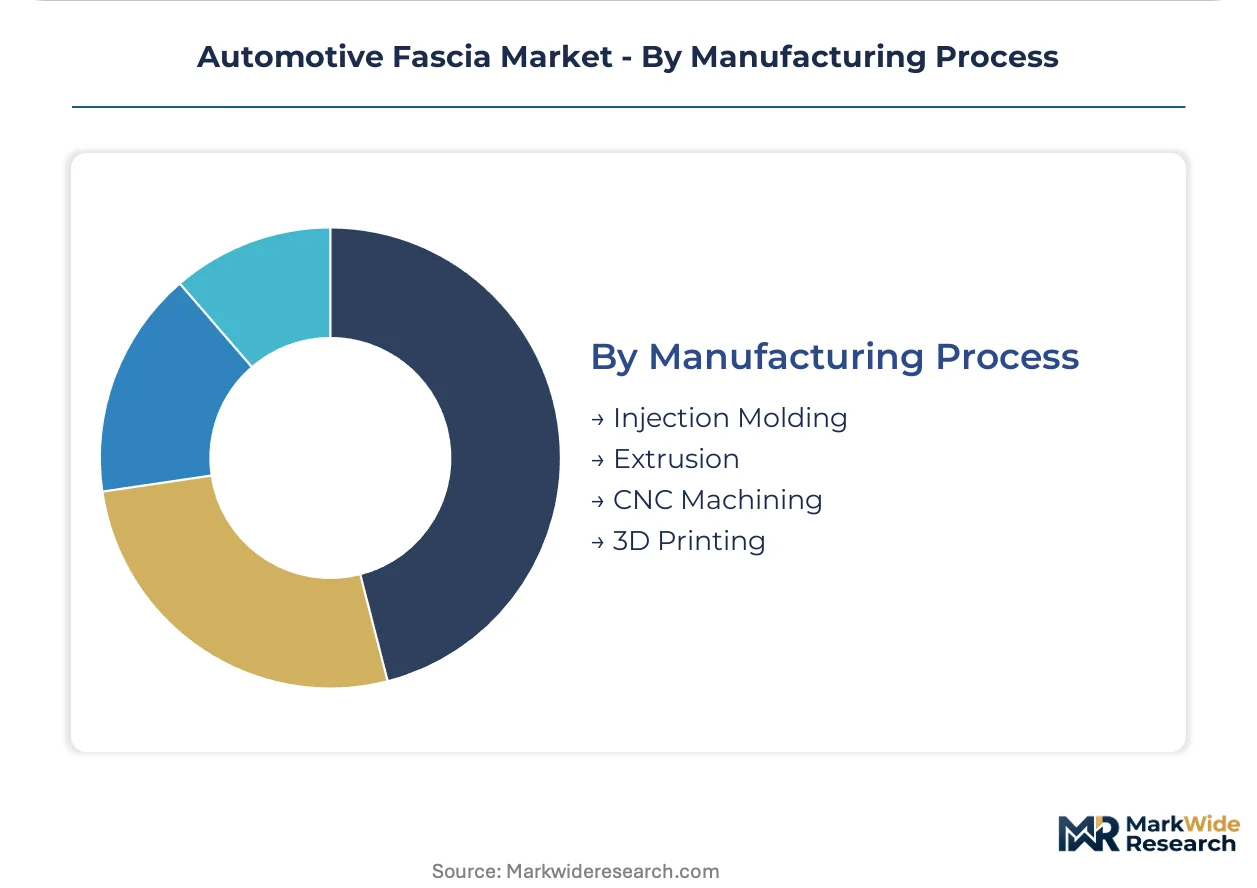
Process selection determines capital intensity, cycle time, and geometric flexibility, with regulatory traceability requirements varying across production methods.
- Injection Molding:Multi-cavity tooling serving mass-market platforms achieves lowest per-unit costs at volumes exceeding 100,000 units annually. Tooling concentration in Lower Saxony creates bottleneck risk for new program launches.
- 3D Printing:Additive manufacturing enables low-volume aftermarket body kit production with geometric complexity impossible through conventional tooling. Digital distribution channels capture margin from customization-seeking segments.
- Extrusion:Continuous profile production serves linear trim components with consistent cross-sections across vehicle programs.
- CNC Machining:Subtractive processing remains viable for carbon fiber and metal prototypes, bridge tooling, and motorsport applications where volumes preclude hard tooling investment.
Highest output volume: Injection Molding. Fastest capability expansion: 3D Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German premium OEM engineering centers in Stuttgart and Munich concentrate specification authority for lightweight composite fascia systems, while Chinese electric vehicle platforms and US aerodynamic mandates fragment tooling investments across three distinct regulatory tracks.
United States
EPA Corporate Average Fuel Economy standards force aerodynamic optimization of front-end geometries, accelerating demand for active grille shutter systems. NHTSA FMVSS pedestrian protection criteria alter crush zone engineering for vehicles sold domestically. Detroit-area engineering centers coordinate specification authority for North American truck and SUV programs.
Germany
Stuttgart and Munich headquarters of premium automakers drive specification intensity for composite front-end carriers. ECHA REACH substance restrictions force 18-24 month reformulation cycles for plasticizers and flame retardants. Lower Saxony's mold-making corridor creates bottleneck risk for multi-cavity die procurement.
China
MIIT-mandated GB standards for pedestrian protection reshape fascia geometric requirements for domestic-market vehicles. Electric vehicle skateboard platforms compress development cycles for integrated front-end modules. Yangtze River Delta manufacturing clusters concentrate injection molding capacity for mass-market EV programs.
Japan
METI industrial policy supports lightweight material adoption for export-oriented vehicle platforms. JIS standards govern surface quality specifications for Class A painted fascia substrates. Nagoya-area engineering centers consolidate exterior system decisions as platform-sharing strategies reduce regional customization.
South Korea
Seoul-based OEM headquarters centralize fascia specification authority for global vehicle programs. MFDS-equivalent automotive safety regulations align with UNECE frameworks for export compliance. Busan-Ulsan manufacturing corridors anchor thermoplastic composite compounding capacity for domestic EV production.
Automotive Fascia Market Vendor Landscape
North American producers anchor one tier; European specialists hold specification leadership for premium platforms; East Asian fabricators capture scale advantages for electric vehicle programs. The supplier base concentrates around injection molding scale, backward resin integration, and active aerodynamics technology. Three archetypes dominate: integrated systems suppliers, compounder-molders with captive material supply, and technology licensors for active grille shutters. Competitive moves center on acquiring downstream molding capability and establishing regional compounding capacity.
Within the integrated systems tier, Magna International and Flex-N-Gate Corporation exemplify divergent scale strategies. Magna leverages multi-continent injection molding footprints to serve premium OEM programs. Flex-N-Gate anchors competitiveness through backward integration into thermoplastic resin compounding. Plastic Omnium occupies a position defined by active grille shutter technology that reduces drag coefficients for electric vehicle platforms.
| Leading Market Players |
|---|
| Magna International |
| Flex-N-Gate Corporation |
| Plastic Omnium |
| Faurecia SE |
| Samvardhana Motherson |
| Gestamp Automoción |
| Hyundai Mobis |
| Toyoda Gosei |
| Chiyoda Manufacturing |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap mold-makers concentrated in Lower Saxony anchor supply discipline through multi-generational tooling expertise, translating into premium pricing power for complex multi-cavity dies serving premium OEM programs while resisting margin compression from volatile polypropylene feedstock markets.
Pricing Analysis
Short lead-time premiums command pricing separation from standard program cycles, with German premium OEMs paying elevated rates for accelerated multi-cavity die delivery to meet compressed EV platform timelines. Three-tier pricing structure across active aerodynamics-integrated, sensor-ready, and baseline fascia tiers reflects specification intensity divergence. Cost compression in mass-market injection molding programs is intensifying because propylene monomer volatility erodes contract margin predictability. Fleet procurement officers at volume OEMs exhibit highest price sensitivity, while Stuttgart-based platform chief engineers prioritize technical performance over unit economics.
Supply Chain Analysis
Regional distribution centers in Lower Saxony, Yangtze River Delta, and Detroit metropolitan area form hub-and-spoke patterns feeding assembly plants across three regulatory zones. Tooling fabrication draws from German precision engineering, Chinese mass-production capacity, and Mexican nearshoring for North American truck programs. Polypropylene resin compounding rests on propylene monomer supply from Gulf Coast petrochemical complexes and Middle Eastern feedstock exporters. Single-source vulnerability concentrates in Lower Saxony's mold-making corridor, where qualified die specialists face 18-month order backlogs. Distribution runs through Tier 1 supplier consolidation centers co-located with OEM assembly footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a backward-integration race, with compounders acquiring downstream molding capability to capture integrated system value previously fragmented across supplier tiers.
For Market Incumbents: Deploy captive thermoplastic resin compounding to secure margin capture from long-fiber structural compounds replacing steel bumper beams. Add molding capacity in India's PLI scheme zones to deflect tariff exposure on exports to domestic EV programs. ECHA REACH substance restriction trajectories threaten legacy formulation portfolios, forcing qualification investment in bio-based plasticizer alternatives. For New Entrants and Emerging Players: Aftermarket body kit distributors seeking geometric customization represent the most penetrable buyer archetype, bypassing entrenched Tier 2 channels through direct-to-consumer 3D printing platforms. India's production-linked incentive zones offer white-space entry for thermoplastic composite compounding absent established supplier footprints. Target digital-native enthusiast segments with parametric design tools enabling bespoke aerodynamic add-ons. For Investors and Strategic Acquirers: Distressed-cycle entries favor compounder-molders with captive resin supply in South Korea and Germany, where platform standardization concentrates specification authority at headquarters engineering centers. Five-to-ten year viability hinges on active grille shutter technology integration as EPA aerodynamic mandates intensify. Monitor ECHA SVHC candidate list expansion velocity as inflection indicator for material qualification cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin from long-fiber thermoplastic compounds replacing steel structural elements. |
| Active Grille Shutter Technology Licensing | Reduces drag coefficients for electric vehicle platforms under EPA fuel economy mandates. |
| Regional Molding Footprint Expansion | Localizes capacity in India's PLI zones to serve domestic EV production requirements. |
| REACH Compliance Intelligence Investment | Anticipates ECHA substance restrictions accelerating 18-24 month reformulation cycles. |
| Aftermarket Digital Distribution Buildout | Bypasses traditional Tier 2 channels through direct-to-consumer 3D-printed body kit platforms. |
Methodological Framework
Document review covered vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed suppliers, and ECHA REACH substance restriction notifications, complemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and thermoplastic compounder technical leads. Bottom-up triangulation across injection molding output volumes and top-down validation against OEM program sourcing disclosures anchored market sizing. Primary fieldwork with Stuttgart and Munich engineering centers clarified specification authority concentration for composite front-end carriers.
Segment-level projections across vehicle class, propulsion architecture, content per vehicle, and regional production cluster fed into analytical framework outputs spanning the projection horizon. CAGRs derived from regression analysis of historical OEM program launch cadence correlated with EV platform proliferation rates. Forecast inputs incorporated MIIT GB standard pedestrian protection geometric requirements and EPA Corporate Average Fuel Economy aerodynamic mandate trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction timing, polypropylene monomer price volatility, and German mold-making capacity bottlenecks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market