
 Weatherstrip Market | 2026-2036
Weatherstrip Market Size, Share, and Industry Trends Forecast 2026-2036
Weatherstrip Market Insights
Asian rubber compounders is broadening EPDM weatherstrip output to serve electric vehicle thermal management needs. Cooper Standard Automotive leverages captive polymer blending operations across North American plants to sustain OEM contract margins. Toyoda Gosei anchors Japanese supply networks through precision extrusion capabilities for luxury vehicle programs. Hutchinson competes in European acoustic sealing through integrated foam-in-place manufacturing lines.
A weatherstrip is an engineered elastomeric or thermoplastic sealing element, typically extruded in continuous profiles with specified compression set values below 25 percent and Shore A hardness ranging from 40 to 80, designed to block air, moisture, dust, and noise ingress at movable or fixed interfaces. Its primary industrial purpose spans automotive door and glass sealing, building envelope thermal barriers, and industrial equipment gasket applications. EPDM formulations dominate automotive glazing and body sealing due to ozone resistance and temperature stability from minus 40 to 150 degrees Celsius, while silicone grades command premium positioning in marine and high-heat industrial environments where UV degradation resistance determines replacement cycles. PVC and neoprene alternatives occupy cost-sensitive residential window retrofits and mid-tier commercial construction segments where installation labor rather than material longevity drives specification.
The US EPA and NHTSA coordinate fuel economy and greenhouse gas rules that elevate aerodynamic sealing standards, compelling OEMs to specify lower-closure-force weatherstrip designs that reduce door-seal drag coefficients. The EU Green Deal and REACH chemical restrictions are reshaping formulation requirements, pushing compounders toward bio-based plasticizers and reduced heavy-metal curing systems. Stakeholders must monitor evolving building energy codes in California and Germany, where passive house certification and net-zero mandates are extending weatherstrip performance warranties from ten to twenty-five years, forcing material suppliers to validate accelerated aging protocols or cede specification authority to certified system integrators.
Market Dynamics
Automotive OEMs are consolidating supplier bases around vertically integrated compounders capable of delivering validated thermal-acoustic sealing systems under single-source accountability, compressing the vendor pyramid from tier-three resin distributors to captive polymer operations.
Growth Catalysts
- EPA-NHTSA coordinated rules:US fuel economy and greenhouse gas standards mandate reduced door-seal drag coefficients, forcing specification of lower-closure-force EPDM profiles across passenger vehicle platforms.
- Electric vehicle thermal management:Battery enclosure sealing requirements are expanding addressable demand for multi-density foam-core weatherstrips with integrated EMI shielding layers.
- Germany passive house certification:Twenty-five-year performance warranties under net-zero building codes are elevating specification authority toward certified system integrators with validated accelerated aging protocols.
Market Restraints
- EPDM feedstock concentration:Ethylene and propylene supply tightness from Gulf Coast petrochemical complexes creates margin volatility for North American compounders without backward integration into monomer production.
- REACH chemical restrictions:EU phasedowns of conventional plasticizers and heavy-metal curing systems force reformulation investments that disadvantage smaller compounders lacking in-house regulatory affairs capabilities.
- Silicone substitution ceiling:Premium marine and industrial applications above 150 degrees Celsius remain addressable only by fluorosilicone grades, capping EPDM expansion in high-heat segments.
Strategic Opportunities
- India building energy codes:BIS thermal performance mandates for commercial envelope systems are creating first-mover advantages for compounders establishing local extrusion capacity ahead of domestic supply shortages.
- Coextrusion automation convergence:Integration of laser profile measurement with closed-loop density control is enabling micro-cellular foam geometries previously requiring manual die adjustment.
- EU Green Deal public procurement:Bio-based plasticizer validation under CSRD-aligned sourcing rules opens specification pathways for compounders with third-party carbon footprint certification.
Industry Challenges
- Accelerated aging protocol validation:OEMs are demanding 10,000-hour thermal-oxidative and UV exposure data for new formulations, extending qualification timelines to 18-24 months.
- Multi-material bonding expertise:Foam-in-place manufacturing requires polymer chemists capable of optimizing adhesive interfaces between EPDM substrates and polyurethane core densities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weatherstrip Market |
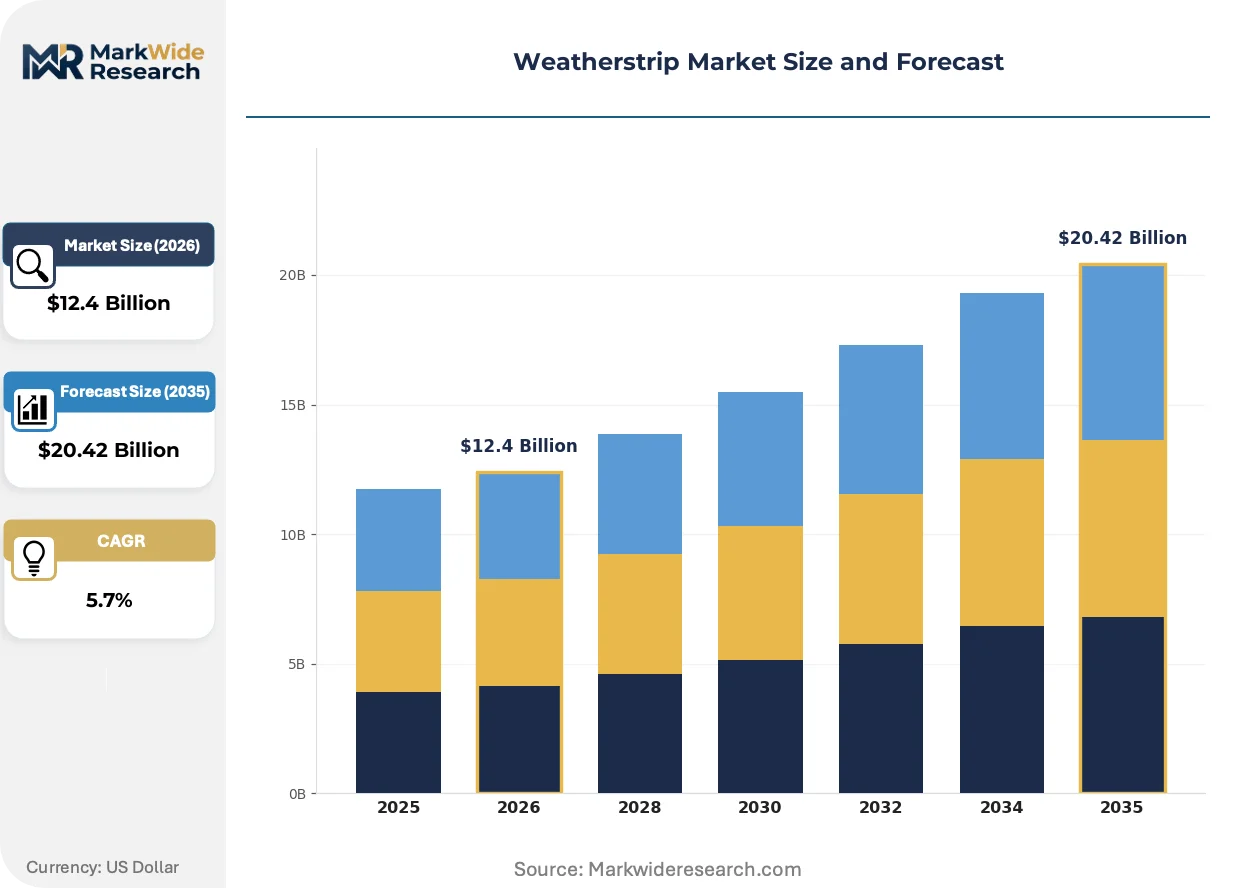
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, Neoprene, PVC, Silicone Application: Automotive, Residential, Industrial, Marine Material: Rubber, Foam, Felt, Vinyl Installation Method: Adhesive, Clips, Snap Fit, Slide In |
| Companies Covered | Cooper Standard Automotive, 3M Company, Hutchinson, Toyoda Gosei, Nishikawa Corporation, Schlegel Automotive, Magna International, Nitto Denko Corporation, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weatherstrip Market Trends and Innovations
Digital manufacturing controls and sustainable formulation chemistry are converging to reshape competitive positioning across automotive and construction sealing markets.
Laser-guided profile measurement systems integrated with real-time density feedback loops are decentralizing quality control from centralized metrology labs to production-line operators. Tier-one automotive suppliers in Stuttgart and Detroit are deploying these systems to compress first-article approval cycles. The technology is decentralizing specification authority toward plant-level engineers capable of certifying dimensional compliance without external laboratory intervention.
REACH Annex XVII restrictions on phthalate plasticizers and cadmium-based curing activators are compelling compounders to validate bio-based alternatives under ECHA notification procedures. German and French automotive OEMs are now requiring full material disclosure down to 0.1 percent substance concentration. The regulatory pressure is concentrating formulation development among compounders with dedicated regulatory affairs teams in Brussels and Ludwigshafen.
Automotive OEMs are unbundling after-sales weatherstrip replacement from dealership service packages, creating direct procurement relationships with certified aftermarket distributors. This disintermediation is compressing margin pools previously captured by franchised dealer networks. The channel shift is most advanced in California and Texas, where fleet operators are negotiating volume contracts with compounders for direct-to-depot delivery of pre-cut sealing kits.
Weatherstrip Market Segmentation
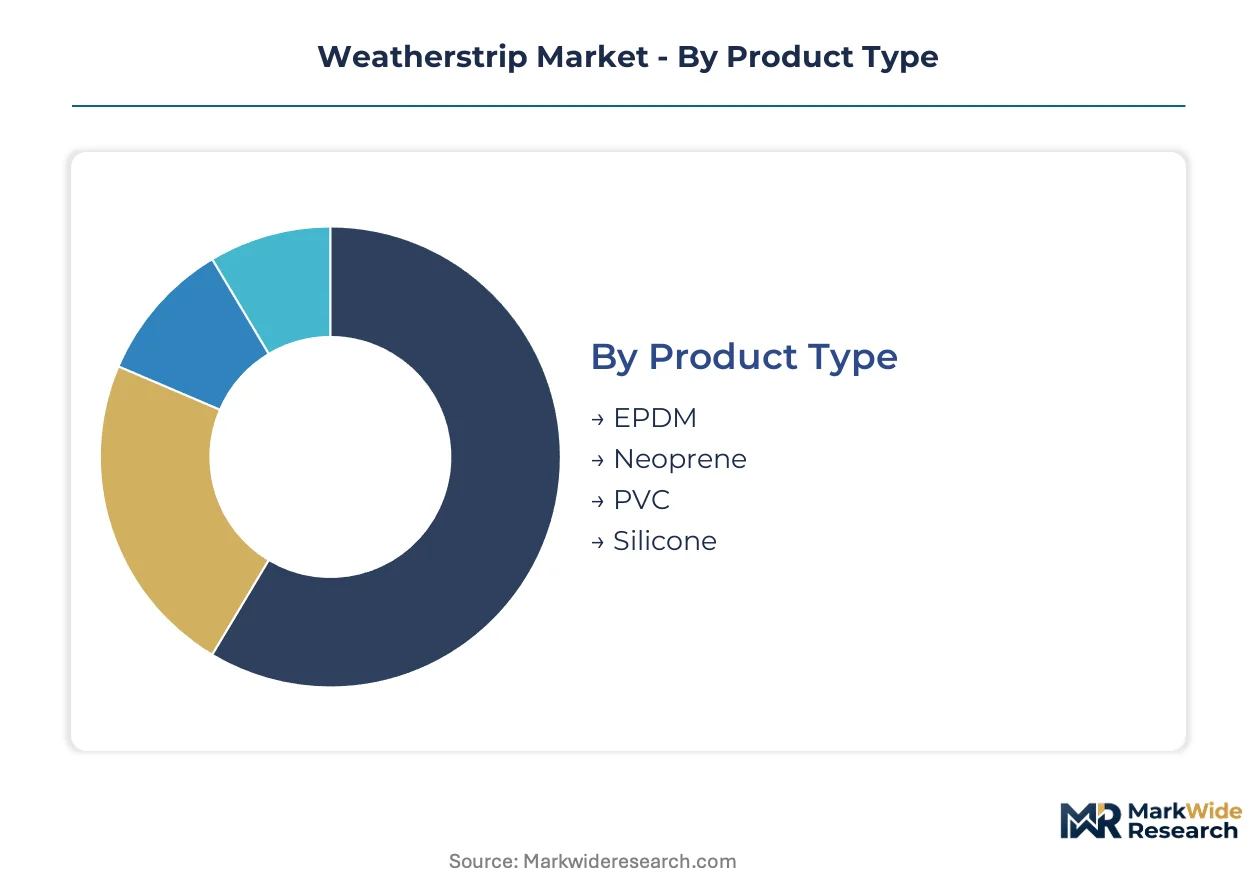
Weatherstrip specification diverges sharply across end-use environments, with automotive thermal-acoustic systems demanding validated compression set performance while residential retrofits prioritize installation speed over material longevity. Material chemistry and fastening geometry together determine warranty terms, replacement cycles, and supplier margin structures.
Product Type:
Customization intensity runs from commodity thermoplastics to precision-tuned elastomer formulations requiring OEM validation cycles.
- EPDM:Ethylene-propylene-diene monomer formulations deliver ozone resistance and thermal stability from minus 40 to 150 degrees Celsius, serving automotive door and glazing seals where EPA-NHTSA fuel economy rules mandate reduced closure-force profiles. Passenger vehicle OEMs in Stuttgart and Detroit specify multi-density foam-core constructions for acoustic damping.
- Silicone:Fluorosilicone and VMQ grades withstand sustained exposure above 150 degrees Celsius, commanding premium positioning in marine engine compartments and industrial oven seals where UV degradation determines replacement intervals. Demand concentrates in Mediterranean yacht builders and Gulf Coast petrochemical facilities.
- Neoprene:Chloroprene-based compounds balance oil resistance with moderate weathering performance, occupying mid-tier commercial construction and HVAC equipment gasket applications.
- PVC:Plasticized polyvinyl chloride offers lowest unit cost for residential window retrofits, though REACH Annex XVII phthalate restrictions are forcing compound reformulation in EU-bound supply chains.
Most installed capacity flows through EPDM. Expansion is steepest in silicone.
Application:
Volume concentration tracks vehicle production cycles and building energy code enforcement intensity across regulatory jurisdictions.
- Automotive:Door, hood, and glass sealing systems require validated compression set below 25 percent and Shore A hardness between 40 and 80, with electric vehicle battery enclosures now demanding integrated EMI shielding layers. German and Japanese OEMs are consolidating supplier bases around vertically integrated compounders.
- Residential:Window and door retrofits prioritize installer productivity over material longevity, with adhesive-backed foam tapes displacing mechanical fastening in California and Texas single-family rehabilitation markets.
- Industrial:Equipment gasket applications span temperature extremes and chemical exposure profiles, with food processing facilities specifying FDA-compliant silicone grades.
- Marine:Hatch and port sealing systems face salt spray and UV degradation cycles, with Mediterranean and Southeast Asian boatbuilders specifying fluorosilicone for premium yacht segments.
Automotive commands the greatest revenue concentration. Residential retrofits are climbing the fastest as building energy codes tighten.
Material:
Cost structure and performance durability separate cellular constructions from dense elastomer extrusions.
- Rubber:Solid and sponge EPDM, neoprene, and natural rubber formulations dominate automotive and industrial sealing, with density gradients engineered through controlled blowing agent decomposition during continuous extrusion.
- Foam:Open-cell and closed-cell polyurethane and polyethylene cores enable multi-density profiles with integrated air chambers, serving acoustic sealing applications where foam-in-place manufacturing lines have concentrated in Stuttgart industrial zones.
- Felt:Compressed wool and synthetic fiber seals occupy legacy automotive applications and furniture drawer systems where low closure force and dust exclusion outweigh weather resistance requirements.
- Vinyl:Flexible PVC extrusions serve cost-sensitive residential and light commercial markets, with formulation flexibility allowing rapid color matching to window frame aesthetics.
Rubber formulations carry the heaviest installed base. Foam-core constructions are gaining specification share fastest in premium automotive platforms.
Installation Method:
Labor content and field failure rates determine method selection across new construction versus retrofit channels.
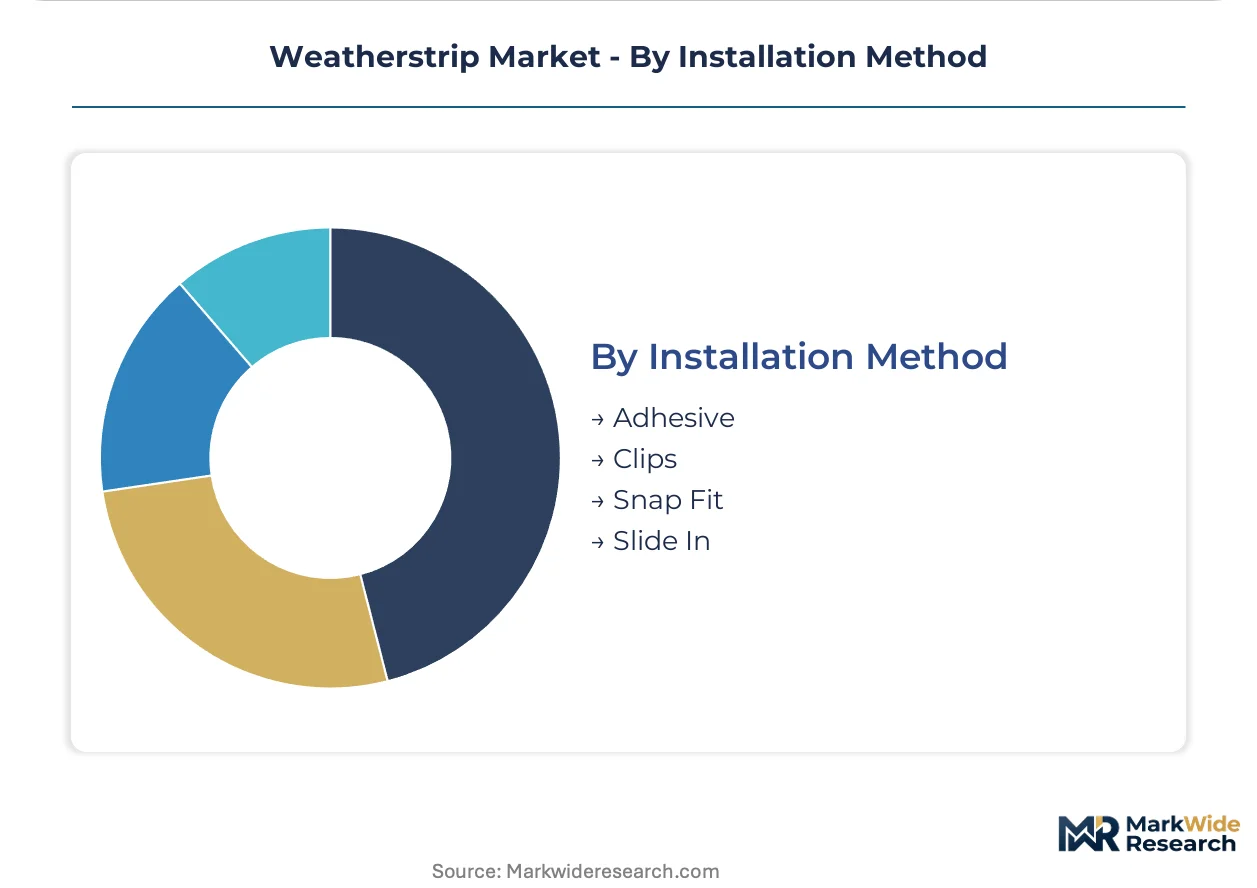
- Adhesive:Pressure-sensitive and structural bonding tapes enable rapid retrofit installation without specialized tooling, though surface preparation requirements and temperature-dependent cure times limit reliability in exterior envelope applications.
- Clips:Mechanical fastening systems with integrated metal carriers allow tool-free replacement of automotive door seals, supporting direct-to-depot aftermarket distribution models advancing in California and Texas fleet operations.
- Snap Fit:Interlocking profile geometries engage with sheet metal flanges or plastic retainers, eliminating consumables while requiring precise dimensional tolerance control during extrusion.
- Slide In:T-slot and kerf-mounted profiles serve replacement window systems and industrial equipment panels where field adjustability outweighs initial installation speed.
Clip-based systems dominate automotive OEM and aftermarket channels. Adhesive methods are expanding most quickly in residential retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting weatherstrip manufacturing toward jurisdictions with lower compliance costs for REACH-style chemical restrictions, while EPA-NHTSA fuel economy mandates in the United States and passive house certification in Germany sustain premium demand for validated sealing systems.
United States
EPA-NHTSA coordinated fuel economy and greenhouse gas standards mandate reduced door-seal drag coefficients across passenger vehicle platforms. California Title 24 building energy codes extend weatherstrip performance warranties to twenty-five years for net-zero residential construction. Detroit-area automotive suppliers are consolidating around vertically integrated compounders capable of single-source accountability for thermal-acoustic sealing systems.
Germany
EU Green Deal procurement rules and REACH Annex XVII chemical restrictions are reshaping formulation requirements for automotive and construction applications. Passive house certification mandates under the Energy Efficiency Directive elevate specification authority toward certified system integrators. Stuttgart industrial zones concentrate foam-in-place manufacturing lines serving premium automotive acoustic sealing programs.
China
MIIT new energy vehicle production quotas are expanding demand for battery enclosure sealing with integrated EMI shielding layers. GB standards for building energy efficiency are tightening thermal performance requirements in commercial envelope systems. Yangtze River Delta rubber compounders are broadening EPDM output to serve electric vehicle thermal management needs.
Japan
METI carbon neutrality roadmaps are accelerating specification of bio-based plasticizers in automotive sealing applications. JIS standards for vehicle component durability sustain demand for precision-extruded profiles with validated compression set performance. Toyoda Gosei anchors domestic supply networks through advanced extrusion capabilities for luxury vehicle programs.
India
BIS thermal performance mandates for commercial building envelope systems are creating first-mover advantages for compounders establishing local extrusion capacity. PLI scheme incentives for automotive component manufacturing are attracting tier-one supplier investments. Maharashtra and Gujarat industrial corridors are emerging as concentration points for domestic weatherstrip fabrication serving OEM retrofit and aftermarket channels.
Weatherstrip Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric vehicle thermal management and bio-based formulation niches. The vendor base concentrates around automotive-tier compounders with captive polymer operations and construction-focused distributors with certified installation networks. Three archetypes dominate: vertically integrated automotive suppliers, regional construction-material distributors, and specialty compounders serving marine and industrial segments. Capacity expansion and backward integration into monomer production represent the dominant competitive moves.
Within the automotive-tier archetype, Cooper Standard Automotive exemplifies North American compounders leveraging captive polymer blending operations, while Toyoda Gosei represents Japanese precision-extrusion specialists serving luxury vehicle programs. Hutchinson occupies a position among European acoustic sealing providers with integrated manufacturing capabilities.
| Leading Market Players |
|---|
| Cooper Standard Automotive |
| 3M Company |
| Hutchinson |
| Toyoda Gosei |
| Nishikawa Corporation |
| Schlegel Automotive |
| Magna International |
| Nitto Denko Corporation |
| Dana Incorporated |
| Others |
Pricing and Supply Chain Analysis
Polymer chemist clusters in the Yangtze River Delta and Stuttgart industrial zones create labor-cost differentials that widen pricing-tier spreads between precision-extruded automotive grades and commodity residential retrofits. EPDM compounders with captive blending operations capture margin buffers unavailable to distributors sourcing from third-party resin suppliers.
Pricing Analysis
Distributor margin compression runs deepest in aftermarket channels where direct-to-depot procurement by California and Texas fleet operators is disintermediating traditional dealer networks. Three-tier pricing structure across premium, standard, and economy levels separates fluorosilicone marine grades from multi-density automotive EPDM and adhesive-backed PVC residential tapes. Price differentiation hinges on certification grade—REACH-compliant bio-based formulations command 15-25 point premiums—and volume scale, with OEM direct contracts securing lowest unit economics. Cost compression in standard-tier EPDM is intensifying because Gulf Coast ethylene-propylene feedstock tightness forces margin absorption by non-integrated compounders. Residential retrofit installers exhibit highest price sensitivity, selecting adhesive foam tapes based on labor-cost-per-linear-foot rather than material longevity.
Supply Chain Analysis
Dual-sourcing requirements from Stuttgart and Detroit OEMs mandate multi-supplier qualification for thermal-acoustic sealing systems, preventing single-source lock-in even for validated formulations. Geographic supply concentration centers on China, Germany, and the United States, with Yangtze River Delta compounders serving domestic EV battery enclosure demand and Stuttgart-area manufacturers anchoring European acoustic sealing programs. Raw material dependencies draw from Gulf Coast petrochemical complexes for EPDM monomers, Southeast Asian carbon black suppliers, and European bio-based plasticizer producers. Single-source vulnerability in ethylene-propylene feedstock creates exposure to Gulf Coast weather events and refinery maintenance cycles. Distribution runs through tier-one automotive suppliers with captive logistics networks, construction-material distributors with certified installer relationships, and emerging direct-to-depot channels for fleet aftermarket procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The weatherstrip market functions as a regulatory compounder where EPA-NHTSA fuel economy mandates and EU REACH chemical restrictions continuously reshape formulation specifications and demand profiles.
For Market Incumbents: Deepen backward integration into EPDM monomer production to insulate margin structures from Gulf Coast feedstock volatility. Expand foam-in-place manufacturing capacity in Stuttgart industrial zones to defend specification authority against emerging acoustic sealing specialists. Prioritize accelerated aging protocol investments that compress 18-24 month qualification timelines, as OEMs are consolidating supplier bases around vertically integrated compounders with validated thermal-oxidative datasets. For New Entrants and Emerging Players: Begin with India commercial building envelope systems where BIS thermal performance mandates are creating first-mover advantages ahead of domestic supply shortages. Target electric vehicle battery enclosure sealing with integrated EMI shielding layers, a segment where MIIT production quotas are expanding addressable demand faster than incumbent capacity expansion. Pursue EU Green Deal public procurement pathways by securing third-party carbon footprint certification for bio-based plasticizer formulations. For Investors and Strategic Acquirers: Automotive-tier compounders with captive polymer operations are the most active acquirer in this space, seeking precision extrusion capabilities and validated OEM qualification datasets. Over the medium-term horizon, consolidation plays among regional distributors with certified installation networks offer defensive cash flow profiles. Monitor REACH Annex XVII enforcement intensity as the inflection indicator—accelerated phasedowns of conventional plasticizers will force reformulation investments that disadvantage smaller compounders lacking dedicated regulatory affairs capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive ethylene-propylene supply insulates Cooper Standard Automotive and similar compounders from Gulf Coast feedstock volatility. |
| Foam-in-Place Manufacturing Scale-Up | Integrated polyurethane core density control enables Hutchinson to serve Stuttgart OEM acoustic damping specifications. |
| Bio-Based Plasticizer Validation | ECHA notification procedures under REACH Annex XVII open EU Green Deal procurement pathways for certified compounders. |
| Direct-to-Depot Distribution Buildout | California and Texas fleet operators are disintermediating dealer networks through volume contracts with compounders. |
| Accelerated Aging Protocol Investment | 10,000-hour thermal-oxidative datasets compress qualification timelines and secure single-source accountability contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer chemists, tier-one automotive procurement officers, building envelope system integrators, and aftermarket distribution managers with secondary validation from EPA fuel economy rulemakings, ECHA REACH substance databases, MIIT new energy vehicle production filings, and customs trade records for EPDM and silicone compound flows. Bottom-up demand modeling across vehicle production cycles and building permit volumes triangulated against top-down chemical industry capacity assessments.
Segment-weighting approaches distributed value projections across material chemistry tiers, installation method channels, and end-use application clusters spanning automotive thermal-acoustic systems, residential retrofit markets, and industrial gasket applications. CAGRs were derived from regression analysis of historical production data and regulatory mandate implementation schedules, with electric vehicle battery enclosure demand and passive house certification adoption serving as primary demand elasticity inputs across the projection horizon.
Several conditions sit outside the modeled scope, including abrupt REACH chemical restriction accelerations, Gulf Coast petrochemical complex disruptions, and trade policy shifts affecting EPDM resin flows. Forecasts reflect assumptions about regulatory implementation timelines and OEM supplier consolidation trajectories. Deviation in EPA-NHTSA rulemaking stringency or EU Green Deal procurement enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
United States Car Bumper Guard Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
Train Seat Materials Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Paint Protection Film Market