
 Automotive Door Check Market | 2026-2036
Automotive Door Check Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Check Market Analysis
Lightweight material substitution is reconfiguring how automotive door check assemblies achieve mass reduction targets without sacrificing mechanical endurance. Magna International leverages aluminum-intensive designs to sustain platform commonality across multiple vehicle programs. Brose Fahrzeugteile anchors its position through specialized electromechanical integration expertise in European premium segments. Gestamp Automoción competes on stamped steel process scale, supplying structural door hardware to volume manufacturers across three continents.
An automotive door check is a mechanical or electromechanical hinge-mounted device that controls door swing arc, hold-open positioning, and closing velocity, typically fabricated from stamped steel or die-cast aluminum with polymer bushings and spring detent mechanisms. Its primary commercial purpose is to prevent uncontrolled door movement during ingress and egress while reducing wind noise and seal wear over the vehicle lifecycle. Conventional check assemblies still dominate unit volume in entry and mid-range vehicle programs, though gas strut check configurations are capturing margin pools in luxury and electric vehicle architectures where smooth kinematics and reduced closing effort command price premiums. Aluminum material grades are displacing steel in applications where OEM manufacturers face fleet-average CO2 or mass compliance thresholds.
NHTSA enforces FMVSS 206 door latch and retention requirements that directly dictate load-cycle validation for check arm assemblies sold into United States vehicle programs. EPA corporate average fuel economy standards create indirect pressure for mass-reduced door check designs through downstream OEM procurement specifications. Tier-1 suppliers and vehicle assemblers must monitor how NHTSA interpretive rulings on automated door systems reshape hardware qualification pathways for electromechanically actuated checks. Stakeholders should track which regulatory body moves first to codify durability standards for soft-close and power-assist door check variants.
Market Dynamics
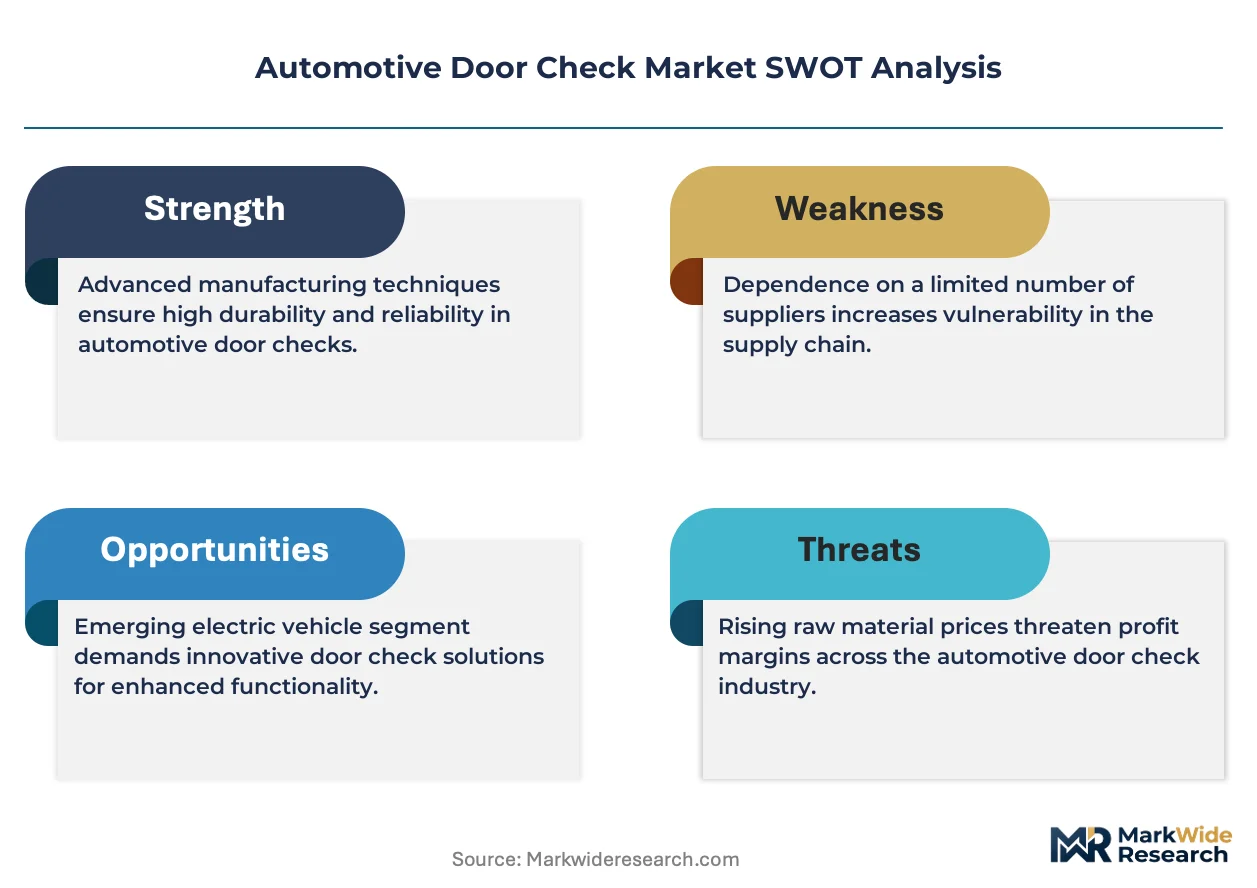
Gas strut check configurations are displacing conventional detent mechanisms in premium electric vehicle architectures, compressing development cycles and forcing suppliers to requalify durability protocols under NHTSA FMVSS 206 latch retention standards.
Growth Catalysts
- EPA fleet CO2 compliance:Mass-reduction mandates compel OEM procurement of aluminum-intensive door check assemblies to offset battery weight in electrified platforms.
- Electric vehicle kinematics:Smooth door actuation and reduced closing effort requirements in luxury EV architectures expand addressable margin pools for electromechanical check variants.
- Germany supply cluster concentration:Brose Fahrzeugteile and Kiekert AG anchor specialized electromechanical expertise that premium European automakers leverage for platform differentiation.
Market Restraints
- Aluminum input cost volatility:London Metal Exchange aluminum price swings compress Tier-1 supplier margins on fixed-price OEM contracts spanning multi-year vehicle programs.
- Stamped steel supply concentration:Gestamp Automoción and Magna International control high-volume structural door hardware capacity, creating single-source risk for volume manufacturers.
- FMVSS 206 validation friction:NHTSA load-cycle durability requirements extend qualification timelines for new check arm geometries, delaying program launches.
Strategic Opportunities
- Soft-close power assist convergence:Integration of electromechanical checks with automated door systems creates white space for suppliers with mechatronics and sensor fusion capabilities.
- Aftermarket replacement channel:Independent repair networks and collision shops represent underpenetrated distribution for check arm and bushing replacement kits.
- China NEV platform proliferation:Domestic electric vehicle manufacturers seek localized door check supply to meet MIIT domestic content and dual carbon policy requirements.
Industry Challenges
- Mechatronics talent scarcity:Electromechanical check development requires embedded software engineers and motion control specialists that traditional hardware suppliers struggle to recruit.
- Legacy vehicle integration complexity:Retrofitting power-assist checks into existing door structures demands structural reinforcement and wiring harness modifications that inflate retrofit costs.
- Cross-platform certification timelines:OEM commonality strategies require single check designs to satisfy divergent regional durability standards, compressing validation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Check Market |
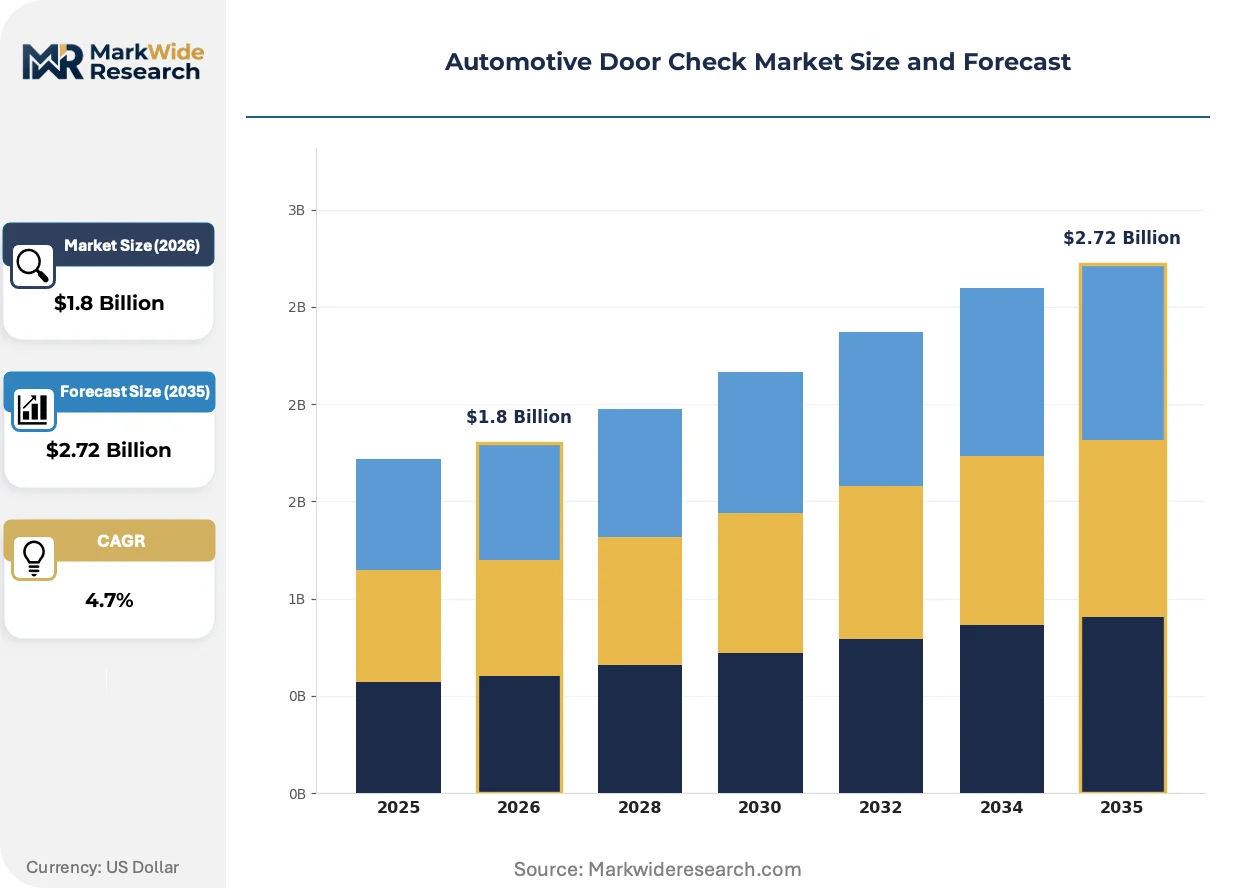
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Check, Adjustable Check, Gas Strut Check, Heavy-Duty Check Material: Steel, Aluminum, Plastic, Composite Material End User: OEM Manufacturers, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation Type: Direct Fit, Universal Fit, Custom Fit, Integrated |
| Companies Covered | Magna International, AISIN Corporation, Brose Fahrzeugteile, Dura Automotive Systems, Gestamp Automoción, Kiekert AG, Inteva Products, Edscha Holding, ITW Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Check Market Emerging Trajectories
Electromechanical actuation is collapsing the functional boundary between door checks and full mechatronic closure systems, compressing supplier value chains and redefining competitive differentiation around software-defined motion profiles rather than mechanical detent precision.
Aluminum die-casting with integrated polymer bushing carriers is collapsing the part count and assembly labor content of traditional stamped steel check arms. Premium EV manufacturers in Germany and California are adopting these consolidated designs to meet fleet mass targets without sacrificing hold-open load specifications. The technology is collapsing the historical cost gap between lightweight and conventional check configurations.
NHTSA interpretive rulings on automated door systems are tightening hardware qualification pathways for electromechanically actuated checks sold into United States vehicle programs. The agency is requiring supplemental validation for power-assist variants that interface with obstacle detection sensors and pinch-protection algorithms. Suppliers must now demonstrate fault-tolerant mechanical retention independent of electronic control systems.
Fleet procurement specifications are consolidating around platform-common check designs that span multiple vehicle segments and price tiers. OEM engineering organizations are rejecting segment-specific hardware in favor of scalable electromechanical architectures that software configures for hold effort and detent positioning. This specification consolidation is most visible in Volkswagen Group and Stellantis platform strategies.
Automotive Door Check Market Segmentation
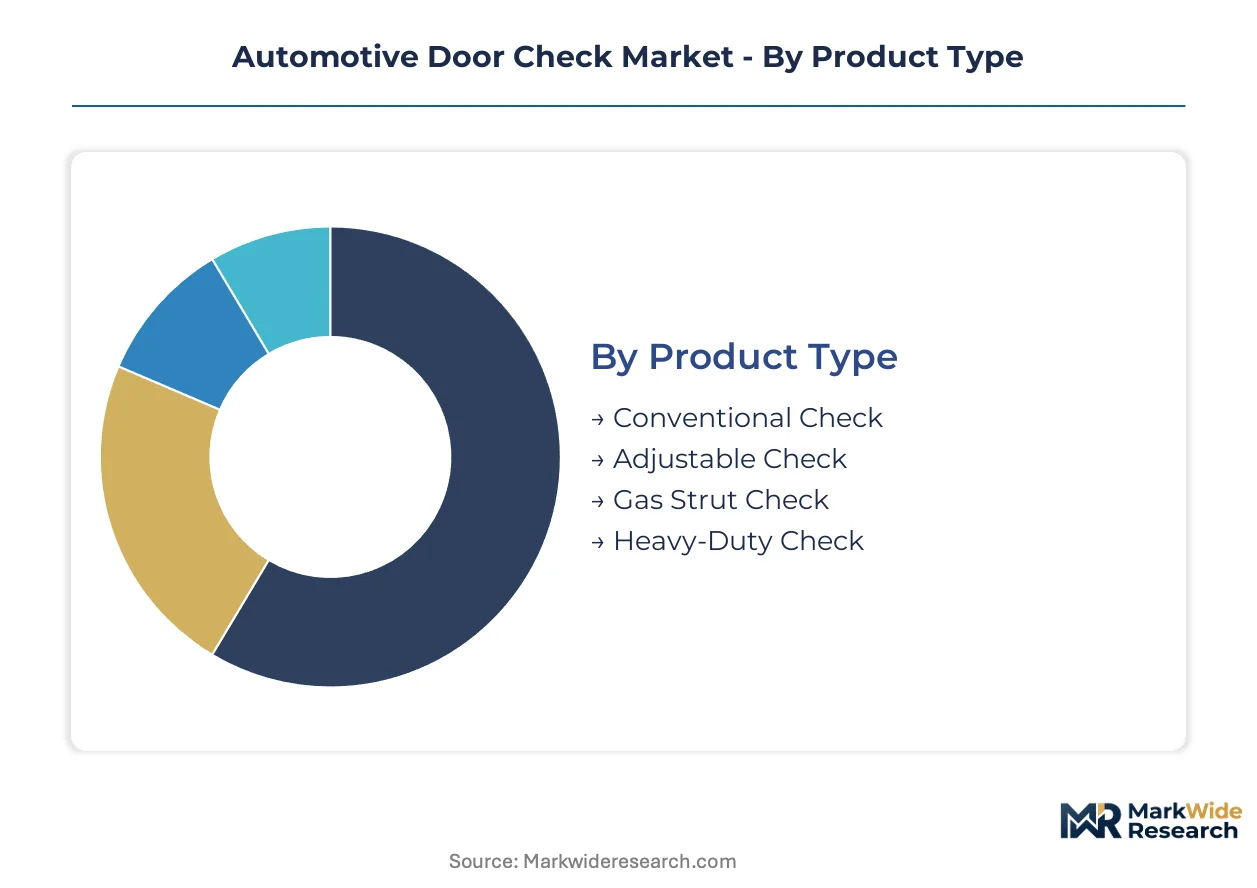
Segmentation in the automotive door check market reveals how procurement specifications diverge across electrification strategies, mass compliance thresholds, and regional regulatory frameworks. Understanding these fault lines enables suppliers to align R&D investment with the highest-margin application clusters.
Product Type:
After-sales service intensity varies sharply across check architectures, with electromechanical variants requiring diagnostic tooling and software updates that conventional detent mechanisms never demand.
- Conventional Check:Mechanical detent systems with stamped steel arms and polymer bushings dominate entry and mid-range vehicle programs. Demand concentrates in India and Southeast Asia where OEMs prioritize unit cost over kinematic refinement in mass-market platforms.
- Gas Strut Check:Pneumatic damping configurations deliver smooth arc control and reduced closing effort for luxury electric vehicle architectures. Premium German automakers specify these for flagship sedan and SUV programs where tactile quality differentiates brand positioning.
- Adjustable Check:Variable hold-force mechanisms accommodate diverse door masses across modular platform strategies. Tier-1 suppliers engineer these for Stellantis and Renault-Nissan commonality programs spanning multiple vehicle segments.
- Heavy-Duty Check:Reinforced arm geometries withstand commercial vehicle duty cycles and frequent operator loading. North American fleet truck manufacturers specify these for pickup and van applications where door mass exceeds passenger car norms.
Conventional Check holds the largest share; momentum sits with Gas Strut Check.
Material:
Cost tier stratification in raw material selection directly shapes supplier margin structures and OEM compliance calculus.
- Steel:Stamped mild and high-strength steel grades remain the baseline for volume production. Gestamp Automoción and Magna International leverage process scale to defend cost positions in entry-level vehicle programs across Mexico and Eastern Europe.
- Aluminum:Die-cast aluminum alloys with integrated bushing carriers collapse part count while satisfying fleet CO2 mass targets. German premium EV manufacturers specify these for battery-electric platforms where every kilogram offsets battery weight.
- Plastic:Glass-reinforced polymer check bodies reduce corrosion risk in coastal and winter-salt environments. Japanese OEMs specify these for kei-car and compact segments where cost and weight minimization converge.
- Composite Material:Carbon fiber reinforced polymers and hybrid metal-composite constructions serve motorsport and ultra-luxury applications. Limited production Italian and British marques specify these where unit economics tolerate extreme material costs.
Steel dominates unit volume; Aluminum is expanding most quickly as electrification accelerates.
End User:
Customer type determines contract structure, with vehicle assemblers demanding system integration liability that component suppliers resist.
- OEM Manufacturers:Brand-owning vehicle producers specify check performance requirements and validate supplier designs against internal durability protocols. Volkswagen Group and Toyota Motor Corporation maintain captive engineering organizations that gate supplier qualification.
- Aftermarket Providers:Independent distributors and collision repair networks source replacement check arms and bushing kits for vehicle aging fleets. North American and European parts chains represent underpenetrated channels relative to brake and suspension categories.
- Vehicle Assemblers:Contract manufacturers and joint venture production entities procure check assemblies as part of door module supply agreements. Magna Steyr and Valmet Automotive integrate checks into complete door systems for outsourced vehicle programs.
- Tier-1 Suppliers:Door system integrators and hinge specialists source check mechanisms as subcomponents for module assembly. Brose Fahrzeugteile and Kiekert AG manufacture proprietary check designs while also procuring commodity variants for cost-sensitive applications.
OEM Manufacturers command the largest procurement volume; Aftermarket Providers offer the steepest expansion trajectory as vehicle parc ages.
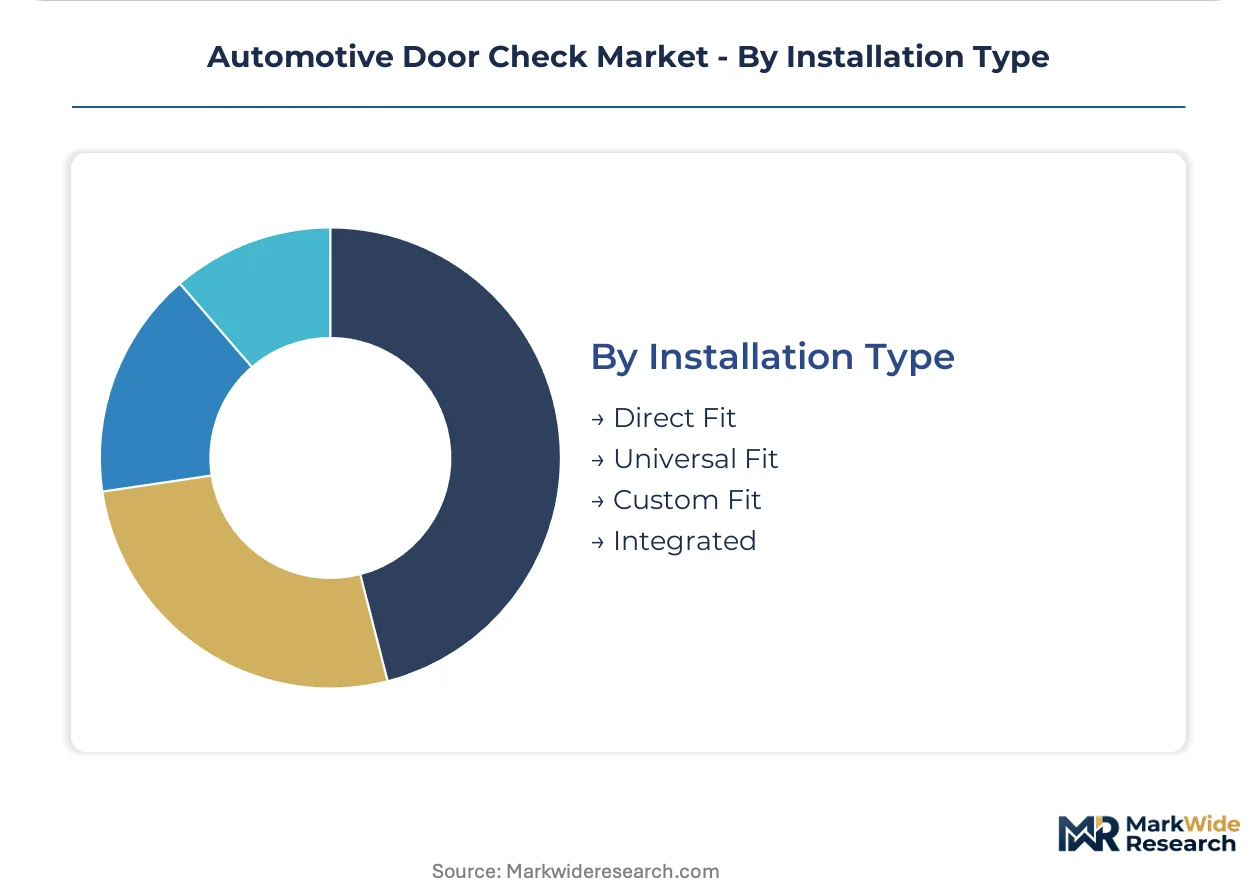
Installation Type:
Volume concentration favors integrated and direct-fit configurations that minimize assembly line labor content.
- Direct Fit:Vehicle-specific check geometries match OEM mounting points without modification. Korean and Chinese automakers specify these for high-volume programs where line-side efficiency dictates minimal adjustment.
- Universal Fit:Adjustable mounting configurations accommodate multiple vehicle applications through hardware adaptation. Aftermarket distributors favor these for inventory efficiency across fragmented vehicle populations.
- Custom Fit:Engineered-to-order check assemblies serve low-volume specialty and commercial vehicle applications. North American upfitters and European coachbuilders specify these for chassis-cab modifications.
- Integrated:Check mechanisms embedded within hinge or door module assemblies reduce part count and assembly steps. BMW and Mercedes-Benz specify these for premium architectures where module consolidation justifies tooling investment.
Direct Fit captures the largest share; Integrated configurations are gaining share fastest as platform commonality intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers dominate export flows into premium European and North American vehicle programs, while Chinese manufacturers scale capacity for domestic new energy vehicle platforms.
United States
NHTSA FMVSS 206 latch retention standards tighten validation protocols for check arm assemblies destined for Detroit Three and Tesla production lines. EPA fleet CO2 compliance pressures OEM procurement toward aluminum-intensive designs. Michigan and Ohio anchor stamping and assembly operations serving the Midwest automotive corridor.
Germany
Brose Fahrzeugteile and Kiekert AG anchor specialized electromechanical expertise that premium automakers leverage for platform differentiation. KBA type-approval requirements govern durability testing for door retention systems entering EU circulation. Bavaria and Baden-Württemberg concentrate R&D facilities and precision manufacturing for luxury EV architectures.
China
MIIT domestic content requirements and dual carbon policy targets accelerate localized supply chain development for NEV door check systems. GB standards for automotive door retention hardware impose testing protocols adapted from UN ECE regulations. Yangtze River Delta and Pearl River Delta clusters house die-casting and module assembly capacity serving BYD, NIO, and Xpeng platforms.
Japan
METI technology roadmaps prioritize lightweight material substitution in structural door hardware for hybrid and battery-electric platforms. JIS standards specify load-cycle durability for check mechanisms in kei-car through luxury segments. Aichi Prefecture and Kansai region maintain integrated supply relationships between Toyota, Honda, and domestic hinge specialists.
Mexico
USMCA regional value content rules shape procurement patterns for door modules exported to United States assembly plants. NOM safety standards align with FMVSS 206 for components entering North American vehicle programs. Nuevo León and Bajío Region concentrate stamping operations supplying Detroit Three and German transplant factories.
Automotive Door Check Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base clusters around three strategic archetypes: integrated door system suppliers, dedicated hinge and check specialists, and diversified structural component fabricators. Scale-driven consolidation and mechatronics capability acquisition define dominant competitive moves.
Within the integrated system tier, Magna International and AISIN Corporation occupy positions spanning module assembly through component supply. Brose Fahrzeugteile and Kiekert AG exemplify the specialist archetype, anchoring electromechanical expertise concentrated in European premium segments. Gestamp Automoción represents the scale-driven structural fabricator model, leveraging stamped steel process breadth across multiple vehicle programs and continents.
| Leading Market Players |
|---|
| Magna International |
| AISIN Corporation |
| Brose Fahrzeugteile |
| Dura Automotive Systems |
| Gestamp Automoción |
| Kiekert AG |
| Inteva Products |
| Edscha Holding |
| ITW Automotive |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese die-casting facilities is compressing aluminum check arm pricing globally while forcing European suppliers to accelerate mechatronics differentiation to defend margin pools. This utilization imbalance concentrates bargaining power with OEM procurement organizations that can arbitrage regional cost structures.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange aluminum pricing dominate long-term OEM supply agreements, insulating buyers from raw material volatility while squeezing supplier margins during price spikes. Pricing stratifies across electromechanical premium, aluminum-intensive standard, and stamped steel economy tiers, with differentiation driven by certification grade against FMVSS 206 and volume scale commitments. Cost compression in the steel tier is intensifying because Gestamp and Magna leverage Mexican stamping scale against fixed-price Asian competitors. Volume manufacturers exhibit highest price sensitivity; luxury EV programs prioritize kinematic performance over unit cost.
Supply Chain Analysis
Export control regimes limiting semiconductor and sensor technology flows to Chinese check actuator manufacturers are fragmenting global supply networks and accelerating regional sourcing decisions. Production gravity centers on Germany for electromechanical expertise, China for die-casting and module assembly, and Mexico for stamped steel serving USMCA-compliant Detroit Three programs. The chain draws from aluminum billets, polymer bushings, and precision sensors as critical inputs. Single-source vulnerability concentrates in German hinge specialists for premium European platforms. Distribution runs through Tier-1 door module integrators rather than direct OEM supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive door check demand sits in early-cycle expansion as electric vehicle architectures multiply touchpoint requirements per vehicle and software-defined motion profiles displace mechanical detents. Penetration of electromechanical variants remains below saturation across volume segments.
For Market Incumbents: Harden supply chain resilience by securing captive aluminum smelting capacity or long-term offtake agreements with European producers to offset LME volatility. Accelerate embedded software talent acquisition before mechatronics capability scarcity widens competitive gaps with emerging Asian suppliers.
For New Entrants and Emerging Players: Pursue aftermarket replacement channels in North America and Europe where independent repair networks remain underpenetrated relative to brake and suspension categories. Target collision repair distributors with diagnostic-enabled electromechanical check kits as the most penetrable segment requiring minimal OEM qualification barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap hinge specialists with latent electromechanical engineering capacity and established OEM qualification relationships. Watch NHTSA rulemaking on automated door system validation timelines as the signal indicating when mechatronics capability premiums will compress or expand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidated check designs spanning multiple vehicle segments reduce tooling amortization for Volkswagen Group and Stellantis. |
| Battery Supply Agreement | Long-term aluminum offtake contracts insulate Tier-1 margins from LME volatility in electrified platform procurement. |
| Software-Defined Vehicle Investment | Embedded motion control algorithms differentiate electromechanical checks from commodity mechanical detents in luxury segments. |
| Geographic Manufacturing Footprint | Mexican stamping capacity serves USMCA regional value content rules for Detroit Three door module exports. |
| Charging Infrastructure Partnership | Aftermarket diagnostic tooling networks create recurring revenue streams for electromechanical check service and calibration. |
Methodological Framework
Cross-validation between Tier-1 supplier procurement disclosures and OEM platform engineering documentation anchors the qualitative findings on specification consolidation trends. Primary interviews with door module integrators, OEM platform engineers, aftermarket distributors, and hinge manufacturing specialists combined with secondary analysis of vehicle production databases, IHS Markit registration data, NHTSA FMVSS 206 interpretive rulings, and SEC Tier-1 supplier filings. Bottom-up build from content-per-vehicle assumptions and top-down reconciliation against regional production volumes ensures triangulation integrity.
Calibration against historical adoption curves for electromechanical closure systems and aluminum substitution patterns in structural automotive components informs the projection framework. Segmentation dimensions span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from elasticity modeling of mass compliance thresholds and electrification penetration rates. Forecast inputs include MIIT domestic content requirements and EPA fleet CO2 trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese die-casting specialists or accelerated NHTSA automated door rulings would shift outcomes. Material shifts in aluminum price volatility regimes or EU battery-electric platform cancellation waves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive Insulation Market