
 Global Headliner (OE) Market | 2026-2036
Global Headliner (OE) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Headliner (OE) Market Analysis
Buyer concentration among electric vehicle OEMs is pivoting as Tesla, BYD, and Volkswagen Group expand their direct sourcing relationships with headliner specialists. Grupo Antolin leverages its integrated manufacturing footprint across Spain and Mexico to serve both European and North American assembly plants. Toyota Boshoku Corporation anchors its position through captive supply to Toyota Motor Corporation while competing for third-party EV platform business. Lear Corporation differentiates via its Seat Comfort and Acoustics division, which controls design-to-delivery programs for premium SUV headliner modules.
A headliner (OE) is a multi-layer composite panel mounted to a vehicle's roof structure, typically comprising a substrate of polyurethane or fiberglass, a foam core for acoustic insulation, and a decorative surface layer of fabric, vinyl, or leather, engineered to absorb cabin noise and integrate lighting, wiring, and safety systems. Foam-backed fabric configurations dominate passenger car volumes due to their balance of weight, cost, and NVH performance, while leather-trimmed variants command concentrated margin pools in luxury SUVs and executive sedans. Electric vehicle applications represent the fastest-growing segment as aerodynamic roof designs and battery packaging constraints intensify demand for thinner, lighter headliner assemblies with integrated thermal management.
The EPA regulates volatile organic compound emissions from automotive interior materials through its National Emission Standards for Hazardous Air Pollutants, while ECHA's REACH restrictions limit certain flame retardants and plasticizers in European-sold vehicles. China's SAMR enforces GB standards for cabin air quality that directly constrain adhesive and foam formulations used in domestic production. Stakeholders must monitor evolving chemical compliance requirements across multiple jurisdictions while positioning material innovation pipelines to serve the transition toward recyclable mono-material headliner designs.
Market Dynamics
Electric vehicle roof packaging constraints are compressing headliner thickness specifications while simultaneously expanding thermal-acoustic performance requirements, forcing material suppliers to engineer multi-functional composites that displace conventional foam-fabric laminates.
Growth Catalysts
- REACH chemical restrictions:Europe's phased limitations on halogenated flame retardants are accelerating formulation shifts toward phosphorus-based alternatives in polyurethane foam cores, opening substitution contracts for compliant suppliers.
- GB standards for cabin air quality:China's SAMR enforcement of interior emission limits is disqualifying high-VOC adhesive systems from domestic vehicle programs, redirecting procurement toward water-based and hot-melt bonding technologies.
- Battery thermal management integration:Electric vehicle platforms are specifying headliner substrates with embedded phase-change materials to moderate cabin temperature swings, creating new specification tiers for thermal-functional composites.
Market Restraints
- Polyol feedstock volatility:Propylene oxide and TDI pricing fluctuations compress foam core margins unpredictably, particularly for suppliers without backward integration into petrochemical inputs.
- Tooling amortization burdens:Deep-draw thermoforming dies for complex roof contours require capital commitments that disadvantage smaller tier suppliers bidding on low-volume premium programs.
- Aluminum honeycomb substitution:Some commercial vehicle and heavy-truck segments are specifying aluminum structural panels in place of polymer-based headliners for fire-resistance compliance, capping addressable market expansion in those categories.
Strategic Opportunities
- Recyclable mono-material designs:Single-polymer headliner constructions that bypass multi-layer separation challenges are qualifying for EU end-of-life vehicle directive credits, positioning early movers for circular-economy procurement mandates.
- India passenger vehicle localization:Domestic OEM assembly expansion around Chennai and Pune is creating import-substitution opportunities for headliner module suppliers willing to establish regional foam-in-place manufacturing.
- Smart surface integration:Capacitive touch controls and ambient lighting systems are embedding directly into decorative headliner layers, converging electronics and trim competencies into higher-value module contracts.
Industry Challenges
- Acoustic simulation talent scarcity:NVH engineering capabilities for predictive modeling of multi-layer composite absorption are concentrated among a limited pool of specialists, constraining supplier development timelines.
- Cross-material bonding validation:Adhesion between dissimilar substrates under thermal cycling requires extended OEM validation protocols that stretch program launch schedules and working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Headliner (OE) Market |
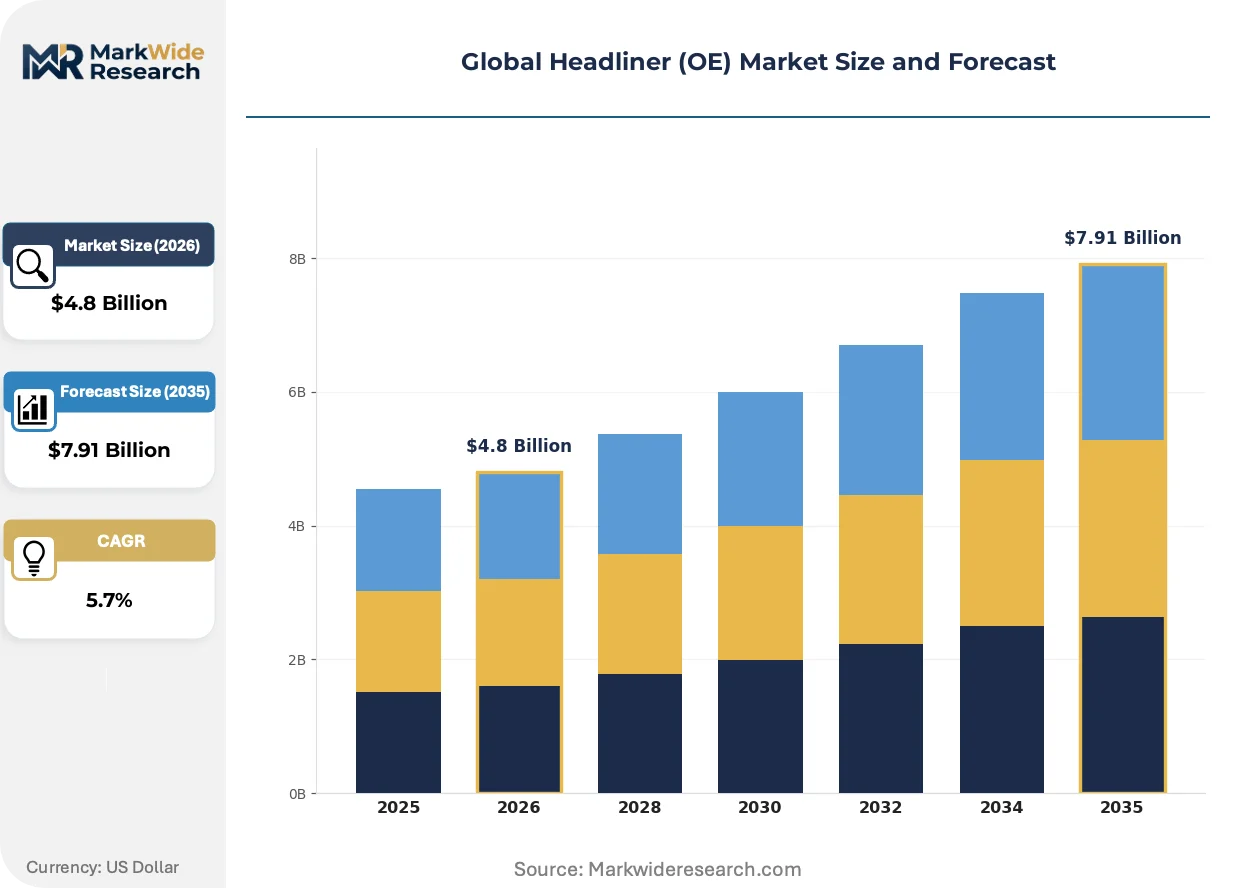
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabric, Foam, Vinyl, Leather End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Material: Polyester, Polyurethane, Cotton, Nylon Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, SUVs |
| Companies Covered | Grupo Antolin, Toyota Boshoku Corporation, IAC Group, Lear Corporation, Motus Integrated Technologies, Howa Co., Ltd, UGN, Inc., Freudenberg Performance Materials, Adient plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Headliner (OE) Market Emerging Trajectories
Active noise cancellation hardware and sustainable material streams are converging to redefine headliner engineering specifications across passenger and commercial vehicle segments.
Embedded microphone arrays and transducer modules are integrating directly into headliner substrates to enable road-noise cancellation without separate pillar-mounted speakers. Electric vehicle manufacturers with panoramic glass roofs are specifying these systems most aggressively, as aerodynamic turbulence and absent metal roof panels amplify cabin acoustics. The technology is integrating amplifier electronics and wiring harnesses into the headliner assembly itself, compressing supplier tiers and expanding module value content.
EPA National Emission Standards for Hazardous Air Pollutants are tightening permissible VOC thresholds from interior materials, directly constraining solvent-based adhesive formulations used in conventional lamination processes. Tier-one suppliers are responding by qualifying hot-melt and reactive polyurethane adhesive systems that eliminate flash-off emissions. Premium SUV and executive sedan programs in the United States are most affected, as these segments historically specified thicker foam constructions with higher adhesive loading.
Direct sourcing contracts from electric vehicle OEMs are consolidating previously fragmented procurement channels, compressing the traditional tiered supply hierarchy. Battery-electric platform specialists are awarding design-to-delivery programs to headliner specialists rather than delegating through seat or interior module integrators. This pattern is most visible in Germany and China, where Volkswagen Group and BYD have established direct material qualification relationships with acoustic component engineers.
Global Headliner (OE) Market Segmentation
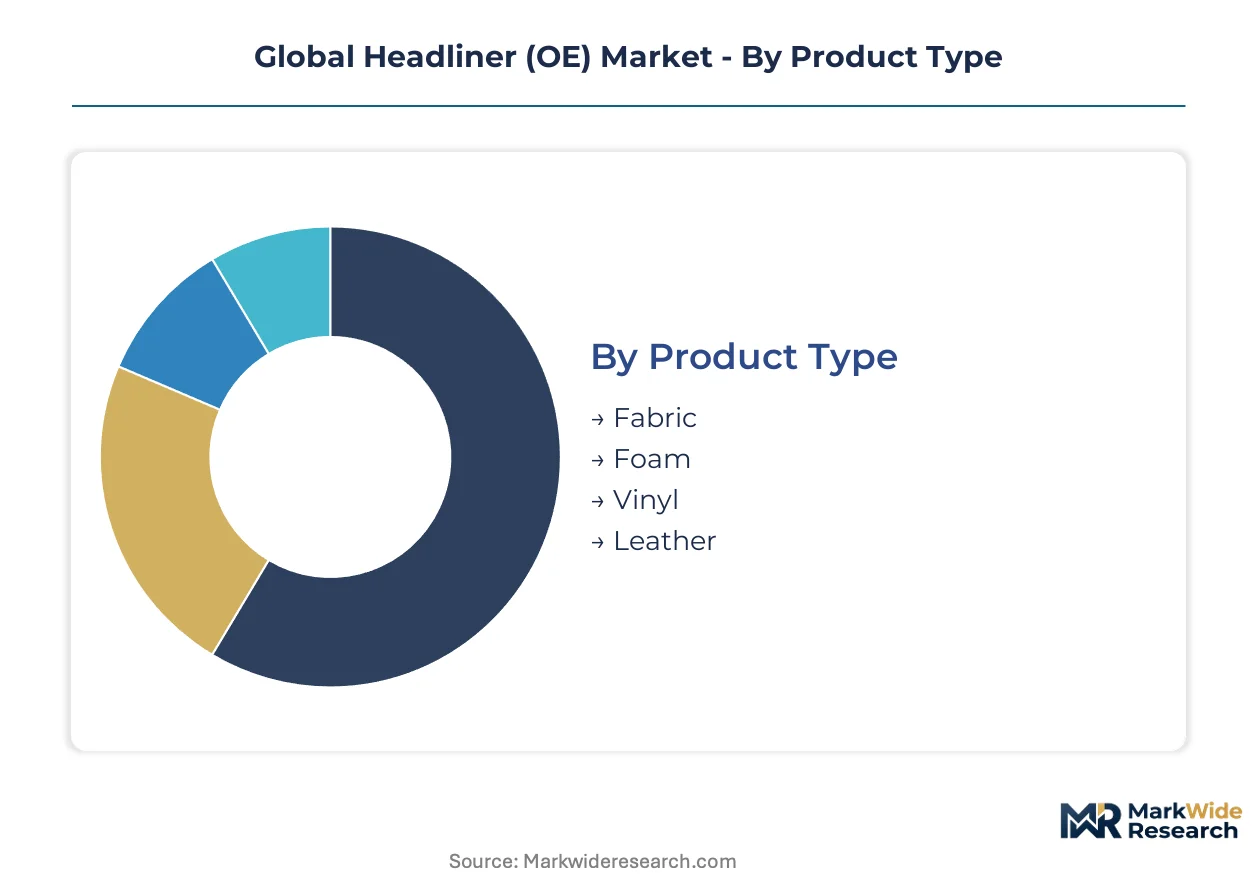
Headliner procurement patterns diverge sharply across material grades and vehicle architectures, with electric vehicle platforms driving specification resets while legacy internal combustion programs sustain conventional foam-fabric volumes. Understanding these segment boundaries clarifies where formulation investments and tooling commitments will concentrate.
Product Type:
Fabric and foam configurations dominate assembly line volumes, while leather and vinyl variants capture disproportionate margin pools in premium vehicle programs.
- Fabric:Woven or knitted textile surfaces bonded to polyurethane foam substrates deliver the baseline acoustic and aesthetic performance for mainstream passenger car production. Demand concentrates in high-volume compact and mid-size sedans manufactured in Germany and China, where cost-positioning limits specification creep toward premium materials.
- Foam:Open-cell polyurethane cores ranging from 3mm to 12mm thickness provide the primary NVH absorption layer in multi-layer headliner composites. Electric vehicle manufacturers in the United States are compressing foam thickness specifications to accommodate battery thermal management hardware while demanding equivalent acoustic performance.
- Vinyl:Thermoplastic polyolefin surfaces offer moisture resistance and simplified cleaning protocols for commercial vehicle and fleet applications. Specified most heavily in light trucks and delivery vans serving North American logistics operators.
- Leather:Genuine or synthetic hide surfaces with perforated acoustic patterns command concentrated procurement in luxury SUVs and executive sedans. Stuttgart-area OEMs maintain the strictest grain consistency and stitching specifications.
Mature deployment sits with fabric-foam laminates. Newer deployment is concentrated in leather-trimmed variants with embedded capacitive controls.
End User:
Direct procurement relationships are consolidating around vehicle manufacturers, compressing traditional tiered supply hierarchies.
- OEMs:Volkswagen Group, Toyota Motor Corporation, and BYD are awarding design-to-delivery contracts directly to acoustic component specialists rather than routing through interior module integrators. This pattern is most visible in Germany and China.
- Tier-1 Suppliers:Grupo Antolin and Lear Corporation maintain integrated manufacturing footprints across multiple continents to serve regional assembly plants with localized foam-in-place production.
- Aftermarket Providers:Independent distributors service collision repair and vehicle refurbishment channels with pattern-matched replacement headliner assemblies. Margins compress relative to OE contracts due to inventory fragmentation.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities in India and Mexico are establishing regional sourcing relationships to satisfy domestic content requirements.
Established relationships anchor tier-1 supply. Emerging direct procurement is accelerating between OEMs and specialized acoustic engineers.
Material:
Petrochemical feedstock volatility is driving substitution experiments across synthetic and natural fiber categories.
- Polyester:Recycled polyethylene terephthalate fibers are qualifying for EU end-of-life vehicle directive credits, positioning compliant suppliers for circular-economy procurement mandates in European production.
- Polyurethane:TDI and MDI-based foam systems face formulation pressure from REACH restrictions on halogenated flame retardants and China's GB standards for cabin air quality. Suppliers are accelerating shifts toward phosphorus-based alternatives.
- Cotton:Natural fiber substrates serve niche applications in luxury vehicles marketing sustainable interior narratives. Limited scale constrains cost competitiveness against synthetic alternatives.
- Nylon:High-tenacity polyamide fabrics deliver abrasion resistance for commercial vehicle headliners subject to heavy operator use. Specified in heavy-truck programs where durability outweighs acoustic optimization.
Volume concentration remains with polyurethane. Steepest expansion trajectory belongs to recycled polyester qualifying for regulatory credits.
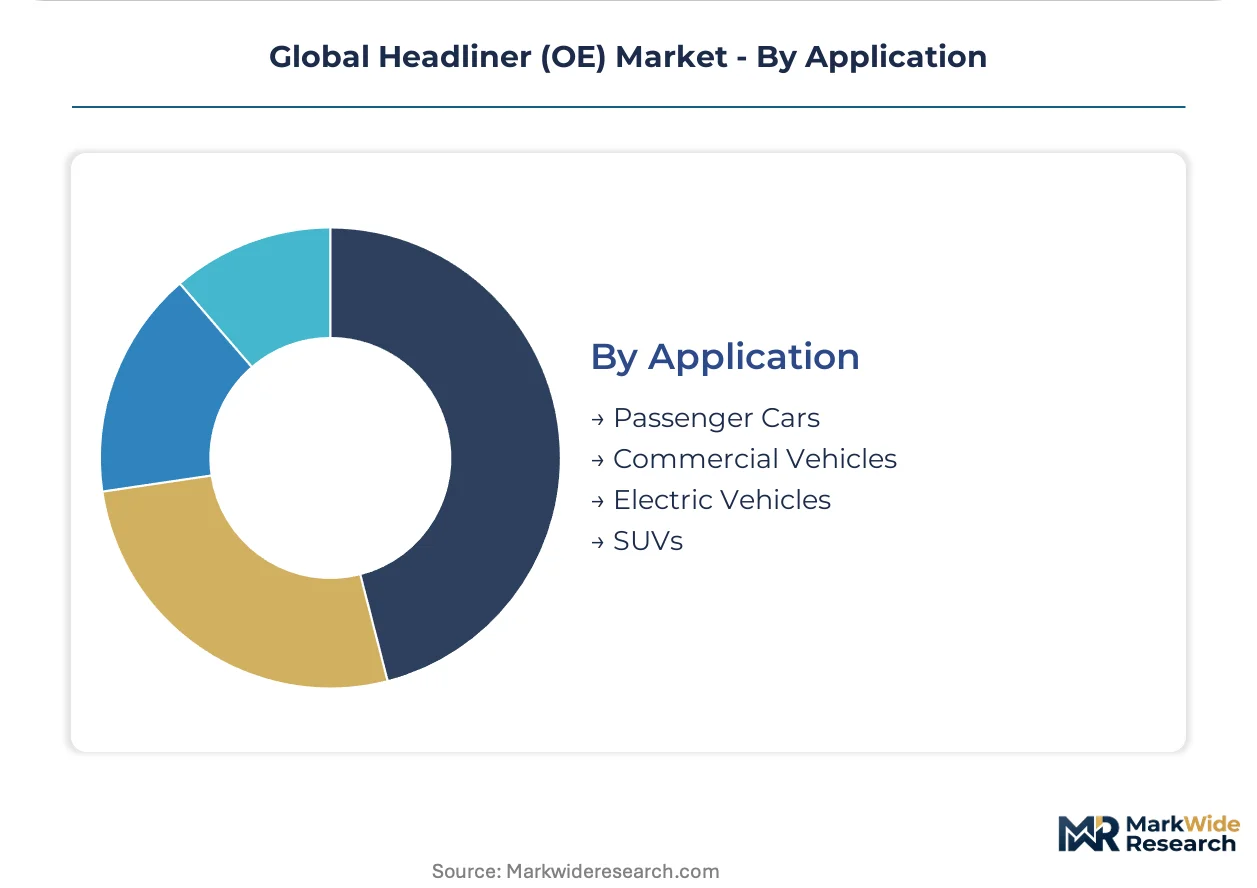
Application:
Roof packaging constraints and thermal management requirements are fragmenting specification pathways across vehicle architectures.
- Passenger Cars:Sedan and hatchback programs sustain the highest unit volumes for conventional foam-fabric headliner configurations. Production clusters around Shanghai and Detroit serve mass-market demand.
- Commercial Vehicles:Heavy-truck and van specifications prioritize fire-resistance compliance, with some segments specifying aluminum honeycomb structural panels in place of polymer-based alternatives.
- Electric Vehicles:Battery packaging and panoramic glass roof designs are compressing headliner thickness while expanding thermal-acoustic performance requirements. Phase-change material integration represents the fastest-moving specification tier.
- SUVs:Premium and luxury sport utility vehicles command the highest per-vehicle headliner value content through leather surfaces, ambient lighting integration, and active noise cancellation hardware.
Conventional deployment dominates passenger car assembly. Technical innovation is concentrating in electric vehicle platforms with integrated thermal management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Headliner procurement concentrates in Germany, China, and the United States where premium passenger car production clusters around Stuttgart, Shanghai, and Detroit. Electric vehicle manufacturers in these markets are compressing roof packaging specifications while expanding thermal-acoustic performance requirements.
Germany
Stuttgart-area OEMs maintain strict grain consistency and stitching specifications for leather-trimmed headliners in luxury SUVs and executive sedans. ECHA's REACH restrictions on halogenated flame retardants are accelerating formulation shifts toward phosphorus-based alternatives in polyurethane foam cores. Volkswagen Group has established direct material qualification relationships with acoustic component engineers, bypassing traditional tiered supply hierarchies.
China
Shanghai serves as the dominant production cluster for mass-market passenger car headliner volumes serving compact and mid-size sedan programs. SAMR enforcement of GB standards for cabin air quality is disqualifying high-VOC adhesive systems from domestic vehicle programs. BYD and other battery-electric platform specialists are awarding design-to-delivery programs directly to headliner specialists rather than routing through interior module integrators.
United States
Detroit-area assembly plants sustain conventional foam-fabric headliner volumes while premium SUV programs drive specification toward thicker foam constructions with integrated active noise cancellation hardware. EPA National Emission Standards for Hazardous Air Pollutants are tightening permissible VOC thresholds from interior materials. Electric vehicle manufacturers with panoramic glass roofs are specifying embedded microphone arrays and transducer modules most aggressively.
India
Domestic OEM assembly expansion around Chennai and Pune is creating import-substitution opportunities for headliner module suppliers establishing regional foam-in-place manufacturing. BIS standards for automotive interior materials are converging with global emission benchmarks. Toyota Kirloskar Motor and Maruti Suzuki are localizing procurement relationships to satisfy domestic content requirements in premium passenger car segments.
Mexico
Assembly plants serving North American logistics operators specify vinyl-surfaced headliners for light trucks and delivery vans requiring moisture resistance and simplified cleaning protocols. Grupo Antolin leverages its integrated manufacturing footprint across Spain and Mexico to serve both European and North American assembly plants. Contract manufacturers in the Bajío Region are establishing regional sourcing relationships to support just-in-time delivery requirements.
Global Headliner (OE) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue thermal-functional composites and smart surface integration. The vendor base clusters around three strategic archetypes: integrated interior module specialists with captive OEM relationships, independent acoustic component engineers serving direct EV platform contracts, and regional foam-in-place fabricators capturing import-substitution opportunities. Dominant competitive moves include geographic co-location with assembly plants and qualification for circular-economy procurement mandates under EU end-of-life vehicle directives.
Within the integrated specialist tier, Grupo Antolin and Lear Corporation exemplify multi-continental manufacturing footprints designed to serve regional assembly plants with localized production. Toyota Boshoku Corporation occupies a position as a captive supplier structure anchored to its parent OEM while competing for third-party EV platform business. These three entities represent distinct competitive positioning vectors: geographic reach, captive supply integration, and hybrid captive-competitive models.
| Leading Market Players |
|---|
| Grupo Antolin |
| Toyota Boshoku Corporation |
| IAC Group |
| Lear Corporation |
| Motus Integrated Technologies |
| Howa Co., Ltd |
| UGN, Inc. |
| Freudenberg Performance Materials |
| Adient plc |
| Others |
Supply Flow & Price Mechanics
Electric vehicle OEM procurement consolidation around direct sourcing contracts is forcing tier-1 suppliers to absorb tooling amortization costs while compressing foam core margins, creating a bifurcated pricing environment where volume-scale fabric-foam laminates face relentless cost pressure and leather-trimmed premium variants retain pricing power through specification complexity.
Pricing Analysis
Volume-scale fabric-foam configurations trade at thin margins serving high-unit compact and mid-size sedan programs, while leather-trimmed variants for Stuttgart-area luxury SUVs command substantial premiums through grain consistency requirements and integrated ambient lighting. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and thermal-acoustic performance tier. Cost compression in polyurethane foam cores is intensifying because propylene oxide and TDI feedstock volatility squeezes suppliers without backward integration. Fleet operators and commercial vehicle assemblers exhibit highest price sensitivity, whereas premium EV platforms prioritize thermal-functional specifications over unit cost.
Supply Chain Analysis
Freight costs from Asian polyol and TDI production centers to European and North American foam-in-place plants represent a structural margin drag, incentivizing regional manufacturing co-location. Supply concentrates in Germany, China, and Mexico where Grupo Antolin and Lear Corporation maintain integrated footprints. Raw material flows draw from Saudi Arabian petrochemical complexes for polyol feedstocks and Belgian chemical plants for phosphorus-based flame retardant formulations. Single-source vulnerability sits with specialized acoustic simulation talent concentrated among limited NVH engineering pools. Distribution runs through just-in-time module delivery direct to OEM assembly plants, bypassing traditional tier-2 warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acoustic engineering talent scarcity and deep-draw thermoforming die requirements create supply-side bottlenecks that prop pricing for qualified suppliers, particularly as electric vehicle platforms multiply thermal-functional specification tiers faster than supplier development timelines can match.
For Market Incumbents: Anticipate aluminum honeycomb substitution in commercial vehicle segments by accelerating recyclable mono-material qualification for EU end-of-life vehicle directive credits. Defensive capacity addition in Chennai and Pune captures India passenger vehicle localization momentum. Backward integration into petrochemical inputs buffers polyol feedstock volatility.
For New Entrants and Emerging Players: Direct digital channels to EV platform specialists in Germany and China bypass entrenched tier-1 relationships. White-space concentrates in phase-change material integration for battery thermal management and smart surface capacitive controls. Target acoustic component engineering contracts for BYD and Volkswagen Group direct procurement programs.
For Investors and Strategic Acquirers: The window for entry favors independent acoustic component engineers with NVH simulation capabilities and active noise cancellation hardware integration expertise. Long-term viability hinges on qualification for circular-economy procurement mandates and thermal-functional composite patents. Watch for OEM direct sourcing contract announcements as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Design Qualification | EU end-of-life vehicle directive credits position suppliers for circular-economy mandates. |
| Phase-Change Material Integration | Battery thermal management specifications from BYD and Volkswagen Group create new revenue tiers. |
| Regional Foam-in-Place Manufacturing | Chennai and Pune assembly expansion satisfies India's domestic content requirements. |
| Acoustic Simulation Talent Acquisition | Predictive NVH modeling capabilities compress supplier development timelines for EV platforms. |
| Smart Surface Electronics Integration | Capacitive controls embedded in decorative layers converge electronics and trim competencies. |
Methodological Framework
SEC 10-K filings, IHS Markit vehicle production databases, and customs/trade data formed the secondary backbone, cross-referenced with primary interviews involving OEM platform engineers, tier-1 supplier procurement leads, acoustic component R&D directors, and aftermarket distribution channel heads. Bottom-up triangulation across material-grade segmentation and top-down validation against regional production clusters ensured analytical coherence.
Historical trendline analysis of polyurethane foam pricing, adhesive formulation shifts, and electric vehicle platform rollouts informed the projection framework. Segmentation dimensions modeled include material substrate, vehicle architecture, thermal-functional performance tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume forecasts and value-per-vehicle content trajectories across the analysis window, incorporating battery thermal management integration rates and REACH-compliant formulation adoption curves.
The model holds under stable petrochemical feedstock availability and continued EV platform expansion; deviation in polyol supply disruptions or aluminum honeycomb substitution acceleration would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context and supplier qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Automotive Intelligent Lighting System Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Windscreen Washer System Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Automotive Grab Handle Market