
 Car Wash Franchise Market | 2026-2036
Car Wash Franchise Market Size, Share, and Industry Trends Forecast 2026-2036
Car Wash Franchise Market Insights
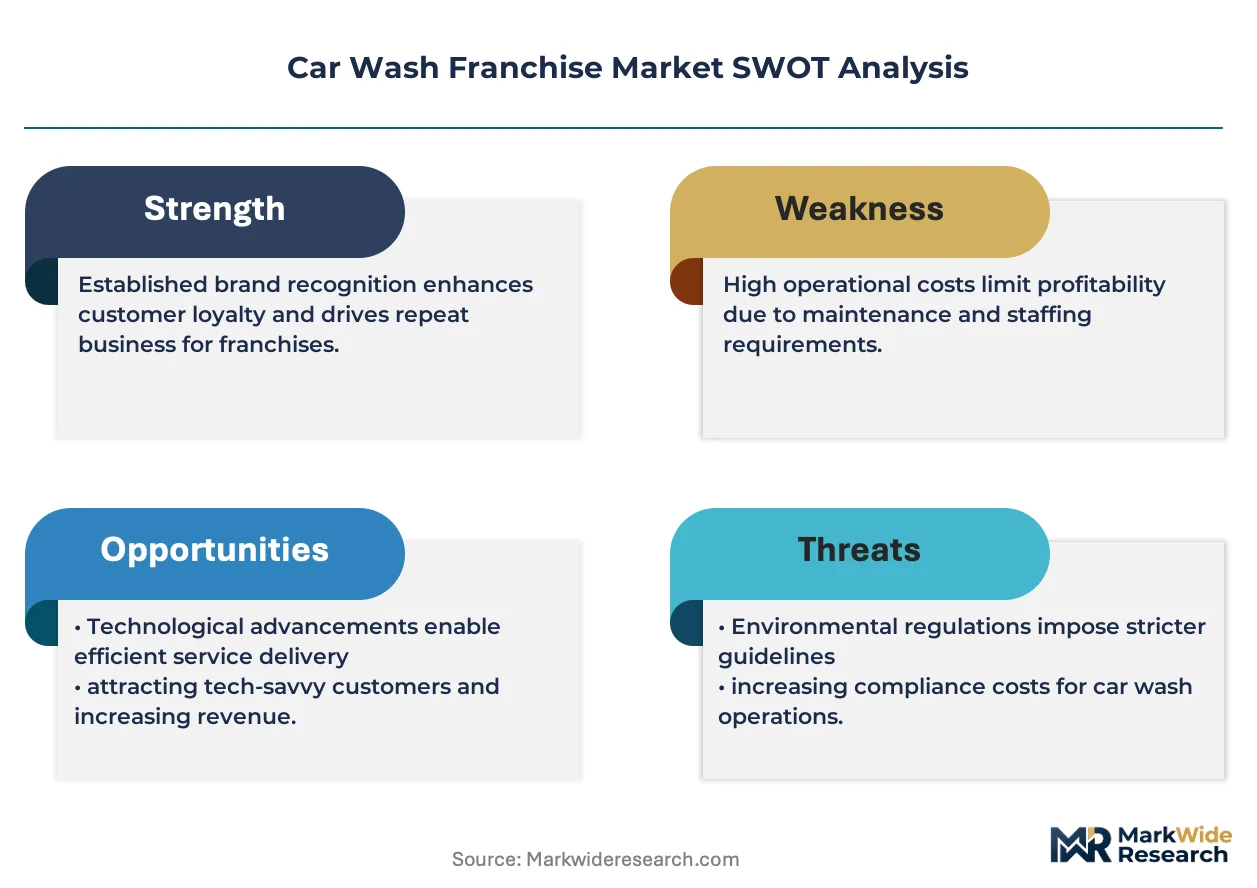
Fleet operator concentration is rebalancing as logistics companies consolidate vendor relationships around national accounts. Tommy's Express Car Wash leverages its modular build format to secure multi-unit development agreements with fleet-focused investors. Mister Car Wash sustains the largest installed base of express tunnels, anchoring its position through subscription membership density in suburban corridors. Green Shine differentiates through eco-certified waterless operations that appeal to corporate sustainability procurement criteria.
A car wash franchise denotes a licensed business model delivering automated or assisted vehicle cleaning services through standardized equipment, chemical formulations, and operational protocols. Tunnel systems typically process vehicles in under three minutes using conveyor-based arch configurations with presoak, high-pressure rinse, and forced-air drying stages. Exterior wash and subscription plans represent the dominant revenue pairing, with exterior tunnels generating the highest throughput per labor hour and subscriptions locking in predictable recurring revenue that supports capital-intensive equipment financing. Touchless systems and waterless solutions capture growing share among environmentally regulated municipalities and drought-prone service territories where discharge permits restrict traditional friction washing.
EPA effluent guidelines under the Clean Water Act shape site-level engineering requirements for water treatment and discharge, while OSHA standards govern chemical handling protocols in tunnel and detail bay environments. State-level drought emergency declarations in California and Texas periodically trigger operational restrictions that accelerate capital deployment into reclamation and reverse osmosis systems. Stakeholders must monitor how municipal water pricing and permitting timelines affect new site economics before committing to ground-up development versus conversion of existing retail pads.
Market Dynamics
Water reclamation mandates and subscription revenue models are compressing site-level payback periods while concentrating capital deployment in high-throughput express tunnel formats.
Growth Catalysts
- Fleet consolidation:Logistics operators are consolidating vendor relationships into national accounts that favor multi-unit franchise development with standardized service level agreements.
- EPA effluent guidelines:The Clean Water Act is accelerating capital deployment into closed-loop water treatment systems that reduce municipal discharge exposure.
- Touchless tunnel technology:Laser-guided vehicle profiling and high-pressure arch configurations are expanding site throughput without friction-induced paint damage liability.
Market Restraints
- Real estate scarcity:Prime suburban corridor retail pads with sufficient vehicle stacking depth command premium lease rates that compress new entrant returns.
- Chemical input volatility:Surfactant and wax formulation costs fluctuate with petroleum derivative pricing, pressuring per-wash margin stability.
- Permitting timeline friction:Municipal water discharge permits in drought-prone jurisdictions extend pre-revenue construction phases by 6-18 months.
Strategic Opportunities
- Corporate sustainability procurement:Enterprise fleet managers with net-zero targets are prioritizing waterless and reclaimed-water operators in vendor selection criteria.
- Electric vehicle wash protocols:Battery-electric vehicle manufacturers are specifying low-pressure undercarriage cleaning standards that favor specialized tunnel configurations.
- Membership platform integration:Mobile app-based subscription management is reducing churn through frictionless billing and location-agnostic access.
Industry Challenges
- Technical workforce scarcity:PLC-programmed conveyor systems and reverse osmosis maintenance require electro-mechanical technicians that command wage premiums above general facility labor.
- Legacy equipment retrofit complexity:Existing friction-wash tunnels face structural constraints when upgrading to touchless arch configurations and water reclamation plumbing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Wash Franchise Market |
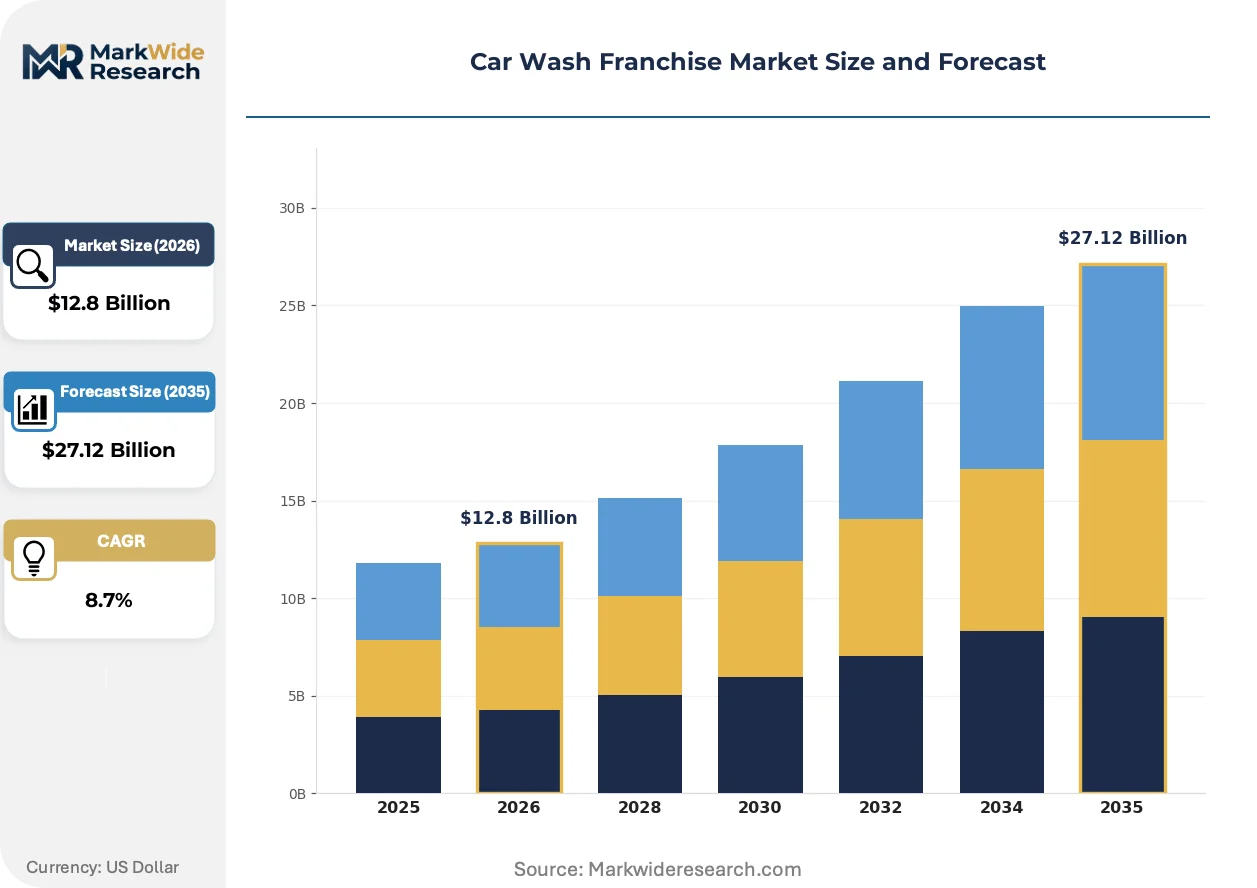
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exterior Wash, Interior Cleaning, Detailing, Engine Cleaning End User: Individual Vehicle Owners, Fleet Operators, Dealerships, Rental Services Technology: Manual Wash, Automatic Wash, Touchless Systems, Waterless Solutions Pricing Model: Pay-Per-Wash, Subscription Plans, Package Deals, Loyalty Programs |
| Companies Covered | Fleet Clean USA, Green Shine, Tommy’s Express Car Wash, Grizzly Auto Detailing, No-H2O, Mister Car Wash, Prime Car Wash, Grease Monkey, DetailXPerts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Wash Franchise Market Trends and Innovations
Automation, regulatory water stewardship, and subscription-based consumption models are converging to redefine site economics and customer retention architecture.
Laser-guided vehicle profiling systems are automating wheel alignment and body contour detection within conveyor tunnels. Express operators with 100,000-plus annual wash volumes are deploying these systems to reduce brush contact incidents and insurance exposure. The technology is automating quality consistency previously dependent on attendant judgment.
EPA effluent guidelines under the Clean Water Act are mandating tertiary treatment for sites discharging to municipal sewer systems. Operators in Texas and California are deploying reverse osmosis and biological filtration to meet total dissolved solids thresholds. Tunnel operators in these states are recapturing 80-90 percent of process water to avoid permit restrictions and volumetric surcharges.
Fleet procurement officers are unbundling wash services from bundled maintenance contracts and sourcing through centralized sustainability dashboards. National logistics operators are consolidating vendor relationships around operators with verified water reclamation certification. This pattern concentrates contract value among multi-unit franchisees with documented environmental compliance systems.
Car Wash Franchise Market Segmentation
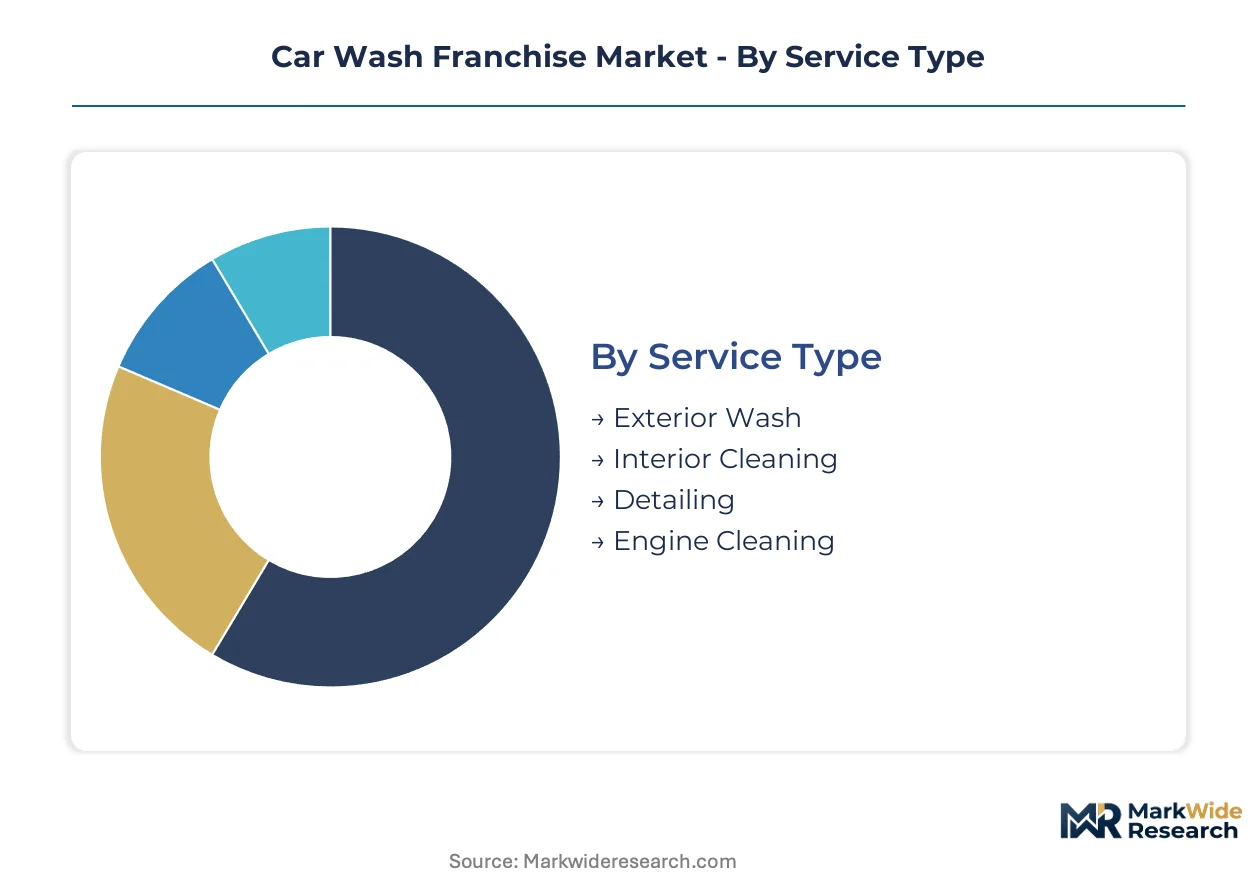
Segmentation in the car wash franchise market reveals how capital allocation, regulatory exposure, and customer lifetime value concentrate across distinct operational models. Service configuration and technology choices determine water reclamation compliance burdens, while end-user targeting shapes subscription revenue stability.
Service Type:
EPA effluent guidelines and OSHA chemical handling protocols apply differentially across service tiers, with water-intensive exterior operations facing the heaviest tertiary treatment mandates.
- Exterior Wash:Conveyor-based tunnel systems process vehicles through presoak, high-pressure rinse, and forced-air drying stages in under three minutes. Fleet operators in Texas and California are consolidating national accounts around exterior-only providers with documented closed-loop reclamation certification.
- Interior Cleaning:Vacuum extraction, surface sanitization, and odor treatment services generate higher labor intensity per revenue dollar. Demand concentrates among rental services and dealerships preparing vehicles for resale, where turnaround speed justifies premium positioning.
- Detailing:Paint correction and ceramic coating applications require skilled technician labor and specialized chemical formulations.
- Engine Cleaning:Low-pressure steam and biodegradable degreaser protocols address corporate sustainability procurement criteria for fleet maintenance contracts.
Exterior Wash sits at the top of the volume ranking, with Detailing climbing the fastest as margin-focused operators seek differentiation.
End User:
Customer concentration patterns reveal which segments anchor recurring revenue and which demand flexible capacity scaling.
- Fleet Operators:Logistics companies with national vehicle footprints are unbundling wash services from bundled maintenance contracts and sourcing through centralized sustainability dashboards. These accounts prioritize standardized service level agreements and verified water reclamation certification.
- Individual Vehicle Owners:Subscription membership density in suburban Sun Belt corridors sustains express tunnel economics. Mobile app-based billing reduces churn through frictionless location-agnostic access.
- Dealerships:Volume spikes align with new vehicle delivery cycles and certified pre-owned reconditioning programs.
- Rental Services:Rapid turnaround requirements favor exterior tunnel throughput over labor-intensive interior services.
Fleet Operators anchor the revenue base for multi-unit franchisees, while Individual Vehicle Owners deliver the steadiest subscription cash flows.
Technology:
Capital intensity and permitting complexity stratify sharply across technological approaches, with drought-prone municipalities accelerating deployment of reclamation-heavy configurations.
- Touchless Systems:Laser-guided vehicle profiling and high-pressure arch configurations eliminate friction-induced paint damage liability. These systems expand throughput in environmentally regulated municipalities where discharge permits restrict traditional brush washing.
- Automatic Wash:Conveyor-based friction tunnels with soft-cloth or foam brush configurations dominate installed base economics. Legacy equipment retrofit complexity constrains upgrades to touchless arch configurations and water reclamation plumbing.
- Manual Wash:Labor-dependent self-service bays persist in rural markets with lower real estate costs and reduced permitting scrutiny.
- Waterless Solutions:Eco-certified operations appeal to corporate sustainability procurement criteria in drought-emergency jurisdictions.
Automatic Wash retains the largest installed footprint, though Touchless Systems are expanding most quickly in regulated coastal and southwestern markets.
Pricing Model:
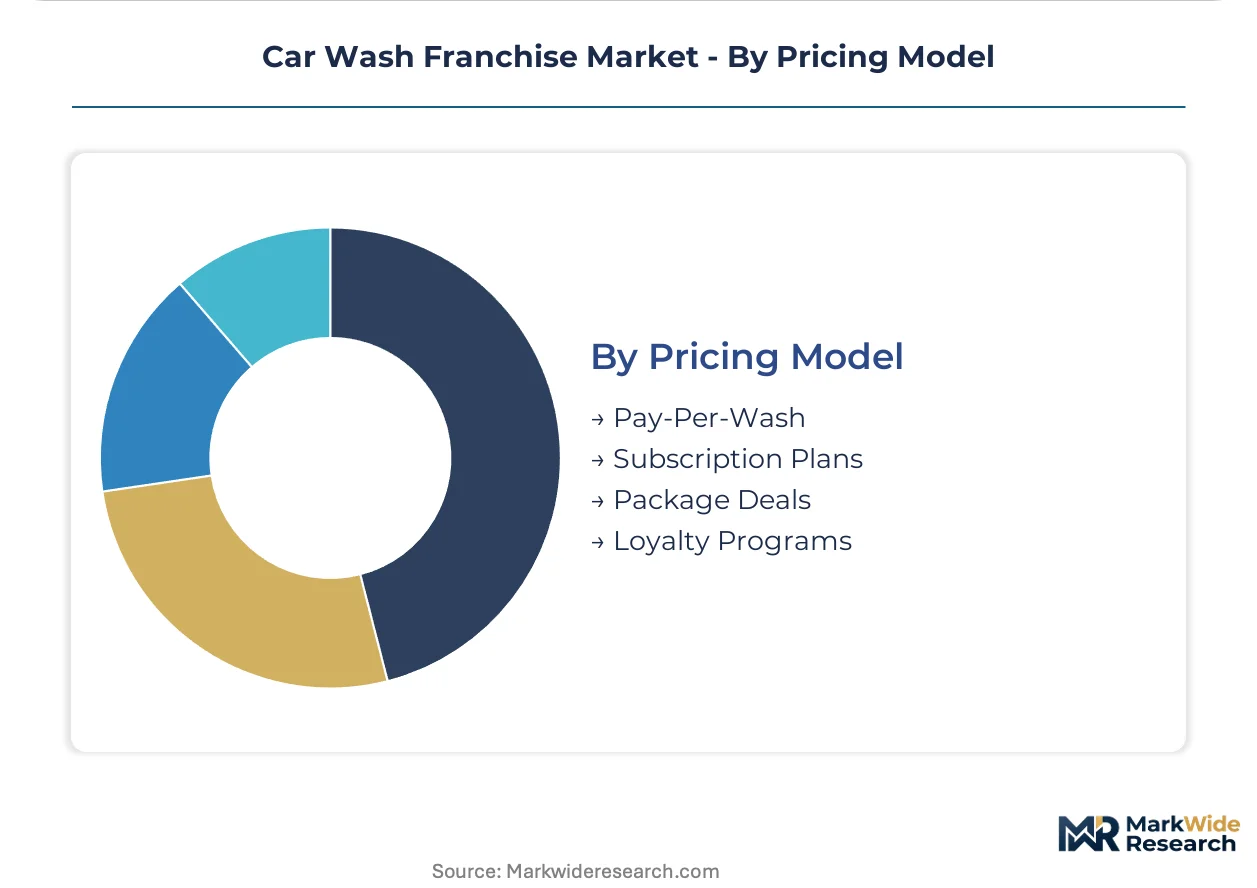
Revenue predictability and customer acquisition cost economics vary substantially across pricing architectures, with subscription density increasingly determining site valuation multiples.
- Subscription Plans:Unlimited wash memberships lock in predictable recurring revenue that supports capital-intensive equipment financing. Mobile platform integration reduces churn through frictionless billing and cross-location access privileges.
- Pay-Per-Wash:Transactional pricing captures occasional users and tourists but suffers from weather-dependent demand volatility. This model concentrates in highway-adjacent locations with high transient vehicle traffic.
- Package Deals:Bundled service combinations of exterior, interior, and detailing tier price points to vehicle condition and owner commitment levels.
- Loyalty Programs:Point accumulation and tiered reward structures seek to convert pay-per-wash customers toward subscription commitment.
Subscription Plans command the highest strategic priority among growth-focused operators, with Package Deals gaining traction as a conversion pathway from transactional to recurring relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas franchisees process higher annual wash volumes than Canadian operators due to Sun Belt climate conditions and extended operating seasons. EPA water reclamation mandates apply differentially across jurisdictions, with southwestern states facing the most stringent discharge permit requirements. Municipal water pricing and permitting timelines remain the critical variables determining new site economics.
United States
Fleet operators in Texas and California are consolidating vendor relationships around multi-unit franchisees with documented closed-loop reclamation certification. EPA effluent guidelines under the Clean Water Act mandate tertiary treatment for sites discharging to municipal sewer systems. The Dallas-Fort Worth metroplex anchors the highest concentration of express tunnel developments, where operators deploy reverse osmosis systems to recapture process water.
Canada
Seasonal demand compression limits exterior tunnel throughput in prairie provinces, pushing operators toward diversified service portfolios. Environment Canada water quality guidelines govern discharge parameters for sites operating near sensitive watersheds. The Greater Toronto Area concentrates the most sophisticated water reclamation installations, where municipal stormwater management requirements accelerate capital deployment into closed-loop systems.
Germany
Stringent EU environmental standards and high labor costs favor automated touchless configurations over labor-intensive detailing operations. The Water Framework Directive and REACH chemical regulations constrain surfactant formulations and discharge thresholds. Industrial clusters around Stuttgart and Munich host franchisees serving premium vehicle segments with specialized ceramic coating protocols.
Australia
Prolonged drought cycles in New South Wales and Queensland drive municipal water restrictions that accelerate waterless solution adoption. State-level environmental protection agencies enforce discharge permits that favor reclamation-heavy tunnel configurations. Sydney's suburban corridor sustains the highest subscription membership density, with operators integrating mobile platform billing to reduce customer churn.
United Arab Emirates
Desert climate conditions and dust accumulation sustain premium pricing for frequent exterior washing despite high ambient temperatures. Dubai Municipality environmental regulations mandate water recycling for commercial wash facilities in designated sustainability zones. The emirate's logistics corridor concentrates fleet wash contracts serving international shipping and last-mile delivery operators.
Car Wash Franchise Market Competitive Landscape
United States operators anchor the high-throughput express tunnel tier; European specialists hold positions in waterless and eco-certified service segments. The vendor base stratifies across three archetypes: national multi-unit developers with standardized build formats, regional fleet-focused operators with sustainability certifications, and technology licensors providing modular equipment packages. Competitive moves concentrate on multi-unit development agreements with fleet-focused investors and certification-driven procurement positioning for corporate accounts.
Within the national multi-unit developer tier, Tommy's Express Car Wash and Mister Car Wash exemplify scale-driven positioning through modular build formats and subscription membership density. Green Shine occupies a distinct niche representing waterless and eco-certified operational archetypes that align with corporate sustainability procurement criteria. These three entities collectively illustrate how franchise systems differentiate through capital deployment models, environmental compliance positioning, and customer retention architecture rather than service variation alone.
| Leading Market Players |
|---|
| Fleet Clean USA |
| Green Shine |
| Tommy's Express Car Wash |
| Grizzly Auto Detailing |
| No-H2O |
| Mister Car Wash |
| Prime Car Wash |
| Grease Monkey |
| DetailXPerts |
| Others |
Pricing and Supply Chain Analysis
Backward integration into water reclamation equipment manufacturing anchors both supply security and pricing power for multi-unit franchisees facing EPA discharge mandates. Captive production of reverse osmosis systems and biological filtration units insulates operators from third-party equipment lead times while supporting premium positioning in sustainability-certified procurement channels.
Pricing Analysis
Capacity additions in Texas and California are reshaping price floors as franchisees deploy high-throughput express tunnels with documented closed-loop certification. Three-tier pricing structure across premium unlimited memberships, standard per-wash transactions, and economy fleet contracts captures divergent buyer willingness-to-pay. Cost compression in the standard tier intensifies because chemical input volatility erodes per-wash margins. Individual vehicle owners exhibit highest price sensitivity to subscription increases, while fleet procurement officers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Reverse logistics for conveyor system refurbishment and PLC component remanufacturing flow through regional equipment depots in Ohio, Michigan, and Illinois. Manufacturing concentration in Germany, China, and the United States supplies laser-guided vehicle profiling systems and high-pressure arch configurations. Raw material dependencies span petroleum-derived surfactants, stainless steel tunnel framing, and semiconductor chips for automation controls. Single-source vulnerability in laser sensor modules from German specialists creates procurement risk. Distribution runs through authorized equipment distributors with field service technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in car wash franchising rests on water reclamation cost-down curves and the shift toward premium unlimited subscription tiers with lower churn profiles.
For Market Incumbents: Acquire underperforming suburban corridor sites with deep vehicle stacking capacity to block emerging multi-unit developers. Consolidate vendor relationships around national surfactant suppliers with volume-based pricing tiers. Defensive moves must address touchless technology substitution threatening legacy friction-wash installed bases. Certification investment in EPA-compliant tertiary treatment systems anchors procurement positioning against sustainability-focused fleet accounts. For New Entrants and Emerging Players: The price-point gap between premium unlimited memberships and pay-per-wash transactions creates white-space for mid-tier hybrid models with bundled service credits. Target drought-emergency jurisdictions in Arizona and Nevada where water discharge restrictions accelerate demand for certified reclamation operators. Fleet-focused sustainability procurement channels offer the most penetrable entry vector, with mobile app-based subscription management as the critical go-to-market differentiator. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional operators lack capital to retrofit legacy tunnels with touchless configurations and closed-loop plumbing. Long-term viability favors multi-unit developers with standardized modular build formats and documented environmental compliance systems. Acquisition target archetypes include regional fleet specialists with verified water reclamation certification and underutilized real estate positions in Sun Belt growth corridors. Monitor municipal water pricing trajectories and permitting timeline extensions as inflection indicators for site economics deterioration.| Strategic Initiative | Industry Significance |
|---|---|
| Water Reclamation Certification Program | EPA compliance documentation unlocks fleet procurement contracts with sustainability mandates. |
| Touchless Tunnel Technology Deployment | Laser-guided profiling systems reduce insurance exposure and expand throughput in regulated municipalities. |
| Mobile Platform Integration | App-based subscription management reduces churn through frictionless billing and location-agnostic access. |
| Multi-Unit Development Agreement | Standardized modular build formats accelerate site rollout for fleet-focused investors. |
| Backward Integration into Equipment | Captive production of reverse osmosis systems insulates against third-party supply constraints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured franchise development executives, municipal water permitting officers, fleet procurement managers, and equipment manufacturer technical directors. Secondary validation drew from EPA effluent guideline filings, state-level drought emergency declarations, SEC 10-K disclosures from publicly traded operators, and municipal water utility rate schedules. Bottom-up site economics modeling triangulated against top-down market sizing from franchise disclosure documents.
Segment-weighting approaches distributed value and volume across service type, technology configuration, end-user category, and regional regulatory cluster dimensions. CAGRs derived from historical throughput data and subscription membership growth trajectories, with adjustments for permitting timeline friction and water pricing volatility. Forecast inputs incorporated express tunnel capacity utilization curves and fleet contract renewal rates.
Caveats apply where EPA regulatory amendments or state-level drought emergency declarations could materially shift the outlook for new site development economics. Practitioners should monitor municipal discharge permit backlogs and surfactant input cost indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Automotive Digital Services Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Automotive Subscription Services Market
Automotive Services
Auto Leasing Services Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Car Subscription Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Vehicle Subscription Market
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
Automotive MRO Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Americas MAP Market
Automotive Services
US Quick Lube Equipment Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Motorsports Market