
 Motorsports Market | 2026-2036
Motorsports Market Size, Share, and Industry Trends Forecast 2026-2036
Motorsports Market Intelligence
Multi-source aerodynamic component procurement is restructuring how top-tier teams manage wind tunnel programs and composite manufacturing. Ferrari S.p.A. sustains in-house carbon fiber layup capabilities at its Maranello facility, preserving design secrecy for Formula One chassis. Mercedes-Benz leverages dual-source hybrid powertrain partnerships to de-risk supply during regulation transitions. Red Bull Racing anchors its competitive edge through exclusive aerodynamic collaborations with sister engineering entities.
Motorsports encompasses organized competitive racing with purpose-built vehicles governed by technical regulations specifying minimum weight, displacement limits, and safety cell construction. The discipline serves as a validated testbed for automotive propulsion, materials science, and driver assistance systems before highway deployment. Circuit Racing commands the largest revenue pool through multi-year broadcasting agreements and premium hospitality infrastructure. Off-Road Racing generates accelerating sponsorship interest as automotive brands seek authenticity in utility and all-terrain segments. Lightweight Materials technology concentrates margin capture among specialized composite suppliers serving prototype and limited-production race vehicles.
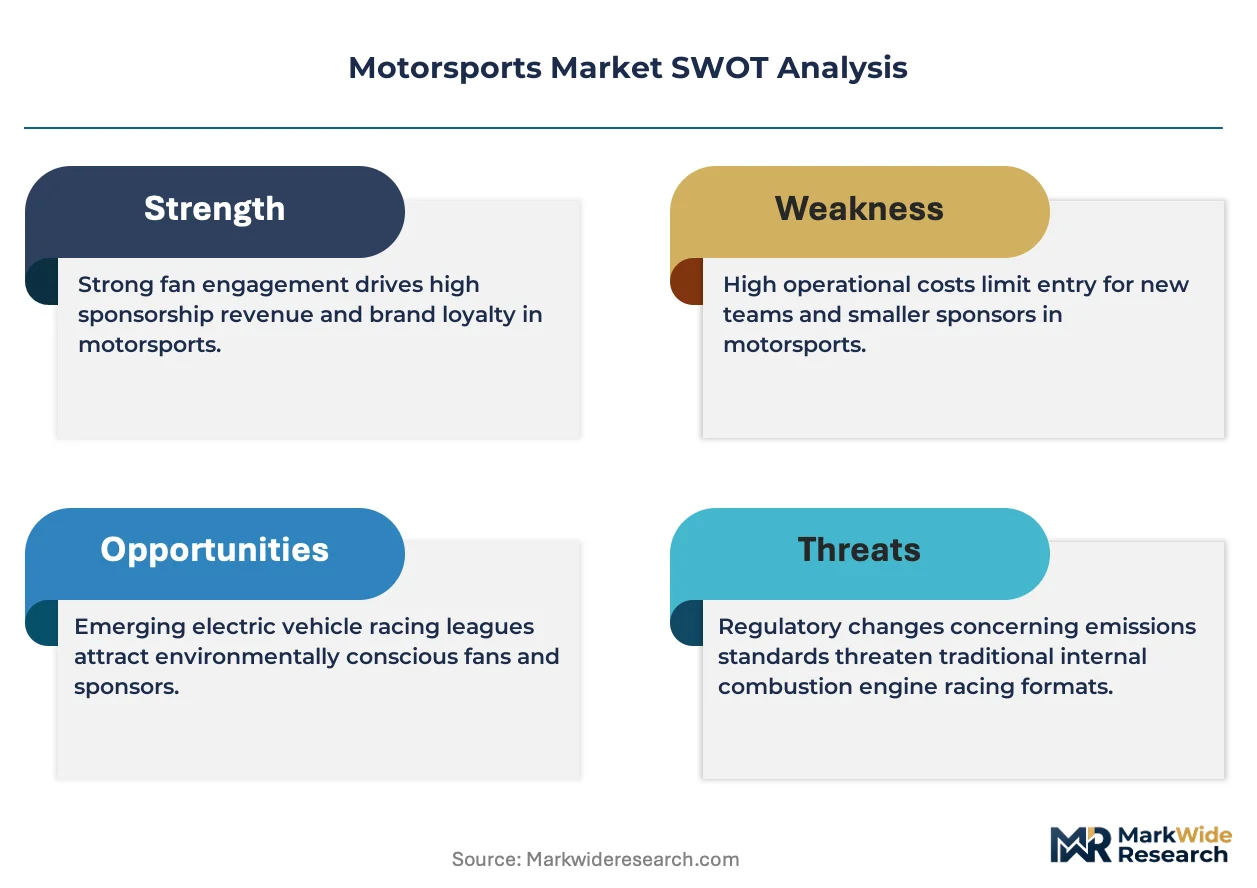
The FIA, EPA, and EU Green Deal collectively constrain combustion engine specifications while mandating sustainable fuel percentages and emissions disclosure. These frameworks compel manufacturers to redirect R&D expenditure toward electrified architectures and synthetic fuel certification. Stakeholders must monitor regulatory divergence between European sustainability mandates and American series-specific rulebooks when allocating capital across racing portfolios.
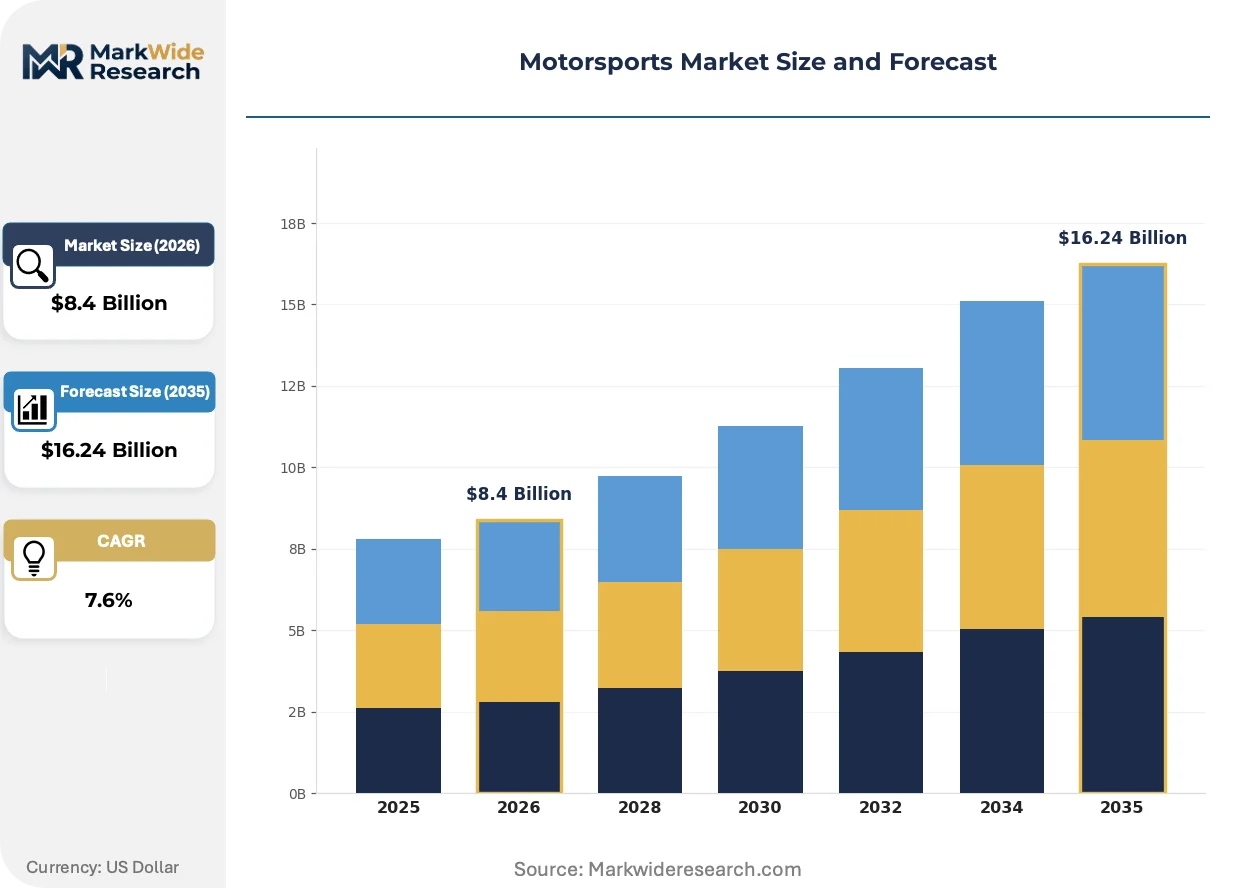
Market Dynamics
The FIA's sustainable fuel mandate and powertrain parity rules are forcing manufacturers to reallocate R&D budgets from combustion refinement to hybrid architectures and synthetic fuel certification, compressing development cycles while elevating supplier technical barriers.
Growth Catalysts
- EU Green Deal Compliance:The EU Green Deal's emissions disclosure requirements push manufacturers to fund motorsports programs as public testbeds for electrified drivetrains, converting regulatory pressure into series investment.
- Broadcast Platform Expansion:Streaming services targeting viewers under 35 are commissioning exclusive behind-the-scenes content, expanding addressable audience for sponsorship monetization beyond traditional linear television.
- Japan:Domestic automotive conglomerates are redirecting marketing spend from auto shows to Super GT and Formula E participation, leveraging home circuit presence for brand authenticity among domestic buyers.
Market Restraints
- Carbon Fiber Supply Concentration:Toray Industries and Hexcel Corporation control aerospace-grade precursor supply, exposing race teams to allocation rationing when commercial aviation demand surges.
- EPA Tier 4 Friction:The EPA's particulate matter standards for compression-ignition engines force off-road series to adopt costly after-treatment systems, elevating privateer entry costs.
- Electrification Skill Gap:The transition from mechanical to high-voltage powertrain engineering outpaces vocational training pipeline output, constraining team technical staffing.
Strategic Opportunities
- India:The country's PLI scheme for automotive manufacturing creates incentive structures for OEMs to establish regional racing series as brand-building infrastructure.
- Synthetic Fuel Certification:FIA-mandated sustainable fuel percentages position early certifiers to supply multiple series, capturing margin from fuel system recalibration services.
- Gamified Broadcast Integration:Real-time telemetry overlays and predictive analytics are penetrating streaming platforms, opening subscription revenue streams distinct from traditional advertising.
Industry Challenges
- Homologation Timeline Compression:FIA regulatory cycles now outpace traditional 24-month vehicle development programs, forcing concurrent engineering workflows that elevate prototype failure rates.
- High-Voltage Safety Certification:Technician licensing for battery-electric powertrains requires specialized facilities and training curricula that smaller teams cannot self-fund.
- IP Fragmentation Across Powertrain Partnerships:Shared hybrid system development between OEMs and racing divisions creates unresolved ownership disputes over derived road-car patents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorsports Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.24 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Motorcycles, Go-Karts, Rally Cars, Touring Cars Event Type: Endurance Racing, Circuit Racing, Off-Road Racing, Drag Racing Technology: Hybrid Systems, Aerodynamics, Telemetry, Lightweight Materials Audience Type: General Public, Enthusiasts, Teams, Sponsors |
| Companies Covered | Ferrari S.p.A., Mercedes-Benz, Red Bull Racing, McLaren Racing, Aston Martin Racing, Hendrick Motorsports, Joe Gibbs Racing, Penske Corporation, Toyota Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorsports Market Strategic Shifts & Innovations
Synthetic fuels and battery-electric architectures are simultaneously penetrating top-tier series, creating parallel technology tracks that split manufacturer investment strategies and reshape competitive differentiation criteria.
Advanced biofuel formulations derived from agricultural waste and synthetic e-fuel processes are overtaking traditional fossil-derived racing gasoline in FIA World Endurance Championship entries. Porsche and Stellantis have committed factory programs to sustainable fuel validation, compressing the timeline for production vehicle powertrain calibration. This transition is overtaking conventional fuel supplier relationships as energy majors reposition from commodity provision to technology partnership models.
The EU Green Deal's carbon border adjustment mechanism and F-Gas Regulation are compelling European-based series to document full lifecycle emissions from logistics through on-track operation. Race organizers must now procure renewable electricity for paddock operations and mandate biofuel blends for support vehicle fleets. GT3 and touring car categories face the steepest compliance cost escalation, driving consolidation among privateer entries.
Younger demographics are consuming motorsports through fragmented digital channels rather than scheduled broadcasts, forcing rights holders to unbundle content into highlight packages, driver-focused documentaries, and esports crossover events. Formula E and Extreme E have built native streaming infrastructure that bypasses traditional broadcast intermediaries. This shift is most visible in the United States, where cable subscription attrition has collapsed Nielsen ratings for NASCAR and IndyCar among viewers under 34.
Motorsports Market Segmentation
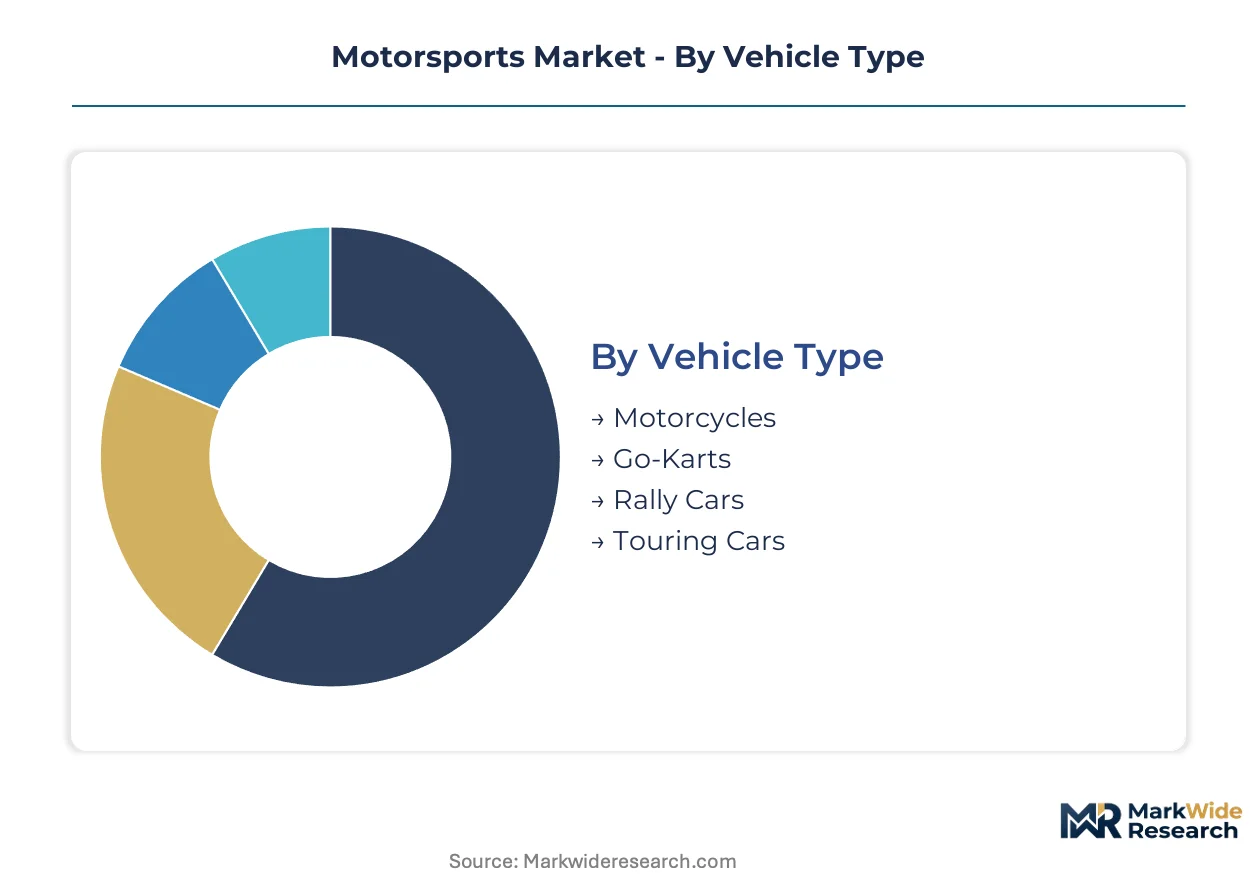
Segmentation in motorsports reveals how capital flows diverge across vehicle architectures, event formats, and technology platforms. Each dimension carries distinct procurement patterns, regulatory exposure, and audience monetization potential that shape investment allocation.
Vehicle Type:
Procurement budgets concentrate where manufacturer R&D commitments align with production vehicle roadmaps.
- Motorcycles:Prototype and production-based categories demand specialized chassis tuning for cornering dynamics. MotoGP and World Superbike draw factory investment from Japan and Italy as brand authenticity anchors. Momentum is accelerating in electric motorcycle racing as battery energy density improves.
- Rally Cars:All-terrain durability specifications require reinforced suspension geometries and protective roll cage structures. FIA homologation rules for WRC and regional championships sustain demand in Finland, France, and the United Kingdom. Regulatory pressure on combustion emissions is redirecting development toward hybrid powertrains.
- Go-Karts:Entry-level categories serve as talent identification pipelines with standardized engine regulations.
- Touring Cars:Production-based silhouettes maintain manufacturer relevance in mass-market segments.
Touring Cars lead on scale through broad manufacturer participation; Rally Cars lead on momentum as electrification expands competitive differentiation.
Event Type:
Broadcast economics and hospitality infrastructure determine which formats capture sponsorship premium.
- Circuit Racing:Purpose-built permanent facilities enable multi-day hospitality programming and predictable television production. Formula One, NASCAR, and IndyCar anchor this category through long-term media rights agreements. The United States, Italy, and Japan concentrate the highest-value venue contracts.
- Endurance Racing:Multi-hour formats stress-test reliability and fuel efficiency under sustained load. Le Mans and the FIA World Endurance Championship attract manufacturer investment as technology validation platforms. Sustainable fuel mandates are compressing development cycles for prototype powertrains.
- Off-Road Racing:Desert and stadium formats emphasize vehicle durability and driver adaptability.
- Drag Racing:Straight-line acceleration events serve as aftermarket component testbeds.
Circuit Racing dominates revenue concentration; Endurance Racing is expanding most quickly through manufacturer technology partnerships.
Technology:
Intellectual property ownership and supplier certification barriers shape competitive moats.
- Hybrid Systems:Dual-powertrain architectures integrate internal combustion with electric motor assistance. Formula One and World Endurance Championship regulations mandate specific energy recovery parameters. OEM partnerships with specialist battery suppliers are consolidating around FIA-certified cell formats.
- Lightweight Materials:Carbon fiber composite construction reduces mass while maintaining structural rigidity. Aerospace-grade precursor supply from Toray Industries and Hexcel Corporation constrains availability during commercial aviation demand surges. Ferrari and Red Bull Racing maintain in-house layup capabilities to preserve design secrecy.
- Aerodynamics:Computational fluid dynamics and wind tunnel programs govern downforce generation.
- Telemetry:Real-time data transmission enables remote performance optimization and broadcast integration.
Hybrid Systems command the largest R&D allocation; Lightweight Materials is gaining share fastest as electrification increases mass sensitivity.
Audience Type:
Monetization models diverge sharply between mass reach and specialized decision-maker access.
- Sponsors:B2B partnerships deliver brand association with technology leadership and performance credibility. Automotive suppliers and energy companies allocate budget based on media metrics and hospitality access. Streaming platform expansion is fragmenting audience measurement methodologies.
- Enthusiasts:Dedicated followers command premium subscription pricing for behind-the-scenes content and direct driver engagement. Esports crossover and gamified telemetry overlays are penetrating this segment in the United States and Japan.
- General Public:Casual viewership sustains free-to-air broadcast economics.
- Teams:Technical staff and engineering personnel drive specialized equipment procurement.
Sponsors anchor commercial revenue; Enthusiasts are climbing the fastest through digital subscription models.
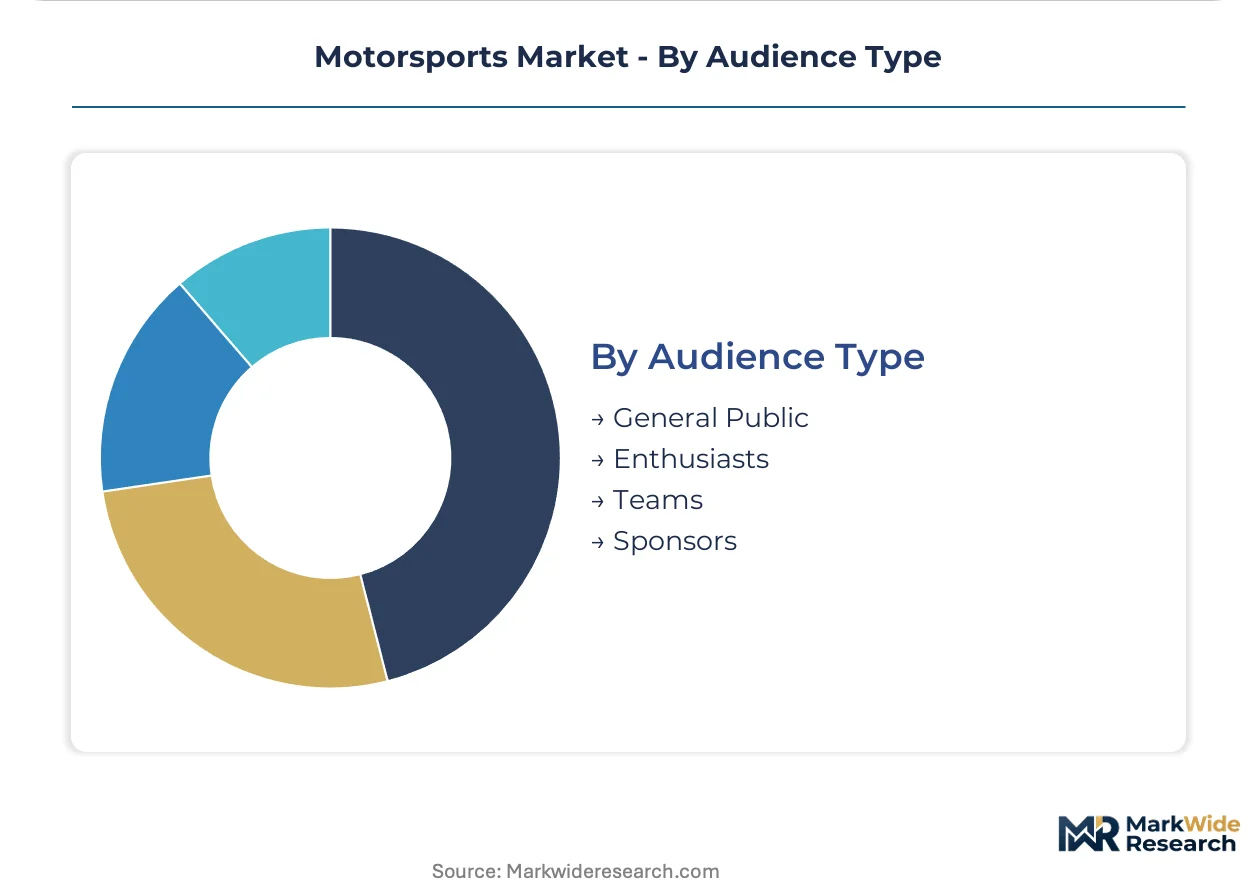
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maranello's Formula One engineering cluster anchors manufacturer investment in high-performance motorsports development. Commercial demand concentrates across the United States, Italy, and Japan where broadcast infrastructure and automotive heritage sustain series participation. Regulatory divergence between European sustainability mandates and American series-specific rulebooks is reshaping capital allocation across racing portfolios.
United States
NASCAR and IndyCar broadcasting agreements drive sponsorship revenue through multi-year media rights deals. The EPA's Tier 4 particulate matter standards elevate privateer entry costs for compression-ignition off-road categories. Charlotte, North Carolina hosts the highest concentration of race team headquarters and engine fabrication facilities.
Italy
Formula One heritage and GT racing tradition sustain manufacturer commitment to circuit-based competition. The EU Green Deal's carbon border adjustment mechanism compels series organizers to document full lifecycle emissions from logistics through on-track operation. Monza and Imola anchor the country's permanent circuit infrastructure with multi-decade hosting contracts.
Japan
Domestic automotive conglomerates redirect marketing expenditure from auto shows to Super GT and Formula E participation. METI industrial policy supports motorsports as a testbed for electrified drivetrain validation. Suzuka and Fuji Speedway concentrate manufacturer testing programs and domestic championship rounds.
Germany
Nürburgring endurance racing and DTM touring car heritage sustain supplier ecosystem density. The F-Gas Regulation and EU Green Deal emissions disclosure requirements compress development cycles for GT3 and touring car categories. Stuttgart and Munich host OEM motorsports divisions with integrated R&D facilities.
United Kingdom
Formula One technology supplier concentration and historic circuit infrastructure attract manufacturer engineering partnerships. REACH chemical compliance and CSRD sustainability reporting obligations elevate operational costs for race team facilities. Silverstone and the Motorsport Valley cluster between Oxford and Northamptonshire host composite manufacturing and aerodynamics consultancies.
Motorsports Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue electrified series and sustainable fuel certification as differentiation vectors. The vendor base concentrates around factory-backed manufacturer programs and independent racing specialists with exclusive technical partnerships. Three archetypes dominate: vertically integrated OEM divisions preserving in-house capabilities, specialist racing constructors leveraging exclusive aerodynamic collaborations, and multi-series conglomerates diversifying across circuit and off-road formats. Capacity expansion in composite manufacturing and strategic partnerships for hybrid powertrain supply represent the dominant competitive moves.
Among Italian-headquartered manufacturers, Ferrari S.p.A. exemplifies the vertically integrated archetype through captive carbon fiber layup capabilities. Mercedes-Benz represents the dual-sourcing strategy for hybrid powertrain partnerships during regulatory transitions. Red Bull Racing occupies a position within the specialist constructor tier, anchoring competitive positioning through exclusive engineering collaborations.
| Leading Market Players |
|---|
| Ferrari S.p.A. |
| Mercedes-Benz |
| Red Bull Racing |
| McLaren Racing |
| Aston Martin Racing |
| Hendrick Motorsports |
| Joe Gibbs Racing |
| Penske Corporation |
| Toyota Motor Corporation |
| Others |
Cost & Logistics Intelligence
Synthetic fuel certification requirements are compressing supplier qualification timelines while simultaneously elevating input costs for race teams navigating FIA-mandated sustainable fuel percentages. This dual pressure reshapes procurement economics as manufacturers absorb certification overhead while negotiating long-term supply agreements with energy majors repositioning from commodity provision to technology partnership models.
Pricing Analysis
Input-cost pass-through from aerospace-grade carbon fiber precursor suppliers concentrates pricing power among Toray Industries and Hexcel Corporation during commercial aviation demand surges. Three-tier pricing structure across factory-backed manufacturer programs, independent racing specialists, and privateer entries reflects certification grade and hospitality access bundling. Cost compression in privateer tiers intensifies because EPA Tier 4 after-treatment system requirements elevate entry barriers for compression-ignition off-road categories. Factory-backed programs exhibit lowest price sensitivity due to captive R&D budgets; privateer entries face acute margin pressure from homologation timeline compression.
Supply Chain Analysis
Dual-sourcing requirements for hybrid powertrain partnerships mandate that OEMs qualify multiple battery suppliers alongside specialist cell format providers, de-risking supply during regulatory transitions. Geographic supply concentration centers on Japan for carbon fiber precursor, Germany for precision powertrain components, and the United States for composite manufacturing equipment. Raw material dependencies encompass lithium-ion cell chemistry, aerospace-grade epoxy resins, and rare-earth magnetic materials. Single-source vulnerability persists around FIA-certified cell formats where OEM partnerships consolidate. Distribution runs through factory team direct procurement and racing constructor tiered supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motorsports market functions as a regulatory compounder where EU Green Deal emissions disclosure requirements and FIA sustainable fuel mandates compound manufacturer R&D commitment intensity. These frameworks transform compliance expenditure into technology validation platforms that sustain series investment across the analysis window.
For Market Incumbents: Acquire in-house carbon fiber layup capabilities to preserve design secrecy for chassis programs as Ferrari S.p.A. maintains at Maranello. Secure dual-source hybrid powertrain partnerships to de-risk supply during FIA powertrain parity rule transitions. Defensive positioning requires monitoring electrification skill gaps that constrain technical staffing for high-voltage powertrain engineering.
For New Entrants and Emerging Players: The price-point gap between factory-backed manufacturer programs and privateer economy tiers opens white-space targeting for synthetic fuel certification services supplying multiple series. India's PLI scheme for automotive manufacturing creates regional series infrastructure opportunities for brand-building OEM partnerships. Gamified broadcast integration through real-time telemetry overlays offers the most penetrable go-to-market angle for streaming-native audience monetization.
For Investors and Strategic Acquirers: Roll-up economics work for specialist racing constructors with exclusive aerodynamic collaborations because IP fragmentation across powertrain partnerships creates unresolved ownership disputes that favor consolidated technical capabilities. Long-term viability centers on five-to-ten year electrification transition windows where hybrid system R&D allocation commands largest capital deployment. Monitor FIA regulatory cycle acceleration as the inflection indicator for concurrent engineering workflow adoption and prototype failure rate elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Fuel Certification Investment | FIA-mandated sustainable fuel percentages position early certifiers to capture margin from fuel system recalibration services across multiple series. |
| Dual-Source Hybrid Powertrain Partnership | Mercedes-Benz leverages multi-supplier qualification to de-risk supply during powertrain parity rule transitions and regulatory uncertainty. |
| In-House Composite Manufacturing Capability | Ferrari S.p.A.'s captive carbon fiber layup at Maranello preserves design secrecy for Formula One chassis programs against aerodynamic IP leakage. |
| Streaming-Native Broadcast Infrastructure | Formula E and Extreme E bypass traditional broadcast intermediaries to monetize younger demographics through subscription revenue streams. |
| Regional Series Infrastructure Development | India's PLI scheme incentivizes OEMs to establish motorsports programs as brand-building anchors for domestic automotive manufacturing. |
Research Approach
Direct dialogue with Formula One team principals, GT category managers, FIA technical delegates, composite manufacturing specialists, and energy sector fuel certification leads grounded qualitative assessment in operational reality. Secondary validation drew from FIA technical regulations, EPA Tier 4 compliance filings, EU Green Deal implementation documents, and motorsports series media rights disclosures. Bottom-up segment sizing across vehicle type, event format, technology platform, and audience category triangulated against top-down manufacturer R&D expenditure allocation patterns.
Segment-level value outputs emerged from modeling procurement budget flows against homologation timeline constraints and broadcast economics across the projection horizon. Segmentation dimensions encompassed propulsion architecture, competition format, materials technology tier, and regional regulatory cluster. CAGRs derived from regression analysis of manufacturer participation rates correlated with sustainability mandate compliance cost trajectories. Forecast inputs incorporated FIA regulatory cycle acceleration patterns and streaming platform audience measurement fragmentation.
The model assumes a particular technology adoption path; alternative pathways for battery-electric powertrain penetration would alter the outlook for hybrid system R&D allocation and synthetic fuel certification demand. Deviation in FIA sustainable fuel mandate enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automatic Tire Changer Market
Automotive Services
Cab Services Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Automotive Retail Market
Automotive Services
Europe Car Wash Market
Automotive Services
GCC Car Wash Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
US Quick Lube Equipment Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Car Washing Service Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Car Rental Business Market