
 GCC Car Wash Market | 2026-2036
GCC Car Wash Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Car Wash Market Insights
Multi-source vendor contracting among fleet operators is consolidating around integrated service providers with captive water-recycling infrastructure. ENOC Group anchors its position through petroleum-retail adjacency and high-throughput tunnel locations across the Emirates. Zips Car Wash competes on subscription-based membership density and rapid bay-turn economics. Mister Car Wash differentiates through ceramic-coating add-ons and interior detailing upsells that lift per-visit revenue.
GCC car wash services encompass mechanized and manual cleaning, surface protection, and interior restoration of passenger and commercial vehicles, typically employing high-pressure water jets, biodegradable detergents, and regenerative water-filtration systems to remove contaminants while complying with arid-climate discharge limits. The primary commercial purpose centers on preserving vehicle resale value, fleet asset longevity, and brand presentation for rental and dealer inventories. Automatic wash systems dominate volume throughput in Saudi Arabia and Kuwait, while hand wash and detailing commands premium pricing from individual vehicle owners seeking paint-safe techniques. Waterless wash formulations represent the fastest-growing service type as municipalities in Qatar and Bahrain enforce seasonal hosepipe bans and commercial water-tariff escalations.
Saudi Arabia's General Authority for Meteorology and Environmental Protection and the UAE's Ministry of Climate Change and Environment enforce wastewater-discharge standards that mandate closed-loop filtration for commercial wash facilities, directly shaping capital-expenditure requirements for new entrants. Dubai Municipality's Green Building Regulations and Estidama Pearl Rating criteria incentivize water-recycling retrofits through accelerated permitting for sustainable-fit-out projects. Operators must monitor evolving municipal water-tariff structures and anticipate mandatory greywater-reuse thresholds that will determine site-level profitability and expansion feasibility across Gulf cities.
Market Dynamics
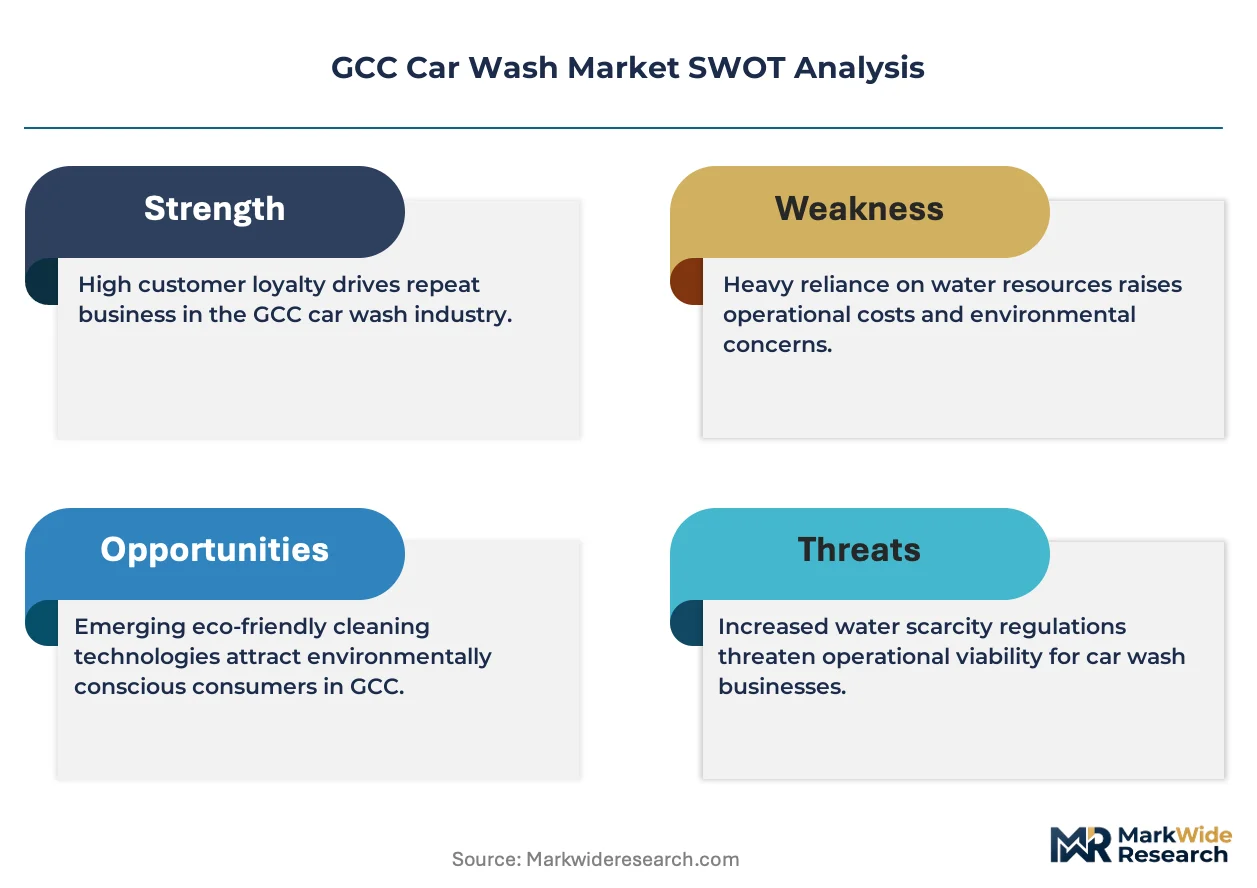
Municipal water-tariff escalations across Gulf Cooperation Council jurisdictions are forcing capital reallocation toward closed-loop filtration and waterless wash chemistry, compressing payback periods for incumbent tunnel operators while elevating barriers for new site development.
Growth Catalysts
- Estidama Pearl Rating incentives:Dubai Municipality accelerates permitting for wash facilities achieving specified sustainability benchmarks, directing developer investment toward retrofitted greywater systems.
- Commercial fleet outsourcing:Saudi logistics and rental operators are consolidating cleaning contracts with integrated service providers capable of captive water recycling at scale.
- Biodegradable surfactant chemistry:Advanced formulations reduce discharge contamination risk while maintaining cleaning efficacy under high-salinity feedwater conditions prevalent in coastal Emirates.
Market Restraints
- Desalinated water cost volatility:GCC municipal water tariffs for commercial users fluctuate with energy input costs, compressing site-level margins during summer peak-demand periods.
- Real estate concentration:Premium express tunnel locations cluster along petroleum retail corridors controlled by incumbent integrated energy retailers, limiting independent site access.
- Technical limitation in waterless application:Heavy soil loads on commercial vehicles exceed current waterless formulation efficacy, constraining serviceable addressable market for fleet segments.
Strategic Opportunities
- Bahrain and Qatar underpenetration:Manama and Doha maintain lower automatic wash density per registered vehicle than Riyadh or Dubai, presenting first-mover site acquisition potential.
- Subscription membership models:Monthly unlimited-wash programs reduce revenue volatility and improve customer lifetime value metrics for operators with sufficient bay throughput.
- Ceramic coating convergence:Surface protection upsells integrate with tunnel wash cycles, capturing margin from premium vehicle owners seeking paint preservation in abrasive desert climates.
Industry Challenges
- Skilled technician scarcity:Interior detailing and paint correction require trained labor pools that remain thin across secondary GCC cities, constraining service quality consistency.
- Legacy system integration:Retrofitting water-recycling infrastructure into operational tunnel sites demands extended downtime and coordination with municipal discharge permitting authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Car Wash Market |
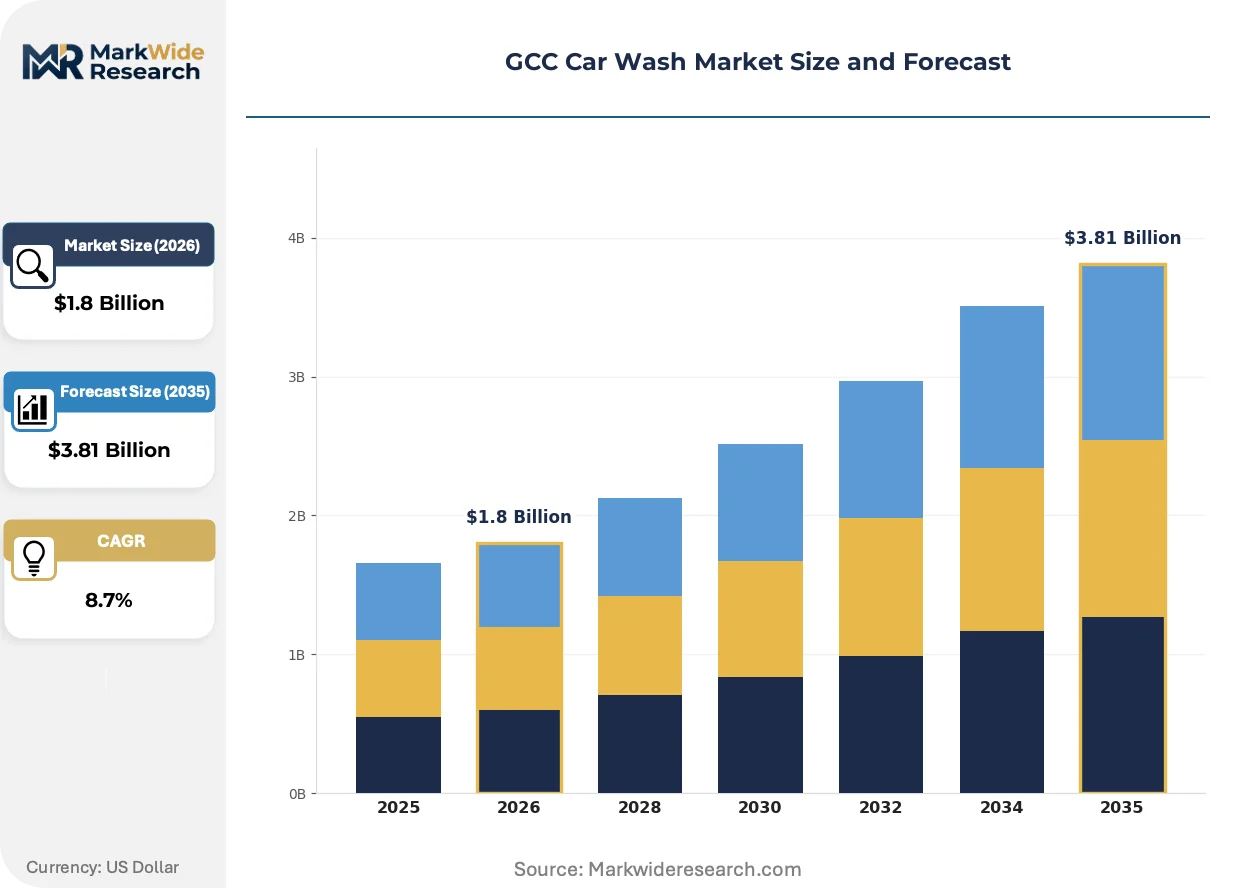
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hand Wash, Automatic Wash, Waterless Wash, Detailing End User: Individual Vehicle Owners, Fleet Operators, Car Dealers, Rental Agencies Packaging Type: Bulk Containers, Spray Bottles, Foaming Cartridges, Pouches Treatment Method: Foam Wash, Rinse, Wax Application, Environmentally Friendly Treatments |
| Companies Covered | Autobell Car Wash, ENOC Group, Zips Car Wash, Delta Sonic Car Wash, Mister Car Wash, International Car Wash Group (ICWG), True Blue Car Wash, BESTCARWASH, Quick Quack Car Wash, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Car Wash Market Trends and Innovations
Waterless wash chemistry and IoT-enabled bay management systems are converging to reshape operator economics and customer throughput across Gulf markets, with regulatory pressure accelerating technology deployment timelines.
Closed-loop water filtration is converging with real-time turbidity monitoring to enable continuous reuse without quality degradation. Tunnel operators in the UAE are deploying these integrated systems to maintain discharge compliance under tightening municipal codes. The technology is converging with automated chemical dosing controls that adjust surfactant injection based on feedwater salinity, reducing consumable waste and labor intervention.
The UAE's Ministry of Climate Change and Environment enforces wastewater-discharge standards mandating closed-loop filtration for commercial wash facilities, directly elevating capital requirements for new market entrants. Saudi Arabia's General Authority for Meteorology and Environmental Protection maintains parallel standards that shape site-level engineering specifications. Fleet operators in both jurisdictions now specify vendor compliance documentation as a mandatory contract precondition, filtering supplier pools toward integrated infrastructure providers.
Fleet procurement managers are consolidating vendor relationships around service providers offering bundled cleaning, maintenance scheduling, and telematics-linked appointment systems. This concentration displaces fragmented spot-contract arrangements prevalent five years prior. The shift is most visible among Saudi Arabia's long-haul logistics operators, where centralized procurement functions now mandate single-source accountability for vehicle presentation standards across distributed depot networks.
GCC Car Wash Market Segmentation
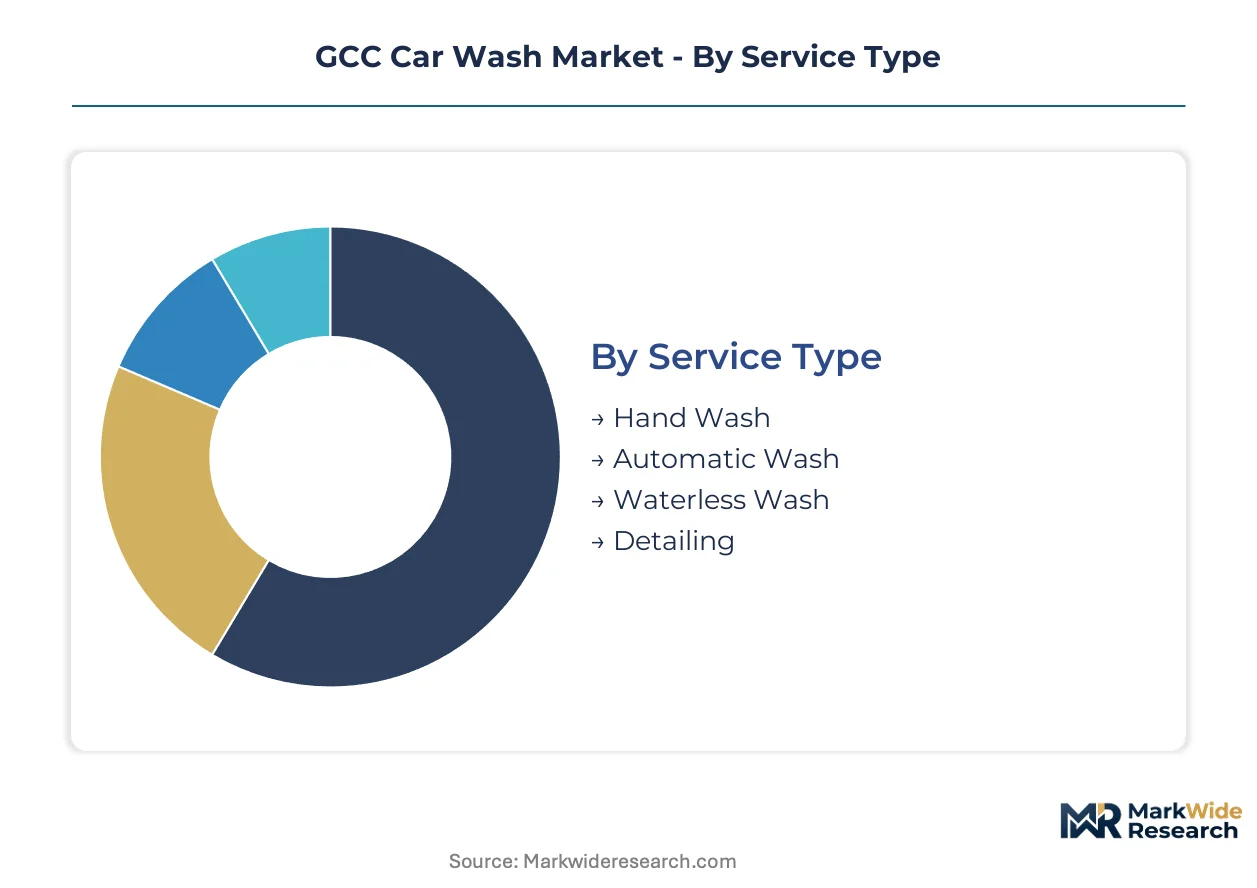
Service configuration and packaging format determine capital intensity and margin structure across Gulf markets. Water scarcity mandates and fleet procurement consolidation are reshaping which segments absorb investment and which face displacement.
Service Type:
Standalone express tunnels dominate petroleum-retail adjacency, while embedded detailing services attach to premium real estate and dealership service lanes.
- Automatic Wash:High-throughput tunnel systems with regenerative water loops process volume at petroleum retail corridors across Riyadh and Dubai. ENOC Group and integrated energy retailers control premium corridor access, compressing independent site economics during tariff escalation periods.
- Waterless Wash:Surfactant-based formulations eliminate discharge compliance burden and enable mobile service deployment. Qatar and Bahrain municipal hosepipe bans are accelerating contract uptake among fleet operators seeking depot-level cleaning without fixed infrastructure investment.
- Hand Wash:Labor-intensive techniques command premium pricing from individual owners prioritizing paint-safe methods. Technician scarcity across secondary GCC cities constrains quality consistency and expansion feasibility.
- Detailing:Interior restoration and paint correction integrate with ceramic coating upsells at premium retail locations. Ceramic protection convergence with tunnel cycles is capturing margin from desert-climate vehicle preservation demand.
Automatic Wash leads volumes today; Waterless Wash is gaining share fastest.
End User:
Procurement concentration varies sharply between fragmented individual demand and consolidated fleet contracting with sustainability compliance requirements.
- Fleet Operators:Saudi logistics and rental operators now mandate single-source accountability with captive water-recycling documentation. Centralized procurement functions are displacing fragmented spot-contract arrangements prevalent five years prior.
- Individual Vehicle Owners:Subscription membership models reduce revenue volatility for operators with sufficient bay throughput. Monthly unlimited-wash programs improve customer lifetime value metrics across Dubai and Riyadh express networks.
- Car Dealers:Inventory presentation standards require integrated cleaning with maintenance scheduling and telematics-linked appointment systems. Bundled service specifications filter supplier pools toward infrastructure-capable providers.
- Rental Agencies:Rapid turnaround requirements favor automatic wash throughput at airport-adjacent and urban hub locations. Vehicle density concentration in Dubai and Riyadh sustains dedicated facility investment.
Fleet Operators anchor contract value; Individual Vehicle Owners expand most quickly through subscription penetration.
Packaging Type:
Format selection tracks application scale and mobility requirements across fixed-site versus on-demand service models.
- Bulk Containers:Concentrated chemistry for tunnel system reservoirs dominates fixed-site operators with chemical dosing automation. Automated injection controls adjust surfactant volumes based on feedwater salinity prevalent in coastal Emirates.
- Spray Bottles:Pre-mixed solutions enable mobile waterless service deployment without infrastructure dependency. Field technician teams across Manama and Doha utilize portable formats for fleet depot contracts.
- Foaming Cartridges:Compressed foam systems attach to self-service bay equipment at petroleum retail locations. Cartridge exchange logistics integrate with existing fuel supply chain operations.
- Pouches:Single-use sachets target consumer retail channels and emergency cleaning applications. Limited commercial penetration due to unit economics versus concentrate alternatives.
Bulk Containers dominate commercial throughput; Spray Bottles climb fastest on mobile service expansion.
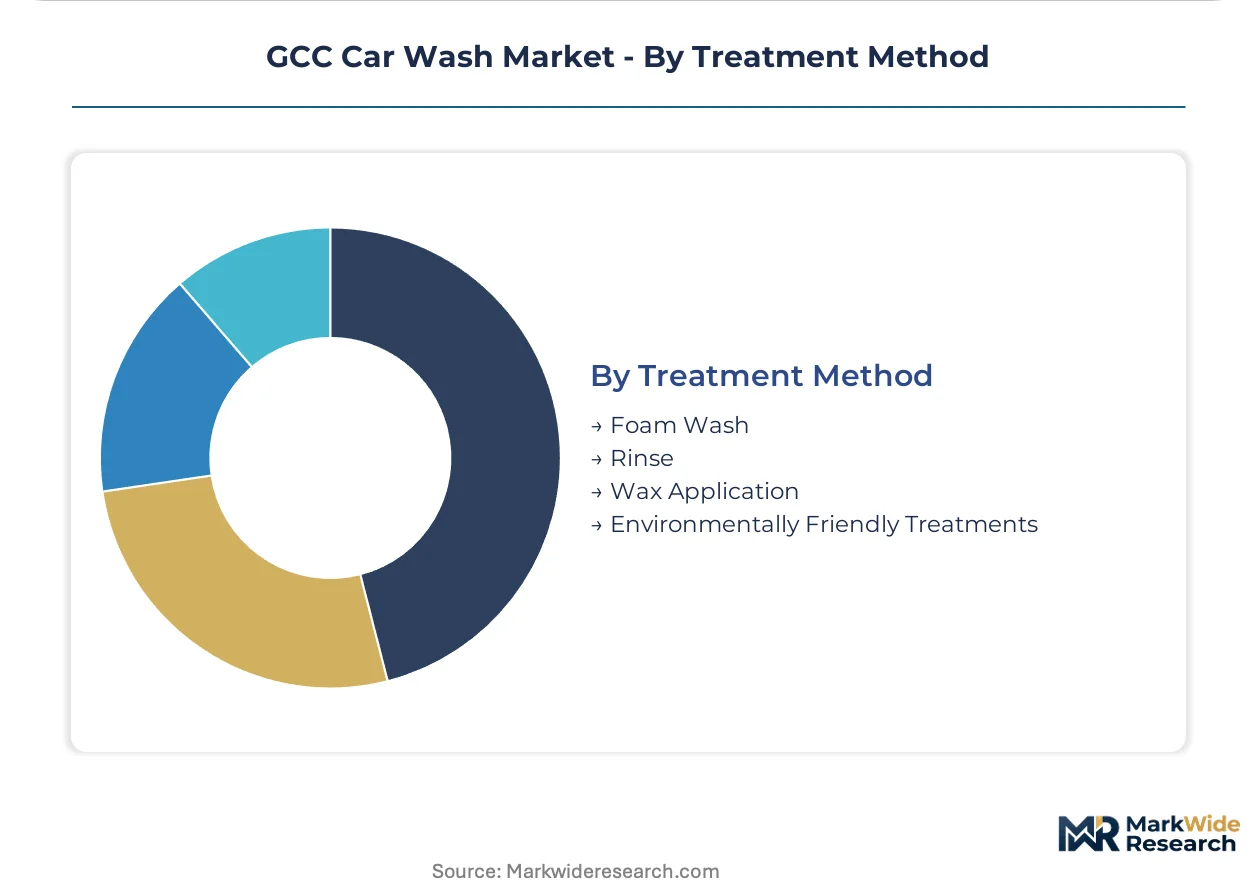
Treatment Method:
Process sequencing determines water consumption intensity and discharge compliance burden under tightening municipal codes.
- Environmentally Friendly Treatments:Biodegradable surfactant chemistry reduces contamination risk while maintaining efficacy under high-salinity feedwater conditions. Advanced formulations are displacing legacy petrochemical-based products under SFDA and MOHAP environmental enforcement.
- Foam Wash:Pre-soak foam application minimizes water volume through extended contact time with soil loads. Foam systems integrate with closed-loop filtration to maintain discharge compliance.
- Rinse:High-pressure water jets remain necessary for heavy soil removal on commercial vehicles exceeding waterless formulation efficacy. Rinse stages consume the majority of site water budgets and drive recycling infrastructure investment.
- Wax Application:Protective coating integration with tunnel cycles captures margin from premium vehicle owners. Ceramic and polymer sealants address abrasive desert climate paint degradation.
Foam Wash leads operational deployment; Environmentally Friendly Treatments show steepest expansion trajectory on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors regional demand through petroleum-retail corridor density and fleet procurement consolidation. Water scarcity mandates and municipal tariff structures shape investment feasibility across Gulf jurisdictions.
Saudi Arabia
Long-haul logistics operators drive fleet outsourcing concentration toward integrated service providers. The General Authority for Meteorology and Environmental Protection mandates closed-loop filtration for commercial wash facilities. Riyadh and Jeddah sustain express tunnel installations along ENOC Group and integrated energy retail corridors.
United Arab Emirates
Dubai's premium vehicle density and airport-adjacent rental agency throughput sustain high-throughput automatic wash economics. Dubai Municipality's Green Building Regulations and Estidama Pearl Rating criteria accelerate permitting for greywater retrofit projects. Abu Dhabi follows with parallel enforcement from the Ministry of Climate Change and Environment.
Qatar
Municipal hosepipe bans and commercial water-tariff escalations accelerate waterless wash formulation uptake among fleet depot operators. The country's national environmental regulator enforces seasonal restrictions that eliminate discharge-dependent fixed infrastructure. Doha maintains lower automatic wash density per registered vehicle than Riyadh or Dubai.
Kuwait
Automatic wash systems dominate volume throughput through petroleum retail adjacency and high vehicle ownership rates. Municipal water-use codes tighten during summer peak-demand periods, compressing site-level margins. Kuwait City concentrates express tunnel investment along controlled retail corridors.
Bahrain
Manama presents first-mover site acquisition potential with lower automatic wash density than larger Gulf markets. Seasonal hosepipe bans restrict traditional wash operations during enforcement windows. Mobile waterless service deployment expands through spray-bottle format field technician teams.
GCC Car Wash Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue waterless chemistry and mobile service deployment. The market structures around petroleum-retail incumbents with captive corridor access, subscription-model specialists, and integrated fleet service providers. Three archetypes dominate: integrated energy retailers controlling premium real estate, membership-density operators optimizing bay-turn economics, and surface-protection specialists capturing ceramic-coating upsells. Competitive moves concentrate on M&A consolidation of fragmented spot-contract vendors and retrofit capital deployment toward closed-loop filtration compliance.
Among integrated energy retail incumbents, ENOC Group anchors petroleum-retail adjacency positioning across Emirates corridor networks. Zips Car Wash and Mister Car Wash represent subscription-model and surface-protection archetypes respectively, occupying positions within membership-density and premium-upsell competitive vectors. These three entities exemplify the strategic segmentation between throughput optimization, real estate control, and per-visit revenue enhancement that defines current competitive dynamics.
| Leading Market Players |
|---|
| Autobell Car Wash |
| ENOC Group |
| Zips Car Wash |
| Delta Sonic Car Wash |
| Mister Car Wash |
| International Car Wash Group (ICWG) |
| True Blue Car Wash |
| BESTCARWASH |
| Quick Quack Car Wash |
| Others |
Pricing and Supply Chain Analysis
Desalinated water tariffs cascade through GCC car wash economics, compressing margins at high-volume tunnel operators while elevating premiums for waterless chemistry providers serving fleet depots in Qatar and Bahrain. Municipal rate volatility forces capital reallocation toward closed-loop filtration, segmenting pricing power between petroleum-retail incumbents with captive infrastructure and mobile service entrants unburdened by fixed-site discharge compliance.
Pricing Analysis
Input-cost pass-through from municipal water tariffs dominates pricing dynamics across fixed-site operators, with ENOC Group and integrated energy retailers absorbing escalation through petroleum-retail cross-subsidies that independent sites cannot replicate. Three-tier pricing structure across premium ceramic-coating, standard tunnel wash, and economy self-service levels stratifies by service intensity and water-recycling certification tier. Pricing pressure stems from seasonal tariff spikes during summer peak demand, particularly in Kuwait and Saudi Arabia. Fleet operators exhibit lowest price sensitivity due to single-source accountability mandates, while individual subscription members show moderate elasticity to monthly rate adjustments.
Supply Chain Analysis
Workforce availability constraints in Saudi Arabia and the UAE shape equipment manufacturing dependencies, with tunnel system fabricators drawing from European and East Asian component suppliers for high-pressure pumps and regenerative filtration membranes. Surfactant chemistry production concentrates in Germany, the United States, and specialty formulation houses in the UAE free zones. Supply chain risk centers on single-source vulnerability for ceramic coating polymers subject to REACH regulatory restrictions. Distribution runs through petroleum-retail procurement channels controlled by integrated energy retailers, limiting independent operator access to premium corridor real estate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC car wash functions as a stable compounder anchored by irreversible fleet outsourcing trends and regulatory mandates that permanently elevate capital requirements for new entrants. Municipal water scarcity enforcement creates durable competitive moats around incumbent infrastructure providers.
For Market Incumbents: Anticipate tariff escalation by accelerating greywater retrofit deployment ahead of mandatory reuse thresholds in Dubai and Riyadh. Defensive consolidation of fragmented spot-contract vendors in secondary cities captures procurement concentration benefits. Vertical integration into surfactant formulation reduces exposure to import cost volatility from European suppliers. For New Entrants and Emerging Players: Begin with mobile waterless service deployment in Manama and Doha, where automatic wash density per registered vehicle trails Riyadh and Dubai by substantial margins. Fleet depot contracts in Qatar present the most penetrable segment given seasonal hosepipe bans that disqualify fixed-site competitors. Go-to-market execution should emphasize spray-bottle format field teams with telematics-linked scheduling systems. For Investors and Strategic Acquirers: Consolidation pressure builds where fleet procurement mandates single-source accountability with water-recycling documentation, filtering fragmented vendor pools toward integrated infrastructure platforms. Long-term viability favors operators with petroleum-retail corridor access and captive greywater systems across the analysis window. Acquisition targets should demonstrate compliance documentation capabilities and municipal permitting relationships. Monitor municipal greywater-reuse threshold announcements as inflection indicators for retrofit capital deployment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Filtration Retrofit | Estidama Pearl Rating criteria accelerate permitting for compliant operators in Dubai. |
| Waterless Chemistry Scale-Up | Qatar's seasonal hosepipe bans eliminate discharge-dependent infrastructure for fleet contracts. |
| Subscription Membership Expansion | Monthly unlimited-wash programs improve customer lifetime value metrics across Riyadh express networks. |
| Ceramic Coating Integration | Desert climate paint preservation demand captures margin from premium vehicle owners in UAE. |
| Fleet Contract Consolidation | Saudi logistics operators mandate single-source accountability with recycling documentation. |
Research Methodology
Coverage spans Saudi Arabia, the UAE, Qatar, Kuwait, and Bahrain, with primary inputs from each jurisdiction combining structured interviews with tunnel operations directors, fleet procurement managers, municipal permitting authorities, and surfactant chemistry formulators. Secondary validation draws from Dubai Municipality Green Building Regulations, SFDA environmental enforcement records, customs trade data for car wash equipment imports, and petroleum-retail corridor development filings. Bottom-up site-level capacity modeling triangulates with top-down fleet contract value aggregation.
Rate-of-change decomposition separates volume growth from pricing evolution across service type, end user, and packaging format dimensions over the projection horizon. Segmentation modeling incorporates automatic wash, waterless wash, hand wash, and detailing service configurations alongside fleet operator, individual owner, dealer, and rental agency demand archetypes. CAGRs derive from installed base expansion rates, subscription penetration curves, and municipal tariff trajectory assumptions. Industry-specific inputs include water-recycling capital expenditure benchmarks and surfactant formulation efficacy under high-salinity feedwater conditions.
Several conditions sit outside the modeled scope, including abrupt municipal tariff restructurings, desalination energy input cost shocks, and breakthrough waterless chemistry efficacy improvements for heavy commercial soil loads. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and fleet outsourcing adoption curves. Practitioners should monitor municipal greywater-reuse threshold announcements and seasonal hosepipe ban enforcement intensity for early signals of competitive repositioning requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Authorized Car Service Center Market
Automotive Services
Mobile Car Wash Service Market
Automotive Services
Qatar Car Rental Market
Automotive Services
Automotive Digital Services Market
Automotive Services
US Car Wash Services Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Australia Fire Truck Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Automotive MRO Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Americas MAP Market
Automotive Services
Driverless Sweeper Market
Automotive Services
Car Subscription Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market