
 Automatic Vehicle Washing System Market | 2026-2036
Automatic Vehicle Washing System Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Vehicle Washing System Market Outlook
Germany's manufacturing base for automated cleaning equipment is reshaping supply dynamics across Europe. Washtec leverages its engineering heritage in tunnel systems to dominate high-throughput installations for commercial fleets. Istobal competes through modular robotics architectures that reduce installation footprints at dealership sites. Coleman Hanna Carwash Systems anchors North American demand with specialized in-bay equipment designed for harsh winter climates.
An automatic vehicle washing system is a mechanized installation employing rotating brushes, high-pressure water jets, chemical applicators, and conveyor mechanisms to clean exterior vehicle surfaces without manual labor, typically processing vehicles in under five minutes at throughput rates exceeding sixty units per hour. Its primary commercial purpose is reducing labor costs, water consumption, and chemical runoff while delivering consistent cleaning quality across high-volume fleet, retail, and dealership operations. Touchless configurations lead the product type landscape where paint preservation drives premium pricing, while tunnel installations capture the largest revenue pool among installation types due to their throughput advantage at express wash locations. Water recycling technology represents the fastest-growing technology segment as drought-prone regions tighten discharge permits and operators seek to cut municipal water bills by reclaiming up to eighty percent of process water.
EPA effluent guidelines under the Clean Water Act shape equipment specifications by mandating oil-water separation and sediment control at commercial wash facilities, while OSHA lockout/tagout standards dictate maintenance access design in automated tunnel systems. The EU Ecodesign Directive and REACH chemical restrictions push European manufacturers toward biodegradable surfactant formulations and reduced energy consumption in dryer assemblies. Stakeholders must monitor how fragmented municipal water pricing and evolving state-level drought declarations alter the payback calculus for water recycling retrofits versus new-build installations.
Market Dynamics
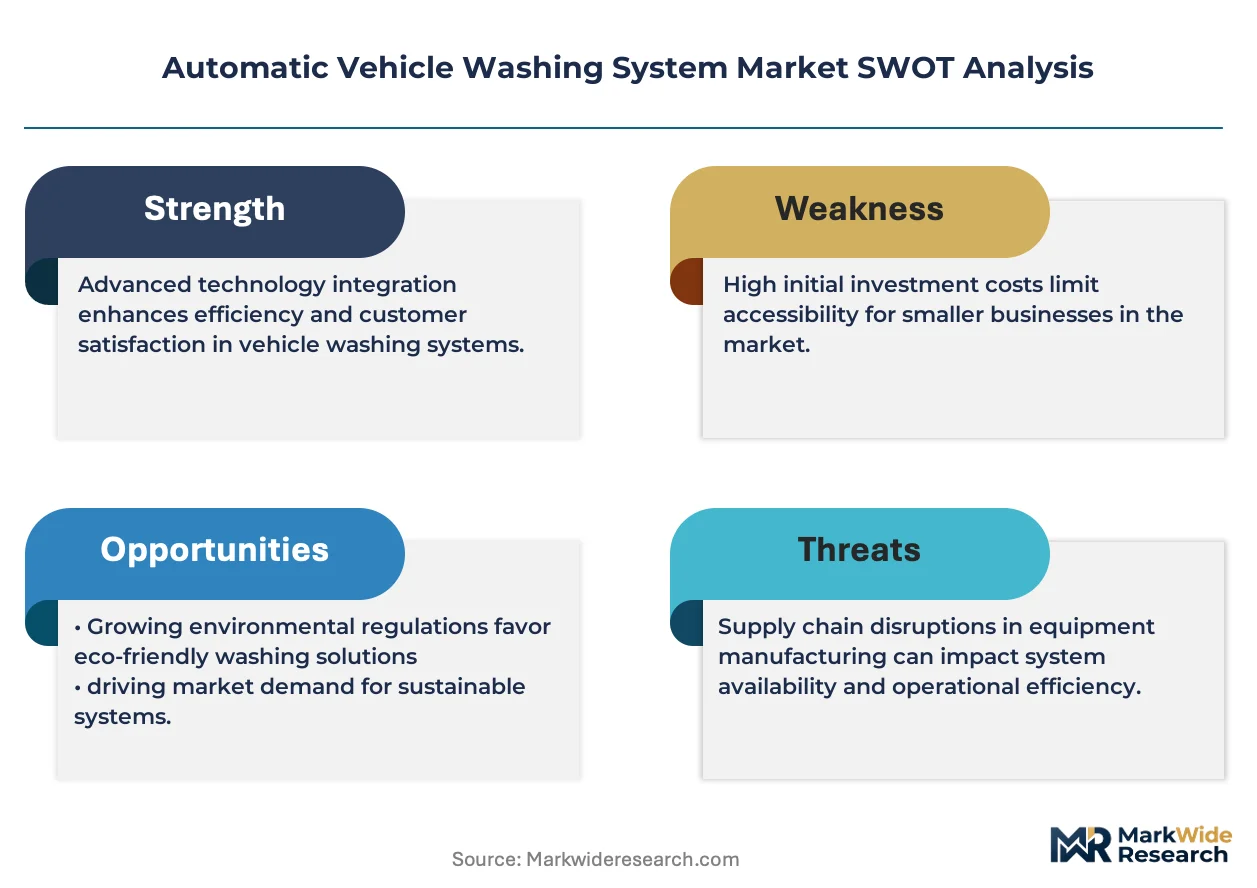
Water recycling technology is compressing capital deployment timelines as drought-prone municipalities restrict discharge permits and fleet operators face escalating municipal water tariffs. This regulatory-environmental squeeze is forcing equipment specification changes across tunnel and in-bay installation categories.
Growth Catalysts
- EPA Effluent Guidelines:Oil-water separation mandates under the Clean Water Act are accelerating retrofit demand at commercial wash facilities seeking permit compliance.
- Fleet Operator Consolidation:Large logistics and rental car fleets are standardizing automated wash protocols to reduce labor headcount and chemical variability.
- Touchless Brush Materials:Advanced closed-cell foam technologies are expanding addressable market into premium dealership and luxury vehicle segments.
Market Restraints
- Stainless Steel Input Volatility:Conveyor frame and brush housing fabrication costs fluctuate with nickel and chromium spot pricing, compressing margin visibility for equipment manufacturers.
- German Supply Concentration:Tunnel system engineering and high-pressure pump manufacturing cluster in Baden-Württemberg and Bavaria, creating geographic single-point vulnerability.
- Touchless Throughput Ceiling:Chemical dwell time requirements limit touchless configurations to sub-forty vehicles per hour, constraining express wash site economics.
Strategic Opportunities
- India Fleet Modernization:Logistics operators in Maharashtra and Gujarat are piloting automated wash bays as commercial vehicle parc expands and labor costs rise.
- Water Recycling Retrofits:Existing in-bay installations in drought-affected US states represent a captive base for membrane filtration and reverse osmosis upgrade kits.
- IoT-Enabled Predictive Maintenance:Sensor-integrated brush motors and conveyor drives are opening recurring revenue streams through remote diagnostics subscriptions.
Industry Challenges
- Mechatronics Technician Scarcity:Integration of PLC controls, variable frequency drives, and chemical dosing systems requires hybrid electrical-mechanical skills that vocational pipelines undersupply.
- Legacy Site Integration:Retrofitting water recycling into 1990s-era wash bays with constrained pad footprints demands custom civil engineering and extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Vehicle Washing System Market |
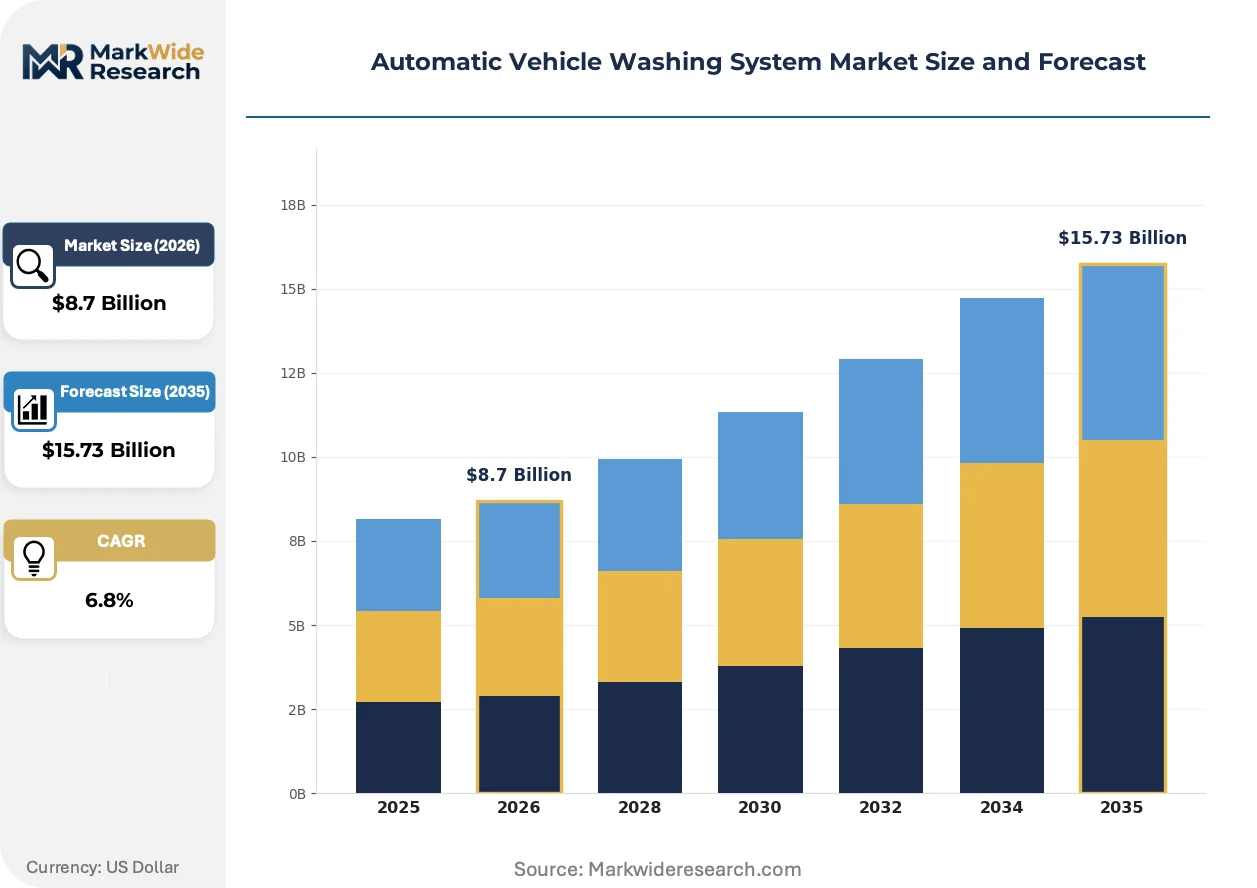
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchless, Brush, Hybrid, Mobile Installation Type: In-Bay, Tunnel, Portable, Self-Service End User: Car Wash Operators, Fleet Services, Dealerships, Residential Technology: Chemical-Based, Water Recycling, Robotics, Automated Systems |
| Companies Covered | MacNeil Wash Systems, Coleman Hanna Carwash Systems, Sonny's Enterprises, C K Enterprises, Washtec, Ryko Solutions, Istobal, Hydro Engineering, PECO Car Wash Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Vehicle Washing System Market Strategic Shifts
Automation architectures are converging with environmental compliance systems, creating equipment categories that bundle cleaning performance with regulatory documentation. This fusion is altering how fleet procurement evaluates total cost of ownership.
Ultrasonic vehicle profiling systems are replacing mechanical limit switches and photoelectric sensors in tunnel wash configurations. Express wash operators in the US Southwest are deploying these sensors to optimize chemical application based on real-time vehicle contour mapping. The technology is rendering obsolete fixed-arc spray manifolds that waste treating solution on irregular vehicle profiles.
REACH chemical restrictions and the EU Ecodesign Directive are mandating biodegradable surfactant formulations and reduced dryer assembly energy consumption. European manufacturers must reformulate presoak and sealant chemistries while redesigning blower motor efficiency curves. Touchless system operators in Germany and France face the steepest compliance timelines due to earlier adoption of high-chemistry wash protocols.
Subscription-based equipment access is displacing outright purchase for mid-sized fleet operators with variable wash volume. Wash bay-as-a-service providers in Texas and Florida are bundling maintenance, chemical supply, and water recycling compliance into per-wash fees. This model is most visible among regional rental car operators seeking to convert fixed infrastructure costs into variable operating expenses aligned with fleet utilization rates.
Automatic Vehicle Washing System Market Segmentation
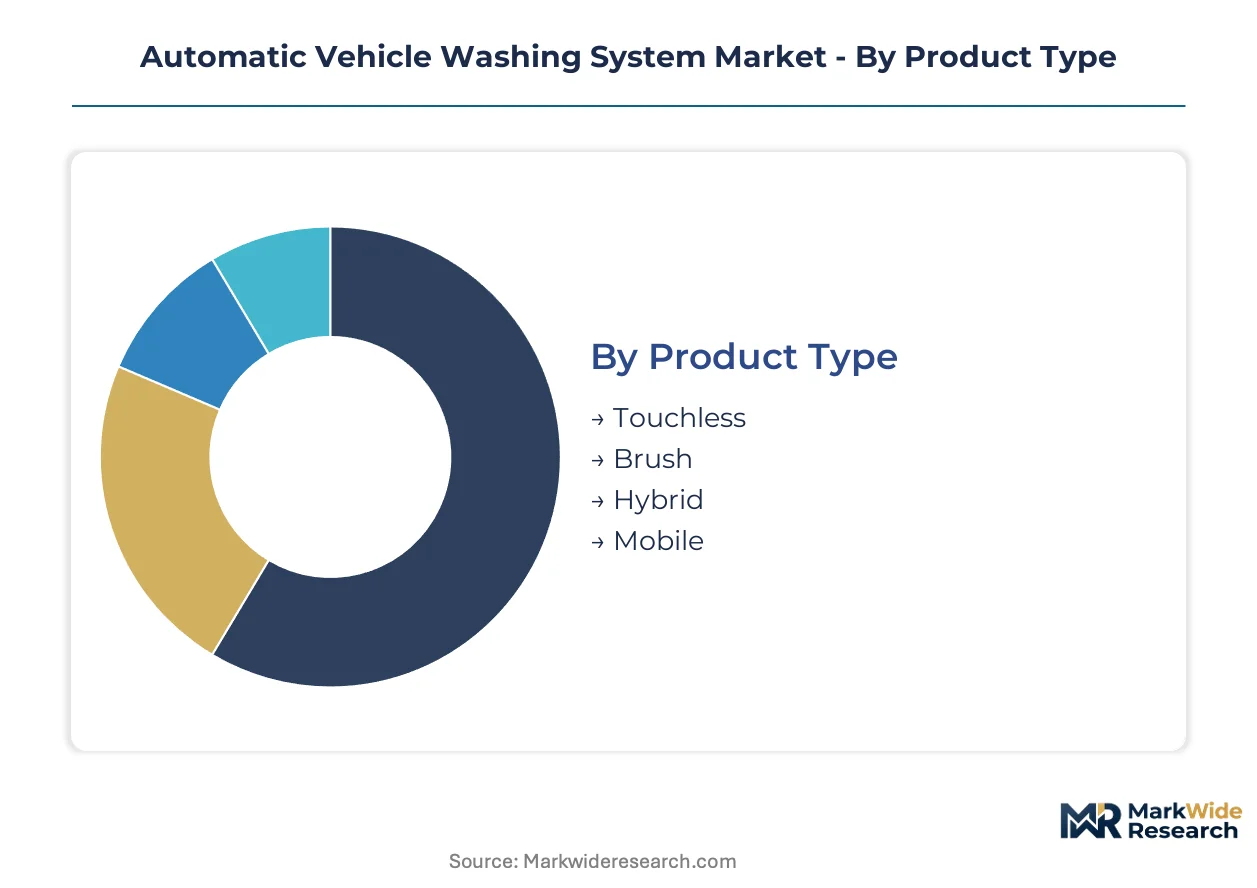
Equipment segmentation in automatic vehicle washing determines service contract structures and spare parts forecasting. Distributors calibrate inventory and technical staffing based on configuration complexity and component wear profiles across installation categories.
Product Type:
After-sales service intensity varies sharply by cleaning mechanism, with brush systems demanding quarterly component replacement and touchless configurations requiring precise chemical calibration protocols.
- Touchless:High-pressure water jets and chemical applicators eliminate mechanical contact with vehicle surfaces. Fleet operators in drought-affected US states specify these configurations to minimize water discharge volumes while preserving paint finishes on high-value commercial vehicles.
- Brush:Rotating closed-cell foam or cloth strips provide aggressive cleaning action for heavily soiled vehicles. Express wash chains in Germany deploy these systems for throughput rates exceeding sixty units per hour at highway-adjacent locations.
- Hybrid:Combines touchless pre-soak stages with gentle brush contact for balanced performance.
- Mobile:Self-contained trailer-mounted units serve temporary fleet deployments and event-based cleaning operations.
By volume, Brush leads. By growth pace, Touchless is ahead.
Installation Type:
Site configuration dictates capital recovery timelines and regulatory compliance pathways for water discharge permitting.
- Tunnel:Conveyor-driven continuous processing achieves maximum throughput for high-volume express operations. US Southwest operators favor these installations for fleet contract economics, though EPA effluent guidelines mandate costly oil-water separation infrastructure.
- In-Bay:Single-vehicle automated cleaning with smaller physical footprints suits constrained urban sites. European dealership networks specify these systems for premium vehicle handling with reduced installation lead times.
- Portable:Modular skid-mounted equipment relocates between temporary sites.
- Self-Service:Customer-operated wands and vacuums minimize labor requirements at low-volume locations.
Tunnel installations dominate revenue contribution. In-Bay configurations are expanding most quickly among retrofit opportunities.
End User:
Procurement authority and wash frequency specifications diverge sharply across customer categories, altering equipment specification priorities.
- Fleet Services:Logistics and rental car operators standardize automated protocols to reduce labor headcount and chemical variability across multiple locations. Consolidated purchasing power drives specification toward high-throughput tunnel configurations with centralized chemical supply contracts.
- Car Wash Operators:Independent and chain express wash businesses optimize for throughput economics and water recycling compliance. Municipal water tariffs in drought-prone regions accelerate capital deployment for reclamation technology.
- Dealerships:Premium vehicle preparation demands gentle cleaning action and showroom-quality finishing.
- Residential:Individual homeowners represent minimal commercial equipment demand.
Fleet Services generates the largest equipment orders. Car Wash Operators show the steepest expansion trajectory for water recycling retrofits.
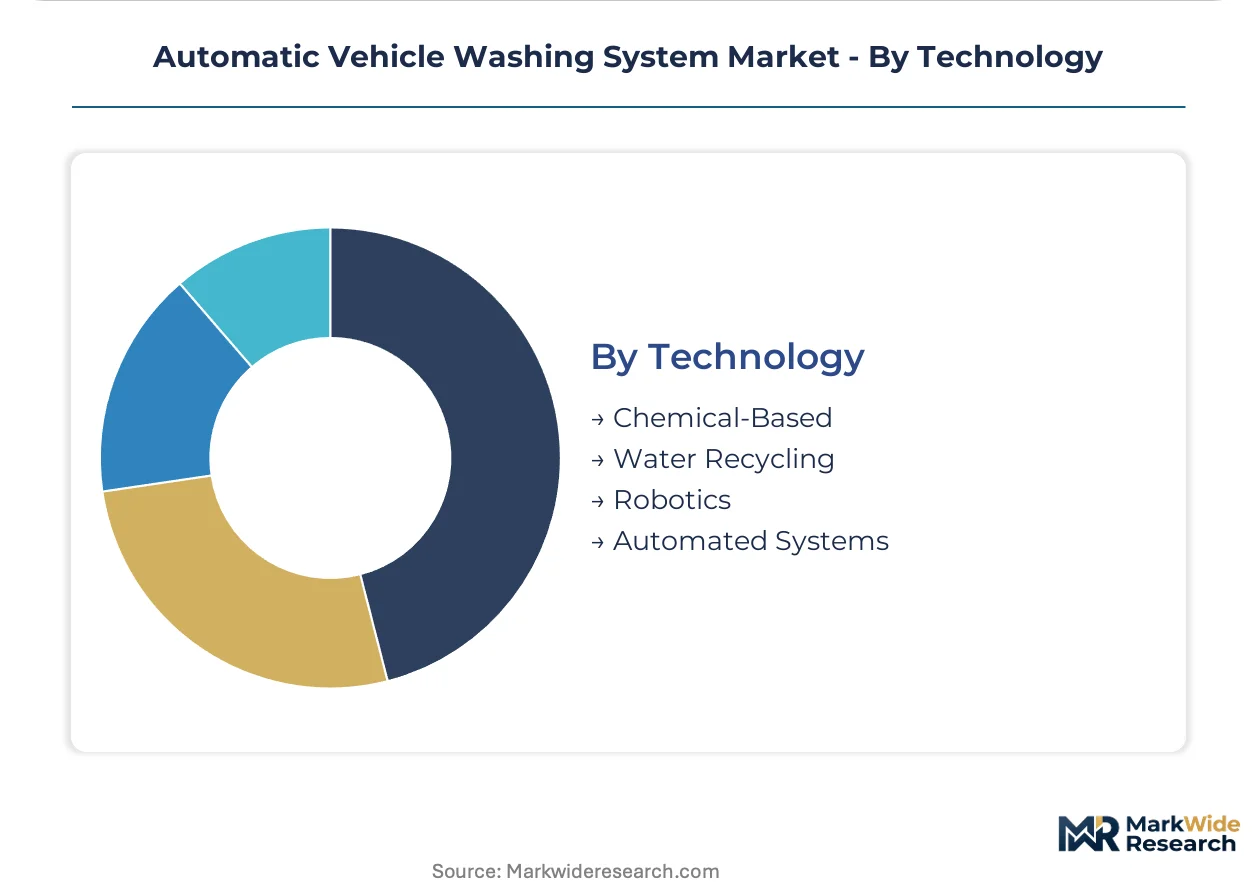
Technology:
Environmental compliance systems are converging with core cleaning functions, creating bundled equipment categories that document regulatory performance.
- Water Recycling:Membrane filtration and reverse osmosis systems reclaim process water for reuse, cutting municipal discharge volumes. California and Texas operators face tightening permit restrictions that mandate reclamation rates approaching eighty percent at new installations.
- Robotics:Articulated arm configurations replace fixed-arch manifolds for adaptive vehicle profiling. German manufacturers lead integration of ultrasonic sensors that map contours in real time.
- Chemical-Based:Traditional surfactant and sealant application systems face reformulation pressure under REACH restrictions.
- Automated Systems:PLC-controlled conveyor and brush coordination provides baseline mechanization.
Automated Systems retains the installed base majority. Water Recycling is gaining share fastest amid regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent guidelines under the Clean Water Act anchor United States demand, while German engineering clusters and Indian logistics expansion shape complementary growth poles across three continents.
United States
Fleet operators in Texas and California deploy tunnel systems to cut labor costs amid tightening municipal water tariffs. EPA oil-water separation mandates accelerate retrofit demand at commercial wash facilities seeking discharge permit compliance. Coleman Hanna Carwash Systems anchors North American supply from its engineering base serving harsh winter climate specifications.
Germany
Washtec and Istobal dominate high-throughput tunnel and modular robotics architectures for European fleet operators. EU Ecodesign Directive and REACH chemical restrictions push biodegradable surfactant formulations and reduced dryer energy consumption. Baden-Württemberg and Bavaria concentrate tunnel system engineering and high-pressure pump manufacturing capacity.
India
Logistics operators in Maharashtra and Gujarat pilot automated wash bays as commercial vehicle parc expands and labor costs rise. Central Pollution Control Board effluent standards for commercial vehicle operations tighten discharge requirements for fleet maintenance facilities. Manufacturing clusters in Pune and Ahmedabad attract equipment distributors targeting fleet modernization contracts.
China
Express wash chains in Yangtze River Delta and Pearl River Delta regions adopt water recycling systems amid municipal water pricing reforms. Ministry of Ecology and Environment discharge standards tighten effluent controls for commercial wash facilities in water-stressed provinces. Zhengzhou and Shandong industrial zones concentrate domestic equipment fabrication serving fleet and dealership segments.
Japan
Premium dealership networks in Kanto and Kansai regions specify gentle cleaning systems for luxury vehicle preparation. METI energy efficiency standards shape dryer assembly specifications and brush motor performance curves. Nagoya automotive supplier corridor integrates wash system procurement into just-in-time vehicle logistics chains.
Automatic Vehicle Washing System Market Competitive Environment
Engineering heritage specialists and scale-driven systems integrators split the market into distinct capability tiers. Tunnel system fabrication concentrates among German and North American manufacturers with decades of conveyor mechanism refinement. Three archetypes dominate: heritage engineering houses with proprietary brush technologies, modular robotics specialists reducing installation footprints, and regional fabricators serving price-sensitive fleet retrofits. Competitive dynamics center on water recycling technology licensing and predictive maintenance software subscriptions.
Within the heritage engineering tier, Washtec AG exemplifies European tunnel system dominance through its Baden-Württemberg engineering base, while Coleman Hanna Carwash Systems occupies the North American climate-specialist position. Istobal S.A. represents the modular robotics archetype with its Spanish corporate structure. These three anchors illustrate how geographic engineering clusters and regulatory proximity shape competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| MacNeil Wash Systems |
| Coleman Hanna Carwash Systems |
| Sonny's Enterprises |
| C K Enterprises |
| Washtec |
| Ryko Solutions |
| Istobal |
| Hydro Engineering |
| PECO Car Wash Systems |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor's volatile container rates compress margin visibility for German tunnel system manufacturers while amplifying price differentiation between premium brush-engineering heritage and standard in-bay configurations sourced from regional fabricators. Stainless steel input costs for conveyor frames and high-pressure pump housings transmit directly to fleet operator procurement budgets, forcing specification trade-offs between throughput capacity and water recycling compliance.
Pricing Analysis
North American tunnel installations command substantial premiums over European in-bay equivalents due to EPA-mandated oil-water separation infrastructure and harsh-climate engineering specifications. Pricing stratifies across premium, standard, and economy tiers based on throughput certification, water reclamation rates, and after-sales service bundling. Cost compression in standard configurations is intensifying because nickel and chromium spot volatility squeezes fabricator margins. Fleet services buyers exhibit lowest price sensitivity due to consolidated purchasing power and labor-cost arbitrage calculus, while independent car wash operators face acute budget constraints.
Supply Chain Analysis
Stainless steel feedstock draws from German, Chinese, and South Korean metallurgical clusters, with Baden-Württemberg and Bavaria anchoring precision machining for high-pressure pump assemblies. Critical inputs include nickel-chromium alloys for brush housings, PLC control modules from Japanese automation specialists, and membrane filtration components. Single-source vulnerability concentrates in German tunnel engineering expertise, where mechatronics technician scarcity constrains capacity expansion. Distribution runs through authorized dealer networks serving fleet procurement teams and independent operator retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The widening gap between PLC-integrated system complexity and vocational pipeline output is constraining deployment velocity across drought-prone municipalities. Equipment specification authority now concentrates with buyers possessing in-house mechatronics capability, fragmenting procurement patterns between self-sufficient fleet operators and service-dependent independents.
For Market Incumbents: Harden water recycling technology licensing positions through patent thickets around membrane filtration integration, as California and Texas effluent guidelines accelerate retrofit demand. Secure captive supply of high-pressure pump castings from Baden-Württemberg foundries to insulate margin structures from stainless steel volatility. Vertical integration into predictive maintenance software subscriptions creates recurring revenue insulation against equipment commoditization. For New Entrants and Emerging Players: Maharashtra and Gujarat fleet modernization represents the most penetrable white-space corridor, where logistics operator consolidation outpaces local equipment manufacturing capacity. Target water recycling retrofit kits for 1990s-era in-bay installations in drought-affected US states, where civil engineering constraints favor modular upgrade solutions over greenfield replacement. Pursue wash bay-as-a-service partnerships with regional rental car operators seeking variable cost structures. For Investors and Strategic Acquirers: EPA effluent guideline phase-ins reshape the acquisition landscape toward water recycling technology specialists with proven membrane filtration deployments. Long-term viability centers on equipment providers bundling regulatory compliance documentation with core cleaning functions. Acquisition target archetype: mid-scale robotics integrators with ultrasonic vehicle profiling capabilities. Monitor state-level drought declaration frequency as inflection indicator for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Water Recycling Technology Licensing | EPA discharge mandates in California and Texas force reclamation rate minimums at new installations. |
| Predictive Maintenance Platform Launch | Sensor-integrated brush motors enable remote diagnostics subscriptions for fleet operator retention. |
| Membrane Filtration Manufacturing Scale-Up | Reverse osmosis component supply constraints limit retrofit deployment timelines in drought regions. |
| Geographic Expansion into Indian Fleet Corridors | Maharashtra logistics hubs seek automated wash protocols as commercial vehicle parc expands rapidly. |
| Biodegradable Surfactant Formulation Partnership | REACH restrictions in Germany and France mandate chemistry reformulation for touchless system operators. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, equipment distributor sales records, and municipal water discharge permit filings. The research team conducted structured interviews with fleet maintenance directors, car wash chain procurement officers, OEM aftermarket service heads, and water recycling technology engineers. Secondary validation drew from EPA effluent guideline documentation, EU Ecodesign Directive technical annexes, and state-level drought restriction declarations. Bottom-up equipment shipment tallies and top-down fleet operator capex surveys were cross-referenced for triangulation.
Forecast inputs include installation type segmentation, end-use procurement authority patterns, technology adoption curves for water recycling and robotics, and regional regulatory enforcement intensity. The analytical framework models tunnel versus in-bay deployment ratios, touchless versus brush configuration mixes, and fleet services versus independent operator demand splits across the projection horizon. CAGRs were derived from equipment replacement cycles, fleet consolidation trajectories, and municipal water tariff escalation patterns. Industry-specific inputs incorporate membrane filtration cost reduction curves and mechatronics technician supply constraints.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by stainless steel processors or membrane filtration specialists would shift outcomes. Regulatory enforcement variance across EPA regional offices and state environmental agencies introduces forecast uncertainty. Cross-checking against municipal water discharge permit issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
United States Automotive Dealership Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
Vehicle Conversion Market
Automotive Services
North America MRO Distribution Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Cab Services Market
Automotive Services
Global Street Sweeper Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Motorsports Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Automotive Repair and Service Market
Automotive Services
Automotive Acoustic Engineering Services Market
Automotive Services
Vehicles for Disabled Market