
 Spare Wheel Carrier Market | 2026-2036
Spare Wheel Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Spare Wheel Carrier Market Analytics
Fleet consolidation among commercial off-road vehicle operators is repositioning procurement power toward volume buyers who specify swing-away and bolt-on installation types. ARB Corporation Ltd leverages its Australian manufacturing base to sustain dominant aftermarket channel control across Asia-Pacific mining and expedition segments. CURT Manufacturing LLC competes through permanent-installation steel carriers that anchor its position in North American truck and SUV original equipment supply chains. Rhino-Rack differentiates via aluminum-focused removable designs that occupy premium recreational vehicle markets in Europe and Oceania.
A spare wheel carrier is a vehicle-mounted structural assembly, typically fabricated from stamped steel, extruded aluminum, or reinforced polymer composites, engineered to secure an auxiliary tire against rotational, vibrational, and impact loads during transit. The device incorporates hinge mechanisms, locking hardware, and load-distributed mounting brackets to maintain tire accessibility while preserving vehicle aerodynamics and rear-visibility compliance. Swing-away configurations lead in aftermarket value due to their dual-function tailgate access, while fixed variants dominate OEM truck installations where cost minimization governs specification. Aluminum material grades represent the fastest-expanding segment as manufacturers reduce unsprung mass to meet fuel-efficiency benchmarks without sacrificing load ratings.
NHTSA rear-visibility standards and FMVSS load-securement regulations in the United States mandate crash-tested mounting integrity and sight-line preservation, compelling redesign of hinge geometry and camera-integration provisions. Australia's ADR vehicle standards and Japan's JIS structural specifications similarly enforce dynamic-load testing protocols that filter non-compliant imports from their respective replacement markets. Stakeholders must monitor evolving material-certification requirements and regional fitment homologation timelines to align production footprints with diverging compliance thresholds.
Market Dynamics
Fleet consolidation among commercial off-road vehicle operators is compressing supplier margins while amplifying volume-buyer leverage over swing-away and bolt-on configuration specifications. This structural force is redistributing procurement power toward mining, agricultural, and expedition fleet managers who demand standardized mounting systems across multi-vehicle deployments.
Growth Catalysts
- FMVSS load-securement rules:NHTSA mandates for crash-tested mounting integrity are filtering non-compliant imports from the US replacement market, creating certification barriers that favor established engineering houses.
- Aluminum extrusion adoption:Automotive lightweighting programs are accelerating specification of high-strength aluminum grades in premium SUV and electric vehicle platforms to reduce unsprung mass.
- Australian mining fleet replacement:Asia-Pacific resource extraction operators are standardizing swing-away carriers for underground and remote-site vehicle accessibility requirements.
Market Restraints
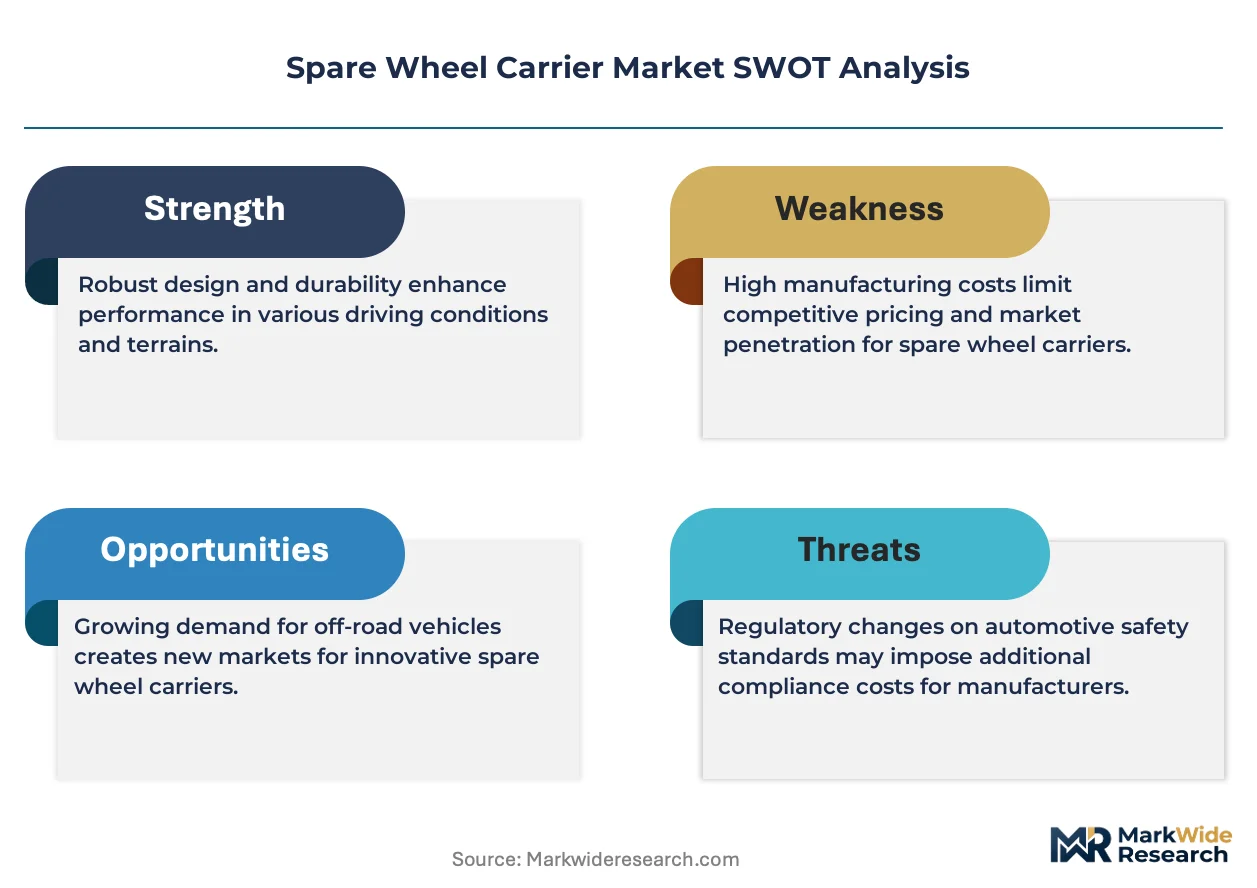
- Steel price volatility:Stamped steel remains the dominant carrier material, exposing fabricators to scrap metal and hot-rolled coil cost swings that compress margin predictability.
- Rear-visibility compliance costs:NHTSA camera-integration mandates are forcing hinge-geometry redesigns that add engineering validation expense without commensurate price recovery.
- Polymer composite substitution:Reinforced thermoplastic wheel well inserts in select electric vehicle architectures are displacing external carrier demand in urban-focused SUV segments.
Strategic Opportunities
- India commercial vehicle aftermarket:Underpenetrated fitment rates in domestic SUV and light commercial fleets offer white-space expansion for localized bolt-on carrier production.
- EU Green Deal material incentives:Recycled aluminum certification programs are creating preferential procurement channels for circular-economy-compliant mounting systems.
- E-commerce direct-to-installer channels:Digital platforms are disintermediating traditional distributor networks, enabling margin capture by specialized carrier manufacturers.
Industry Challenges
- Homologation timeline compression:Diverging regional test protocols for dynamic-load certification are stretching engineering resources across parallel validation tracks.
- Precision welding skill scarcity:Aluminum TIG welding expertise for thin-wall extrusion assembly is concentrating in limited geographic labor pools, constraining production scaling.
- Legacy vehicle fitment complexity:Retroactive carrier adaptation for discontinued SUV platforms requires custom bracket development that fragments SKU economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spare Wheel Carrier Market |
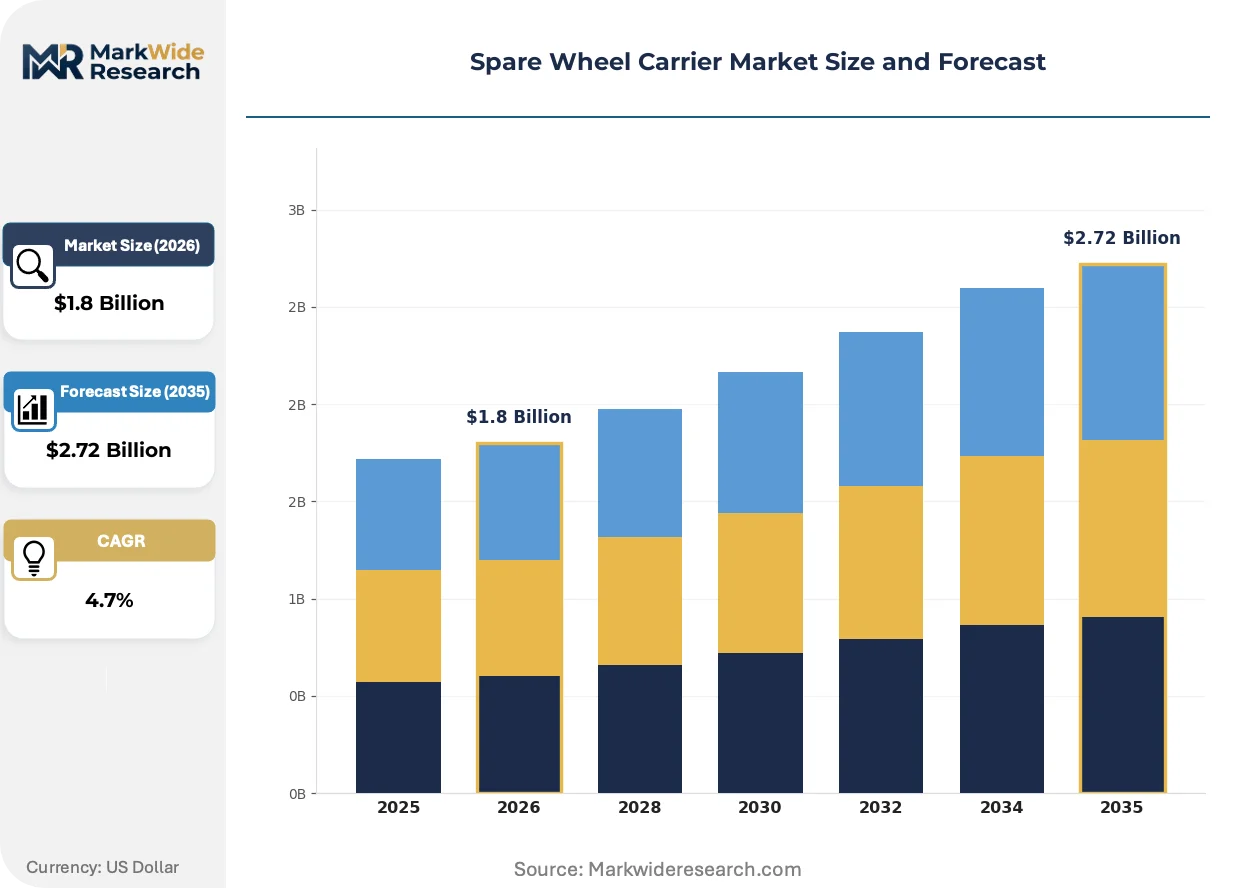
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Swing Away, Removable, Storage End User: Off-Road Vehicles, SUVs, Trucks, Motorhomes Material: Steel, Aluminum, Plastic, Composite Installation Type: Permanent, Temporary, Bolt-On, Clamp-On |
| Companies Covered | Bestop Inc, ARB Corporation Ltd, CURT Manufacturing LLC, Rhino-Rack, Smittybilt, Bak Industries, Kargo Master, Superior Engineering, Fab Fours Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spare Wheel Carrier Market Evolving Landscape
Active engineering focus is migrating toward modularity and material substitution as fleet operators demand configurable mounting systems that adapt across vehicle generations without full replacement. This shift is compressing product lifecycles while elevating design-service content in supplier relationships.
Extruded aluminum carrier architecture is modularizing product development cycles by enabling platform-shared hinge mechanisms across multiple vehicle wheelbases. Tier-1 suppliers are adopting this approach for electric SUV programs where mass reduction targets exceed 15% versus stamped steel equivalents. The structural consequence is collapsing the traditional tooling amortization model, as die-cost recovery now spans shorter production runs across variant-rich nameplates.
REACH substance restrictions on hexavalent chromium plating are compelling European manufacturers to migrate toward zinc-nickel and organic coating systems for corrosion protection. This regulatory pressure is elevating surface treatment costs by an estimated 12-18% while extending qualification timelines for salt-spray performance validation. German and French automotive suppliers are responding by consolidating finishing operations with captive plating facilities to control chemistry compliance.
Direct fleet procurement contracts are displacing traditional aftermarket distributor relationships in North American commercial off-road segments. Mining and agricultural operators are unbundling carrier specification from vehicle OEM supply agreements, creating dedicated supplier panels for mounting system lifecycle management. This pattern is most visible in Wyoming oil-field service fleets and Alberta oil sands logistics operations, where standardized swing-away configurations reduce field-service downtime across mixed-vehicle pools.
Spare Wheel Carrier Market Segmentation
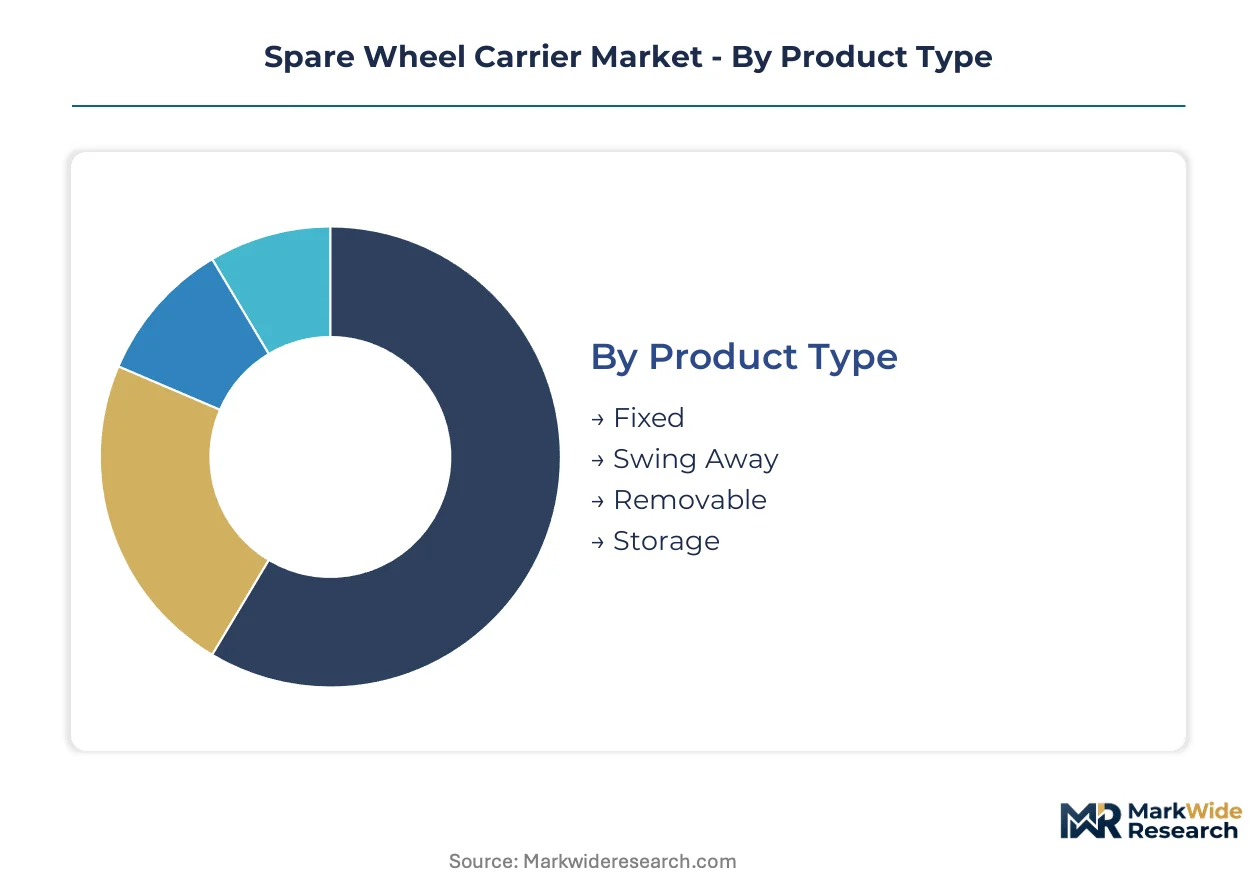
Spare wheel carrier specifications diverge sharply across vehicle duty cycles, material engineering priorities, and regulatory compliance thresholds. Fleet operators and OEM procurement teams segment demand by installation permanence, mass reduction targets, and rear-visibility mandates that reshape supplier value propositions.
Product Type:
Replacement cycles accelerate where tailgate access conflicts with cargo security requirements, driving upgrade decisions toward dual-function configurations.
- Swing Away:Hinge-mounted assemblies rotate outward from vehicle rear panels, preserving cargo bed or trunk access without carrier removal. Mining and expedition fleet operators in Australia specify these for underground equipment and remote-site accessibility where downtime carries operational penalties.
- Fixed:Rigid bracket systems weld or bolt directly to frame rails, offering maximum load security at lowest unit cost. North American truck OEMs default to fixed mounting for factory installations where procurement cost minimization governs specification.
- Removable:Quick-release pin mechanisms enable seasonal or trip-specific deployment without permanent vehicle modification.
- Storage:Integrated compartment designs house tools, fluids, or recovery equipment alongside the spare tire.
Volume placements concentrate in Fixed configurations; the faster expansion belongs to Swing Away.
End User:
Customer procurement authority fragments across fleet managers, vehicle OEMs, and individual owners with diverging technical priorities.
- Off-Road Vehicles:Modified 4x4 platforms for mining, agriculture, and expedition use carry the most demanding dynamic-load specifications. Australian resource extraction operators standardize swing-away carriers across underground and open-pit vehicle pools.
- Trucks:Commercial and consumer pickup segments drive stamped-steel volume through OEM supply chains. FMVSS load-securement testing filters non-compliant imports from US replacement demand.
- SUVs:Premium unibody platforms specify aluminum carriers to meet corporate fuel-efficiency targets.
- Motorhomes:Recreational vehicle builders prioritize lightweight removable systems with integrated storage.
Fleet procurement dominates Off-Road and Truck segments; Motorhome demand is climbing fastest as RV production scales.
Material:
Mass reduction imperatives and corrosion resistance requirements are restructuring material specification across price tiers.
- Steel:Hot-rolled and stamped grades anchor cost-sensitive OEM truck installations. Scrap metal price volatility compresses fabricator margin predictability across production cycles.
- Aluminum:Extruded high-strength grades enable 15% mass reduction versus steel equivalents in premium SUV and electric vehicle programs. EU Green Deal recycled aluminum certification creates preferential procurement channels for circular-economy-compliant suppliers.
- Plastic:Reinforced polymer brackets serve temporary and clamp-on configurations in light-duty applications.
- Composite:Carbon fiber and glass-reinforced systems occupy niche motorsport and expedition markets.
Steel retains volume leadership; aluminum is gaining share fastest as lightweighting targets intensify.
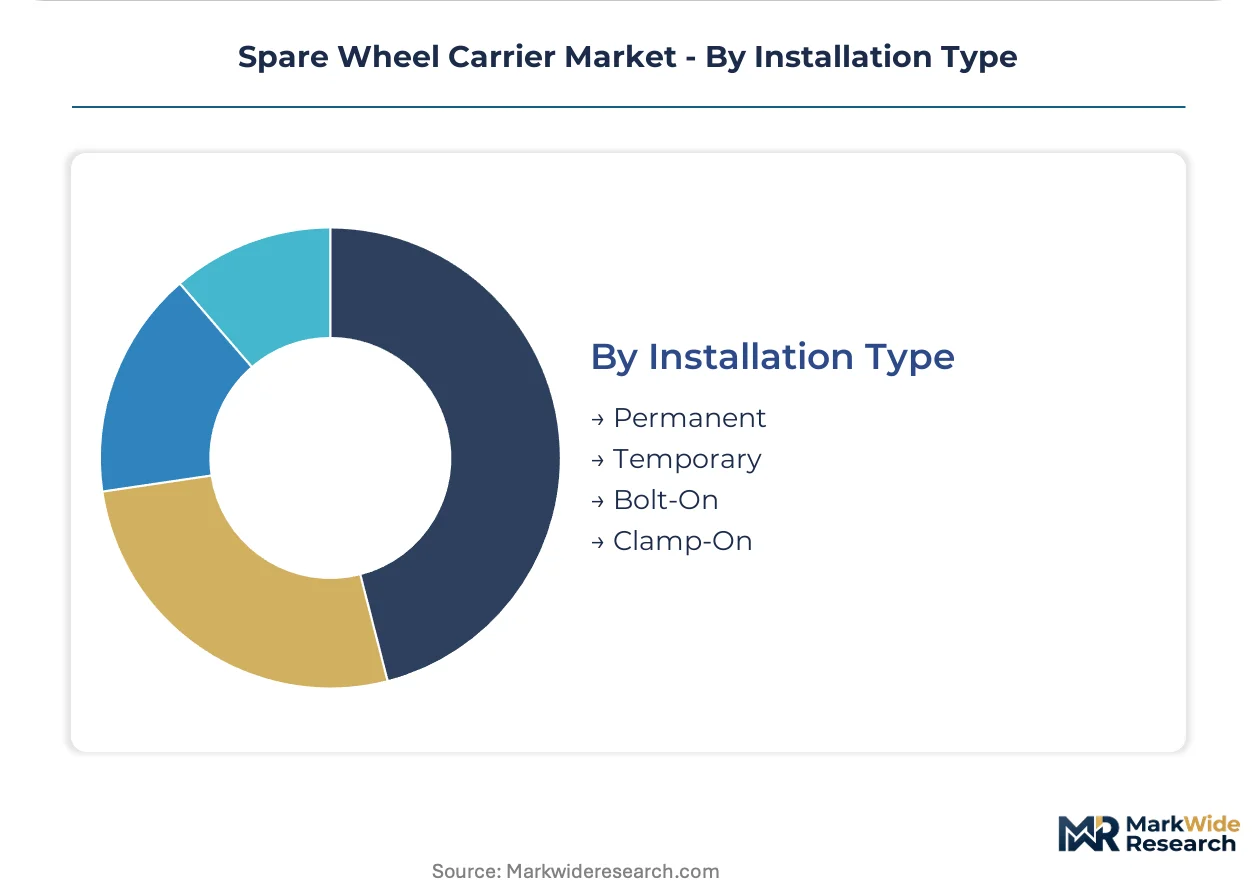
Installation Type:
Mounting permanence determines distribution channel structure and aftermarket upgrade potential.
- Bolt-On:Through-frame hardware enables professional or proficient owner installation without welding. Indian commercial vehicle aftermarket channels underpenetrated in this configuration offer white-space expansion for localized production.
- Permanent:Welded or riveted factory installations dominate OEM truck supply chains where lifecycle cost minimization outweighs service flexibility.
- Temporary:Suction or strap-mounted systems serve rental fleets and emergency roadside use.
- Clamp-On:Receiver-hitch or bumper-clamp designs enable tool-free attachment for recreational users.
Permanent installations hold volume concentration; bolt-on systems are expanding most quickly as fleet standardization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Australia, where mining fleet standardization and expedition vehicle modification anchor aftermarket procurement volumes for swing-away configurations.
United States
Commercial off-road fleet operators in Wyoming and Alberta oil sands logistics drive procurement of standardized swing-away carriers. NHTSA rear-visibility standards and FMVSS load-securement rules mandate crash-tested mounting integrity and camera-integration provisions. Detroit-area automotive suppliers redesign hinge geometry to preserve sight-line compliance for OEM truck programs.
Australia
Resource extraction operators across Western Australia and Queensland standardize swing-away carriers for underground equipment accessibility requirements. ADR vehicle standards enforce dynamic-load testing protocols that filter non-compliant imports from replacement markets. Melbourne and Perth anchor aftermarket distribution networks for mining and expedition vehicle segments.
Germany
Premium SUV manufacturers specify aluminum carriers to meet corporate fuel-efficiency targets and EU Green Deal recycled material incentives. REACH substance restrictions on hexavalent chromium plating compel migration toward zinc-nickel coating systems. Stuttgart and Munich automotive clusters consolidate finishing operations with captive plating facilities.
Japan
Domestic SUV and light truck OEMs integrate permanent-installation carriers for factory supply chains. JIS structural specifications enforce rigorous dynamic-load certification that limits import penetration. Nagoya and Tokyo metropolitan areas concentrate precision welding expertise for thin-wall aluminum extrusion assembly.
India
Underpenetrated fitment rates in domestic SUV and light commercial fleets create white-space expansion for localized bolt-on carrier production. BIS certification requirements and DGFT import regulations shape supplier qualification timelines. Maharashtra and Gujarat manufacturing corridors attract regional production investments for commercial vehicle aftermarket channels.
Spare Wheel Carrier Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aluminum lightweighting and modular platform strategies to capture premium specification contracts. The vendor base separates into three functional tiers: multinational automotive suppliers with OEM certification depth, regional fabricators serving aftermarket distribution, and specialized expedition-equipment houses. Competitive positioning hinges on homologation speed, material certification breadth, and fleet-direct relationship depth. M&A activity concentrates on aluminum extrusion capabilities and captive surface-treatment assets; strategic partnerships link carrier specialists with electric vehicle platform engineering.
Among Australian-based specialists, ARB Corporation Ltd and Superior Engineering exemplify the expedition-equipment archetype with mining fleet standardization programs. CURT Manufacturing LLC represents the North American OEM supply tier with permanent-installation steel carrier relationships. Rhino-Rack occupies the premium recreational vehicle segment through aluminum-focused removable designs across European and Oceania markets.
| Leading Market Players |
|---|
| Bestop Inc |
| ARB Corporation Ltd |
| CURT Manufacturing LLC |
| Rhino-Rack |
| Smittybilt |
| Bak Industries |
| Kargo Master |
| Superior Engineering |
| Fab Fours Inc |
| Others |
Value Network & Pricing Analysis
EU Green Deal recycled aluminum certification gates qualified supply access and premium-tier pricing power for mounting system fabricators serving European automotive OEMs. Compliance-validated producers capture 15-20 point margin premiums over uncertified competitors while non-compliant suppliers face channel exclusion from Stuttgart and Munich procurement panels.
Pricing Analysis
Volume-mass splits between steel and aluminum tiers drive divergent margin structures across the market. Three-tier pricing structure across premium, standard, and economy levels separates certified aluminum extrusion carriers from commodity steel stampings and temporary polymer configurations. Price differentiation hinges on material certification grade and fleet-direct contract scale. Cost compression in steel-tier production is intensifying because scrap metal volatility erodes fabricator predictability. Fleet procurement managers exhibit lowest price sensitivity; individual aftermarket buyers face highest elasticity.
Supply Chain Analysis
Regional distribution centers in Melbourne, Detroit, and Stuttgart anchor hub-and-spoke patterns for aftermarket and OEM fulfillment. Manufacturing concentrates in Australia, the United States, and Germany for mining-grade swing-away systems, stamped-steel truck carriers, and aluminum SUV platforms respectively. Supply chains draw from hot-rolled steel coil, high-strength aluminum extrusion billets, and zinc-nickel plating chemistry inputs. Single-source vulnerability concentrates in thin-wall aluminum TIG welding expertise pools. Distribution runs through captive OEM supply agreements and specialized aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum extrusion capacity scarcity props pricing power for certified suppliers while constraining volume expansion for non-integrated competitors. This bottleneck justifies selective capacity investments in captive melt-and-extrude operations.
For Market Incumbents: Anchor market position through backward integration into aluminum extrusion assets and captive zinc-nickel plating facilities. Polymer composite substitution in urban SUV segments threatens external carrier demand; counter through fleet-direct relationship depth in mining and agricultural segments. Certification investment in EU Green Deal compliance and NHTSA FMVSS testing protocols creates defensible moats against import competition. For New Entrants and Emerging Players: Capture white-space in India's underpenetrated bolt-on aftermarket through localized production in Maharashtra and Gujarat manufacturing corridors. E-commerce direct-to-installer channels offer disintermediation leverage against established distributor networks. Prioritize aluminum lightweighting specifications for electric SUV platform engineering partnerships. For Investors and Strategic Acquirers: Fleet procurement contract unbundling from OEM supply agreements is the leading indicator that dedicated carrier supplier panels will consolidate toward lifecycle management providers. Long-term viability favors vertically integrated fabricators with captive surface treatment and homologation expertise. Target acquisition archetype: regional aluminum extrusion specialists with mining fleet relationships. Watch aluminum TIG welding labor pool concentration as inflection signal for production scaling constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive melt-and-extrude capacity secures EU Green Deal certification and margin control against scrap volatility. |
| Fleet-Direct Procurement Panel Formation | Wyoming and Alberta oil sands operators unbundle carrier specification from OEM agreements, creating dedicated supplier relationships. |
| Modular Platform Standardization | Die-cost recovery across variant-rich electric SUV nameplates collapses traditional tooling amortization models. |
| Captive Surface Treatment Consolidation | German and French suppliers consolidate zinc-nickel plating to control REACH compliance and salt-spray validation timelines. |
| E-Commerce Direct-to-Installer Channel Buildout | Digital platforms disintermediate traditional aftermarket distributors, enabling margin capture by specialized manufacturers. |
Research Methodology
SEC 10-K filings, customs and trade databases, and vehicle production registries formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and mining fleet maintenance directors validated demand assumptions and pricing dynamics. Triangulation across bottom-up production volume estimates and top-down expenditure flows anchored forecast confidence.
Bottom-up modeling tracked carrier shipments by material grade, installation type, and end-use segment across the projection horizon. Analytical lenses incorporated vehicle class, propulsion architecture, and regional production cluster dimensions. CAGRs derived from fitted growth curves applied to baseline volume data. Industry-specific inputs included aluminum LME price trajectories, NHTSA regulatory compliance timelines, and mining fleet replacement cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel scrap volatility, aluminum extrusion capacity expansion, and diverging regional homologation protocols. Forecasts reflect documented assumptions regarding fleet procurement consolidation rates and electric SUV platform adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Two-Wheeler Lubricants Market