
 Global Street Sweeper Market | 2026-2036
Global Street Sweeper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Street Sweeper Market Outlook
Municipal leasing programs and asset-light fleet service contracts is reconfiguring capital deployment across the competitive landscape. Bucher Municipal leverages its European manufacturing footprint to anchor premium truck-mounted sweeper supply. Aebi Schmidt sustains alpine-region specialization through purpose-built compact units for narrow municipal corridors. Zoomlion Environmental competes on domestic scale within China's urban sanitation overhaul.
Street sweepers are mobile surface-cleaning machines employing mechanical brooms, vacuum suction, and water suppression systems to remove debris, particulate matter, and contaminants from paved areas. Their primary purpose centers on maintaining air quality compliance, drainage functionality, and public safety across transportation corridors. Truck-mounted configurations dominate municipal procurement budgets due to higher productivity per labor hour, while electric power sources represent the fastest-growing segment as battery energy density improves and total cost of ownership narrows against diesel equivalents. Walk-behind units occupy stable niche demand among commercial property managers managing constrained parking structures.
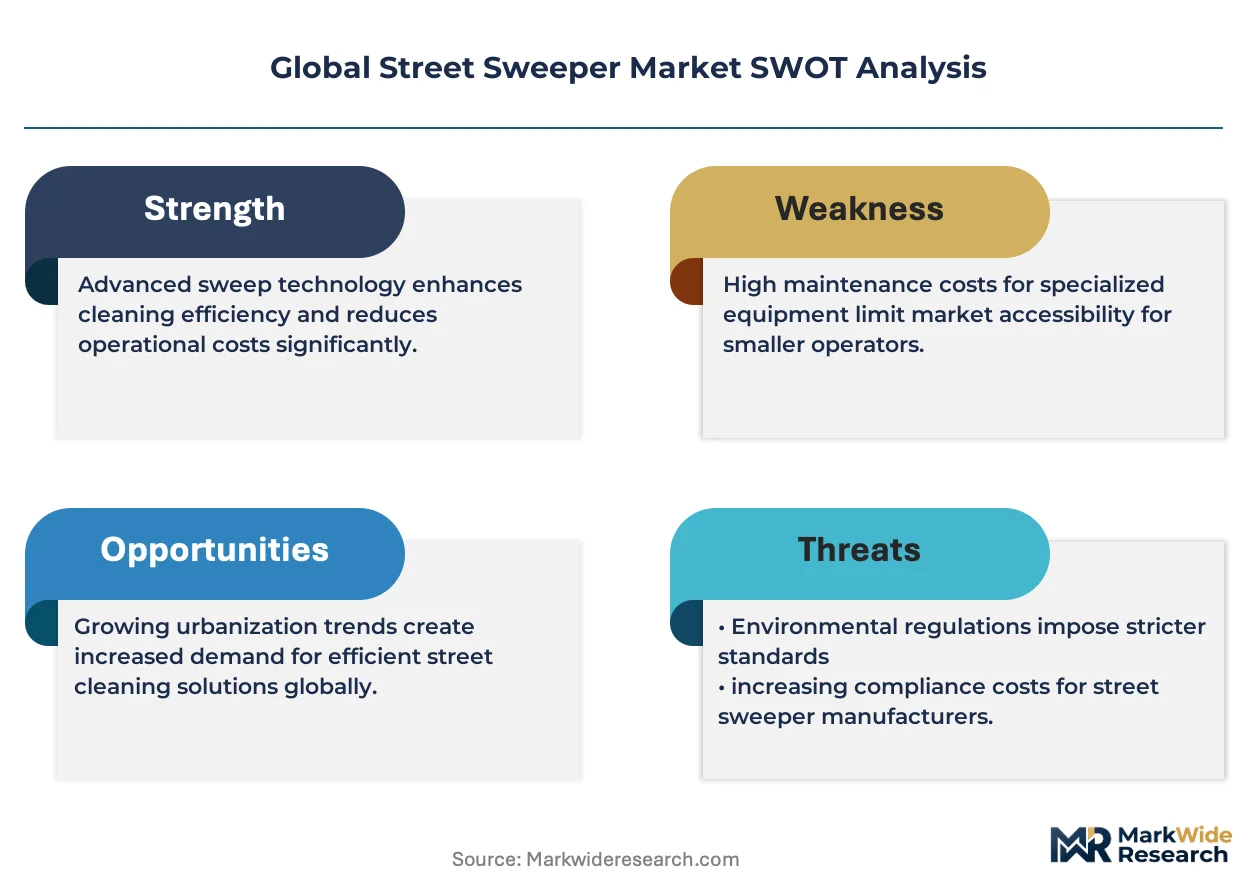
EPA emissions tiers in the United States, EU Stage V standards under the European Commission, and China's MEE air quality directives collectively mandate particulate filtration and noise reduction in urban equipment. These frameworks push OEMs toward electrified platforms and regenerative braking systems as baseline compliance. Stakeholders must monitor municipal procurement rule changes that increasingly embed lifecycle carbon accounting into contract awards.
Market Dynamics
Municipal procurement departments are accelerating fleet electrification timelines as total cost of ownership equations for battery-powered sweepers converge with diesel alternatives across European and Chinese urban contracts.
Growth Catalysts
- EU Stage V emissions mandates:Urban equipment standards in Germany, France, and the Netherlands now require particulate filtration and noise suppression, forcing diesel fleet replacements and opening contract volume for electric platforms.
- Metro expansion corridors in China:Urban rail construction in Chengdu, Wuhan, and Xi'an generates sustained demand for street surface preparation and maintenance equipment across station-adjacent districts.
- Regenerative braking systems:This technology recaptures energy during stop-start municipal routes, extending battery range and reducing charging infrastructure requirements for electric sweeper deployments.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack production for electric sweepers depends heavily on Chinese cathode material processing, exposing OEMs to export restriction risks and input cost volatility.
- Charging infrastructure gaps:Municipal depots in mid-sized US cities lack 480V fast-charging capacity, delaying electric fleet conversions despite available equipment.
- Diesel residual value collapse:Secondary markets for used diesel sweepers are contracting as resale buyers anticipate stricter emissions enforcement, trapping capital in depreciating assets.
Strategic Opportunities
- India's Smart Cities Mission:Urban sanitation infrastructure investment across 100 designated cities creates first-mover advantage for electric sweeper OEMs establishing local assembly partnerships.
- Autonomous navigation convergence:Lidar mapping combined with AI-powered obstacle detection enables overnight unmanned sweeping operations in controlled campus environments.
- Equipment-as-a-service channels:Municipal leasing platforms in Nordic countries are displacing direct capital purchases, opening recurring revenue streams for fleet operators.
Industry Challenges
- High-voltage technician scarcity:Electric powertrain maintenance requires certified specialists that municipal workshops rarely employ, forcing reliance on OEM service networks.
- Legacy fleet integration complexity:Mixed diesel-electric operations demand dual training protocols, spare parts inventories, and scheduling systems that strain sanitation department resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Street Sweeper Market |
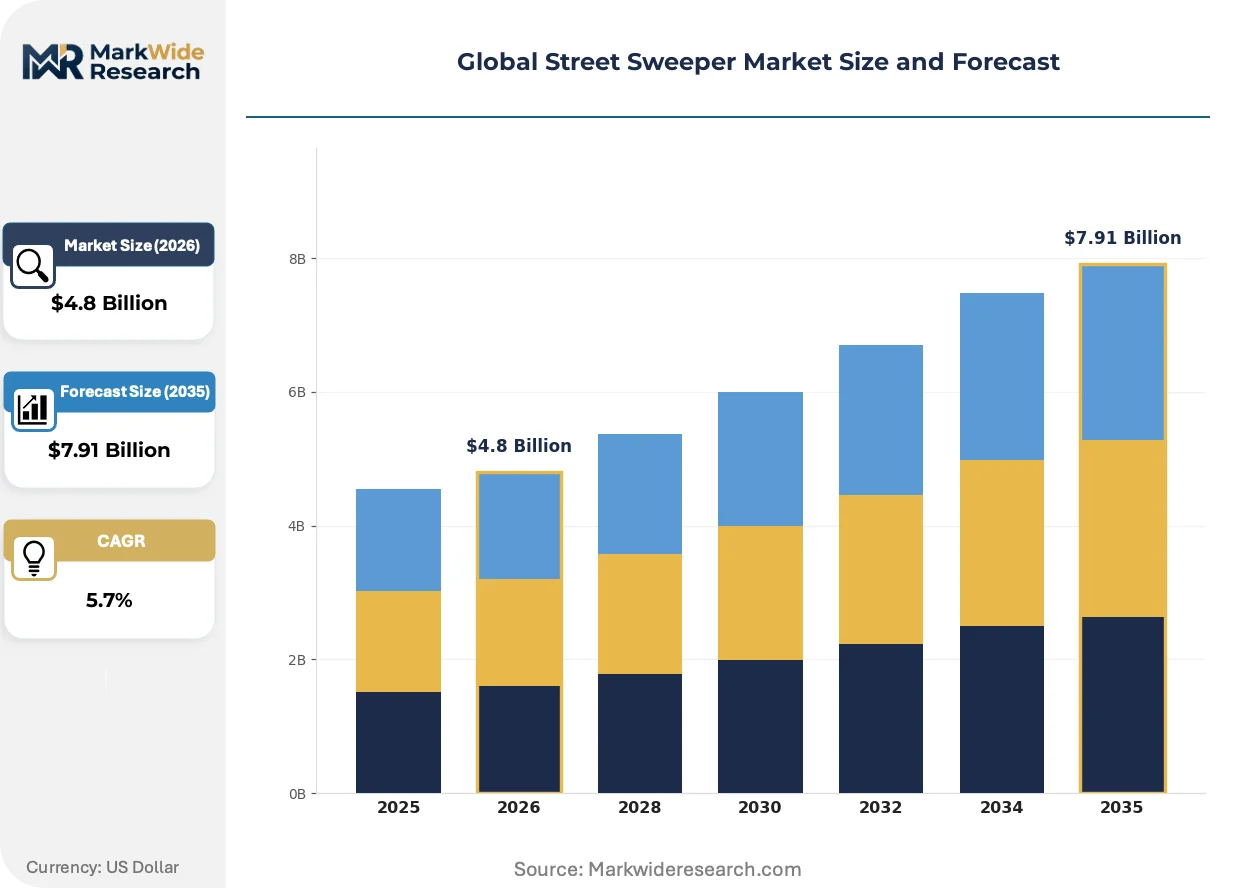
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Ride-On, Walk-Behind, Truck Mounted, Compact Power Source: Electric, Diesel, Gasoline, Hybrid End User: Municipalities, Contractors, Industrial Sites, Commercial Areas Application: Parking Lots, Streets, Airports, Public Spaces |
| Companies Covered | Bucher Municipal, Aebi Schmidt, Alamo Group, Dulevo, Elgin Sweeper, Hako, FAUN, Boschung, Zoomlion Environmental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Street Sweeper Market Strategic Shifts
Powertrain architecture is fragmenting across multiple technical pathways as municipalities balance emissions compliance against operational range requirements and charging infrastructure availability.
Hybrid diesel-electric powertrains are hybridizing municipal fleet procurement by offering transitional compliance without range anxiety. German and Dutch sanitation departments are specifying these systems for peripheral suburban routes where charging networks remain sparse. This architecture is hybridizing competitive positioning between pure-electric specialists and incumbent diesel OEMs.
China's MEE air quality directives now mandate real-time particulate emissions monitoring for urban cleaning equipment operating in designated low-emission zones. OEMs must integrate telematics-enabled exhaust sensors to maintain equipment certification. Truck-mounted sweepers in Beijing and Shanghai face the tightest enforcement windows, compressing product development cycles.
Service contract unbundling is fragmenting traditional procurement patterns. French and Belgian municipalities are separating equipment purchase from maintenance provision, awarding multi-year operational contracts to specialized fleet managers. This shift concentrates buyer power among large sanitation service providers while marginalizing smaller municipal direct purchasers.
Global Street Sweeper Market Segmentation
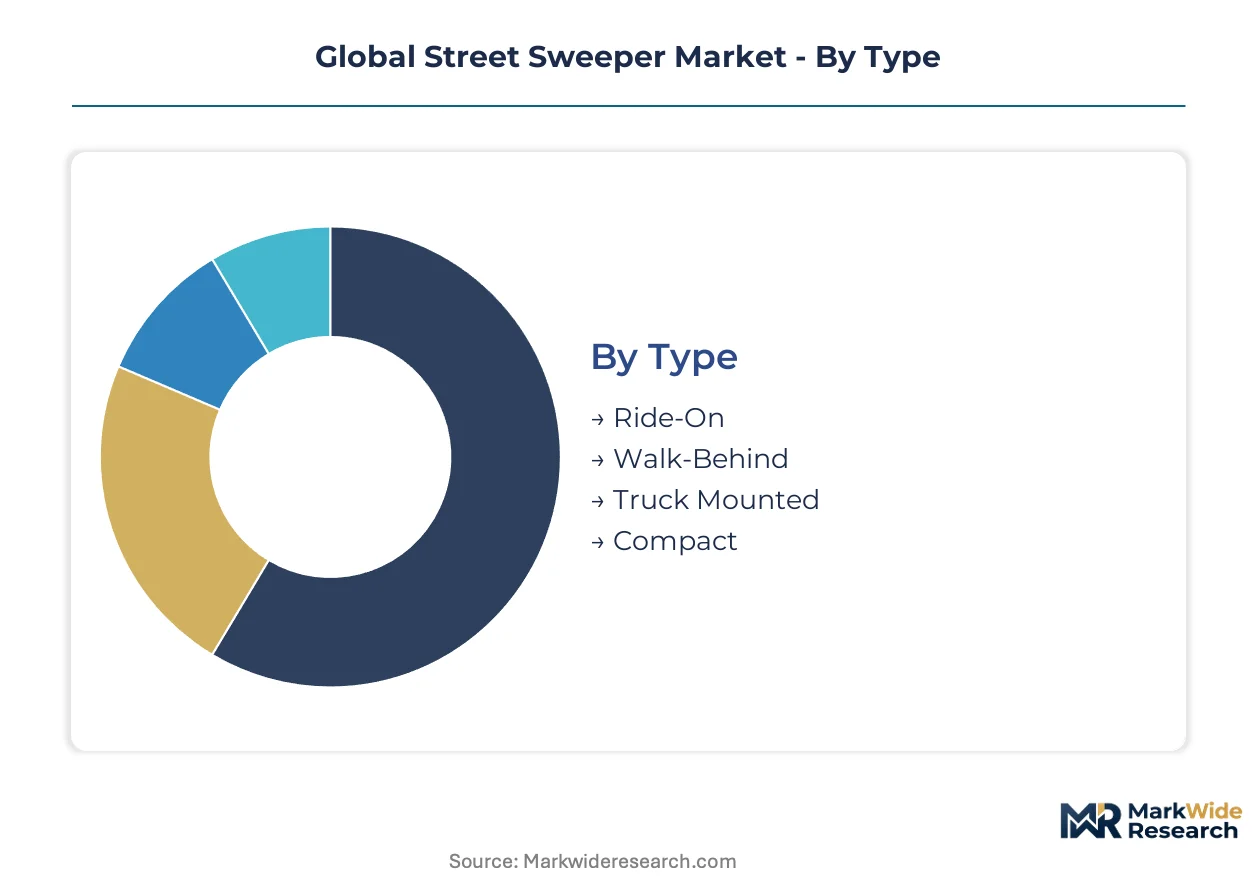
Street sweeper procurement patterns diverge sharply across equipment categories, with replacement cycles stretching from 3 years for compact urban units to 12 years for heavy truck-mounted platforms. Fleet managers prioritize total cost of ownership calculations that weight capital expenditure against labor productivity and compliance durability.
Type:
Replacement velocity varies dramatically by chassis scale, with walk-behind units cycling fastest due to intensive daily use and limited serviceability, while truck-mounted configurations endure decade-long deployment horizons.
- Truck Mounted:These heavy-duty chassis integrate vacuum suction, mechanical broom arrays, and water suppression tanks for high-volume arterial road maintenance. Municipal procurement in Germany and France concentrates here for primary route coverage, driven by EU Stage V particulate mandates forcing diesel fleet turnover.
- Compact:Purpose-built narrow-body units navigate historic European city centers and Chinese urban rail construction zones where corridor width constrains equipment selection. Alpine municipalities in Switzerland and Austria specify these for pedestrianized core districts.
- Ride-On:Mid-scale operator-positioned machines serve commercial parking structures and institutional campuses with moderate debris loads.
- Walk-Behind:Manual-guided units occupy constrained access environments including multi-level parking garages and loading docks.
Truck-mounted configurations dominate installed base value. Compact units are where expansion concentrates.
Power Source:
Cost tier stratification separates premium electric platforms from standard diesel workhorses, with hybrid systems occupying a transitional middle band as charging infrastructure matures unevenly across municipal markets.
- Electric:Battery-powered architectures employing regenerative braking and lithium-ion packs achieve total cost parity with diesel across high-utilization European and Chinese urban contracts. Shanghai and Amsterdam sanitation departments specify these for low-emission zone compliance.
- Hybrid:Diesel-electric dual-mode systems extend operational range for peripheral suburban routes in the Netherlands and Germany where fast-charging depots remain sparse. These configurations bridge compliance requirements against infrastructure reality.
- Diesel:Compression-ignition engines persist in secondary markets and developing municipal fleets prioritizing acquisition cost over lifecycle accounting.
- Gasoline:Spark-ignition powertrains occupy niche demand among small commercial contractors with intermittent usage patterns.
Diesel retains volume leadership in installed units. Electric platforms are climbing the fastest.
End User:
Customer type determines specification rigor, with municipalities imposing certification and telematics requirements that commercial operators often bypass for cost minimization.
- Municipalities:City sanitation departments mandate real-time emissions monitoring, noise suppression, and lifecycle carbon accounting in procurement contracts. China's MEE directives and EPA emissions tiers in the United States enforce equipment certification standards.
- Contractors:Private fleet operators serving multiple municipal clients under service contracts prioritize equipment flexibility and rapid deployment capability across varying route specifications.
- Industrial Sites:Manufacturing and logistics facilities specify heavy-debris capacity for metal shavings, pallet fragments, and chemical containment.
- Commercial Areas:Retail and hospitality property managers select compact ride-on units for aesthetic maintenance with minimal labor visibility.
Municipal procurement commands specification leadership. Contractor fleets are gaining share fastest.
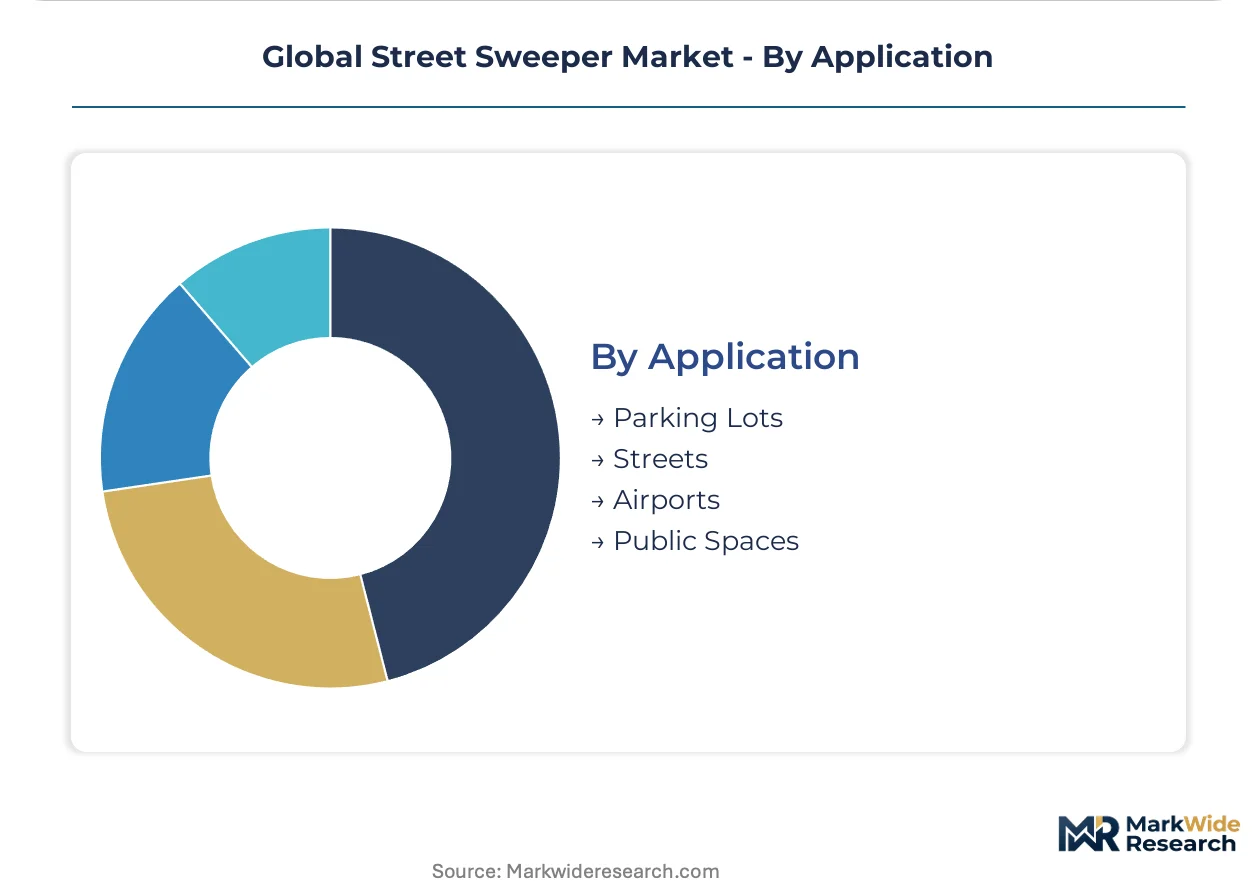
Application:
Surface characteristics and debris composition dictate equipment matching, with airports representing the most demanding specification environment due to foreign object damage risks and continuous operations requirements.
- Streets:Arterial and collector road networks generate baseline demand for high-capacity truck-mounted sweepers with curb-reaching broom configurations. Urban China metro expansion corridors in Chengdu and Wuhan sustain equipment deployment for surface preparation.
- Airports:Runway and apron cleaning demands specialized magnetic debris detection, high-speed operation capability, and 24/7 reliability certification. FAA regulations and ICAO standards govern equipment approval.
- Parking Lots:Commercial and institutional surface parking requires maneuverable compact units for oil stain removal and perimeter debris collection.
- Public Spaces:Plazas, parks, and pedestrian zones specify low-noise electric platforms for daytime operation without community disturbance.
Street applications anchor equipment volume. Airport specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and Chinese manufacturing hubs supply municipal fleets across Europe and Southeast Asia, while import dependence for lithium-ion cells shapes electrification timelines in markets lacking domestic battery processing capacity.
Germany
KBA emissions certification and municipal noise ordinances in Bavaria and North Rhine-Westphalia accelerate diesel fleet replacements. EU Stage V standards enforce particulate filtration thresholds. Stuttgart's urban sanitation department specifies low-noise electric platforms for nighttime historic district operations.
China
Metro expansion in Chengdu, Wuhan, and Xi'an generates sustained equipment demand for surface preparation and maintenance. MEE air quality directives mandate real-time emissions monitoring in Beijing and Shanghai low-emission zones. Yangtze River Delta manufacturing clusters supply compact units for narrow corridor navigation.
United States
EPA emissions tiers drive fleet turnover in California and Northeast corridor states with tightening particulate rules. FAA regulations govern specialized runway cleaning equipment procurement. Municipalities in Texas and Florida prioritize truck-mounted configurations for highway debris clearance.
Netherlands
Amsterdam and Rotterdam sanitation departments specify electric platforms for inner-city low-emission zones. National procurement frameworks embed lifecycle carbon accounting into contract awards. Randstad urban clusters deploy hybrid systems for peripheral suburban routes with sparse charging infrastructure.
India
Smart Cities Mission sanitation infrastructure investment across designated urban centers creates equipment demand. BIS certification requirements shape import specifications for municipal procurement. Delhi-NCR and Maharashtra state municipalities pilot electric fleet segments in designated clean air zones.
Global Street Sweeper Market Competitive Environment
On the supply side, the industry is consolidating around specialized manufacturing footprints and electrification capabilities. European and Chinese production bases anchor distinct competitive spheres. Three archetypes dominate: premium truck-mounted specialists, compact urban equipment fabricators, and scale-driven domestic suppliers. Capacity expansion in battery pack assembly and strategic partnerships for charging infrastructure deployment represent the primary competitive vectors.
Among European-headquartered specialists, Bucher Municipal and Aebi Schmidt exemplify differentiated positioning through manufacturing footprint specialization. Zoomlion Environmental represents the scale-driven archetype serving domestic Chinese municipal procurement. These three occupy positions across distinct geographic and product-tier segments without overlapping strategic territory.
| Leading Market Players |
|---|
| Bucher Municipal |
| Aebi Schmidt |
| Alamo Group |
| Dulevo |
| Elgin Sweeper |
| Hako |
| FAUN |
| Boschung |
| Zoomlion Environmental |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European lithium-ion cell fabrication is compressing supplier margins and forcing OEMs toward longer-term contract structures that lock in pricing stability across multi-year municipal procurement cycles.
Pricing Analysis
Municipal fleet buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates EU Stage V-certified electric platforms from transitional hybrid systems and legacy diesel units, with certification tier and battery energy density as primary drivers. Cost compression in the economy tier is intensifying because Chinese OEMs are scaling compact electric production for domestic urban sanitation overhauls. Contractor fleets exhibit highest price sensitivity due to thin service margins, while airport authorities show lowest sensitivity given foreign object damage liability exposure.
Supply Chain Analysis
Export controls on cathode material processing technology are constraining battery pack assembly expansion outside China, South Korea, and Japan. Supply draws from Yangtze River Delta manufacturing clusters for compact chassis, German component suppliers for precision hydraulic systems, and South Korean cell fabricators for high-density lithium-ion packs. Single-source vulnerability concentrates in Chinese cathode precursor supply, exposing OEMs to MIIT export license delays. Distribution runs through municipal procurement frameworks in Europe and fleet leasing platforms in Nordic countries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracts are expanding faster than hardware sales as Nordic municipalities displace direct capital purchases with multi-year operational agreements bundling maintenance and telematics.
For Market Incumbents: Pre-empt pure-electric specialists by securing exclusive battery supply agreements with South Korean cell producers and embedding regenerative braking IP into municipal specification templates. Defend against Chinese scale players by anchoring premium truck-mounted positions through KBA emissions certification and Stuttgart-style low-noise historic district deployments. For New Entrants and Emerging Players: Build out local assembly partnerships in India's Smart Cities Mission designated urban centers before incumbent OEMs establish service networks. Target mid-sized US municipal fleets facing charging infrastructure gaps with hybrid diesel-electric offerings that bridge compliance requirements against depot capacity constraints. Lead with equipment-as-a-service pricing to bypass capital budget limitations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet operators controlling municipal service contracts across multiple European jurisdictions. Long-term viability centers on OEMs with captive battery pack assembly and telematics-enabled emissions monitoring capabilities. Watch for MEE directive enforcement windows in Beijing and Shanghai as inflection indicators for Chinese electric fleet penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in lithium-ion cell access ahead of municipal electrification procurement waves. |
| Equipment-as-a-Service Launch | Captures recurring revenue from Nordic municipalities displacing direct capital purchases. |
| Regenerative Braking Integration | Extends electric range for stop-start urban routes, reducing charging infrastructure requirements. |
| Local Assembly Partnership | Positions OEMs for India's Smart Cities Mission sanitation infrastructure investment. |
| Telematics Certification Investment | Enables real-time emissions monitoring compliance under China's MEE air quality directives. |
Study Parameters
Cross-validation between municipal procurement officer interviews and OEM sales director assessments anchors the qualitative findings. Primary fieldwork encompassed sanitation department fleet managers, aftermarket service heads, battery pack procurement leads, and municipal leasing platform operators. Secondary validation drew from KBA emissions certification databases, EPA equipment registration filings, MEE low-emission zone enforcement notices, and municipal contract award disclosures. Bottom-up unit deployment estimates were triangulated against top-down market value reconstruction.
Calibration against historical replacement cycle data and announced metro expansion timelines shaped the projection framework. Segmentation modeling spanned chassis type, powertrain architecture, end-user procurement mode, and regional regulatory cluster. CAGRs were derived from fitted trend lines across equipment category growth rates, with explicit inputs for battery energy density improvement curves and EU Stage V compliance cost pass-through assumptions.
Stress conditions across lithium export restriction severity, municipal budget contraction scenarios, and charging infrastructure deployment pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet electrification timeline convergence and hybrid system transitional demand persistence. Material shifts in Chinese cathode material export licensing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
US Car Wash Services Market
Automotive Services
Qatar Car Rental Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Automotive Register Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Americas MAP Market
Automotive Services
Car Subscription Market
Automotive Services
Automatic Tire Changer Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Europe Car Wash Market
Automotive Services
Driver's License Market