
 Automotive Remanufactured Parts Market | 2026-2036
Automotive Remanufactured Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Remanufactured Parts Market Insights
Aftermarket service revenue is rewriting how suppliers capture lifetime value from vehicle populations. Robert Bosch GmbH leverages its captive remanufacturing network across Europe and North America to control quality standards and channel access. BorgWarner anchors its position in turbocharger remanufacturing through direct OEM partnerships, while Cardone Industries dominates independent aftermarket distribution with broad coverage of brake and electrical categories.
Automotive remanufactured parts constitute components restored to original equipment specifications through disassembly, cleaning, inspection, replacement of worn elements, and reassembly with performance testing equivalent to new production. The process typically achieves energy savings versus new manufacturing while meeting OEM warranty thresholds for functionality and durability. Engine Components and Transmission Parts command the largest share of current value pools given their high replacement costs and established remanufacturing infrastructure. Electrical Systems represent the fastest-expanding category as hybrid and electric vehicle power electronics create new refurbishment requirements, while Brake Systems maintain steady aftermarket volume across both passenger and commercial vehicle fleets.
The EPA regulates remanufactured automotive components under emission compliance frameworks that distinguish between new production and certified rebuilt assemblies, while NHTSA oversees safety-critical system standards for brake and steering remanufacturing. ISO 14001 environmental management certifications increasingly shape supplier qualification for OEM remanufacturing contracts in North America and Europe. Stakeholders must monitor how battery electric vehicle architectures redefine which component categories remain economically viable for remanufacturing versus replacement.
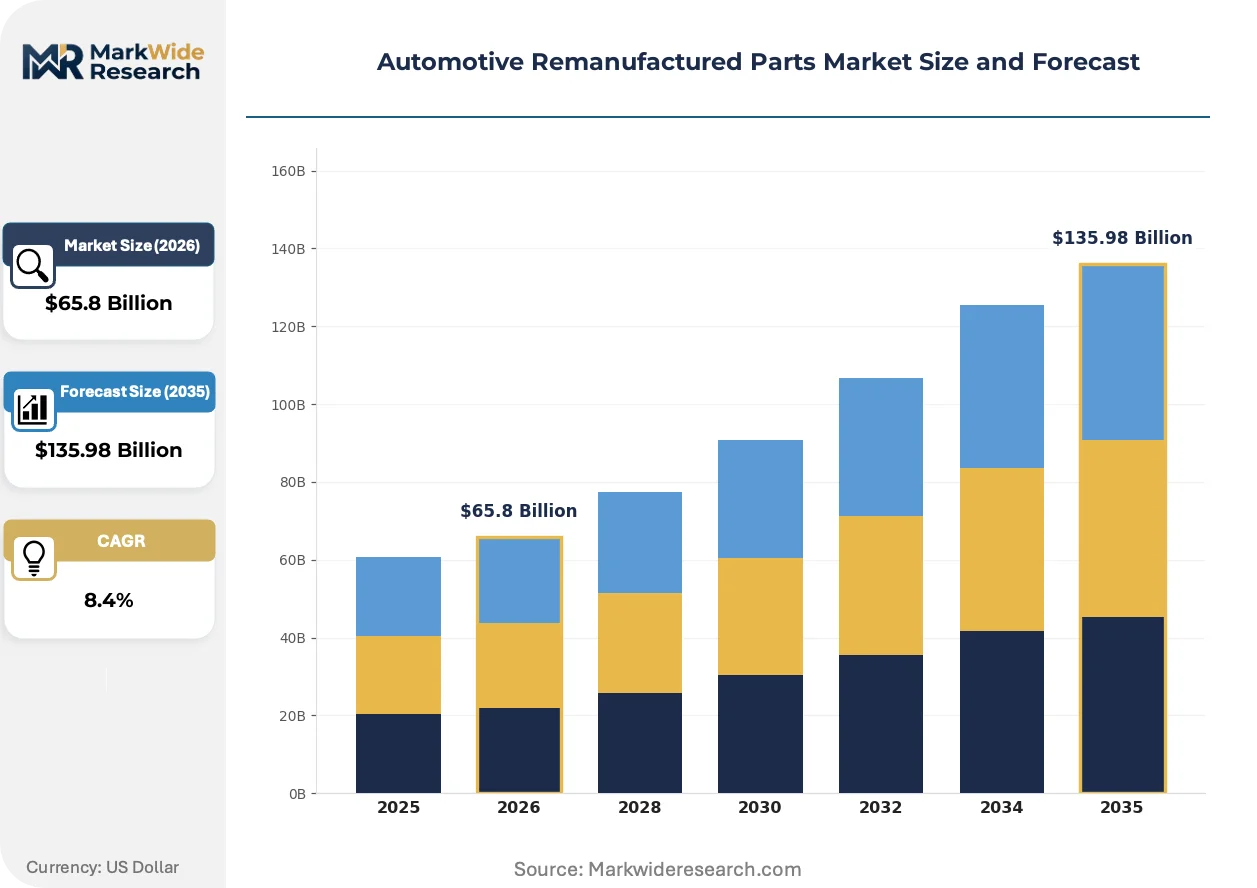
Market Dynamics
Fleet operators now mandate remanufactured brake and transmission components to compress total cost of ownership, while EPA emission compliance windows for medium and heavy-duty vehicles favor rebuilt assemblies over new production cycles.
Growth Catalysts
- EPA emission standards:Tighter compliance windows for new versus remanufactured component life cycles create regulatory preference for certified rebuilt assemblies in medium and heavy-duty vehicle categories.
- Fleet procurement mandates:Commercial vehicle operators in the United States are expanding volume commitments to remanufactured powertrain components to reduce lifecycle maintenance expenditure.
- ISO 14001 certification:Environmental management standards increasingly gate OEM remanufacturing contracts, pushing independent suppliers toward certified process upgrades.
Market Restraints
- Core availability volatility:Used component cores represent the primary input cost, with supply concentration in aging vehicle populations creating price instability for transmission and engine rebuilders.
- Electric vehicle substitution:Battery electric architectures eliminate traditional remanufacturing categories including turbochargers and internal combustion engine components.
- NHTSA safety certification:Extended testing protocols for brake and steering system remanufacturing create timeline friction versus aftermarket replacement part channels.
Strategic Opportunities
- Power electronics refurbishment:Hybrid and electric vehicle inverter and converter modules represent emerging remanufacturing categories with limited established competition.
- Independent aftermarket channel consolidation:Direct distribution partnerships with national service chains bypass traditional jobber networks for brake and electrical categories.
- EU Green Deal circularity mandates:Extended producer responsibility frameworks in European member states create regulatory pull for OEM-certified remanufacturing programs.
Industry Challenges
- Diagnostic technician scarcity:Power electronics remanufacturing requires specialized training in high-voltage systems and semiconductor failure analysis that existing mechanical workforces lack.
- Cross-border core logistics:International shipment of used component cores faces customs classification complexity and environmental handling code disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Remanufactured Parts Market |
| Market Size in 2026 | $65.8 Billion |
| Market Size in 2035 | $135.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Brake Systems, Electrical Systems End User: OEMs, Aftermarket Providers, Independent Repair Shops, Fleet Operators Technology: Additive Manufacturing, CNC Machining, Surface Treatment, Assembly Techniques Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Auction Platforms |
| Companies Covered | Robert Bosch GmbH, BorgWarner, ZF Friedrichshafen AG, Denso Corporation, Valeo SA, Cardone Industries, Motorcar Parts of America, Eaton Corporation, Meritor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Remanufactured Parts Market Trends and Innovations
Digital inspection and additive repair technologies are compressing remanufacturing cycle times while expanding the range of components economically viable for restoration to OEM specifications.
Automated optical scanning and AI-driven defect detection systems are virtualizing quality assurance workflows in remanufacturing facilities. Tier-1 suppliers in Germany and the United States are deploying these systems at scale for transmission assembly inspection. The technology is virtualizing traditional manual teardown and measurement processes, reducing skilled labor dependency while tightening variance control.
REACH substance restrictions in the European Union are prohibiting specific cleaning chemistries and surface treatments historically standard in component restoration. Remanufacturers must reformulate process flows or source compliant alternatives from qualified chemical suppliers. Brake system rebuilders face the steepest adaptation costs given legacy reliance on solvent-based degreasing protocols.
Service contract unbundling is separating component remanufacturing from installation labor in fleet maintenance agreements. National leasing companies in the United States now specify remanufactured part tiers independently from service provider selection. This pattern concentrates volume with certified remanufacturers capable of direct warranty fulfillment rather than channel intermediaries.
Automotive Remanufactured Parts Market Segmentation
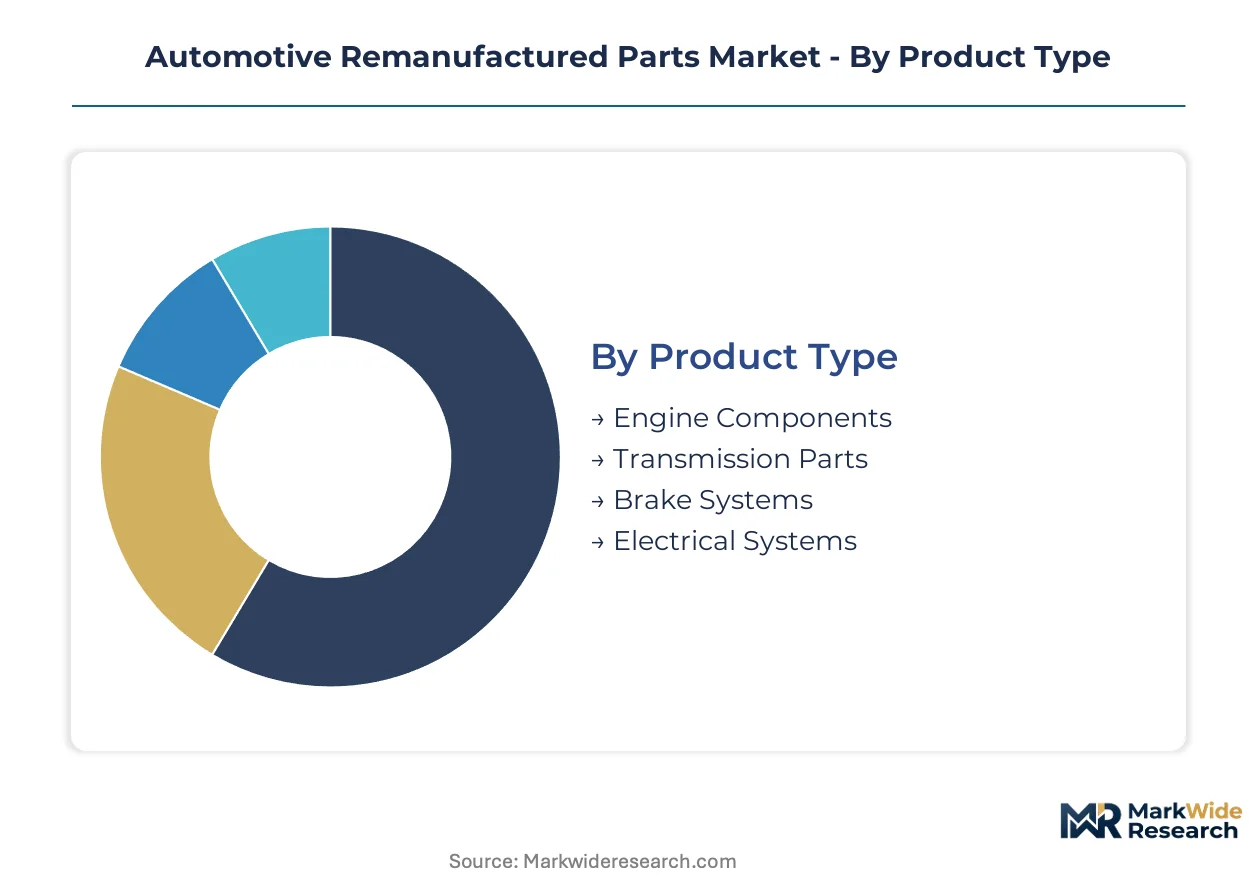
Remanufactured parts markets fragment across product lifecycles, procurement authority, and technical restoration methods. Understanding these divides exposes where margin pools concentrate and which customer relationships lock in recurring volume.
Product Type:
Mature mechanical assemblies anchor current revenue while electrification creates new refurbishment categories.
- Engine Components:Cylinder heads, blocks, and crankshafts undergo thermal cleaning, machining to OEM tolerances, and pressure testing. Fleet operators in the United States source these through long-term maintenance contracts to compress lifecycle costs. Core availability volatility constrains rebuilder margins as aging vehicle populations thin.
- Transmission Parts:Gear sets, torque converters, and valve bodies require precision measurement and selective component replacement. Independent aftermarket distributors in Germany and the United States dominate procurement channels for automatic transmission rebuilds. The EPA's emission compliance windows for medium and heavy-duty vehicles favor rebuilt over new assemblies.
- Brake Systems:Calipers, master cylinders, and ABS modules constitute steady aftermarket volume across passenger and commercial fleets.
- Electrical Systems:Alternators, starters, and emerging power electronics for hybrid vehicles represent the steepest expansion trajectory as electrification extends refurbishment requirements.
Engine Components retain volume leadership; Electrical Systems holds the steepest expansion curve.
End User:
Procurement authority separates warranty-backed volume from price-sensitive spot purchasing.
- OEMs:Certified remanufacturing programs control quality thresholds and channel access for powertrain categories. Ford and General Motors operate captive networks that specify process standards and core return logistics. ISO 14001 certification gates contract eligibility for Tier-1 supplier status.
- Fleet Operators:National leasing companies and commercial vehicle aggregators mandate remanufactured brake and transmission components in maintenance agreements. These contracts separate component procurement from installation labor, concentrating volume with direct warranty fulfillers.
- Aftermarket Providers:Jobber networks and national service chains intermediate between rebuilders and installation points.
- Independent Repair Shops:Single-location mechanics source through wholesale distributors on price and immediate availability.
Fleet Operators command the largest committed volume; OEMs maintain the tightest quality specifications.
Technology:
Restoration methods span subtractive machining, additive repair, and precision assembly disciplines.
- CNC Machining:Computer-controlled cutting restores dimensional tolerances on engine blocks, cylinder heads, and transmission housings. German and United States facilities deploy five-axis systems for complex geometry restoration. REACH substance restrictions in the European Union force reformulation of cutting fluids and cleaning chemistries.
- Additive Manufacturing:Directed energy deposition repairs worn surfaces on high-value components without full replacement. Tier-1 suppliers pilot these methods for turbine blade and gear tooth restoration. Process qualification for OEM warranty acceptance remains incomplete.
- Surface Treatment:Thermal spraying and coating processes rebuild bearing surfaces and seal journals.
- Assembly Techniques:Automated torque control and end-of-line testing validate rebuilt unit performance against new production benchmarks.
CNC Machining dominates current throughput; Additive Manufacturing carries the highest technical upside.
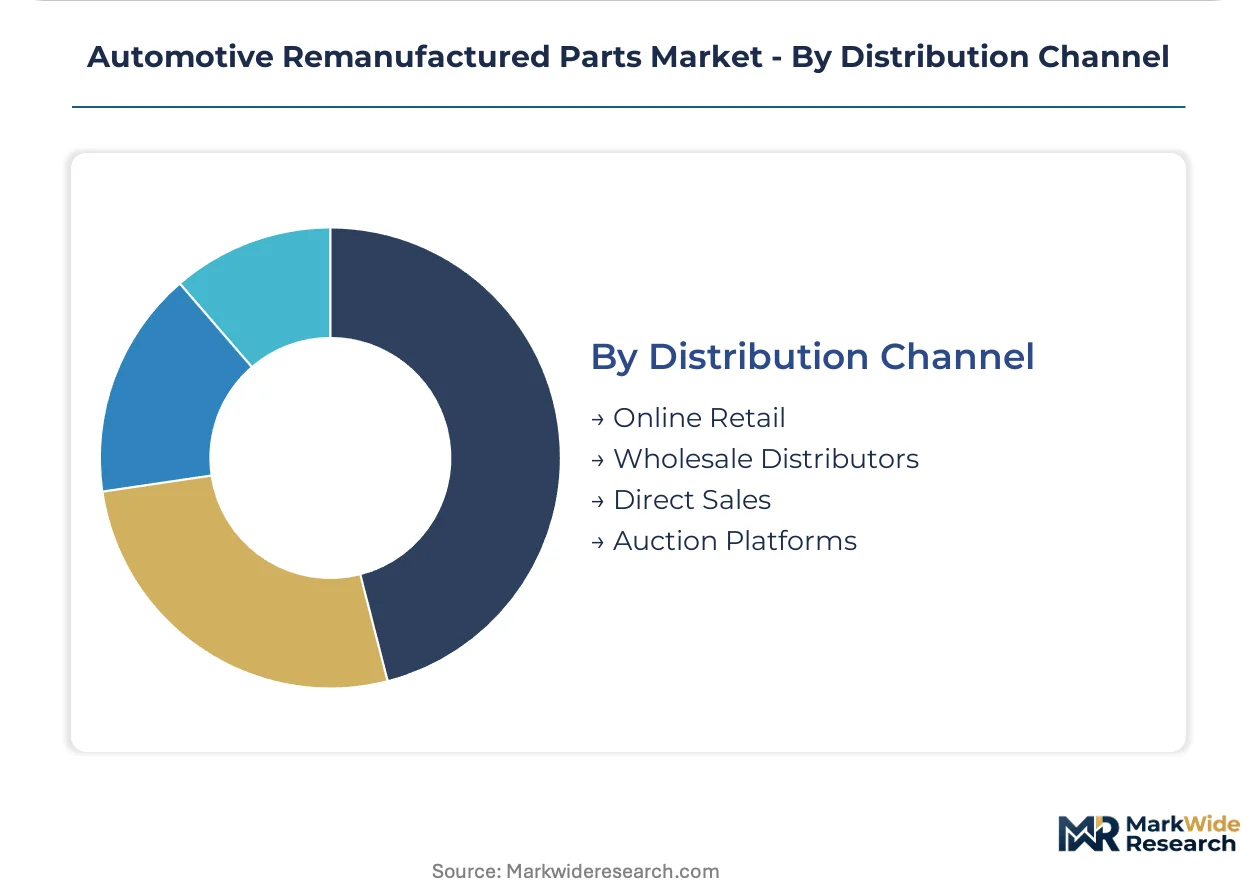
Distribution Channel:
Channel selection determines margin capture and customer relationship depth.
- Wholesale Distributors:Traditional jobber networks aggregate demand from independent repair shops and small fleet garages. Cardone Industries and similar suppliers anchor shelf presence through breadth of brake and electrical coverage. Inventory carrying costs and core return logistics compress net margins.
- Direct Sales:OEM-certified remanufacturers and large independent rebuilders bypass intermediaries for national fleet accounts and service chain partnerships. Robert Bosch GmbH leverages this channel across Europe and North America to control quality standards.
- Online Retail:E-commerce platforms enable price comparison and direct-to-installer procurement for standard catalog items.
- Auction Platforms:Secondary markets liquidate surplus cores and refurbished inventory to regional rebuilders.
Wholesale Distributors retain the broadest reach; Direct Sales captures the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Remanufacturing capacity clusters in Germany, the United States, and China, with each geography leveraging distinct regulatory and industrial foundations to capture value from circular economy mandates.
United States
Fleet operators in the United States mandate remanufactured brake and transmission components to compress total cost of ownership across commercial vehicle populations. The EPA regulates remanufactured automotive components under emission compliance frameworks that distinguish between new production and certified rebuilt assemblies. Detroit and the broader Midwest industrial corridor host dense concentrations of powertrain remanufacturing facilities serving domestic OEM-certified programs.
Germany
German Tier-1 suppliers deploy automated optical scanning and AI-driven defect detection systems at scale for transmission assembly inspection. REACH substance restrictions prohibit specific cleaning chemistries and surface treatments historically standard in component restoration, forcing process reformulation. The Stuttgart and Munich metropolitan regions anchor captive remanufacturing networks that control quality standards and channel access across Europe.
China
Chinese remanufacturers face expanding refurbishment requirements as hybrid and electric vehicle power electronics create new category demand. The Ministry of Industry and Information Technology oversees standards development for automotive component remanufacturing under national circular economy promotion policies. The Yangtze River Delta industrial cluster concentrates precision machining capacity for engine block and cylinder head restoration serving domestic and export markets.
Japan
Japanese suppliers specialize in high-precision electrical system remanufacturing for alternators, starters, and emerging hybrid vehicle components. METI coordinates industry-wide initiatives to extend producer responsibility frameworks and promote certified rebuilt assembly channels. The Nagoya industrial corridor in the Chubu region maintains advanced torque converter and valve body remanufacturing operations integrated with Toyota and Honda supply networks.
India
Indian aftermarket distributors expand procurement of remanufactured engine components as aging vehicle populations sustain core availability for transmission and brake rebuilders. The Bureau of Indian Standards develops technical specifications for automotive remanufacturing processes to support formal sector growth. The Chennai-Bengaluru industrial corridor in southern India clusters independent remanufacturing operations serving commercial vehicle fleets and export markets.
Automotive Remanufactured Parts Market Competitive Landscape
OEM-captive networks and independent aftermarket specialists split the market into distinct quality-tier segments with divergent channel strategies. Tier-1 automotive suppliers operate certified remanufacturing programs that gate contract eligibility through ISO 14001 environmental management certification. Three archetypes dominate: multinational OEM affiliates controlling powertrain categories, independent volume distributors anchoring brake and electrical coverage, and emerging specialists targeting hybrid-electric power electronics. Competitive moves concentrate on direct fleet partnerships bypassing traditional jobber networks and additive manufacturing pilot programs for high-value component restoration.
Within the OEM-affiliate tier, Robert Bosch GmbH and BorgWarner exemplify the captive network model, with the former leveraging direct distribution across Europe and North America to control quality standards. Among independent aftermarket distributors, Cardone Industries occupies a position representing broad-coverage brake and electrical specialists. These three companies anchor the competitive structure, with each archetype pursuing distinct margin capture strategies through channel selection and certification depth.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| BorgWarner |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Valeo SA |
| Cardone Industries |
| Motorcar Parts of America |
| Eaton Corporation |
| Meritor Inc. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in German transmission remanufacturing facilities is compressing supplier margins while simultaneously enabling aggressive pricing postures for OEM-certified rebuilders seeking volume commitments from United States fleet operators.
Pricing Analysis
After-sales service revenue tiers drive lifetime value capture across the automotive remanufactured parts sector. Three-tier pricing structure across OEM-certified premium, independent aftermarket standard, and unbranded economy levels segments buyer access. Price differentiation hinges on ISO 14001 certification status and core return logistics bundling. Cost compression in standard-tier brake and electrical categories is intensifying because wholesale distributors compete on immediate availability. Independent repair shops exhibit the highest price sensitivity, while national fleet operators prioritize warranty-backed direct procurement over unit cost.
Supply Chain Analysis
Export-control regimes on advanced semiconductor testing equipment limit flows into Chinese power electronics remanufacturing facilities. Supply concentrates in Germany, the United States, and China for precision machining capacity and core aggregation networks. The industry draws from used component cores, high-grade steel alloys, and specialized cleaning chemistries as primary inputs. Single-source vulnerability in core availability from aging United States vehicle populations threatens transmission rebuilder input stability. Distribution runs through OEM-certified direct sales channels for fleet accounts and wholesale jobber networks for independent aftermarket access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
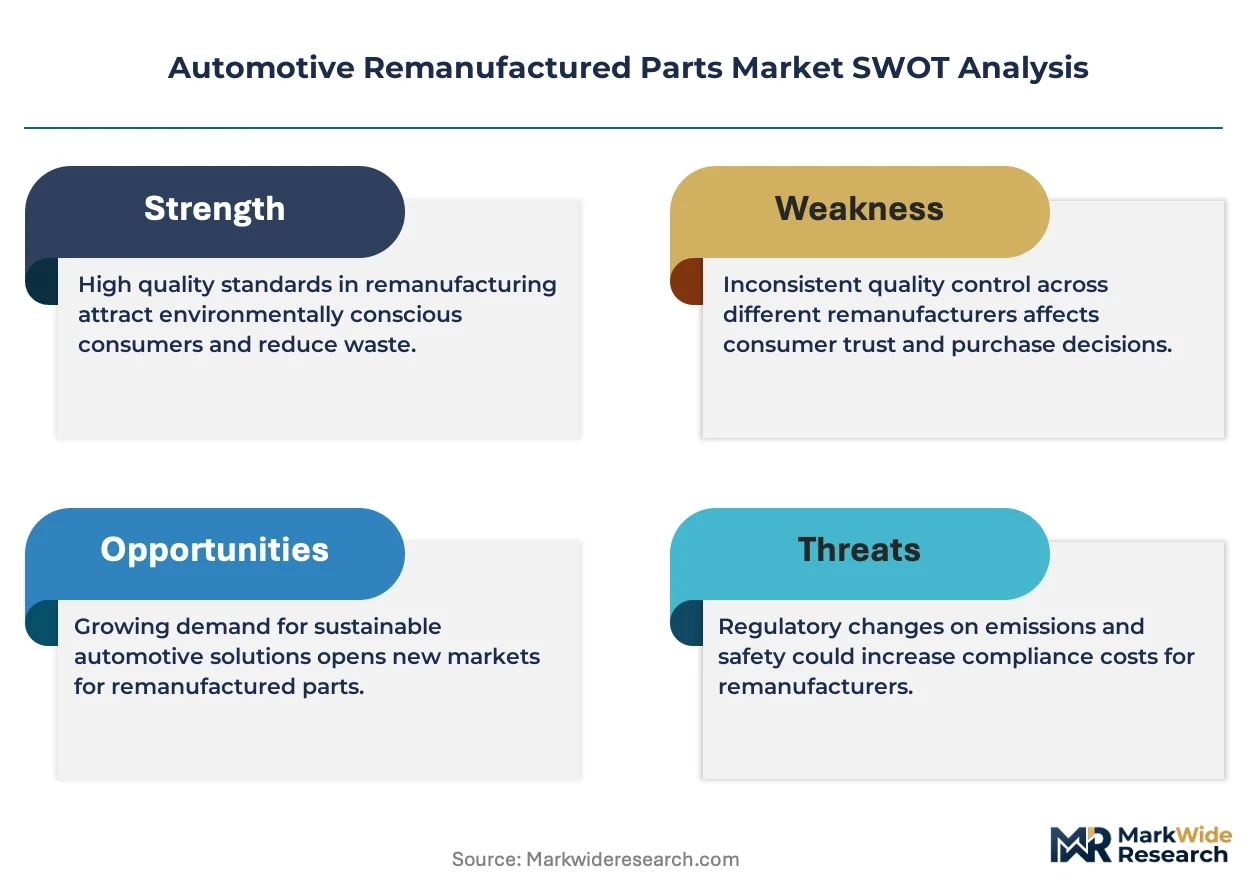
The automotive remanufactured parts market constitutes a defensive-moat story anchored in regulatory entrenchment: EPA emission compliance windows and ISO 14001 certification requirements create structural barriers that incumbent OEM-affiliated networks exploit to lock out unqualified competitors.
For Market Incumbents: Build certification moats by deepening ISO 14001 process coverage into emerging power electronics categories before REACH substance restrictions expand. Secure captive core return logistics through direct fleet partnerships, neutralizing the core availability volatility that threatens independent rebuilders. Capacity addition in the Yangtze River Delta industrial cluster hedges against tariff exposure on precision machining equipment. For New Entrants and Emerging Players: Hybrid vehicle inverter refurbishment in the United States represents the most penetrable entry point given diagnostic technician scarcity among incumbent mechanical workforces. Power electronics remanufacturing for commercial vehicle charging infrastructure offers a second white-space target with limited established competition. A go-to-market angle anchored in high-voltage systems training partnerships with technical institutes bypasses the certification barriers that gate OEM contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across power electronics refurbishment sub-segments as semiconductor failure analysis equipment requirements escalate. The five-to-ten year viability window favors acquisition targets with established core logistics networks and EPA-certified process documentation. The signal to watch is NHTSA rulemaking on safety-critical system remanufacturing timelines, which would accelerate consolidation pressure on independent brake system rebuilders.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Fleet Partnership Formation | Bypasses wholesale jobber networks, concentrating volume with warranty-capable rebuilders like Bosch-certified facilities. |
| Additive Manufacturing Process Qualification | Directed energy deposition for gear tooth restoration awaits OEM warranty acceptance to unlock high-value component tiers. |
| Power Electronics Refurbishment Scale-Up | Hybrid inverter modules represent emerging categories with limited competition and steep EPA compliance barriers. |
| Core Logistics Network Integration | Cross-border used component flows face customs complexity that integrated operators can arbitrage through regional hubbing. |
| EU Green Deal Circularity Compliance | Extended producer responsibility frameworks in member states pull OEM-certified programs ahead of independent aftermarket distributors. |
Research Methodology
Desk research of EPA regulatory filings, ISO certification databases, and vehicle production statistics preceded structured interviews with Tier 1 supplier procurement leads, aftermarket distributor operations heads, fleet maintenance directors, and remanufacturing facility engineers. Primary fieldwork combined with secondary validation from NHTSA safety standards documentation and REACH substance restriction notices. Bottom-up volume modeling across component categories triangulated against top-down market sizing from trade association data.
Assumptions held fixed include EPA emission compliance window differentials and ISO 14001 contract gating prevalence, while electric vehicle penetration rates and core availability indices were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, end-user procurement authority, restoration technology, and distribution channel structure. CAGRs derived from regression analysis of historical replacement part demand against vehicle-in-operation populations. Forecast inputs incorporated fleet operator maintenance contract unbundling trends and power electronics failure rate projections.
Macroeconomic conditions sit as an overlay; deviation in commercial vehicle utilization rates or steel alloy pricing would shift the trajectory. Forecasts reflect these documented assumptions. Material shifts in battery electric vehicle architecture standardization or NHTSA remanufacturing certification protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Surface Coated Brake Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Odometer Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
Gearshift Sleeves Market