
 Vehicles for Disabled Market | 2026-2036
Vehicles for Disabled Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicles for Disabled Market Intelligence
Consolidation among specialized vehicle converters in North America and Europe is restructuring the competitive landscape. BraunAbility leverages its extensive dealer network across North America to maintain a dominant market position. VMI specializes in side-entry minivan conversions with innovative ramp systems, competing on engineering and accessibility features. Meanwhile, Freedom Motors USA differentiates its offerings through a focus on rear-entry conversions for a wider range of SUV and crossover chassis.
Vehicles for disabled are automobiles structurally modified to accommodate physical limitations, involving lowered floors and the installation of certified ramps or lifts. These adaptations enable independent mobility for personal transportation, medical transport, and community service applications. Wheelchair Vans continue to dominate the vehicle type category, offering the most space and flexibility for various user needs. Among end users, Individuals with Disabilities constitute the primary buyer group, though procurement from Elder Care Providers is accelerating.
Safety and compliance are governed by a patchwork of national and regional standards. In the United States, modifications must adhere to Federal Motor Vehicle Safety Standards enforced by the NHTSA, while in Europe, converters must meet CE marking requirements for medical devices and vehicle safety. Navigating the transition to electric vehicle platforms while maintaining accessibility and safety compliance presents the central challenge for vehicle modifiers.
Market Dynamics
The core tension in the vehicles for disabled market is the engineering conflict between the transition to electric vehicle platforms and the structural requirements of accessibility modifications. The industry must innovate around floor-mounted battery packs that interfere with traditional lowered-floor conversions.
Growth Catalysts
- Accessibility Mandates:Legislation like the Americans with Disabilities Act (ADA) in the United States and similar frameworks in Europe create a baseline demand by requiring accessible transportation options in public and commercial services.
- Demographic Shifts:Aging populations in developed nations, particularly Japan and Germany, are expanding the Senior Mobility segment, which constitutes a significant and growing user base for modified personal vehicles.
- Ramp and Lift Technology:Innovations in lightweight composite materials and automated, remote-controlled deployment systems for ramps and lifts are improving vehicle usability and reducing the physical effort required for operation.
Market Restraints
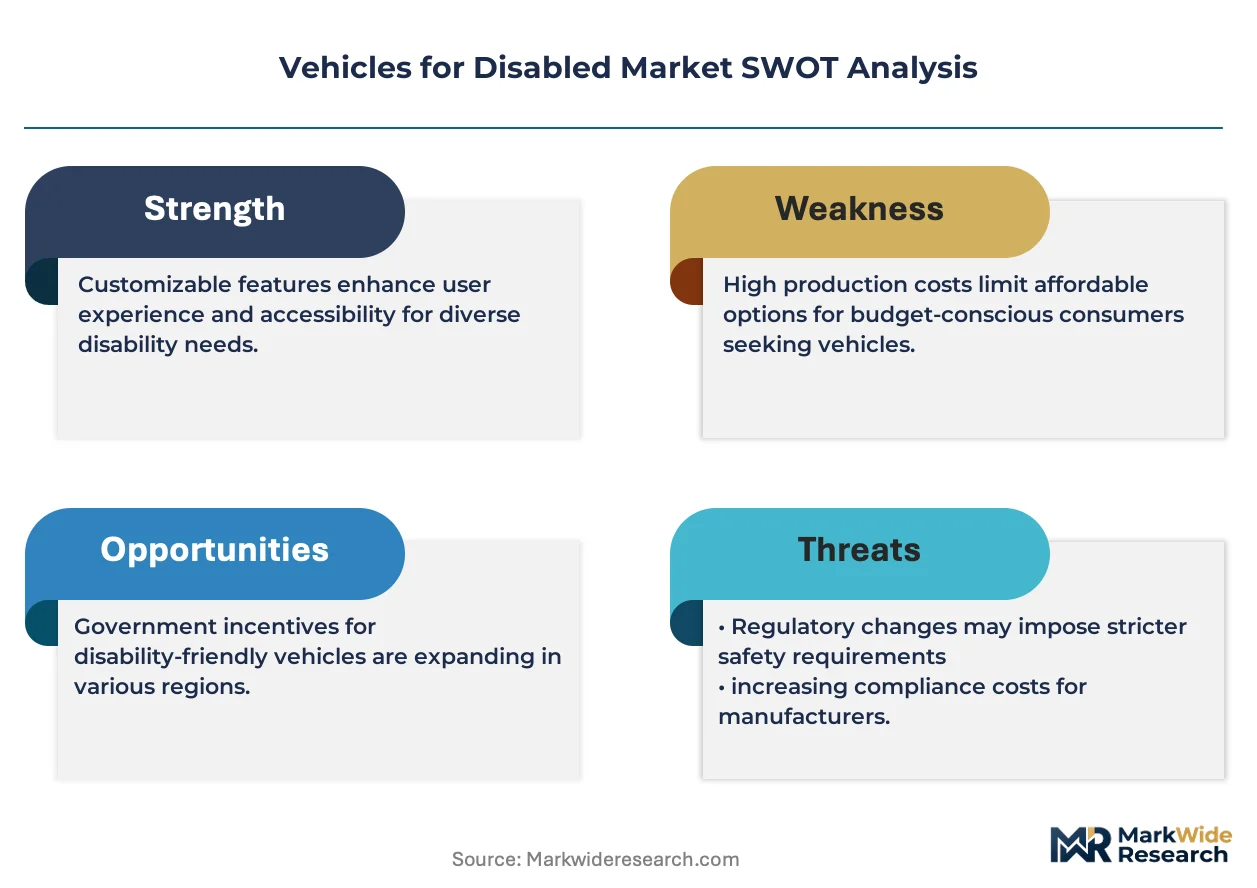
- High Conversion Costs:The extensive structural engineering, specialized components, and skilled labor involved result in a final vehicle price that is often prohibitive for many individuals and families without subsidies or insurance support.
- Regulatory Fragmentation:Converters face a complex and costly patchwork of safety standards, from NHTSA crashworthiness requirements in the U.S. to CE marking for medical devices on lifts within the European Union.
- Vehicle Platform Constraints:The increasing use of unibody construction and the unique chassis designs of electric vehicles present significant technical hurdles for implementing traditional lowered-floor and side-entry modifications.
Strategic Opportunities
- SUV and Crossover Conversions:Expanding modification services to a wider range of popular SUV and crossover models addresses consumer demand for less conspicuous and more versatile accessible vehicles beyond traditional minivans.
- Autonomous Driving Integration:Incorporating Level 2 and Level 3 autonomous driving features can provide new levels of independence for users with progressive conditions or upper-body limitations that impede conventional driving.
- Emerging Market Penetration:There is a significant opportunity in large developing economies where disability awareness is rising, creating new demand for affordable, locally adapted vehicle conversion solutions.
Industry Challenges
- Skilled Technician Scarcity:A shortage of technicians with dual expertise in modern automotive electronics and the specialized fabrication skills needed for structural vehicle modification creates production bottlenecks and increases labor costs.
- EV Conversion Compliance:Ensuring that modified electric vehicles still meet all Federal Motor Vehicle Safety Standards after major structural changes, including protecting battery integrity during a crash, is a major engineering and certification hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicles for Disabled Market |
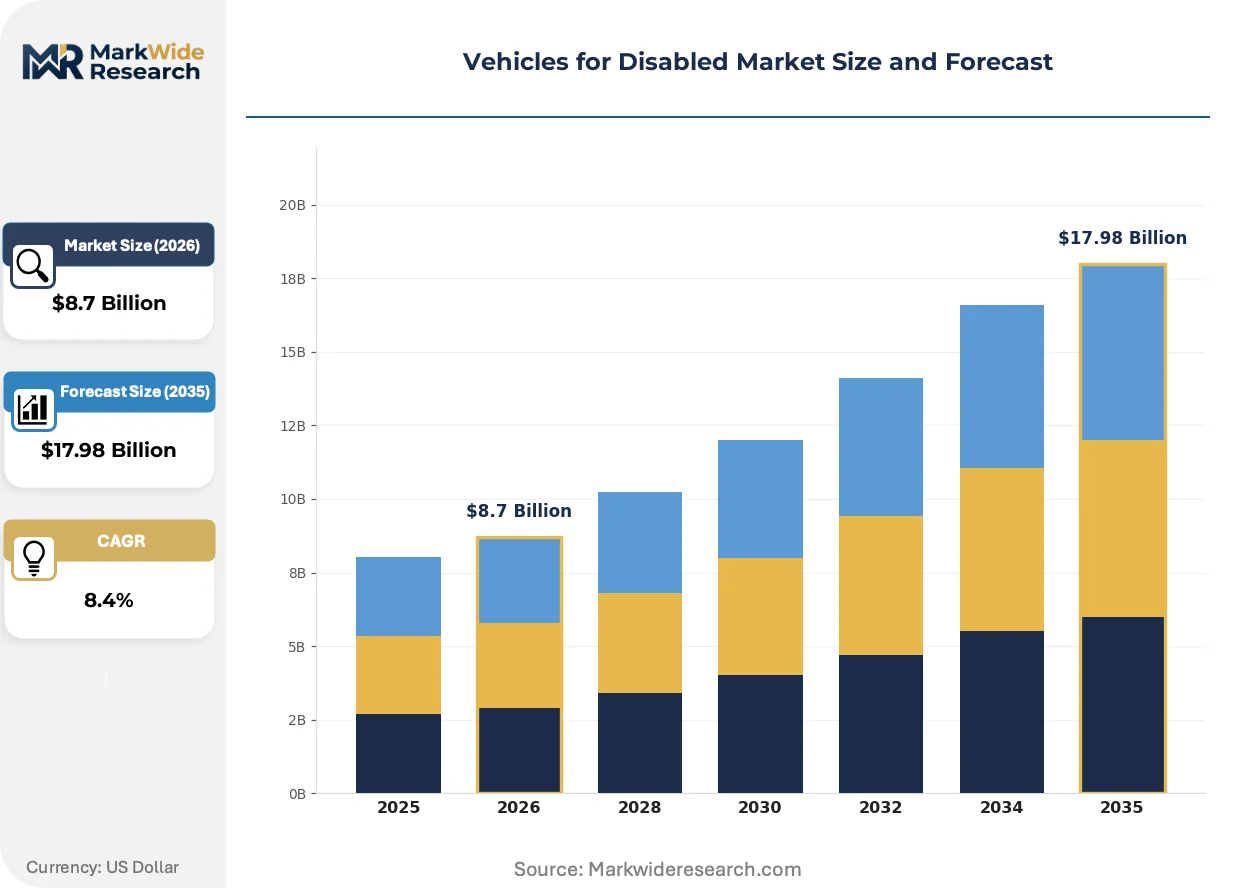
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Wheelchair Vans, Mobility Scooters, Accessible Cars, Modified SUVs, Adapted Trucks Drive Type: Manual, Electric, Hybrid, Gasoline, Hydrogen Fuel Cell Application: Personal Transportation, Medical Transport, Community Services, Rehabilitation, Senior Mobility End User: Individuals with Disabilities, Rehabilitation Centers, Elder Care Providers, Disability Support Organizations, Nonprofit Agencies |
| Companies Covered | ATS Mobility, United Access, BraunAbility, EZmobility Direct, Jubilee Mobility, Driverge, Freedom Motors USA, GM Mobility, VMI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicles for Disabled Market Strategic Shifts & Innovations
Product evolution is moving beyond simple structural adaptations toward fully integrated systems that blend accessibility with mainstream automotive technology. This shift is driven by user expectations for feature parity and the need to adapt to new electric and software-defined vehicle architectures.
Integrated electronic control units that manage ramps, lifts, and secondary driving controls are becoming standard. Individual buyers and commercial fleet operators for elder care are adopting these systems for their reliability and ease of use. This software-led approach is modularizing the conversion process, enabling more tailored configurations and future software-based feature upgrades.
European Union regulations, specifically the Medical Device Regulation (MDR), are increasing compliance burdens. The MDR classifies certain accessibility components like lifts as medical devices, requiring converters to implement rigorous quality management systems and post-market surveillance. This change most directly impacts converters in Germany and across the EU, forcing greater investment in regulatory affairs and documentation to maintain market access.
A clear behavioral shift shows users preferring discreet conversions of popular consumer vehicles over purpose-built vans. This trend challenges the dominance of the wheelchair van segment, forcing converters to engineer solutions for a wider array of SUV and crossover chassis. The preference is most pronounced in North America, where families and younger individuals with disabilities seek vehicles that do not signal "disability" and blend in with common traffic.
Vehicles for Disabled Market Segmentation
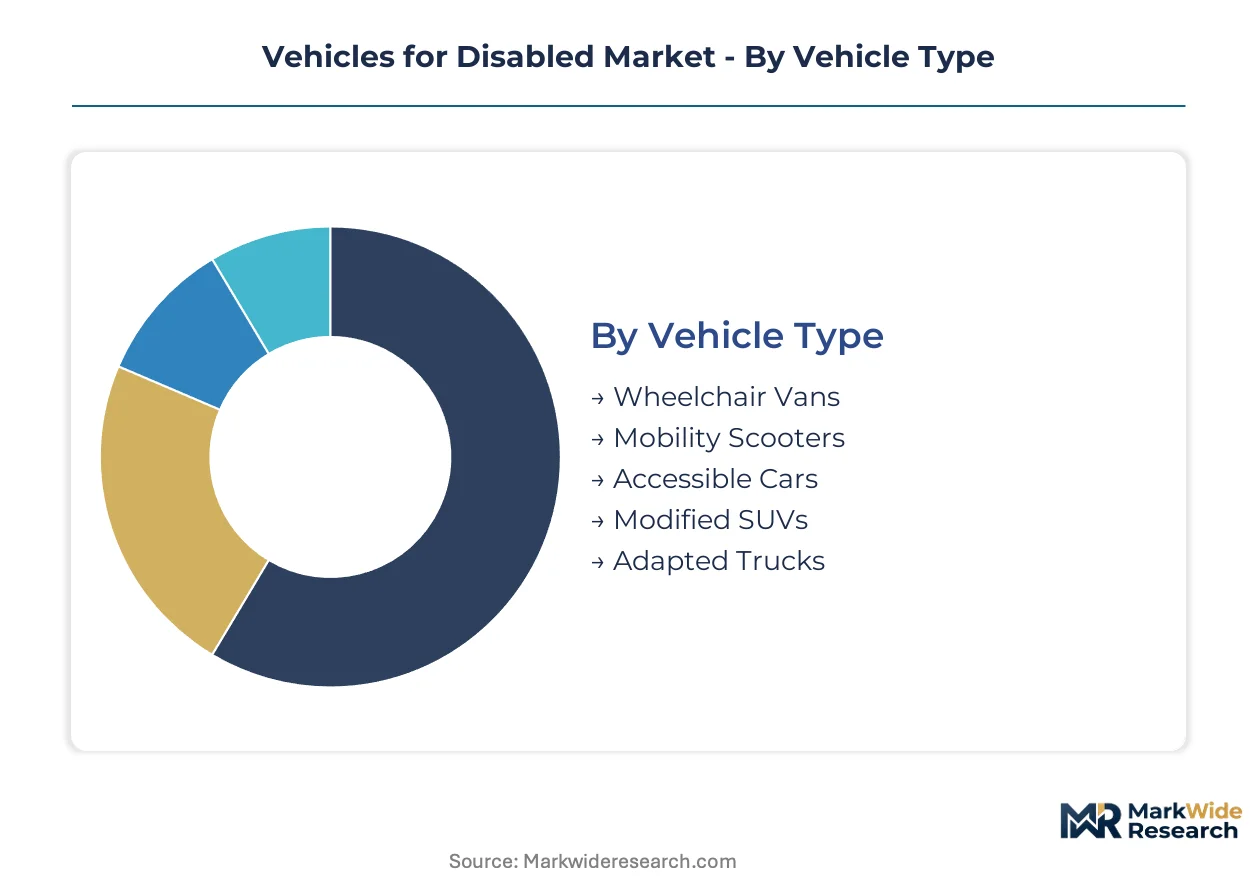
The Vehicles for Disabled Market is characterized by diverse user requirements and specialized modification techniques. Understanding these distinct segments allows manufacturers and converters to tailor solutions effectively, addressing specific mobility challenges and evolving consumer preferences. This detailed segmentation highlights areas of significant demand and technological innovation across the industry.
Vehicle Type:
The upgrade and replacement cycles in vehicle type reveal a dynamic market where traditional solutions coexist with newer, more versatile options.
- Wheelchair Vans:These vehicles feature extensive structural modifications, including lowered floors and integrated ramps or lifts, providing maximum interior space and ease of access for wheelchair users. Demand for these highly specialized vans remains strong in North America for both personal and commercial medical transport applications.
- Modified SUVs:These popular consumer vehicles undergo rear-entry or side-entry conversions, often with power ramps or lifts, appealing to users seeking a less conspicuous and more contemporary aesthetic. The North American market shows a pronounced preference for these conversions, driven by younger individuals with disabilities.
- Accessible Cars:Standard passenger cars are adapted with features such as hand controls, swivel seats, or portable ramps, offering basic mobility solutions for individuals with less extensive physical limitations.
- Mobility Scooters:Compact electric vehicles designed for short-distance personal transportation, often used in conjunction with accessible vans or cars that can transport them.
- Adapted Trucks:Pickup trucks modified with specialized lifts or driving controls cater to users who require both accessibility and the utility of a truck, particularly in rural areas of the United States.
Wheelchair Vans sits at the top of the volume ranking, with Modified SUVs climbing the fastest.
Drive Type:
The maturity of various drive types impacts vehicle availability and infrastructure, influencing purchasing decisions for accessible vehicles.
- Gasoline:Internal combustion engine vehicles represent the most established drive type, offering widespread fueling infrastructure and lower initial purchase costs for modified vehicles. These vehicles maintain dominance in markets like the United States where extensive charging networks for electric vehicles are still developing.
- Electric:Battery-electric vehicles present a significant future growth area, offering reduced operating costs and environmental benefits, though structural modifications for accessibility pose engineering challenges due to floor-mounted battery packs. Regulatory pushes in Europe, such as those driven by EU Green Deal initiatives, accelerate the focus on electric platforms.
- Manual:Vehicles requiring traditional gear shifting and clutch operation, often adapted with hand controls for individuals with lower-body mobility impairments.
- Hybrid:Vehicles combining a gasoline engine with an electric motor, offering improved fuel efficiency and reduced emissions compared to pure gasoline models.
- Hydrogen Fuel Cell:Emerging technology offering zero-emission operation and quick refueling times, though infrastructure remains limited and vehicle availability is scarce.
Gasoline vehicles maintain the largest share, while Electric drive types are expanding most quickly.
Application:
The volume of demand varies significantly across different applications, reflecting the core needs addressed by accessible vehicles.
- Personal Transportation:This segment encompasses vehicles modified for individual use, enabling independence for daily commutes, errands, and social activities. This application forms the largest segment, driven by individuals seeking autonomy across all geographies.
- Senior Mobility:Vehicles adapted specifically for older adults, often featuring power lifts, swivel seats, and improved ergonomics to maintain independence as physical capabilities change. This segment is expanding rapidly in countries with aging populations like Japan and Germany.
- Medical Transport:Vehicles used by non-emergency medical services, hospitals, and clinics to transport patients requiring accessible options to appointments.
- Community Services:Vehicles operated by local governments or non-profit organizations to provide accessible transport for community members to various programs and facilities.
- Rehabilitation:Vehicles used within rehabilitation centers for training individuals to drive or be transported, supporting their reintegration into independent living.
Personal Transportation accounts for the largest volume, and Senior Mobility shows the steepest expansion trajectory.
End User:
The margin profiles associated with different end-user segments influence product development and service offerings within the market.
- Individuals with Disabilities:This primary end-user group directly purchases or leases modified vehicles for personal use, often relying on government subsidies or insurance support to offset high conversion costs. Their diverse needs drive innovation in personalized adaptations and control systems.
- Elder Care Providers:Organizations and businesses offering services to senior citizens procure accessible vehicles for resident transport, contributing to the accelerating growth of the Senior Mobility segment. These providers often seek reliable, easy-to-operate vehicles for their fleets.
- Rehabilitation Centers:Institutions focused on physical recovery and therapy acquire accessible vehicles for patient transport and driving instruction, supporting the rehabilitation process.
- Disability Support Organizations:Non-profit groups and advocacy organizations purchase or facilitate the acquisition of accessible vehicles to support their members and programs.
- Nonprofit Agencies:Various charitable organizations utilize accessible vehicles to deliver services, transport clients, or support community outreach initiatives for underserved populations.
Individuals with Disabilities represent the largest end-user base, while Elder Care Providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for accessible vehicles emphasizes personal independence, while Germany focuses on public transport accessibility and elder care. This market demonstrates varied regional priorities driven by demographic and regulatory frameworks. Each region adapts to specific user needs and compliance requirements.
United States
Individual mobility and medical transport drive demand for accessible vehicles in the United States. Federal Motor Vehicle Safety Standards enforced by the NHTSA govern vehicle modifications, ensuring safety. California and Florida exhibit high concentrations of accessible vehicle users, reflecting significant senior populations and disability advocacy.
Germany
Germany's aging population significantly expands the senior mobility segment for modified vehicles. Converters must meet CE marking requirements for medical devices and vehicle safety within the European Union. Stuttgart, a major automotive hub, fosters innovation in electric vehicle platforms for accessibility solutions.
Japan
The rapidly aging population in Japan creates substantial demand for senior mobility solutions and personal accessible vehicles. Japanese Industrial Standards (JIS) influence the design and safety of modified vehicles. Tokyo's urban density necessitates compact and efficient accessible transport options.
United Kingdom
Public transport accessibility initiatives and personal independence needs shape the market in the United Kingdom. UK vehicle regulations ensure safety and compliance for adapted vehicles. London's focus on accessible taxi fleets stimulates demand for specialized commercial conversions.
Canada
Growing demand for personal accessible vehicles and aging demographics contribute to market expansion across Canada. The Accessibility for Ontarians with Disabilities Act (AODA) influences design standards for accessible transportation. Toronto serves as a key center for vehicle converters and mobility service providers.
Vehicles for Disabled Market Key Industry Players
North American specialized vehicle converters anchor one tier; European modification houses hold another. The market structure exhibits fragmentation, with numerous regional players and a few dominant specialists. Strategic archetypes include full-service conversion providers, niche technology developers, and chassis-agnostic modifiers. Dominant competitive moves involve strategic partnerships with automotive OEMs and geographic expansion into underserved markets.
Specialists in advanced accessibility features include VMI, renowned for its innovative side-entry minivan conversions. BraunAbility, a full-service provider, leverages its extensive dealer network across North America. Freedom Motors USA exemplifies a niche modifier, focusing on rear-entry conversions for popular SUV and crossover chassis.
| Leading Market Players |
|---|
| ATS Mobility |
| United Access |
| BraunAbility |
| EZmobility Direct |
| Jubilee Mobility |
| Driverge |
| Freedom Motors USA |
| GM Mobility |
| VMI |
| Others |
Cost & Logistics Intelligence
Outsourced specialized fabrication anchors both the supply position and the pricing power for vehicle converters. This model allows smaller regional players to access advanced components but also concentrates risk among key component suppliers, influencing final vehicle costs.
Pricing Analysis
Capacity additions in North America are reshaping price floors for common minivan conversions. The dominant pricing model remains project-based, reflecting the high degree of customization for each vehicle. Price differentiation stems from the level of vehicle structural modification and the certification grade of installed components, such as CE marking for lifts. Pricing softness reflects high conversion costs, which often necessitate subsidies or insurance support for individual buyers. Individuals with Disabilities often exhibit the highest price sensitivity, while Elder Care Providers prioritize reliability and ease of use over lowest cost.
Supply Chain Analysis
Returns, refurbishment, and remanufacturing flows for specialized components remain nascent, primarily handled by original equipment manufacturers. Geographic supply concentration for critical conversion components centers on the United States and Germany, reflecting advanced manufacturing capabilities. Raw material dependencies include specialized electronics for control systems, lightweight composite materials for ramps, and steel alloys for structural reinforcements. Skilled technician scarcity represents a structural supply chain risk, creating production bottlenecks. Downstream distribution runs through a network of specialized dealer franchises and authorized installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the vehicles for disabled market is achievable through the strategic integration of advanced manufacturing techniques, driving down unit costs for complex modifications.
For Market Incumbents: Extend partnerships with automotive OEMs to influence future vehicle platform designs, addressing the EV conversion compliance challenge proactively. This defensive move mitigates the threat of new EV architectures rendering traditional conversion methods obsolete. Invest in R&D for modular conversion kits compatible with multiple chassis types, leveraging economies of scale.
For New Entrants and Emerging Players: Enter via niche segments like adapted trucks or specialized SUV conversions, where established players have less market penetration. Focus on regions with rising disability awareness and less stringent regulatory frameworks, such as emerging markets. A go-to-market angle emphasizing discreet, aesthetically integrated solutions for popular consumer vehicles resonates with younger individuals with disabilities.
For Investors and Strategic Acquirers: Roll-up economics work for specialized vehicle converters because market fragmentation creates opportunities for consolidation and operational efficiencies. The long-term viability of this market is strong, driven by demographic shifts and persistent accessibility mandates. Target vertically integrated mid-cap specialists with strong intellectual property in EV conversion technologies. Watch for rising government subsidies for accessible EV purchases as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| OEM Platform Co-Development | Shapes future vehicle designs for inherent accessibility, reducing post-production modification costs. |
| Modular EV Conversion Kits | Enables efficient adaptation of electric vehicles, addressing the core engineering challenge. |
| Geographic Expansion into Emerging Markets | Captures new demand in regions with rising disability awareness and less developed infrastructure. |
| Investment in Technician Training Programs | Mitigates skilled labor scarcity, ensuring quality and timely vehicle conversions. |
| Integration of Autonomous Driving Features | Offers enhanced independence for users with progressive conditions, expanding the user base. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct a comprehensive market view. This approach combined insights from vehicle converters, disability advocacy groups, elder care administrators, and automotive engineers, ensuring a holistic understanding of market dynamics.
Data-stream reconciliation formed the analytical framework for projecting market growth across the analysis window. Segmentation dimensions modeled included vehicle type, drive type, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived through a proprietary algorithm considering historical trends and forecast inputs like demographic shifts in Japan and Germany, and EV adoption rates.
Inputs from NHTSA reports, EU MDR guidelines, and automotive industry publications were available through the study window; gaps in emerging market data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Practitioners should monitor policy changes in EV conversion incentives and advancements in battery technology for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Car Rental Business Market
Automotive Services
North America MRO Distribution Market
Automotive Services
Cab Services Market
Automotive Services
Automatic Vehicle Washing System Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Online Car-Hailing Service Market
Automotive Services
Car Washing Service Market
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
Car Vending Machine Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Driver's License Market
Automotive Services
Vehicle Analytics Market