
 Gearshift Sleeves Market | 2026-2036
Gearshift Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Gearshift Sleeves Market Analysis
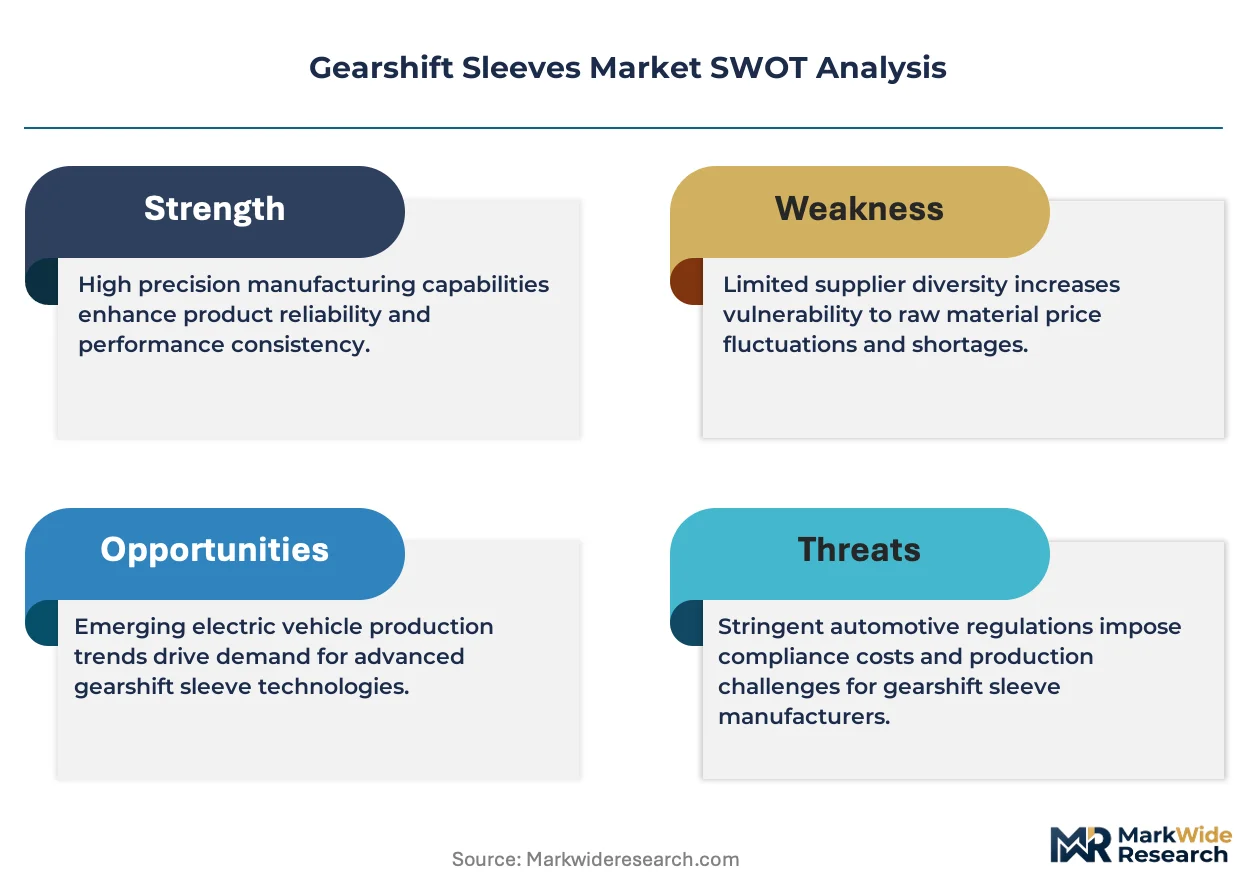
Passenger car OEM procurement is consolidating toward fewer Tier-1 suppliers capable of integrated transmission module supply. ZF Friedrichshafen leverages its dual-clutch transmission expertise to anchor long-term supply agreements with European vehicle assemblers. BorgWarner competes through its electrified driveline portfolio, positioning gearshift sleeves within broader e-axle architectures. Schaeffler specializes in precision-engineered friction components, sustaining manufacturing scale across its German and Chinese plants.
Gearshift sleeves are cylindrical synchronizer components, typically manufactured from brass alloys or engineered polymers with tolerances below 50 microns, that engage gear clusters during ratio changes in manual and automated manual transmissions. Their primary commercial purpose is to enable smooth torque transfer while minimizing shift shock and component wear across millions of duty cycles. Metal sleeves dominate OEM channels where thermal loads and mechanical durability requirements remain stringent, while composite formulations gain traction in lightweighting-focused vehicle platforms where machining stage innovation reduces raw material waste. Injection molding occupies the highest volume manufacturing stage for plastic variants serving cost-sensitive aftermarket providers.
Germany's KBA enforces type-approval standards that mandate fatigue testing protocols for transmission subcomponents sold into EU vehicle assembly chains. China's MIIT implements corporate average fuel consumption rules that incentivize weight reduction in driveline hardware, directly influencing sleeve material selection by domestic Tier-1 suppliers. REACH compliance in Europe restricts certain brass alloy additives, forcing reformulation of traditional metal sleeve compositions. Stakeholders must monitor how electrification transitions reshape synchronizer demand as pure battery-electric architectures eliminate multi-speed gearboxes while hybrid platforms sustain sleeve requirements across dedicated e-CVT and multi-speed transmission designs.
Market Dynamics
Passenger car OEM procurement consolidation toward integrated transmission module suppliers is compressing vendor margins while elevating technical qualification barriers for standalone gearshift sleeve manufacturers.
Growth Catalysts
- China MIIT fuel consumption standards:Corporate average fuel consumption rules incentivize driveline lightweighting, accelerating polymer sleeve adoption in domestic passenger vehicle platforms.
- Hybrid transmission proliferation:Dedicated e-CVT and multi-speed hybrid architectures sustain synchronizer demand as pure battery-electric platforms eliminate multi-speed gearboxes.
- Stuttgart-Munich manufacturing corridor:Concentrated German automotive assembly capacity creates localized demand pull for precision-engineered transmission subcomponents.
Market Restraints
- Brass alloy input volatility:Copper and zinc price fluctuations compress margin stability for metal sleeve foundries serving OEM channels.
- REACH additive restrictions:ECHA limitations on traditional brass alloy compositions force costly reformulation of established metal sleeve specifications.
- Battery-electric substitution threat:Single-speed reduction gear architectures in pure EV platforms eliminate synchronizer requirements entirely.
Strategic Opportunities
- India PLI scheme automotive incentives:Production-linked incentives for advanced automotive components attract sleeve manufacturing investment toward emerging passenger vehicle hubs.
- Polymer-metal hybrid convergence:Composite sleeves combining polymer cores with metal friction surfaces address thermal durability and weight reduction simultaneously.
- Aftermarket channel digitization:Direct-to-workshop platforms bypass traditional distributor layers for replacement sleeve procurement.
Industry Challenges
- Sub-50-micron tolerance talent scarcity:Precision machining expertise for synchronizer components concentrates among aging German and Japanese technician cohorts.
- Dual certification timeline compression:Simultaneous KBA type-approval and MIIT compliance documentation extends product launch cycles.
- Legacy transmission integration complexity:Electrified driveline architectures require sleeve redesign for compatibility with integrated e-axle modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gearshift Sleeves Market |
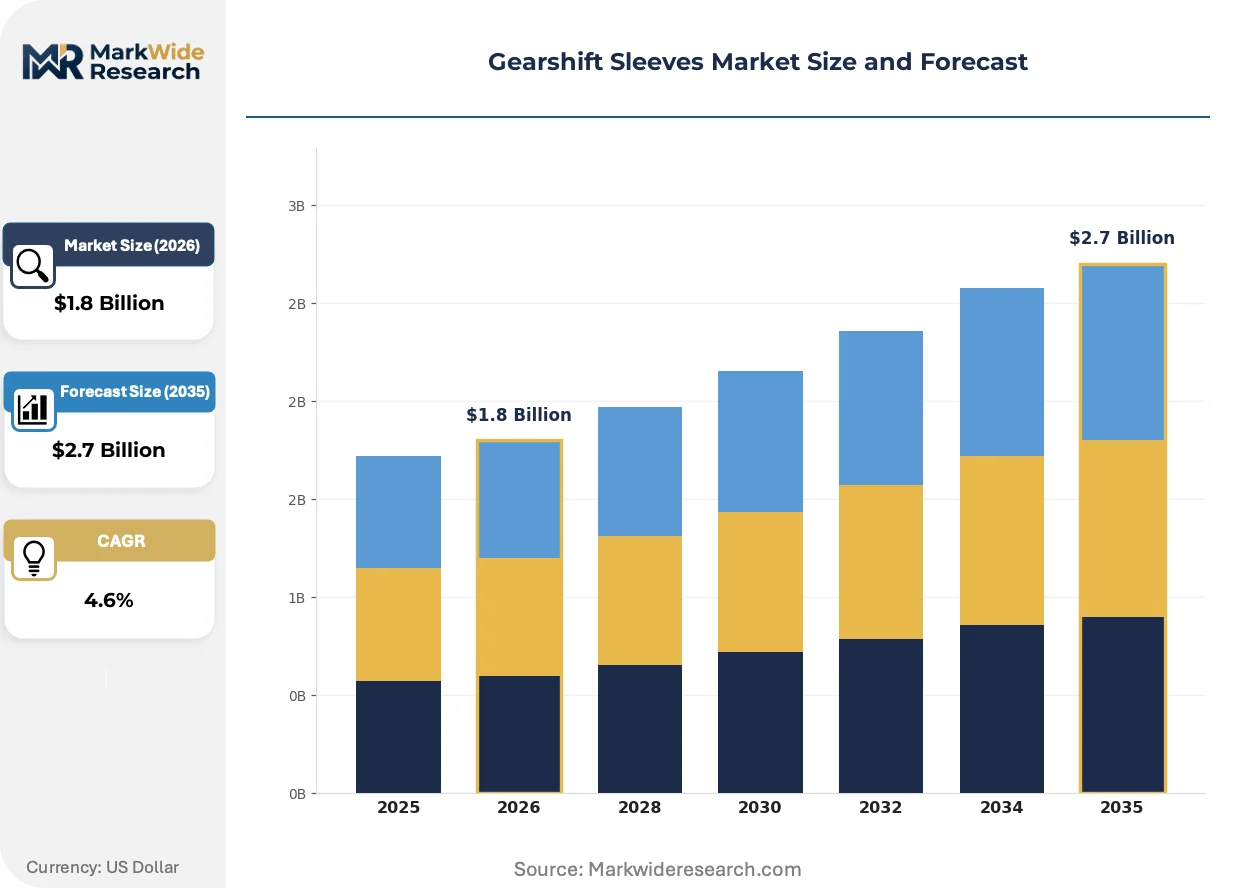
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Composite, Rubber End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Manufacturing Stage: Injection Molding, Machining, 3D Printing, Casting Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | ZF Friedrichshafen, GKN Automotive, BorgWarner, Schaeffler, Aisin Seiki, Guangzhou Maxiou Auto Parts, JDMotorsport, Melrose Industries, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gearshift Sleeves Market Emerging Trajectories
Manufacturing process digitization and material science advances are redefining competitive advantage in gearshift sleeve production, with automation and regulatory compliance emerging as decisive capability differentiators.
Multi-material injection molding is automating the production of polymer-composite sleeves with embedded metal friction rings, enabling single-stage manufacturing of previously multi-component assemblies. Tier-1 suppliers in Germany and China are adopting these systems at pilot scale, compressing cycle times while eliminating secondary machining operations for lightweighting-focused vehicle platforms.
Europe's REACH framework is forcing systematic reformulation of brass alloy compositions used in traditional metal sleeves, restricting lead and certain bismuth additives previously standard in friction-optimized alloys. Foundries serving EU vehicle assembly chains are qualifying alternative copper-zinc-tin compositions, with compliance costs most acute for mid-volume suppliers lacking in-house metallurgical R&D.
Integrated module procurement contracts are consolidating specification authority with transmission system architects rather than component buyers, compressing the supplier base capable of direct OEM engagement. ZF Friedrichshafen and BorgWarner now specify sleeve tolerances and materials within broader e-axle supply agreements, with this concentration most visible in Germany's Stuttgart manufacturing corridor where module integration is deepest.
Gearshift Sleeves Market Segmentation
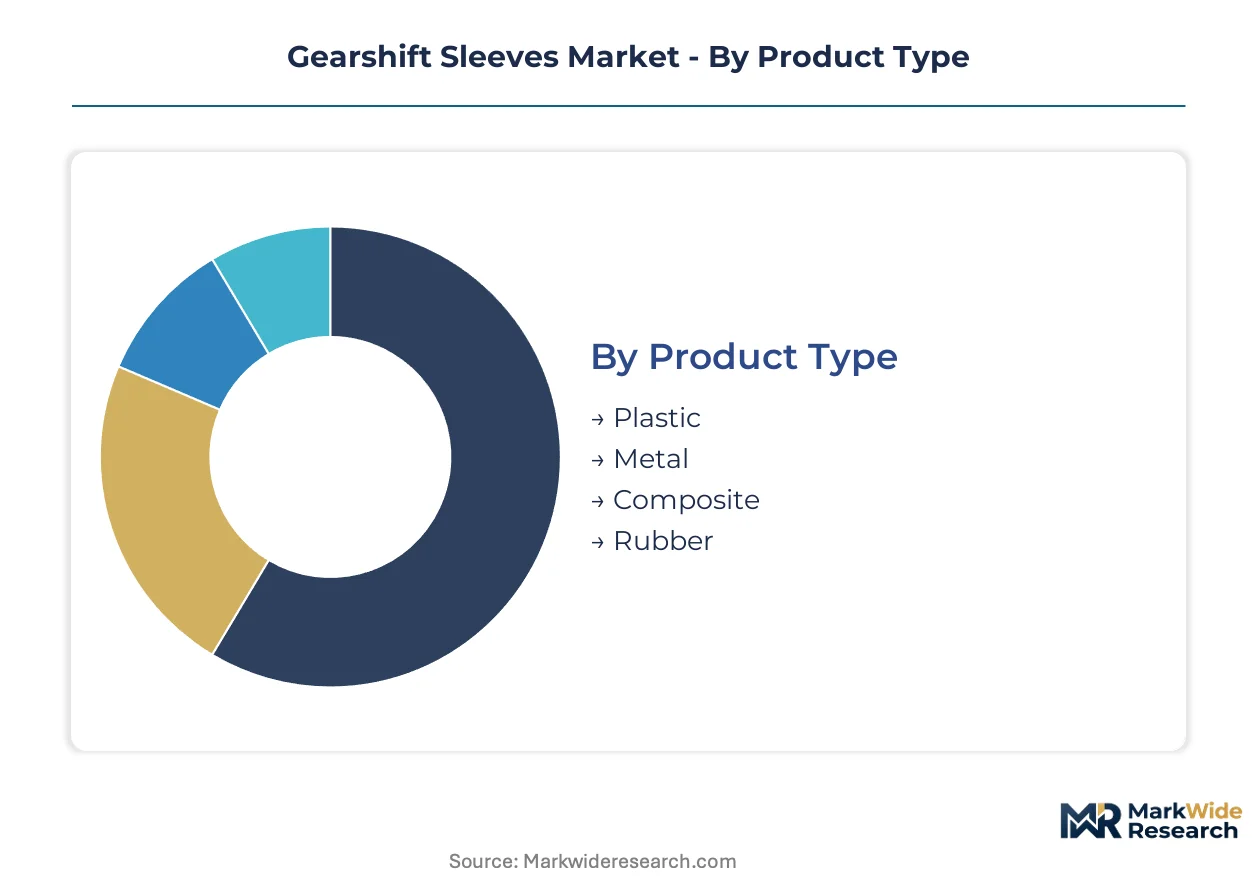
Gearshift sleeve procurement patterns diverge sharply across material grades, customer tiers, and manufacturing methods. Each segment carries distinct capital requirements, margin profiles, and regulatory exposure that reshape supplier positioning.
Product Type:
Metal sleeves demand the heaviest upfront investment in precision machining infrastructure and metallurgical R&D capacity.
- Plastic:Injection-molded polymer formulations serve cost-sensitive aftermarket channels and lightweighting-focused passenger vehicle platforms. China's MIIT fuel consumption rules accelerate domestic adoption as Tier-1 suppliers seek gram-level weight reductions in driveline hardware.
- Metal:Brass and steel alloy sleeves machined to sub-50-micron tolerances dominate OEM procurement where thermal durability and fatigue resistance remain non-negotiable. Germany's KBA type-approval protocols mandate extensive testing cycles that favor established foundries with captive metallurgy labs.
- Composite:Hybrid constructions combining polymer cores with metal friction surfaces address simultaneous weight and durability targets in hybrid transmission architectures.
- Rubber:Elastomeric variants occupy niche damping applications within automated manual transmission systems requiring vibration isolation.
Metal absorbs the bulk of installed capacity; composite is expanding most quickly.
End User:
Volume concentrates with customers controlling specification authority over integrated transmission modules.
- OEMs:Vehicle manufacturers with captive transmission divisions source sleeves through long-term supply agreements tied to platform lifecycle commitments. Procurement consolidation favors suppliers capable of module-level integration across German and Chinese assembly corridors.
- Aftermarket Providers:Independent distributors and workshop chains procure replacement sleeves through digitized procurement platforms, bypassing traditional wholesale layers. Price sensitivity drives preference toward plastic variants with shorter service life tolerances.
- Tier-1 Suppliers:ZF Friedrichshafen and BorgWarner specify sleeve materials and tolerances within broader e-axle supply contracts, compressing direct engagement opportunities for standalone component manufacturers.
- Vehicle Assemblers:Contract manufacturers without captive transmission engineering rely on Tier-1 module supply, limiting direct sleeve procurement to exceptional quality escapes or regional supply disruptions.
Tier-1 suppliers command the deepest specification influence; aftermarket channels are climbing the fastest as direct-to-workshop platforms proliferate.
Manufacturing Stage:
Process selection determines capital intensity, cycle economics, and regulatory compliance burden.
- Injection Molding:Automated polymer processing achieves highest volume throughput for plastic sleeve variants. Multi-material systems embedding metal friction rings eliminate secondary machining operations.
- Machining:Precision turning and grinding of brass alloys requires specialized equipment and aging technician expertise concentrated in German and Japanese manufacturing clusters.
- 3D Printing:Additive manufacturing enables rapid prototyping and low-volume customization for motorsport and specialty vehicle applications.
- Casting:Foundry-based production of metal sleeves serves high-volume OEM channels with established tooling amortization across multi-year platform commitments.
Machining retains the largest installed equipment base; injection molding is gaining share fastest as polymer formulations mature.
Distribution Channel:
Channel structure reflects customer scale, urgency requirements, and technical support needs.
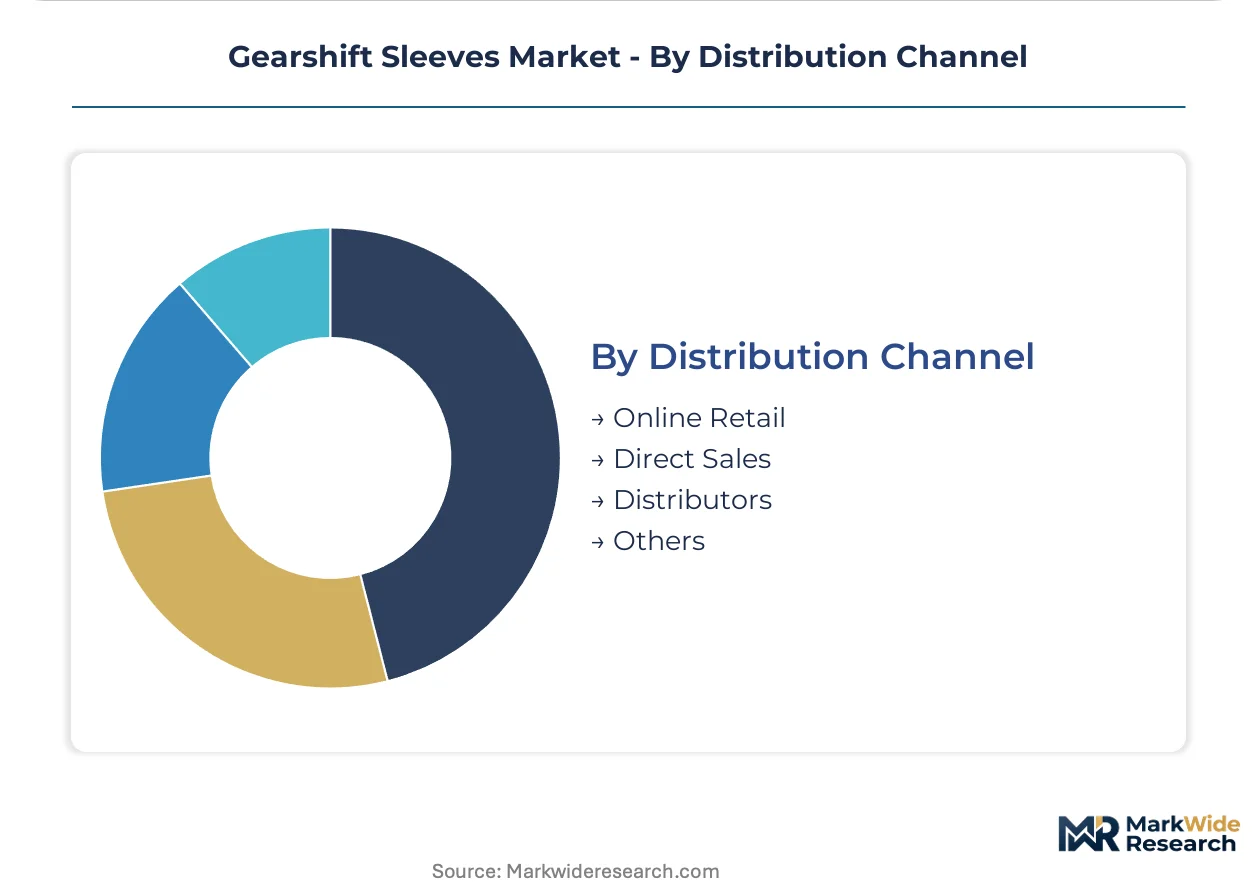
- Online Retail:Digital platforms aggregate aftermarket demand from independent workshops and regional distributors, compressing price discovery cycles.
- Direct Sales:OEM and Tier-1 procurement operates through negotiated framework agreements with dedicated account management and engineering liaison support.
- Distributors:Traditional wholesale networks maintain inventory buffers for aftermarket replenishment, particularly in regions with fragmented workshop bases.
- Others:Consortium purchasing arrangements and cooperative procurement pools serve smaller vehicle assemblers lacking individual volume leverage.
Direct sales capture the majority of contract value; online retail is expanding most quickly as workshop digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Passenger vehicle assembly corridors concentrate procurement pull for precision transmission subcomponents. Germany's Stuttgart-Munich corridor anchors European demand. China's Yangtze River Delta manufacturing belt drives volume requirements.
Germany
The KBA enforces type-approval fatigue testing protocols that elevate qualification barriers for synchronizer component entry. REACH additive restrictions on traditional brass alloys force foundries to reformulate established metal sleeve specifications. Stuttgart's integrated transmission module ecosystem concentrates specification authority with ZF Friedrichshafen and BorgWarner.
China
MIIT corporate average fuel consumption rules accelerate polymer sleeve adoption across domestic passenger vehicle platforms. Tier-1 suppliers in the Yangtze River Delta region qualify lightweight driveline hardware to meet tightening efficiency mandates. Shanghai and surrounding manufacturing hubs host captive machining operations serving BYD and Geely transmission divisions.
United States
Detroit's powertrain engineering centers sustain demand for thermal-durable metal sleeves in full-size truck and SUV platforms. NHTSA fuel economy standards push domestic OEMs toward multi-speed automatic transmissions that retain synchronizer architectures. Michigan and Ohio assembly corridors source through BorgWarner and Eaton module supply agreements.
Japan
METI energy efficiency directives shape material selection for hybrid transmission components across Toyota and Honda supply chains. Aisin Seiki's concentration in Aichi Prefecture anchors precision machining expertise for sub-50-micron tolerance sleeves. Nagoya's automotive component cluster maintains captive metallurgical R&D for friction-optimized alloy formulations.
India
PLI scheme incentives for advanced automotive components attract sleeve manufacturing investment toward emerging passenger vehicle hubs. BIS quality certification requirements extend product launch timelines for Tier-1 suppliers entering domestic assembly chains. Tamil Nadu and Maharashtra automotive corridors concentrate Maruti Suzuki and Hyundai Motor India transmission sourcing.
Gearshift Sleeves Market Vendor Landscape
German producers anchor the premium-tier supply base; Chinese fabricators hold volume-scale positions in polymer variants. The vendor structure splits between consolidated module integrators and specialized component foundries. Three archetypes dominate: integrated transmission system architects, precision machining specialists, and polymer-composite innovators. Competitive moves center on backward integration into metallurgy capabilities and multi-material injection molding capacity expansion.
Within the integrated system architect tier, ZF Friedrichshafen and BorgWarner exemplify specification authority concentration through e-axle module supply agreements. Schaeffler occupies a position among precision-engineered friction component specialists sustaining manufacturing scale across German and Chinese plants. These three anchors demonstrate how procurement consolidation favors suppliers capable of module-level integration across major automotive assembly corridors.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| GKN Automotive |
| BorgWarner |
| Schaeffler |
| Aisin Seiki |
| Guangzhou Maxiou Auto Parts |
| JDMotorsport |
| Melrose Industries |
| Eaton |
| Others |
Supply Flow & Price Mechanics
Brass alloy input costs cascade through three pricing tiers before reaching Tier-1 module integrators, with copper and zinc spot volatility compressing margin stability for mid-volume foundries serving Germany's KBA-certified channels. China's MIIT lightweighting mandates pull polymer formulations into premium positioning, inverting traditional material-cost hierarchies as composite sleeves command price parity with machined brass in domestic passenger vehicle platforms.
Pricing Analysis
Volume concentrates in contract-based long-term offtake agreements between Tier-1 suppliers and OEM transmission divisions, while margin accrues to precision machining specialists with captive metallurgy labs. Price differentiation hinges on KBA type-approval certification and sub-50-micron tolerance grade, with aftermarket channels exhibiting highest sensitivity to unit cost. Pricing pressure stems from procurement consolidation toward integrated module suppliers, forcing standalone sleeve manufacturers into tier-two supply positions with compressed engineering influence.
Supply Chain Analysis
China's domestic-content thresholds for automotive components are reshaping sourcing patterns, requiring foreign suppliers to establish captive machining operations in Yangtze River Delta hubs to maintain BYD and Geely contract eligibility. Raw material flows draw from Chilean copper concentrates, Australian zinc, and German specialty alloy formulations. Single-source vulnerability concentrates in precision grinding equipment anchored in aging German and Japanese technician clusters. Distribution runs through direct sales frameworks for OEM procurement and digitized platforms for aftermarket replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gearshift sleeves market sits at a technology-transition inflection as polymer-composite formulations displace legacy brass alloys in lightweighting-focused vehicle architectures. Electrification divergence—sustaining synchronizer demand in hybrid multi-speed transmissions while eliminating it in pure battery-electric platforms—demands strategic positioning clarity.
For Market Incumbents: To counter battery-electric substitution in pure EV architectures, prioritize backward integration into polymer-metal hybrid R&D and expand multi-material injection molding capacity in China's Yangtze River Delta to capture MIIT-driven lightweighting procurement. Anchor specification authority through e-axle module integration contracts with European vehicle assemblers. For New Entrants and Emerging Players: Begin with India's PLI-scheme corridors in Tamil Nadu and Maharashtra, where domestic passenger vehicle expansion outpaces established supplier coverage. Target aftermarket digitization through direct-to-workshop platforms for plastic sleeve variants, bypassing traditional wholesale layers with price-transparent procurement tools. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision machining specialists with captive KBA certification infrastructure in Germany's Stuttgart corridor, where technician scarcity creates defendable moats. Monitor hybrid transmission platform announcements from Toyota and Honda as the critical signal for synchronizer demand sustainability over the mid-term horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Injection Molding Scale-Up | Enables single-stage production of polymer-metal hybrid sleeves for MIIT-compliant lightweighting platforms. |
| Backward Integration into Metallurgy R&D | Captures REACH-compliant brass alloy formulation capability, insulating margin from ECHA additive restriction costs. |
| Geographic Manufacturing Footprint Expansion | Establishes captive machining operations in India's PLI corridors to access Maruti Suzuki and Hyundai Motor India procurement. |
| Platform Standardization Partnership | Locks in long-term sleeve supply agreements within ZF Friedrichshafen and BorgWarner e-axle module architectures. |
| Aftermarket Channel Digitization | Bypasses traditional distributor layers through direct-to-workshop platforms for replacement sleeve procurement. |
Methodological Framework
Multi-period observation of MIIT fuel consumption compliance trajectories, REACH additive restriction implementation, and hybrid transmission platform rollouts anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM transmission platform engineers, aftermarket distribution channel heads, and precision machining operations managers. Secondary validation drew from KBA type-approval filings, vehicle production databases, customs trade records for copper and zinc inputs, and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down macroeconomic automotive demand indicators.
Input-output matrices mapped sleeve content per vehicle across manual, automated manual, dual-clutch, and hybrid transmission architectures, with volume and value outputs derived through cross-referencing production forecasts against material cost indices. Segmentation dimensions spanned material grade, end-user tier, manufacturing process, and regional regulatory cluster. CAGRs were computed from fitted growth curves applied to baseline procurement volumes, incorporating electrification scenario weights and MIIT efficiency mandate compliance trajectories as primary forecast drivers.
Copper and zinc price volatility, unanticipated battery-electric platform acceleration, and REACH regulatory scope expansion are the dominant revision risks that could compress or extend synchronizer demand trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Automotive Spring Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
Air Springs Market
Automotive Parts
Automotive Forging Market