
 North America Automotive Bearing Market | 2026-2036
North America Automotive Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Bearing Market Analytics
Ceramic is decoupling traditional steel economics in high-speed electric motor applications, reducing friction losses and extending service intervals. SKF leverages its ceramic hybrid portfolio to anchor premium positioning in EV powertrains. The Timken Company sustains manufacturing scale across tapered roller designs for heavy-duty chassis systems. NSK Ltd. competes through R&D intensity in low-torque ball bearing architectures for transmission modules.
Automotive bearings are precision-engineered rotary components, typically manufactured from through-hardened alloy steel or silicon nitride ceramic, with dimensional tolerances measured in micrometers to support radial and axial loads in rotating assemblies. Their primary commercial purpose is to reduce mechanical friction, maintain shaft alignment, and enable reliable power transmission across powertrain and chassis subsystems. Roller bearing configurations command the largest share of OEM demand due to their load-carrying capacity in transmission and wheel hub applications, while ceramic material adoption represents the fastest-expanding margin pool as electrification intensifies thermal and speed requirements. Ball bearing demand from Tier-1 Suppliers remains structurally mature in internal combustion engine architectures but faces displacement risk as vehicle assemblers consolidate platforms around integrated e-axle designs.
NHTSA Corporate Average Fuel Economy standards and EPA tailpipe emissions regulations are tightening friction-reduction mandates that directly shape bearing specification requirements for OEMs and Tier-1 Suppliers. The Department of Transportation's vehicle safety protocols further influence durability testing protocols for chassis and suspension bearing applications. Stakeholders must monitor how NHTSA electrification timelines and EPA powertrain rules recalibrate procurement criteria across the Detroit manufacturing base and Mexican assembly corridors.
Market Dynamics
Electric vehicle powertrain electrification is compressing bearing count per vehicle while simultaneously elevating thermal and rotational speed specifications, forcing suppliers to recalibrate material portfolios and manufacturing footprints across Detroit and Mexican assembly corridors.
Growth Catalysts
- EPA Emissions Rules:NHTSA Corporate Average Fuel Economy standards mandate friction reduction in driveline components, compelling OEMs to specify low-torque bearing architectures in transmission modules.
- Silicon Nitride Ceramics:This material class enables higher speed operation with reduced thermal expansion, matching electric motor operating envelopes that exceed traditional steel fatigue limits.
- Mexican Assembly Corridor:Vehicle production concentration in Guanajuato and Nuevo León generates localized demand for wheel hub and chassis bearing supply chains serving export markets.
Market Restraints
- Alloy Steel Price Volatility:Through-hardened bearing steel input costs fluctuate with scrap metal and energy pricing, compressing margin stability for commodity-grade roller bearing producers.
- Supplier Concentration Risk:Premium ceramic powder and precision grinding equipment sources cluster in East Asian manufacturing bases, exposing North American fabricators to logistics disruption.
- Technical Limitation:Ceramic rolling elements exhibit brittleness under impact loading, restricting deployment in heavy-duty commercial vehicle suspension systems where steel retains dominance.
Strategic Opportunities
- Canadian EV Supply Chain:Ontario's battery cell and electric motor manufacturing investments create demand for localized precision bearing production serving integrated e-axle assembly.
- Integrated E-Axle Designs:Consolidated motor-transmission units require specialized high-speed bearings that command premium positioning versus legacy multi-bearing powertrain architectures.
- IRA Clean Vehicle Credits:Domestic content requirements in the Inflation Reduction Act incentivize bearing reshoring to qualify assembled vehicles for consumer tax incentives.
Industry Challenges
- Precision Grinding Skill Gap:Micrometer-tolerance ceramic finishing requires specialized machinist training that outpaces current vocational pipeline output in Midwest manufacturing regions.
- Dual Certification Burden:Suppliers must simultaneously satisfy NHTSA durability protocols for legacy internal combustion platforms and evolving EPA electrification testing standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Bearing Market |
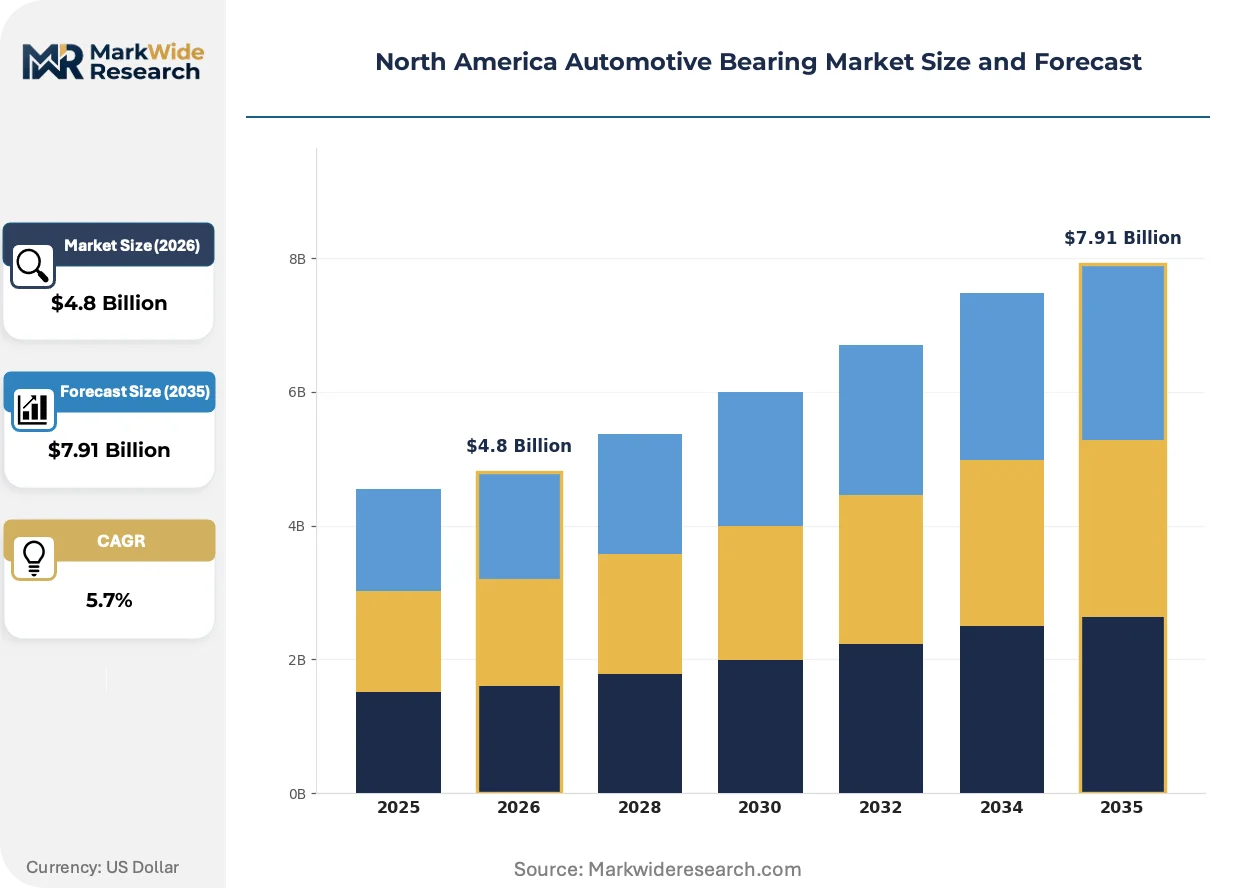
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearing, Roller Bearing, Thrust Bearing, Plain Bearing Material: Steel, Ceramic, Plastic, Composite Application: Engine, Transmission, Chassis, Suspension End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | NSK Ltd., JTEKT Corporation, NTN Corporation, SKF, Schaeffler AG, The Timken Company, RBC Bearings, Inc., Nippon Thompson Co., Ltd., Iljin Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Bearing Market Evolving Landscape
Ceramic hybrid architectures are redefining performance benchmarks as electrification intensifies thermal and speed requirements beyond conventional steel capabilities.
Silicon nitride ceramic rolling elements deliver reduced density and superior thermal stability for electric motor shaft support. Tier-1 powertrain suppliers are adopting these configurations for 20,000+ RPM motor applications. This material transition is consolidating supplier tiers around firms with captive ceramic processing capabilities.
NHTSA fuel economy mandates and EPA tailpipe rules are tightening friction-reduction specifications across driveline components. OEM procurement teams now require bearing suppliers to document coefficient-of-friction performance across standardized duty cycles. Wheel hub and transmission module specifications in the Detroit manufacturing base reflect these tightened thresholds.
Fleet operators and vehicle assemblers are compressing supplier qualification timelines to match accelerated platform development cycles. Traditional 18-month validation protocols are yielding to parallel testing frameworks that compress bearing approval to 9-12 months. This behavioral shift is most visible among electric vehicle startups and established OEMs launching dedicated battery-electric nameplates.
North America Automotive Bearing Market Segmentation
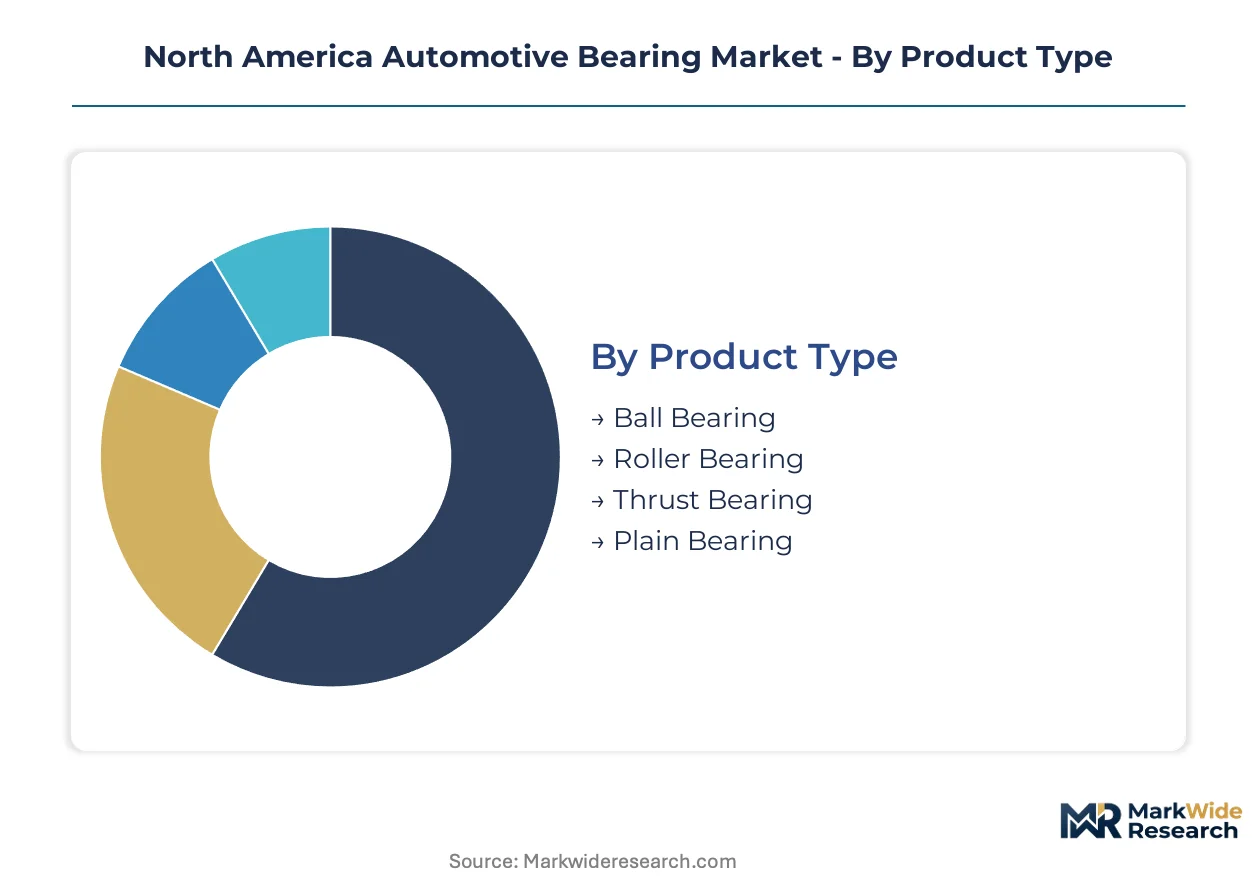
Segmentation in North America's automotive bearing market reveals how capital allocation and technical specialization diverge across powertrain architectures. Each dimension—product design, material composition, application target, and customer channel—carries distinct margin profiles and investment thresholds that shape supplier strategy across Detroit and Mexican manufacturing corridors.
Product Type:
Capital intensity peaks in roller bearing manufacturing, where through-hardened steel processing and precision grinding infrastructure demand the heaviest upfront equipment outlays.
- Roller Bearing:Tapered and cylindrical configurations dominate transmission and wheel hub assemblies across heavy-duty truck platforms. Detroit's OEM procurement teams specify these for load-bearing durability in commercial vehicle chassis systems subject to NHTSA durability protocols.
- Ball Bearing:Deep-groove and angular-contact designs serve electric motor shaft support and auxiliary power unit applications. Mexican assembly corridors in Guanajuato generate concentrated demand for compact ball bearing variants in passenger vehicle powertrains.
- Thrust Bearing:Axial-load configurations manage gear shift forces in automated manual transmissions. Tier-1 suppliers in Ontario integrate these into integrated e-axle modules for battery-electric platforms.
- Plain Bearing:Sleeve and flanged bushings reduce friction in suspension linkages and steering columns. Aftermarket channels in the US Southwest stock these for high-mileage fleet maintenance programs.
Most installed capacity flows through Roller Bearing. Expansion is steepest in Ball Bearing.
Material:
Cost tier stratification separates commodity steel from engineered ceramics, with plastic and composite grades occupying mid-range positioning for non-critical applications.
- Steel:Through-hardened alloy grades remain the baseline for commercial vehicle suspension and chassis bearings where impact resistance outweighs weight considerations. EPA fuel economy standards are tightening friction specifications that erode steel's historical cost advantage in driveline applications.
- Ceramic:Silicon nitride rolling elements enable 20,000+ RPM operation in electric motor shafts with reduced thermal expansion. SKF and NSK have anchored premium positioning through captive ceramic processing capabilities serving Detroit's EV powertrain engineering centers.
- Plastic:Polymer and thermoplastic composites reduce mass in auxiliary components with moderate load requirements. Tier-1 suppliers specify these for HVAC blower motors and window regulator mechanisms.
- Composite:Hybrid metal-polymer laminates balance stiffness and damping in steering column bearings. Aftermarket distributors in Texas and California stock these for corrosion-resistant replacement demand.
Steel retains the deepest installed base. Ceramic is climbing the fastest as electrification intensifies thermal specifications.
Application:
Volume concentration tracks vehicle production patterns, with transmission and chassis modules generating the highest unit throughput in Mexican and US assembly plants.
- Transmission:Manual, automatic, and e-axle gearbox bearings face diverging demand curves as electrification consolidates multi-speed architectures. NHTSA fuel economy mandates are compressing friction budgets that favor low-torque ceramic designs.
- Chassis:Wheel hub and driveline bearings support vehicle dynamics and load distribution across light-duty and commercial platforms. Guanajuato's vehicle assembly concentration generates localized procurement pull for heavy-duty tapered roller variants.
- Engine:Crankshaft and camshaft bearings face displacement risk as internal combustion volumes plateau. Ontario's remaining engine manufacturing facilities sustain residual demand for precision steel-backed designs.
- Suspension:Control arm and strut bearings manage road input isolation and steering precision. Aftermarket channels in the US Midwest service high-mileage replacement cycles for these wear-intensive components.
Chassis absorbs the largest production volume. Transmission is gaining share fastest amid e-axle integration trends.
End User:
Customer type determines certification burden and contract structure, with OEMs and Tier-1 suppliers imposing the most stringent validation protocols.
- OEMs:Ford, General Motors, and Stellantis specify bearings directly for proprietary powertrain and chassis architectures. These relationships demand 18-month qualification cycles that compress to 9-12 months for dedicated EV platform launches.
- Tier-1 Suppliers:Bosch, Denso, and Magna integrate bearings into transmission, motor, and axle subsystems delivered to vehicle assemblers. Their procurement teams are consolidating supplier tiers around firms with captive ceramic capabilities.
- Vehicle Assemblers:Tesla, Rivian, and Lucid source specialized high-speed bearings for integrated e-axle designs. These startups are accelerating validation timelines to match compressed product development cycles.
- Aftermarket Providers:Distributors and service chains supply replacement bearings for maintenance and repair. NAPA and O'Reilly Auto Parts dominate inventory positioning for standard steel-backed designs across the US Sun Belt.
Tier-1 Suppliers channel the majority of contract volume. Vehicle Assemblers are expanding procurement most aggressively as EV startups scale production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive manufacturing cluster commands the dominant share of North American bearing procurement, with specialized demand radiating from Michigan's powertrain engineering centers into Mexican assembly corridors and Canadian EV supply chains.
United States
NHTSA fuel economy standards and EPA emissions rules are tightening friction-reduction mandates for driveline components. The Inflation Reduction Act's domestic content requirements incentivize bearing reshoring to qualify assembled vehicles for consumer tax credits. Michigan's Detroit-Warren corridor concentrates OEM procurement teams specifying low-torque ceramic architectures for transmission modules.
Mexico
Guanajuato and Nuevo León vehicle assembly plants generate localized demand for wheel hub and chassis bearing supply chains serving export markets. Mexican manufacturing integration into USMCA trade frameworks positions the Bajío Region as a cost-competitive fabrication base. Tier-1 suppliers in Querétaro are consolidating procurement around firms with captive ceramic processing capabilities.
Canada
Ontario's battery cell and electric motor manufacturing investments create demand for localized precision bearing production serving integrated e-axle assembly. Federal clean technology investment tax credits support capital equipment upgrades for micrometer-tolerance finishing operations. Windsor-Toronto automotive corridor suppliers are recalibrating material portfolios toward silicon nitride hybrid configurations.
California
Electric vehicle startups in Silicon Valley and Los Angeles Basin are accelerating bearing validation timelines to match compressed product development cycles. CARB zero-emission vehicle mandates intensify thermal and rotational speed specifications beyond conventional steel capabilities. Fremont and Torrance engineering centers specify specialized high-speed bearings for 20,000+ RPM motor applications.
North America Automotive Bearing Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers consolidate tiers around captive ceramic capabilities and integrated e-axle expertise. The vendor base organizes into three tiers: multinational conglomerates with full material portfolios, mid-scale specialists in precision grinding, and regional fabricators serving aftermarket channels. Two archetypes define competitive positioning: firms with backward integration into silicon nitride powder processing, and those with downstream control over e-axle module assembly. Technology licensing and geographic expansion represent the dominant competitive moves as Japanese and European incumbents establish North American finishing capacity.
Among Japanese precision engineering houses, NSK Ltd., JTEKT Corporation, and NTN Corporation exemplify the R&D-intensive archetype, with their corporate structures reflecting keiretsu-affiliated supply chain relationships. These Tokyo and Osaka-based entities occupy positions emphasizing low-torque ball bearing architectures and ceramic hybrid development. SKF represents the European multinational model, with its Aktiebolag structure anchoring premium positioning through material science capabilities. The Timken Company and RBC Bearings, Inc. exemplify North American scale-driven fabrication, with their Inc.-structured entities focusing on tapered roller and specialty bearing production for heavy-duty applications.
| Leading Market Players |
|---|
| NSK Ltd. |
| JTEKT Corporation |
| NTN Corporation |
| SKF |
| Schaeffler AG |
| The Timken Company |
| RBC Bearings, Inc. |
| Nippon Thompson Co., Ltd. |
| Iljin Group |
| Others |
Value Network & Pricing Analysis
OEM procurement teams in Detroit are consolidating supplier tiers around firms with captive ceramic processing capabilities, forcing mid-scale fabricators to absorb certification costs or exit premium contract pools. This buyer-driven consolidation concentrates pricing power among silicon nitride hybrid specialists while compressing margins for commodity steel roller bearing producers serving Mexican assembly corridors.
Pricing Analysis
Alloy steel input cost pass-through dominates pricing dynamics for standard roller bearings, with scrap metal and energy pricing volatility transmitting directly to contract renegotiation cycles. Three-tier pricing structure across premium ceramic hybrid, certified steel, and economy-grade alloy separates SKF and NSK from Timken's heavy-duty positioning and regional aftermarket fabricators. Pricing pressure stems from NHTSA fuel economy mandates tightening friction-reduction specifications that erode steel's historical cost advantage. Tier-1 suppliers exhibit lowest price sensitivity due to qualification lock-in, while aftermarket distributors in the US Sun Belt face highest sensitivity from fleet operator procurement consolidation.
Supply Chain Analysis
Remanufacturing flows for high-mileage wheel hub assemblies create reverse-logistics value recovery for aftermarket distributors serving Midwest fleet operators. Supply concentrates in Germany, Japan, and China for precision grinding equipment and silicon nitride powder feedstock, with Mexican assembly corridors providing cost-competitive finishing capacity under USMCA frameworks. Raw material dependencies center on through-hardened bearing steel, ceramic powder precursors, and specialized grinding abrasives. Single-source vulnerability in East Asian ceramic processing equipment exposes North American fabricators to logistics disruption. Distribution runs through Tier-1 supplier integration into e-axle modules, with direct OEM contracting gaining share for specialized EV powertrain bearings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America's automotive bearing market functions as a stable compounder anchored by electrification-driven specification upgrades that sustain replacement demand across vehicle lifecycles.
For Market Incumbents: Extend ceramic hybrid production capacity in Ontario and Michigan to capture IRA domestic content requirements for clean vehicle tax credits. Deepen backward integration into silicon nitride powder processing to defend margin position against Japanese keiretsu-affiliated competitors. Consolidate supplier tiers by acquiring mid-scale precision grinding specialists facing certification cost burdens from dual NHTSA-EPA validation protocols. For New Entrants and Emerging Players: The Inflation Reduction Act in the United States opens a window for specialized high-speed bearing producers to qualify for domestic content thresholds in integrated e-axle assemblies. Target Ontario's battery cell manufacturing corridor for localized precision bearing production serving electric motor shaft applications. Pursue parallel testing frameworks that compress bearing approval timelines to 9-12 months for EV startup procurement teams accelerating platform development cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale ceramic processing specialists possessing captive silicon nitride capabilities and existing Tier-1 supplier relationships. Long-term viability over a 5-10 year horizon favors firms with demonstrated qualification success across both legacy internal combustion and emerging electrified powertrain architectures. Monitor NHTSA electrification timeline announcements and EPA powertrain rule revisions as inflection indicators for procurement criteria shifts across Detroit's manufacturing base.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Hybrid Capacity Expansion | Captures IRA domestic content requirements for EV tax credit qualification in Michigan and Ontario corridors. |
| Backward Integration into Powder Processing | Reduces East Asian supply concentration risk for silicon nitride precursors critical to 20,000+ RPM motor bearings. |
| Parallel Testing Framework Adoption | Compresses validation timelines to match Tesla and Rivian's accelerated e-axle development cycles. |
| Mexican Manufacturing Footprint Expansion | Positions cost-competitive finishing capacity to serve Guanajuato assembly plants under USMCA trade frameworks. |
| Tier-1 Supplier Partnership Deepening | Locks in procurement relationships with Bosch and Magna for integrated transmission and e-axle module supply. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and ceramic processing equipment specialists with secondary validation. Bottom-up triangulation drew from vehicle production databases, IHS Markit registration data, SEC filings from bearing manufacturers, and NHTSA fuel economy compliance reports. Top-down cross-checks referenced EPA emissions rulemakings and IRA domestic content guidance documents.
Segment-weighting approaches distributed value and volume estimates across product type, material composition, application target, and end-user channel dimensions. The analytical framework modeled propulsion architecture splits between internal combustion, hybrid, and battery-electric platforms alongside content-per-vehicle trajectories for bearing count and specification tier. CAGRs were derived from regression analysis of historical production volumes married to electrification adoption curves and regulatory compliance timelines. Forecast inputs incorporated NHTSA electrification scenario planning and Tier-1 supplier capital expenditure disclosures for e-axle manufacturing capacity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA powertrain rule revisions or extended alloy steel price volatility. Practitioners should monitor NHTSA electrification timeline announcements, silicon nitride powder supply contract renewals, and Tier-1 supplier qualification timeline compressions for early signals of procurement criteria shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Automobile Accessories Market
Automotive Components
Global Automotive Collapsible Steering Column Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Drive System Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market