
 Europe Automotive Relay Market | 2026-2036
Europe Automotive Relay Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Relay Market Foresight
Market Context
German component manufacturing is realigning toward high-voltage relay architectures for electrified platforms. Robert Bosch GmbH leverages its vertically integrated semiconductor capabilities to dominate powertrain relay supply. TE Connectivity anchors its position through specialized high-current connector-relay integration for OEM harness systems. HELLA GmbH and Co. KGaA competes in lighting relay segments with advanced solid-state switching portfolios.
Technical Definition and Segments
Europe automotive relays are electromechanical or solid-state switching devices rated for 12V to 800V operation, controlling current flow between battery systems, control modules, and actuator loads across vehicle electrical architectures. Solid-state relay variants are displacing electromechanical units in powertrain applications due to superior cycle life and arc suppression under inverter switching loads. Passenger car OEM installations command the largest value pool, while safety system relays carry premium positioning through ASIL-D functional safety certification requirements. Aftermarket retrofit demand extends from aging commercial vehicle fleets requiring relay replacement across lighting and starter motor circuits.
Regulatory Environment
The EU Green Deal and Euro 7 standards from the European Commission mandate CO2 reduction trajectories that expand electrified powertrain relay counts per vehicle. ECE R10 electromagnetic compatibility regulations govern relay emission profiles for connected vehicle architectures. REACH and RoHS frameworks restrict hazardous substance content in relay contact materials and housings. Stakeholders must monitor battery relay standards evolution as 800V architectures penetrate premium vehicle segments.
Market Dynamics
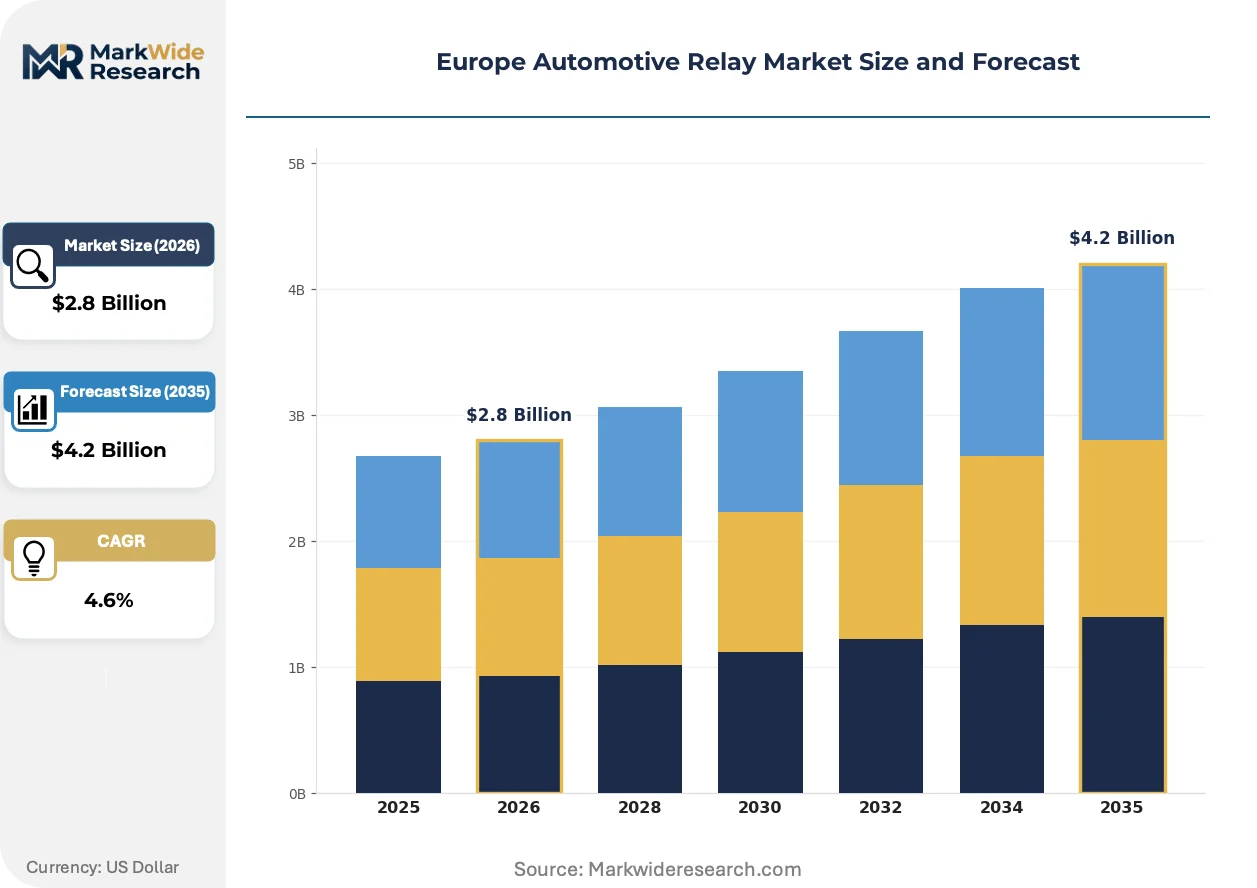
The EU Green Deal's CO2 reduction mandates are forcing powertrain electrification at scale, multiplying relay counts per vehicle while shifting specifications toward 800V solid-state architectures. German OEMs and Czech supplier networks are reconfiguring procurement specifications to match this voltage transition.
Growth Catalysts
- Euro 7 emission standards:The European Commission's stringent limits on internal combustion engines accelerate hybrid and battery-electric platform rollouts, each requiring expanded relay systems for power distribution and thermal management.
- 800V traction architectures:Premium EV platforms from Stuttgart and Munich manufacturing clusters demand high-voltage battery disconnect relays with arc-quenching capabilities beyond traditional 12V/48V specifications.
- ASIL-D functional safety certification:Safety-critical relay applications in braking and steering systems command premium positioning as OEMs integrate redundant switching for autonomous driving readiness.
Market Restraints
- Silver-copper contact material costs:Precious metal price volatility in relay contact plating creates margin pressure for electromechanical manufacturers serving cost-sensitive commercial vehicle segments.
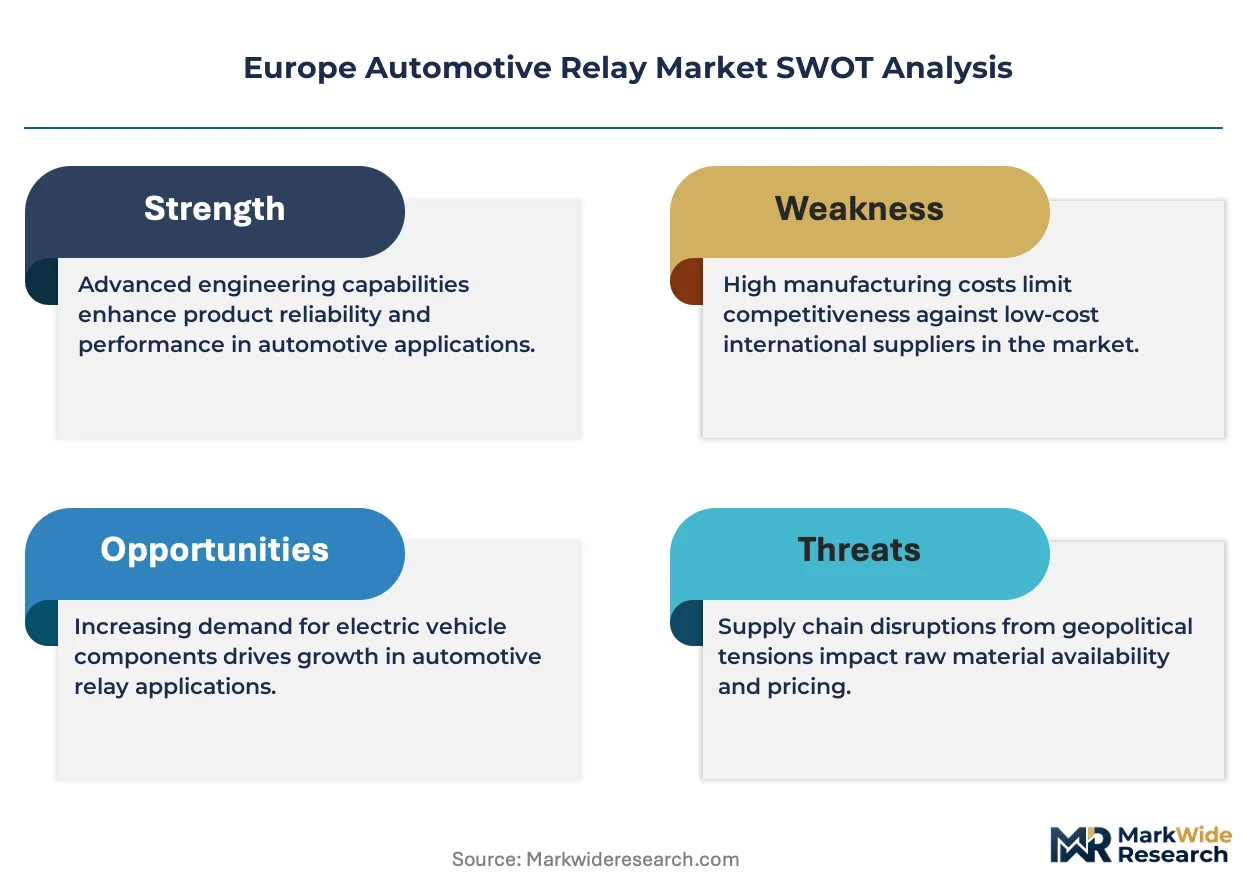
- Semiconductor foundry concentration:Solid-state relay production depends on silicon carbide and gallium nitride wafer supply concentrated in East Asian fabrication facilities, exposing European module assemblers to allocation risk.
- REACH substance restrictions:ECHA's evolving candidate list for hazardous substances complicates contact material formulations and housing polymer selections, extending qualification timelines.
Strategic Opportunities
- Polish and Romanian manufacturing expansion:Greenfield relay assembly investments in lower-cost EU member states capture OEM localization incentives while maintaining proximity to German vehicle production.
- Vehicle-to-grid bidirectional charging:Emerging grid-interactive EV platforms require specialized relays capable of handling reverse power flow, opening new specification categories beyond traditional automotive applications.
- CSRD supply chain disclosure mandates:The EU's Corporate Sustainability Reporting Directive creates competitive differentiation for relay manufacturers with verified carbon footprints and circular material recovery programs.
Industry Challenges
- High-voltage safety engineering talent:The shortage of engineers qualified in 800V arc containment and insulation coordination delays product development cycles for Tier-2 suppliers.
- ECE R10 electromagnetic compatibility testing:Expanding relay emission test protocols for connected vehicle architectures extend certification timelines and require specialized anechoic chamber investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Relay Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Solid-State, Reed, Miniature Application: Powertrain, Lighting, Safety Systems, Infotainment Installation: On-board, Aftermarket, OEM, Retrofit End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Others |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, TE Connectivity, Panasonic Corporation, Fujitsu Ltd., HELLA GmbH and Co. KGaA, Omron Corporation, Littelfuse, Inc., Nidec Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Relay Market Shifts & Advancements
Silicon carbide power electronics and solid-state switching are compressing the traditional electromechanical relay's dominance in powertrain applications. Component suppliers must requalify entire product portfolios for voltage classes that did not exist five years ago.
Silicon carbide-based solid-state relays are overtaking electromechanical contactors in battery disconnect applications due to elimination of contact arcing and welding under inverter switching loads. German premium EV platforms have standardized on solid-state architectures for main battery isolation. This voltage-class migration is compressing the addressable market for traditional high-current electromechanical products.
REACH and RoHS frameworks from ECHA are restricting cadmium and lead content in relay contact alloys and housing thermoplastics. Manufacturers are reformulating silver-tin oxide and silver-nickel contact materials to maintain conductivity while eliminating restricted substances. Czech and Slovak component suppliers face the steepest reformulation burden given their concentration in cost-optimized electromechanical relay categories.
Fleet operators and leasing companies are consolidating procurement specifications across multi-brand vehicle pools, standardizing relay replacement intervals and supplier qualification criteria. This buying-pattern compression favors relay manufacturers with pan-European service networks and consolidated part numbering systems. The aftermarket channel in Spain and Italy shows the most visible consolidation, where aging commercial vehicle fleets drive replacement volume through distributor networks rather than OEM captive parts operations.
Europe Automotive Relay Market Segmentation
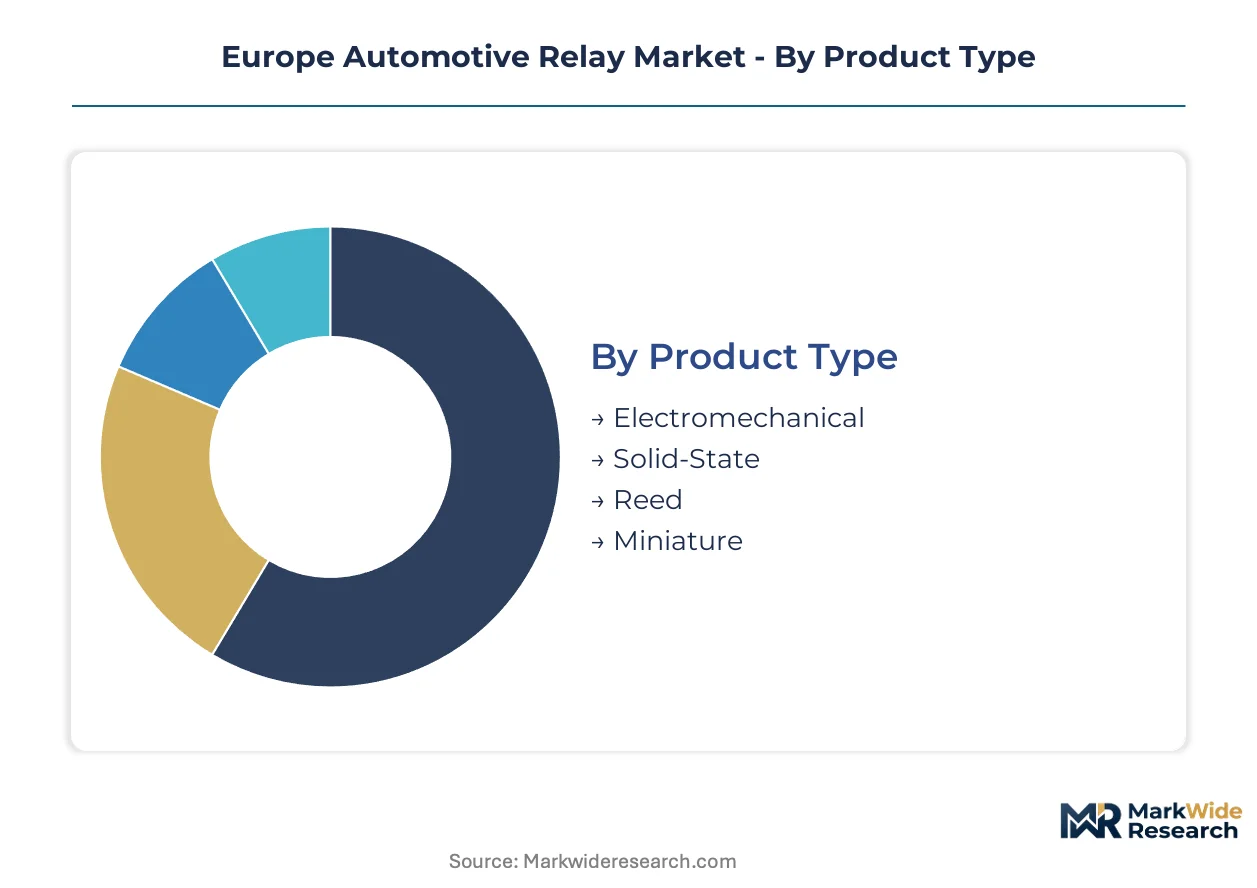
Relay segmentation in Europe reflects divergent upgrade cycles across electrification tiers. Solid-state architectures demand wholesale replacement of electromechanical inventories, while safety system mandates force faster refresh rates than lighting or infotainment applications.
Product Type:
Upgrade urgency varies sharply by switching technology, with voltage-class migrations forcing premature replacement of established electromechanical stocks.
- Electromechanical:Conventional coil-driven contact mechanisms dominate commercial vehicle starter and lighting circuits across Czech and Polish supplier networks. German OEMs are phasing out these units from battery disconnect positions as 800V architectures render arc-prone contacts obsolete.
- Solid-State:Silicon carbide and gallium nitride switching elements eliminate contact wear for inverter-interfaced powertrain loads. Stuttgart and Munich manufacturing clusters have standardized solid-state battery isolation relays, with demand concentrating in premium EV platforms where cycle life exceeds 10 million operations.
- Reed:Hermetically sealed magnetic switches serve low-current sensor and control module interfaces. These units see stable replacement demand from aging vehicle electronics across Spanish and Italian aftermarket channels.
- Miniature:Compact PCB-mounted variants populate body control modules and climate management systems. Czech component suppliers specialize in high-volume miniature relay production for cost-optimized vehicle segments.
Electromechanical relays sit at the top of the volume ranking, with solid-state variants climbing the fastest as voltage architectures migrate upward.
Application:
Functional safety certification tiers create divergent margin structures across vehicle electrical domains, with powertrain and safety systems commanding premium positioning over convenience applications.
- Powertrain:Battery disconnect, inverter isolation, and thermal management switching operate across 48V to 800V ranges. German OEM procurement specifications now mandate solid-state architectures for main traction battery isolation, displacing electromechanical contactors.
- Safety Systems:ASIL-D certified relays for braking, steering, and occupant protection carry redundant switching requirements. These units face accelerated replacement cycles as autonomous driving readiness mandates expand fault-tolerant architectures.
- Lighting:Headlamp and signal circuit switching spans halogen, xenon, and LED load profiles. HELLA GmbH and Co. KGaA anchors this segment with integrated relay-controller modules for German premium brands.
- Infotainment:Low-current signal routing for displays and audio systems operates at standard 12V levels. This application sees longest replacement intervals and greatest price compression from module integration trends.
Powertrain applications generate the steepest expansion trajectory, while infotainment relay demand is flattening as domain controller consolidation advances.
Installation:
Channel economics split sharply between captive OEM supply and fragmented aftermarket replacement, with retrofit demand emerging from electrification conversion programs.
- On-board:Factory-installed relays embedded in vehicle harness systems at assembly. TE Connectivity dominates this channel through specialized high-current connector-relay integration for German OEM harness specifications.
- Aftermarket:Replacement units distributed through independent channels for aging fleet maintenance. Spanish and Italian commercial vehicle operators drive volume through consolidated procurement across multi-brand pools.
- OEM:Direct supply arrangements with vehicle manufacturers for original equipment fitment. Robert Bosch GmbH leverages vertically integrated semiconductor capabilities to secure long-term supply agreements.
- Retrofit:Electrification conversion kits for internal combustion platforms requiring upgraded switching components. Emerging demand centers on Czech and Slovak commercial vehicle retrofit programs targeting Euro 7 compliance.
OEM supply captures the dominant value share, though aftermarket channels are expanding most quickly as Eastern European fleet aging accelerates replacement velocity.
End User:
Vehicle class electrification timelines create divergent relay specification roadmaps, with passenger cars leading voltage migration and commercial vehicles trailing on cost constraints.
- Passenger Cars:Premium EV platforms from Stuttgart and Munich manufacturing clusters drive 800V solid-state relay adoption. These vehicles carry 3-4x relay counts versus internal combustion equivalents due to distributed power distribution architectures.
- Commercial Vehicles:Heavy-duty trucks and buses retain electromechanical dominance in starter and lighting circuits across cost-sensitive fleet procurement. Polish and Romanian assembly operations concentrate on standard-voltage relay supply for this segment.
- Two-Wheelers:Motorcycles and scooters operate primarily at 12V with minimal relay counts for ignition and lighting. Italian manufacturers anchor regional demand through specialized compact relay specifications.
- Others:Agricultural machinery, construction equipment, and specialty vehicles requiring sealed relay housings for severe operating environments. These applications prioritize environmental protection over switching speed or cycle life.
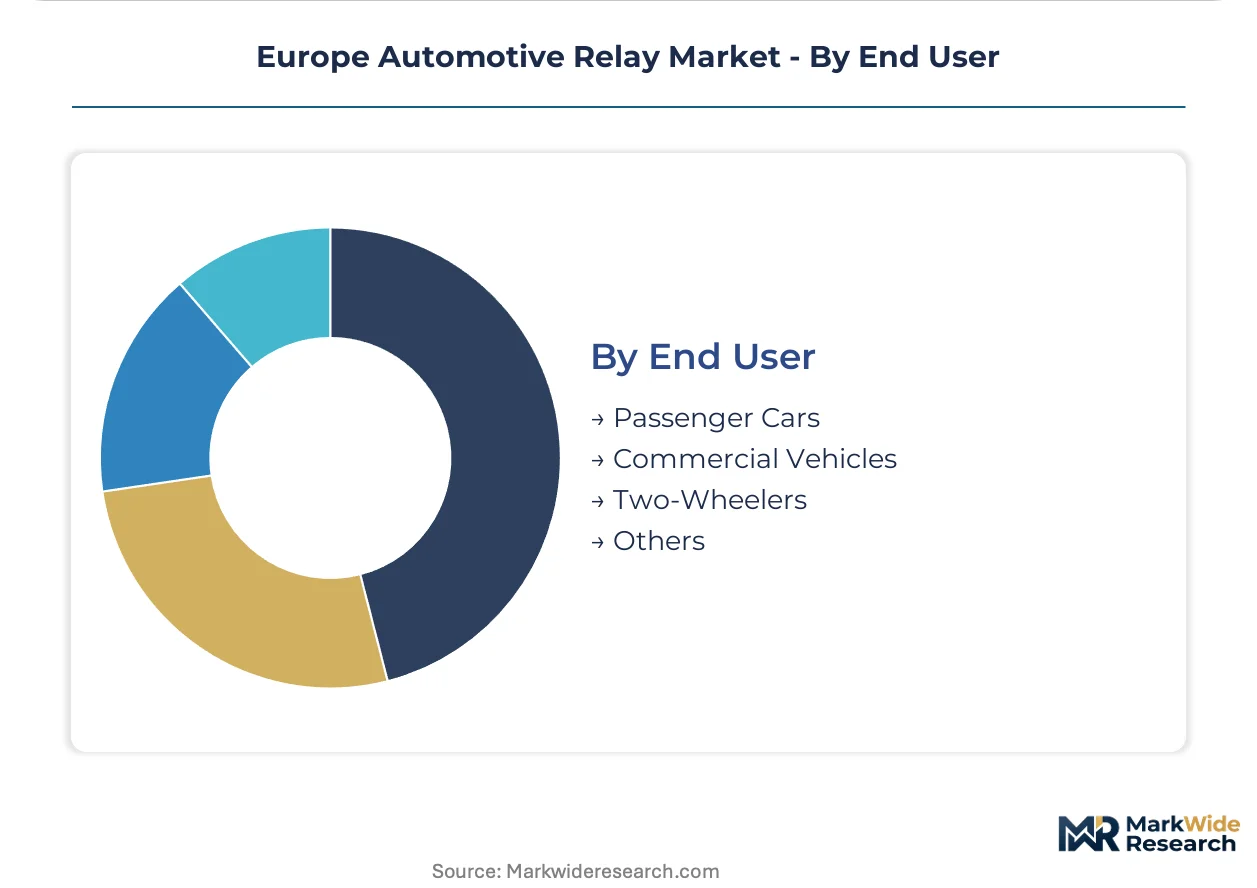
Passenger cars command the largest installed base, with commercial vehicles gaining share fastest as electrification mandates extend to heavy-duty segments under EU Green Deal trajectories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting relay assembly toward lower-cost EU member states as REACH compliance costs widen the manufacturing cost gap between Western and Eastern Europe. Production migration accelerates where ECHA substance restrictions are uniform but labor and facility costs diverge sharply.
Germany
Stuttgart and Munich manufacturing clusters demand 800V solid-state battery isolation relays for premium EV platforms. KBA vehicle type-approval standards enforce electromagnetic compatibility testing that extends product qualification timelines. Bavarian suppliers are reconfiguring semiconductor packaging lines to match silicon carbide switching specifications from domestic OEMs.
Czech Republic
Cost-optimized electromechanical relay production concentrates in Moravian assembly corridors serving commercial vehicle starter and lighting circuits. EU Green Deal electrification mandates are forcing Czech suppliers to retool for 48V mild-hybrid architectures. Brno-based component houses face the steepest REACH reformulation burden for silver-tin oxide contact materials.
Poland
Greenfield relay assembly investments in Lower Silesia capture German OEM localization incentives while maintaining proximity to vehicle production. ECE R10 electromagnetic compatibility regulations govern emission profiles for exports to Western European markets. Warsaw-area logistics hubs consolidate aftermarket distribution for aging Eastern European commercial fleets.
Italy
Specialized compact relay specifications for two-wheeler ignition systems anchor demand in Emilia-Romagna manufacturing zones. Euro 7 emission standards accelerate hybrid platform rollouts requiring expanded relay counts per motorcycle. Milan-based distributors are consolidating procurement specifications across multi-brand scooter fleets.
Spain
Aging commercial vehicle fleets in Catalonia drive aftermarket replacement volume through independent distributor networks rather than OEM captive parts operations. CSRD supply chain disclosure mandates create competitive differentiation for relay manufacturers with verified carbon footprints. Barcelona logistics corridors serve as consolidation points for Mediterranean aftermarket distribution.
Europe Automotive Relay Market Competitive Landscape
German producers anchor the premium-tier supply; Czech and Polish specialists hold cost-optimized electromechanical segments. The vendor base splits between vertically integrated semiconductor-capable manufacturers and module assemblers dependent on external wafer supply. Three archetypes dominate: silicon carbide switching specialists, high-current connector-integrators, and legacy electromechanical fabricators. M&A activity concentrates on semiconductor packaging capabilities; capacity expansion targets Polish and Romanian greenfield sites.
Within the vertically integrated tier, Robert Bosch GmbH and TE Connectivity exemplify divergent strategic positions. Bosch anchors powertrain relay supply through captive semiconductor fabrication, while TE Connectivity occupies a position in high-current connector-relay integration for OEM harness systems. HELLA GmbH and Co. KGaA represents the specialized lighting relay segment with solid-state switching portfolios.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| TE Connectivity |
| Panasonic Corporation |
| Fujitsu Ltd. |
| HELLA GmbH and Co. KGaA |
| Omron Corporation |
| Littelfuse, Inc. |
| Nidec Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in Moravian assembly corridors anchor electromechanical relay production, their conservative capital structures enabling patient pricing discipline even as REACH compliance costs erode margins. Their ownership model insulates pricing from quarterly earnings pressure while forcing hard supply choices on silver-copper contact sourcing.
Pricing Analysis
Distributor margin compression runs through Czech and Polish aftermarket channels as fleet operators consolidate procurement across multi-brand pools. Three-tier pricing structure across ASIL-D certified safety relays, standard powertrain units, and economy lighting components reflects certification-grade differentiation. Pricing pressure stems from semiconductor foundry allocation volatility for solid-state variants. Commercial vehicle fleet operators exhibit highest price sensitivity, while German premium OEMs accept premium positioning for 800V battery isolation relays.
Supply Chain Analysis
Silicon carbide wafer supply rests on Taiwanese and South Korean specialty semiconductor producers, exposing European module assemblers to single-source vulnerability. Silver-copper contact alloys and gallium nitride substrates feed from East Asian material refineries. Tariff exposure concentrates on semiconductor packaging equipment imports. Distribution runs through Warsaw-area logistics hubs consolidating aftermarket volume for aging Eastern European commercial fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by demand-shift toward ASIL-D certified solid-state architectures commanding premium positioning over electromechanical substitutes.
For Market Incumbents: Deploy captive semiconductor packaging capabilities to defend against silicon carbide switching specialists threatening electromechanical incumbency. Prioritize backward integration into gallium nitride wafer sourcing to reduce allocation risk from East Asian foundries. Secure long-term supply agreements with Stuttgart and Munich OEM clusters before platform standardization locks in competitor architectures. For New Entrants and Emerging Players: The gap between premium 800V solid-state battery isolation relays and economy 12V electromechanical lighting units offers entry space for specialized 48V mild-hybrid architectures. Target Czech commercial vehicle retrofit programs facing Euro 7 compliance deadlines with cost-optimized relay modules. Lead with ECE R10 pre-certified designs to compress OEM qualification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among legacy electromechanical fabricators with unconverted 12V/24V product portfolios. Five-to-ten year viability hinges on successful voltage-class migration to solid-state architectures. Signal to watch: German OEM procurement specifications dropping electromechanical options from battery disconnect positions entirely.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Packaging Investment | Captive semiconductor capabilities secure supply agreements with Stuttgart premium EV platforms. |
| ASIL-D Certification Acceleration | Functional safety credentials unlock safety system relay positioning for autonomous driving readiness. |
| Polish Greenfield Assembly Expansion | Lower Silesia facilities capture German OEM localization incentives while maintaining proximity. |
| REACH-Compliant Contact Reformulation | Silver-tin oxide alternatives maintain conductivity while satisfying ECHA substance restrictions. |
| Vehicle-to-Grid Relay Development | Bidirectional charging capabilities open specification categories beyond traditional automotive applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and semiconductor packaging specialists with secondary validation through vehicle production databases, IHS Markit registration data, ECHA substance restriction filings, and customs trade records. Bottom-up relay shipment tallies and top-down vehicle content-per-unit estimates were triangulated to anchor volume figures.
Comparable historical periods anchored the projection horizon across solid-state and electromechanical technology transitions, with segmentation modeling spanning switching technology, application domain, installation channel, and vehicle class. CAGRs derived from fitted growth curves incorporating Euro 7 regulatory phase-in schedules and German OEM platform rollout timelines. Propulsion architecture mix and voltage-class migration curves served as primary forecast inputs.
Caveats apply where semiconductor foundry allocation disruptions or ECHA substance list expansions could materially shift the outlook. Forecasts reflect assumptions on EV adoption trajectories and REACH compliance timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Automotive Fuel Injection System Market
Automotive Components
Automotive Retarders Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
Automotive Emblem Market
Automotive Components
China Automotive Composites Market
Automotive Components
Automotive Solenoid Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Global Automotive Collapsible Steering Column Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Electric Vehicle Fluid Lubricants Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Automobile Accessories Market