
 Automobile AC Condensers Market | 2026-2036
Automobile AC Condensers Market Size, Share, and Industry Trends Forecast 2026-2036
Automobile AC Condensers Market Insights
Aftermarket service revenue is narrowing as OEMs extend warranty periods and captive service networks absorb routine maintenance. Denso Corporation leverages its integrated thermal-system portfolio to dominate first-fit supply for Japanese and North American vehicle programs. Mahle GmbH anchors European production through specialized microchannel manufacturing lines in Germany and Slovakia. Valeo SA competes aggressively on electrification-ready condenser platforms designed for hybrid thermal management.
An automobile AC condenser is a heat-exchanger component typically constructed from aluminum alloy tubes and fins, brazed into a sealed circuit that desuperheats and liquefies refrigerant vapor ahead of the expansion valve. Its primary purpose is to reject cabin heat to ambient air, with operating pressures commonly tested to 30 bar burst ratings and fin densities optimized for frontal-area constraints. Aluminum tube-and-fin configurations retain the largest installed base across legacy internal-combustion vehicles, while microchannel designs are gaining fastest in electric-vehicle applications where packaging space and refrigerant charge minimization command premium engineering. OEM end users capture the dominant margin pool through long-term platform contracts, whereas aftermarket channels face margin compression from catalog proliferation and price transparency.
EPA refrigerant management rules under Section 608 and the AIM Act phase-down of HFCs are forcing condenser redesigns for lower-GWP alternatives such as R-1234yf and CO2 systems. NHTSA fuel-economy standards and California Air Resources Board zero-emission vehicle mandates compound thermal-efficiency requirements by linking climate-system load to electric range. Stakeholders must monitor refrigerant-transition timelines and thermal-test-protocol harmonization between EPA, CARB, and SAE International to avoid platform-certification delays.
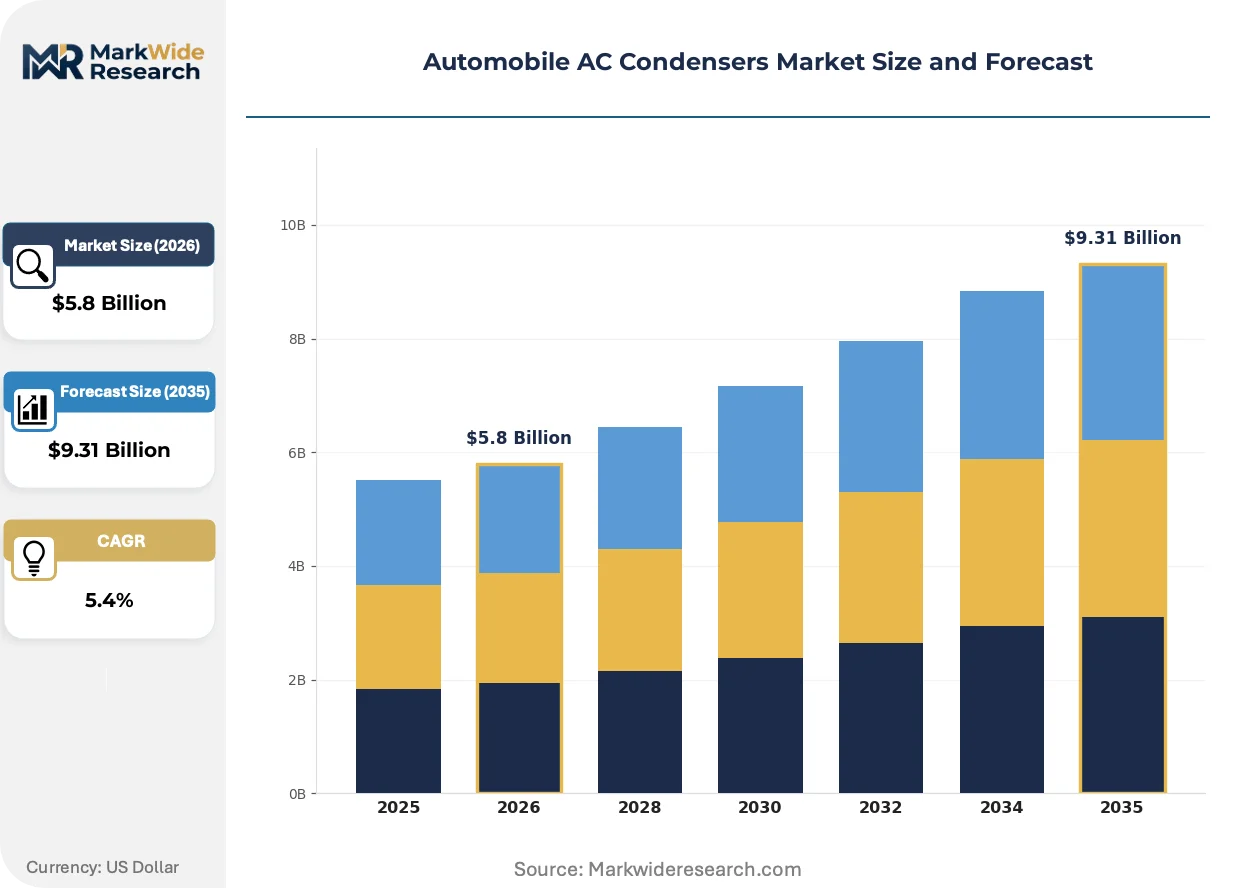
Market Dynamics
Passenger vehicle electrification is compressing thermal-system packaging envelopes and forcing condenser architectures toward microchannel aluminum designs that minimize refrigerant charge while maximizing heat-rejection density per frontal area.
Growth Catalysts
- EPA AIM Act phase-down:HFC refrigerant restrictions under Section 608 are mandating condenser redesigns for R-1234yf and CO2 compatibility across US vehicle platforms.
- Battery-electric vehicle thermal loads:Cabin cooling demand directly consumes driving range, amplifying OEM procurement for high-efficiency heat exchangers in hybrid and BEV programs.
- China NEV subsidies:Dual credit policies and new energy vehicle purchase incentives are accelerating domestic OEM adoption of lightweight condenser architectures.
Market Restraints
- Aluminum price volatility:Tube-and-fin raw material exposure concentrates margin risk with London Metal Exchange pricing swings and energy-intensive smelting costs.
- Brazing equipment concentration:Vacuum furnace and controlled-atmosphere brazing line supply clusters in Germany and Japan, creating capex bottlenecks for new entrants.
- Refrigerant transition friction:SAE International test protocol gaps between R-134a legacy systems and R-1234yf/CO2 designs are extending platform validation timelines.
Strategic Opportunities
- India two-wheeler thermalization:Premium motorcycle and scooter segments are adding cabin comfort systems, opening condenser demand outside traditional passenger vehicle channels.
- EU F-Gas Regulation revision:Lower-GWP mandates are creating first-mover advantage for suppliers with CO2 transcritical condenser testing capabilities.
- Remanufacturing channel development:Circular economy directives and core return programs are enabling aftermarket revenue capture through reconditioned aluminum heat exchangers.
Industry Challenges
- Microchannel brazing expertise scarcity:Thin-wall aluminum multiport extrusion joining requires specialized process engineers, constraining capacity expansion at tier-two suppliers.
- Platform-specific validation cycles:OEM thermal test protocols vary across German, Japanese, and US vehicle programs, fragmenting engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automobile AC Condensers Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Copper, Hybrid, Plastic End User: OEMs, Aftermarket, Vehicle Assemblers, Repair Shops Technology: Tube & Fin, Plate & Fin, Microchannel, Smooth Bore Installation Type: Direct Fit, Universal, Custom Fit, Compact |
| Companies Covered | Denso Corporation, Valeo SA, Mahle GmbH, Hanon Systems, Sanden Corporation, Calsonic Kansei Corporation, Modine Manufacturing Company, Continental AG, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automobile AC Condensers Market Trends and Innovations
Refrigerant chemistry transitions and electric vehicle packaging constraints are jointly forcing material and manufacturing process reinvention across condenser supply chains.
Microchannel aluminum extrusions with internal port counts exceeding twelve are replacing traditional tube-and-fin assemblies in electric vehicle programs. OEM thermal engineers at battery-electric platforms are specifying these designs to cut refrigerant charge volumes by half. The technology is rendering obsolete legacy mechanically assembled condensers that depend on higher internal volumes and thicker wall sections.
The EU F-Gas Regulation and its periodic tightening of hydrofluorocarbon quotas are compelling condenser manufacturers to validate CO2 transcritical pressure ratings. European OEMs face burst-test requirements exceeding 120 bar, fundamentally altering header tank and manifold design practices. German and Slovak production lines are retooling brazing parameters to accommodate thicker aluminum stock and reinforced joint geometries.
Fleet operators and mobility-as-a-service providers are consolidating thermal-system procurement under long-term total-cost-of-ownership contracts rather than per-unit component purchasing. This behavior compresses supplier margins while demanding predictive failure analytics and guaranteed uptime commitments. The shift is most pronounced in California ride-hail electrification mandates and European corporate fleet decarbonization programs.
Automobile AC Condensers Market Segmentation
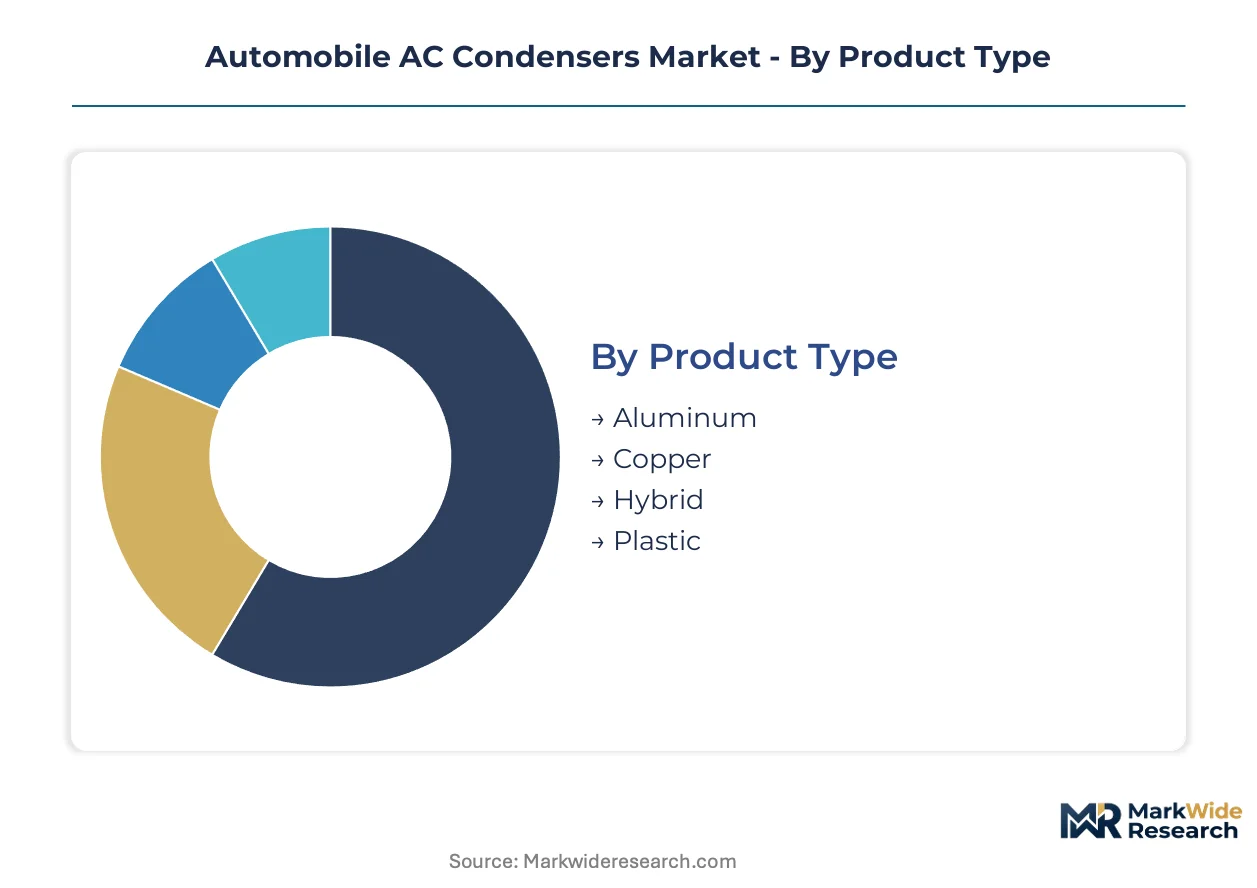
Condenser segmentation dictates procurement economics, with OEM captive supply chains operating on platform-specific validation cycles while aftermarket channels compete on catalog breadth and price transparency. Understanding material, technology, and installation-type splits reveals where margin pools concentrate and where commoditization pressures mount.
Product Type:
After-sales service intensity varies sharply by material—aluminum condensers dominate warranty-covered replacements under extended OEM service contracts, while copper and hybrid configurations drive independent repair shop revenue.
- Aluminum:Tube-and-fin and microchannel architectures rely on 3003 and 6061 alloy brazing stock, with fin densities optimized for 30 bar burst ratings. Passenger vehicle OEMs in China and Germany specify aluminum for lightweighting compliance with NHTSA fuel-economy standards and EU CO2 fleet targets. By volume, aluminum leads. By growth pace, hybrid configurations are expanding most quickly.
- Copper:Legacy mechanically assembled designs persist in commercial vehicle and heavy-duty applications where corrosion resistance outweighs weight penalties. Demand concentrates in Indian and Brazilian truck retrofit markets where older R-134a systems remain operational.
- Hybrid:Aluminum-copper composite headers with aluminum multiport extrusions balance thermal conductivity and cost. Japanese OEMs favor these for hybrid vehicle thermal management where refrigerant charge minimization is critical.
- Plastic:Glass-reinforced nylon end tanks reduce mass in entry-level passenger cars. Southeast Asian assemblers specify plastic for cost-sensitive compact vehicle programs.
Material selection tracks refrigerant chemistry transitions, with aluminum and hybrid designs capturing platform redesigns for R-1234yf and CO2 compatibility.
End User:
Cost-tier stratification separates long-term platform contracts from spot-market purchasing, with OEMs extracting volume discounts while repair shops absorb catalog fragmentation costs.
- OEMs:First-fit procurement locks suppliers into 5-7 year platform agreements with thermal-test protocol compliance requirements. German and US vehicle programs dominate contract value.
- Aftermarket:Catalog proliferation and price transparency compress margins. Independent distributors serve legacy vehicle parc with tube-and-fin replacements.
- Vehicle Assemblers:Contract manufacturers in Mexico and Eastern Europe source condensers under total-cost-of-ownership agreements with guaranteed uptime clauses.
- Repair Shops:Quick-turn universal fitments and remanufactured units drive transaction volume. California CARB refrigerant handling certification requirements filter shop eligibility.
OEMs command the dominant margin pool. Aftermarket channels gain share fastest through remanufacturing programs and circular economy core return systems.
Technology:
Volume concentration in legacy tube-and-fin contrasts with application-specific acceleration in microchannel designs for electrified platforms.
- Tube & Fin:Mechanically assembled round-tube designs with louvered aluminum fins retain the largest installed base across internal-combustion vehicle parc. Cost optimization drives demand in emerging market replacement channels.
- Plate & Fin:Bar-and-plate aluminum constructions suit heavy-duty and off-highway applications with severe-duty thermal cycling. Mining and construction OEMs in Australia and Canada specify these for durability.
- Microchannel:Multiport extrusions with internal port counts exceeding twelve minimize refrigerant charge and frontal area. Battery-electric vehicle programs in China, Germany, and California mandate microchannel for range preservation.
- Smooth Bore:Reduced internal surface roughness lowers pressure drop in CO2 transcritical systems. European OEMs validate smooth bore for EU F-Gas Regulation compliance.
Tube-and-fin dominates current unit volume. Microchannel configurations show the steepest expansion trajectory as electrification compresses packaging envelopes.
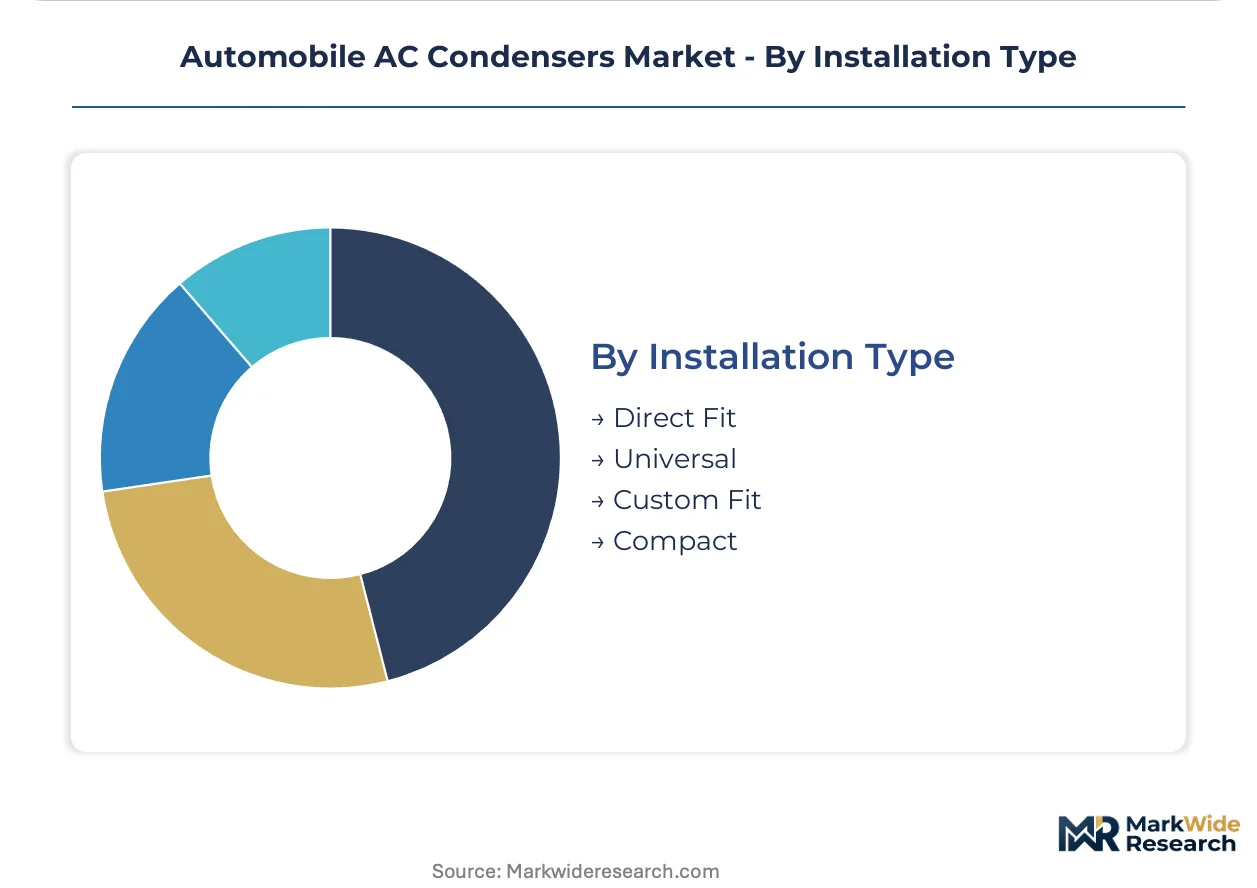
Installation Type:
Customer-type differentiation separates platform-engineered direct fitments from price-driven universal configurations.
- Direct Fit:OEM-validated designs with exact thermal performance maps and mounting geometries. Platform-specific validation cycles in Japanese and German programs lock in supplier relationships.
- Universal:Adjustable header positions and multi-fit brackets serve fragmented vehicle parc. Independent aftermarket distributors stock universal units for inventory efficiency.
- Custom Fit:Engineered-to-order condensers for specialty vehicle and motorsport applications. Low-volume UK and Italian niche manufacturers drive specification.
- Compact:Reduced frontal-area designs for city cars and electric microvehicles. Chinese NEV subsidies accelerate compact specification in domestic urban mobility programs.
Direct fit commands OEM contract value. Compact installations are gaining share fastest as urban vehicle footprints shrink and electric powertrain packaging constraints tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply by geography. United States OEMs absorb premium engineering costs for electrification compliance, while Indian and Brazilian aftermarket channels prioritize cost minimization over thermal efficiency gains.
United States
Domestic OEMs specify microchannel condensers for battery-electric vehicle programs to preserve driving range under NHTSA fuel-economy standards. EPA AIM Act HFC phase-down rules under Section 608 mandate R-1234yf compatibility validation. Detroit thermal engineering clusters concentrate platform testing for CO2 transcritical systems.
Germany
Luxury vehicle manufacturers drive demand for high-pressure aluminum architectures capable of withstanding CO2 transcritical operation above 120 bar. EU F-Gas Regulation quota tightening accelerates refrigerant transition timelines. Stuttgart and Munich engineering centers validate next-generation header tank geometries for reinforced joint integrity.
China
Domestic NEV subsidies and dual credit policies compress thermal system packaging for urban electric mobility platforms. MIIT new energy vehicle standards mandate refrigerant charge minimization. Yangtze River Delta manufacturing corridors scale microchannel extrusion capacity for export and domestic OEM supply.
Japan
Hybrid vehicle thermal management requirements sustain demand for aluminum-copper composite condenser configurations. METI energy efficiency standards link climate system performance to vehicle certification. Nagoya and Tokyo supplier clusters specialize in thin-wall multiport extrusion joining for refrigerant charge-critical applications.
India
Two-wheeler cabin comfort system adoption opens condenser demand outside traditional passenger vehicle channels. BIS automotive component standards and state-level electric mobility policies shape procurement specifications. Pune and Chennai manufacturing zones assemble tube-and-fin replacements for legacy vehicle parc maintenance.
Automobile AC Condensers Market Competitive Landscape
Capability concentration sits with integrated thermal system specialists; scale advantage sits with diversified automotive component conglomerates. The market structures around three tiers: full-system integrators with captive OEM relationships, dedicated heat exchanger fabricators with brazing expertise, and regional assemblers serving aftermarket price points. Dominant competitive moves include backward integration into aluminum extrusion supply and strategic partnerships for CO2 transcritical testing infrastructure.
Among Japanese and European integrated suppliers, Denso Corporation and Valeo SA occupy positions exemplifying full-system thermal capability, while Mahle GmbH anchors the dedicated heat exchanger fabrication tier with specialized European production infrastructure. These three entities represent the archetype spectrum from integrated platform supply to focused component engineering.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo SA |
| Mahle GmbH |
| Hanon Systems |
| Sanden Corporation |
| Calsonic Kansei Corporation |
| Modine Manufacturing Company |
| Continental AG |
| Delphi Technologies |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese microchannel extrusion facilities is compressing supplier margins and forcing tier-two fabricators toward spot-market aluminum sourcing, while OEM procurement teams exploit utilization softness to extract longer payment terms and volume rebates.
Pricing Analysis
Long-term offtake contracts dominate first-fit procurement, with German and Japanese OEMs locking suppliers into five-to-seven year platform agreements that bundle thermal-test validation with unit pricing. Pricing stratifies across premium, standard, and economy tiers based on refrigerant compatibility certification and fin density specifications. Cost compression in aftermarket channels is intensifying because catalog proliferation and price transparency empower independent distributors to force universal-fit discounts. Repair shops exhibit the highest price sensitivity, while electrification-focused OEMs absorb premium engineering costs for microchannel architectures without volume negotiation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning, with Section 301 duties on aluminum brazing stock forcing dual-sourcing strategies across Yangtze River Delta and Mexican maquiladora corridors. Raw material dependencies center on 3003 and 6061 aluminum alloy stock from Chinese smelters, vacuum furnace equipment from German and Japanese suppliers, and HFC refrigerant feedstocks subject to EPA AIM Act phase-down quotas. Single-source vulnerability concentrates in controlled-atmosphere brazing line supply, where equipment lead times extend capacity expansion timelines. Distribution runs through captive OEM logistics networks for first-fit, with independent aftermarket channels consolidating under regional distributor banners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automobile AC condensers market sits in early-cycle expansion as battery-electric vehicle thermal load management creates first-fit demand for refrigerant-minimizing architectures.
For Market Incumbents: Pre-empt margin erosion in legacy tube-and-fin segments by accelerating backward integration into aluminum multiport extrusion supply and securing CO2 transcritical testing certifications ahead of EU F-Gas Regulation tightening. Denso Corporation's integrated thermal-system portfolio demonstrates how captive R&D control defends against emerging microchannel specialists. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian two-wheeler cabin comfort systems and remanufactured condenser channels under circular economy core-return programs. The most penetrable segment lies in compact urban electric vehicle platforms where packaging constraints favor specialized microchannel engineering over legacy supplier relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across CO2 transcritical validation infrastructure as European OEMs mandate 120-bar burst-test capabilities. Acquisition targets should emphasize tier-two heat exchanger fabricators with brazing expertise scarcity and existing OEM thermal-test protocol relationships. The signal to watch is EPA refrigerant transition timeline acceleration under Section 608 enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of 3003 alloy brazing stock insulates margin from LME price volatility and Chinese export duty exposure. |
| CO2 Transcritical Testing Certification | EU F-Gas Regulation compliance unlocks German and Slovak luxury vehicle platform contracts above 120-bar pressure ratings. |
| Remanufacturing Channel Development | Circular economy core-return programs capture aftermarket revenue from California CARB-certified repair shop networks. |
| Microchannel Brazing Process Patenting | Thin-wall multiport extrusion joining expertise creates defensible capacity constraints against tier-two supplier expansion. |
| Total-Cost-of-Ownership Contracting | Long-term fleet service agreements with California ride-hail electrification mandates secure predictable revenue streams. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing OEM platform thermal engineers, Tier 1 supplier procurement directors, aftermarket distributor category managers, and brazing equipment process specialists. Secondary validation drew from EPA Section 608 enforcement data, NHTSA fuel-economy compliance filings, SAE International thermal-test protocol documentation, and vehicle production databases. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Calibration against historical platform adoption curves and refrigerant transition timelines anchored the analytical framework. Segmentation dimensions modeled include vehicle propulsion architecture, refrigerant chemistry compatibility, condenser technology type, and regional OEM production cluster. CAGRs were derived from installed base turnover analysis and electrification penetration assumptions. Industry-specific inputs incorporated MIIT new energy vehicle subsidy trajectories and EU F-Gas Regulation quota reduction schedules.
Sensitivities concentrate around EPA refrigerant phase-down acceleration, aluminum price volatility from energy-intensive smelting cost swings, and SAE International test protocol harmonization gaps between legacy and next-generation systems. Forecasts reflect documented assumptions regarding electrification adoption curves and thermal efficiency regulatory stringency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Automotive Door Module Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Automotive Subframe Market
Automotive Components
Automotive Chromium Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Automotive Glass Film Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Automotive Axle Market
Automotive Components
Automotive Refrigerant Market