
 Middle East and Africa Heat Shrink Tubing for Automotive Market | 2026-2036
Middle East and Africa Heat Shrink Tubing for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Heat Shrink Tubing for Automotive Market Foresight
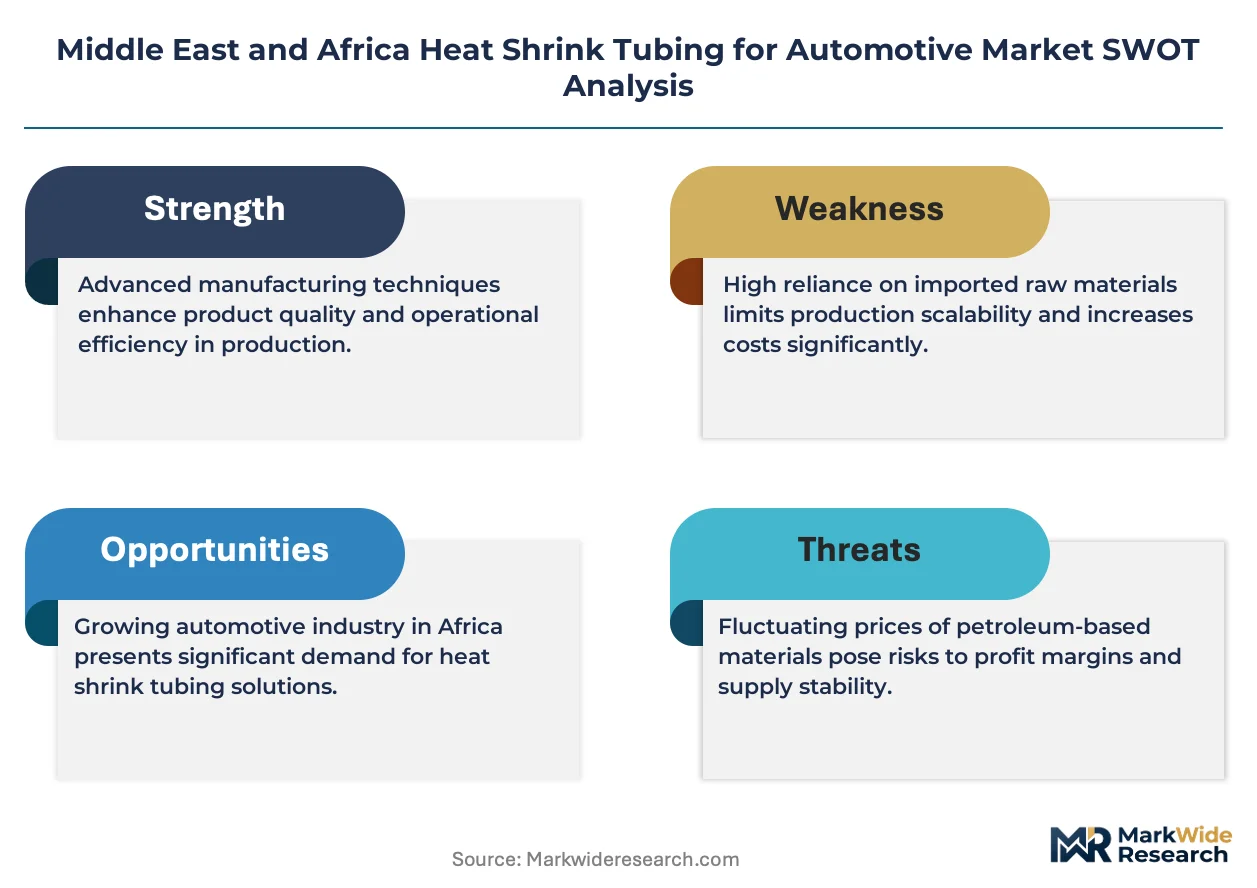
ISO 6722 automotive cable qualification is bifurcating the competitive landscape between certified and uncertified suppliers in the Middle East and Africa. TE Connectivity leverages its global testing infrastructure to sustain certification compliance across regional production hubs. RADPOL S.A anchors its position through specialized polyolefin compounding capabilities tailored to local automotive OEM requirements.
Heat shrink tubing for automotive applications comprises cross-linked polymeric sleeves that contract radially when exposed to controlled thermal energy, typically recovering to 50 percent or less of their supplied diameter at temperatures between 90 degrees Celsius and 175 degrees Celsius depending on base polymer chemistry. These components seal electrical connections against moisture ingress, provide mechanical abrasion resistance, and enable color-coded circuit identification in increasingly dense vehicle architectures. Adhesive-lined tubing commands premium positioning due to its dual-layer construction integrating hot-melt sealants that outperform standard polyolefin in underhood environments where thermal cycling and fluid exposure concentrate failure risk. Multi-layer tubing represents the fastest-expanding material category as OEMs specify fluoropolymer barriers for high-voltage battery routing in electrified platforms entering regional assembly lines.
South Africa's National Regulator for Compulsory Specifications enforces SANS automotive standards that incorporate modified EU REACH substance restrictions, while EMA chemical safety guidelines influence polymer additive approvals for suppliers serving North African export-oriented assembly plants. These overlapping compliance frameworks elevate testing costs for imported formulations while creating structural advantages for regional compounders with established certification portfolios. Stakeholders must monitor how evolving UN ECE regulations on electric vehicle high-voltage cabling propagate into national type-approval requirements across Gulf Cooperation Council automotive markets.
Market Dynamics
Adhesive-lined multi-layer tubing specifications for electric vehicle high-voltage architectures are compressing supplier qualification timelines while elevating technical barriers for compounders serving South Africa's Eastern Cape automotive corridor.
Growth Catalysts
- EU REACH alignment:South Africa's SANS standards adoption creates procurement preference for pre-certified compounders, accelerating material specification upgrades among wiring harness manufacturers.
- Electric vehicle platform localization:Regional assembly of battery-electric models requires fluoropolymer-barrier tubing for 800-volt architectures, pulling advanced material categories into domestic supply chains.
- Gulf Cooperation Council electrification mandates:UN ECE regulation propagation into national type-approval frameworks is generating preemptive certification investments by tubing suppliers serving UAE and Saudi Arabian automotive markets.
Market Restraints
- Polymer additive import dependency:Flame-retardant and stabilizer formulations face extended customs clearance under overlapping EMA chemical safety guidelines and national substance registries.
- Testing infrastructure concentration:ISO 6722 cable qualification capacity clusters in South Africa and Morocco, creating logistics penalties for suppliers serving East African and Levantine markets.
- Technical limitation in high-temperature performance:Standard polyolefin formulations degrade above 135 degrees Celsius, restricting penetration into turbocharger-adjacent routing zones where silicone alternatives dominate.
Strategic Opportunities
- Underpenetrated East African markets:Kenya and Ethiopia's nascent automotive wiring harness sectors present first-mover positioning for adhesive-lined tubing specifications ahead of formal EV mandates.
- Regulatory tailwind from EU Green Deal:Extended producer responsibility frameworks for automotive plastics create demand for recyclable polyolefin formulations that regional compounders can certify faster than imports.
- Technology convergence:Integration of RFID-enabled traceability layers with heat-shrink tubing enables OEMs to meet component-level digital passport requirements emerging in European export markets.
Industry Challenges
- Compounding chemist scarcity:Formulation expertise for cross-linking agent optimization and hot-melt adhesive compatibility remains concentrated among retiring technical staff at established South African suppliers.
- Certification timeline compression:Accelerated vehicle platform launches by OEMs are compressing SANS and ISO 6722 approval cycles from 18 months to under 12 months, straining laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Heat Shrink Tubing for Automotive Market |
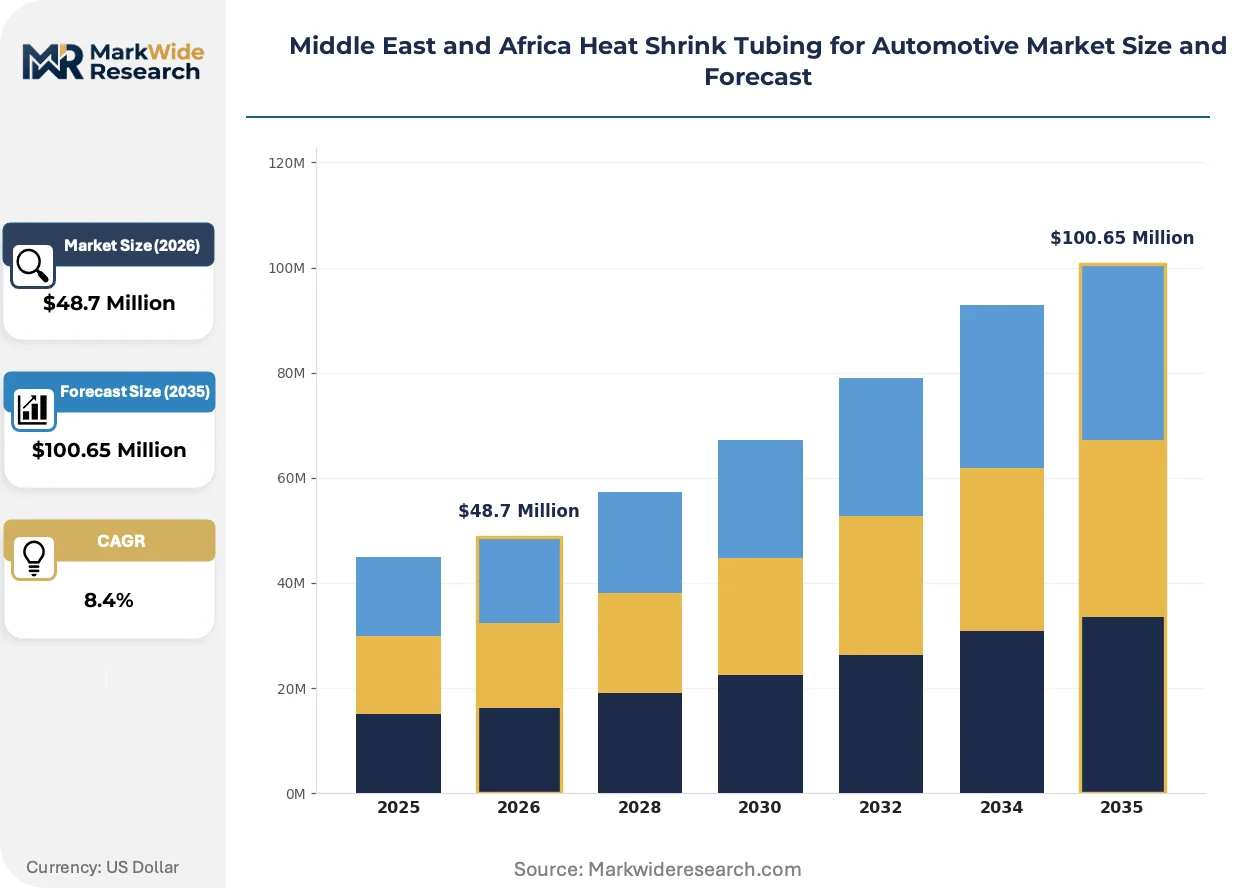
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Tubing, Rigid Tubing, Multi-Layer Tubing, Adhesive-Lined Tubing Material: Polyolefin, PVC, Fluoropolymer, Polyamide Application: Wiring Protection, Insulation, Strengthening, Identification End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Repair Shops |
| Companies Covered | TE Connectivity, Molex, Panduit, ABB, 3M, Sumitomo Electric Industries, RADPOL S.A, Thermosleeve USA, Techflex, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Heat Shrink Tubing for Automotive Market Shifts & Advancements
Material specification bifurcation between legacy internal combustion architectures and electrified platforms is forcing compounders to maintain dual qualification portfolios while regional certification frameworks lag technology evolution.
Fluoropolymer-barrier multi-layer tubing is fragmenting the competitive landscape between pure-play polyolefin suppliers and integrated polymer compounders with fluoropolymer extrusion capabilities. OEMs specifying 800-volt battery routing in regional electric vehicle assembly are adopting these constructions for dielectric strength and thermal endurance. The technology is fragmenting procurement patterns as tier-one harness manufacturers bypass commodity distributors to engage directly with specialized compounders possessing in-house lamination expertise.
EU REACH substance restrictions are propagating into South African SANS standards and EMA chemical safety guidelines across North Africa, creating overlapping compliance obligations for polymer additive formulations. This regulatory convergence elevates testing costs for imported raw materials while advantaging regional compounders with established certification portfolios. Suppliers serving Morocco's export-oriented Renault-Nissan assembly hub are prioritizing pre-registered additive packages to avoid production-line interruptions.
Buyer concentration among Eastern Cape wiring harness manufacturers is compressing supplier negotiation cycles and unbundling technical service from material supply contracts. Tier-one procurement teams are deploying direct material qualification programs that bypass traditional distributor technical support, replacing bundled service with in-house polymer engineering capabilities. This pattern is most visible in South Africa where Toyota, Volkswagen, and Ford component sourcing teams have established captive testing protocols.
Middle East and Africa Heat Shrink Tubing for Automotive Market Segmentation
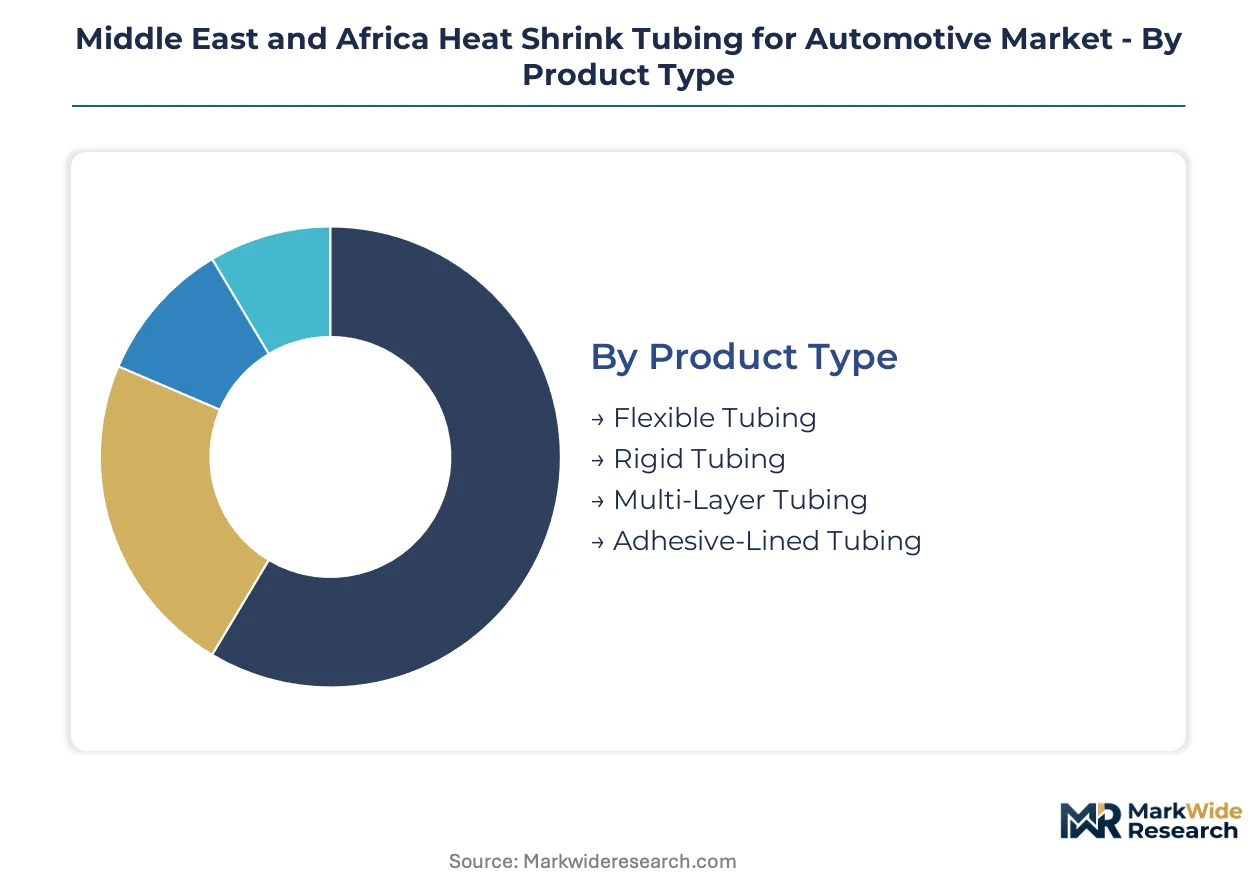
Material specification tiers in Middle East and Africa automotive heat shrink tubing correlate directly with certification complexity under SANS and EMA chemical safety frameworks. Procurement patterns bifurcate between legacy internal combustion platforms and electrified architectures demanding fluoropolymer-barrier constructions.
Product Type:
SANS automotive standards and ISO 6722 cable qualification requirements create divergent technical barriers across construction categories, with adhesive-lined and multi-layer specifications facing extended approval timelines.
- Adhesive-Lined Tubing:Dual-layer construction integrates hot-melt sealants that outperform standard polyolefin in underhood environments. Eastern Cape wiring harness manufacturers are expanding procurement for electric vehicle battery routing where thermal cycling and fluid exposure concentrate failure risk.
- Multi-Layer Tubing:Fluoropolymer barriers laminated onto polyolefin substrates deliver dielectric strength for 800-volt architectures. Regional assembly of battery-electric models in South Africa's automotive corridor is pulling these advanced constructions into domestic supply chains ahead of formal Gulf Cooperation Council EV mandates.
- Flexible Tubing:Cross-linked polyolefin formulations recovering to 50 percent or less of supplied diameter dominate commodity wiring protection in legacy vehicle platforms.
- Rigid Tubing:Higher-durometer constructions serve turbocharger-adjacent routing zones where dimensional stability under thermal stress takes priority over conformability.
Established volume favors flexible tubing; emerging adoption favors multi-layer tubing.
Material:
Cost tier stratification separates commodity thermoplastics from performance polymers commanding formulation premiums and specialized compounding infrastructure.
- Polyolefin:Base cross-linked polymer chemistry dominates volume production across South Africa's Eastern Cape manufacturing cluster. SANS standards adoption of EU REACH substance restrictions is accelerating material specification upgrades among regional compounders with established certification portfolios.
- Fluoropolymer:PTFE and FEP constructions deliver thermal endurance above 175 degrees Celsius for high-voltage battery routing. UN ECE regulation propagation into national type-approval frameworks across Gulf Cooperation Council markets is generating preemptive qualification investments by tubing suppliers serving UAE and Saudi Arabian automotive markets.
- PVC:Lower-cost alternative restricted in export-oriented harness production by evolving chemical safety guidelines across North African assembly hubs.
- Polyamide:Nylon-based formulations penetrate abrasion-critical routing zones where mechanical protection outweighs cost minimization.
Polyolefin captures dominant share; fluoropolymer is climbing the fastest.
Application:
Application priority shifts with vehicle electrification, as high-voltage architectures reweight functional requirements away from simple insulation toward integrated protection systems.
- Wiring Protection:Sealing electrical connections against moisture ingress and mechanical abrasion remains the foundational specification across internal combustion platforms. Toyota and Volkswagen component sourcing teams in South Africa have established captive testing protocols that bypass traditional distributor technical support.
- Insulation:Dielectric strength requirements escalate sharply for 800-volt battery routing, favoring multi-layer constructions with fluoropolymer barriers.
- Strengthening:Mechanical reinforcement applications concentrate in commercial vehicle segments operating across East African markets with degraded road infrastructure.
- Identification:Color-coded circuit specification supports dense vehicle architectures but faces margin compression as OEMs unbundle technical service from material supply contracts.
Wiring protection maintains installed base; insulation requirements are gaining share fastest.
End User:
Customer type concentration in South Africa's Eastern Cape corridor compresses negotiation cycles and elevates direct engagement over distribution channels.
- Tier-1 Suppliers:Wiring harness manufacturers deploy direct material qualification programs that replace bundled distributor services with in-house polymer engineering capabilities. Procurement teams at Eastern Cape facilities serving Ford, Toyota, and Volkswagen have established captive testing protocols.
- OEMs:Original equipment manufacturers specify adhesive-lined multi-layer tubing for electric vehicle platforms, compressing supplier qualification timelines while elevating technical barriers for compounders.
- Aftermarket Providers:Distribution-dependent channel serving repair and maintenance demand across fragmented North African and Levantine markets.
- Repair Shops:Price-sensitive terminal channel with limited specification influence, concentrated in South Africa's established vehicle parc.
Tier-1 suppliers command specification authority; OEMs are driving fastest adoption of advanced material categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UN ECE regulation propagation into national type-approval frameworks is reshaping procurement patterns across Gulf Cooperation Council automotive markets. South Africa's SANS standards alignment with EU REACH chemical restrictions creates certification advantages for regional compounders. Electric vehicle platform localization in Morocco and South Africa is pulling advanced fluoropolymer-barrier tubing into domestic supply chains.
South Africa
Eastern Cape wiring harness manufacturers are expanding adhesive-lined tubing procurement for electric vehicle battery routing applications. The National Regulator for Compulsory Specifications enforces SANS automotive standards incorporating modified EU REACH substance restrictions. Toyota, Volkswagen, and Ford component sourcing teams in the Eastern Cape corridor have established captive testing protocols that bypass traditional distributor channels.
United Arab Emirates
Preemptive certification investments by tubing suppliers are accelerating ahead of formal Gulf Cooperation Council EV mandates. MOHAP chemical safety guidelines influence polymer additive approvals for automotive applications serving export-oriented assembly plants. Dubai-based distribution hubs are consolidating procurement for Levantine and East African markets facing extended customs clearance timelines.
Saudi Arabia
SFDA chemical safety frameworks are elevating testing costs for imported flame-retardant formulations while advantaging regional compounders. Domestic automotive assembly expansion is generating demand for ISO 6722 cable qualification capacity previously concentrated in South Africa and Morocco. Riyadh-based procurement teams are deploying direct material qualification programs for high-voltage architecture specifications.
Morocco
Export-oriented Renault-Nissan assembly hub operations are prioritizing pre-registered additive packages to avoid production-line interruptions. EMA chemical safety guidelines overlap with national substance registries, creating compliance complexity for imported raw materials. Casablanca-Rabat corridor compounders with established certification portfolios are capturing specification authority from commodity distributors.
Kenya
Nascent automotive wiring harness sectors present first-mover positioning opportunities for adhesive-lined tubing specifications ahead of formal EV mandates. Kenya Bureau of Standards automotive component regulations are evolving toward alignment with emerging UN ECE requirements. Nairobi-based tier-one procurement teams are exploring direct engagement with specialized compounders possessing in-house lamination expertise.
Middle East and Africa Heat Shrink Tubing for Automotive Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with global testing infrastructure and specialized regional compounders with established certification portfolios. The competitive structure bifurcates between certified suppliers serving OEM direct qualification programs and uncertified distributors facing procurement exclusion. Three strategic archetypes dominate: integrated polymer compounders with fluoropolymer extrusion capabilities, pure-play polyolefin suppliers serving legacy platforms, and wiring harness manufacturers with captive polymer engineering functions. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress from eighteen months to under twelve.
Within the integrated compounder tier, TE Connectivity and RADPOL S.A exemplify divergent geographic positioning strategies. TE Connectivity leverages global testing infrastructure to sustain certification compliance across regional production hubs, while RADPOL S.A anchors its position through specialized polyolefin compounding capabilities tailored to local automotive OEM requirements. Molex occupies a position representing the scale-driven end of the spectrum, with diversified industrial conglomerate resources enabling parallel qualification portfolios for both legacy internal combustion and electrified platform specifications.
| Leading Market Players |
|---|
| TE Connectivity |
| Molex |
| Panduit |
| ABB |
| 3M |
| Sumitomo Electric Industries |
| RADPOL S.A |
| Thermosleeve USA |
| Techflex |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month ISO 6722 certification lead times concentrate pricing power among South African and Moroccan compounders with established laboratory relationships, while wiring harness manufacturers in the Eastern Cape corridor absorb premium markups for adhesive-lined fluoropolymer-barrier specifications.
Pricing Analysis
Certification tier creates the primary spread between SANS-registered compounders and uncertified distributors. Three-tier pricing structure across OEM-direct, tier-one contract, and aftermarket channels reflects qualification depth rather than volume scale alone. Cost compression in standard polyolefin runs through distributor-heavy segments as Kenyan and Ethiopian buyers prioritize landed cost over technical service. Aftermarket repair shops exhibit highest price sensitivity; OEM platform engineering teams show lowest.
Supply Chain Analysis
Strategic stockpiling of flame-retardant additive packages dominates procurement behavior among Casablanca-Rabat corridor compounders facing EMA chemical safety guideline delays. Raw material sourcing draws from Saudi petrochemical feedstocks, German cross-linking agent specialists, and Chinese stabilizer formulators. Single-source vulnerability concentrates in hot-melt adhesive laminates qualified for 800-volt architectures. Distribution runs through Dubai-based hubs consolidating Levantine and East African demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform localization across South Africa and Morocco is accelerating material specification bifurcation faster than regional certification frameworks can adapt, compressing supplier qualification timelines while elevating technical barriers for compounders without fluoropolymer extrusion capabilities.
For Market Incumbents: Compound certification portfolio depth by adding UN ECE high-voltage cabling pre-qualification ahead of formal Gulf Cooperation Council mandates. Secure backward integration into polyolefin compounding within the Eastern Cape corridor to defend margin position against distributor disintermediation by Toyota and Volkswagen captive testing protocols. For New Entrants and Emerging Players: Technical service gaps in adhesive-lined tubing specification support present first-mover positioning in Kenya's nascent wiring harness sector. Target direct engagement with Nairobi-based tier-one procurement teams exploring fluoropolymer-barrier constructions ahead of formal EV mandates, bypassing commodity distribution channels entirely. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because SANS-EMA-REACH alignment creates structural advantages for regional compounders with pre-registered additive portfolios. Acquisition focus should center on South African laboratories with ISO 6722 cable qualification capacity. Watch UN ECE regulation propagation velocity into UAE and Saudi national type-approval frameworks as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Extrusion Capacity Addition | Enables 800-volt battery routing qualification for regional EV assembly platforms. |
| SANS Pre-Certification Investment | Accelerates procurement preference from Eastern Cape wiring harness manufacturers. |
| Direct Tier-One Engagement Program | Bypasses distributor technical service unbundling by Toyota and Volkswagen sourcing teams. |
| Additive Package Pre-Registration | Avoids production-line interruptions under overlapping EMA chemical safety guidelines. |
| RFID-Enabled Traceability Integration | Supports EU Green Deal component-level digital passport requirements for export markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with polymer compounding technical directors, Tier 1 supplier procurement managers, OEM platform engineers, and aftermarket distribution heads; and secondary validation against SANS regulatory filings, EMA chemical safety guideline updates, UN ECE regulation propagation tracking, and customs trade data for flame-retardant additive imports. Bottom-up volume modeling triangulated against top-down spending estimates from automotive wiring harness production forecasts.
Across the projection horizon, the analytical framework segmented volume and value by product construction, base polymer chemistry, functional application, and end-user procurement tier. CAGRs derived from regression analysis of historical certification timeline compression and electrification-driven content-per-vehicle escalation. Key inputs included electric vehicle platform localization schedules and Gulf Cooperation Council regulatory adoption trajectories.
Forecasts assume regulatory continuity in South African SANS standards, EMA chemical safety frameworks, and UN ECE propagation patterns; material policy shifts would require re-modeling. Revision becomes warranted when fluoropolymer-barrier tubing qualification timelines compress below nine months or when additive import clearance delays exceed current baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Automotive Differential Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Australia Automotive Composites Market