
 Poland Passenger Vehicles Lubricants Market | 2026-2036
Poland Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Passenger Vehicles Lubricants Market Analytics
Multi-source procurement among Polish fleet operators and independent garage networks is restructuring supply relationships across the lubricants value chain. PKN ORLEN anchors its position through captive refining capacity and nationwide service station coverage. BP PLC (Castrol) leverages brand recognition in premium synthetic grades to differentiate in urban retail channels. FUCHS specializes in high-performance formulations tailored to Central European OEM specifications.
Poland passenger vehicles lubricants encompass refined petroleum-based and synthetic fluid formulations engineered to reduce friction, dissipate heat, and prevent wear in internal combustion engines and driveline components, with viscosity grades typically ranging from 0W-20 to 5W-40 under SAE J300 standards. These products serve the essential commercial purpose of extending engine operational life and maintaining fuel efficiency across passenger car parc. Engine oil commands the dominant value share within the application dimension, reflecting Poland's aging vehicle fleet and extended drain interval technologies. Synthetic oil captures accelerating demand as OEM fill specifications shift toward lower-viscosity grades, while mineral oil retains volume leadership in price-sensitive aftermarket segments. Independent garages represent a concentrated margin pool within end user channels due to their bulk purchasing power and brand-agnostic service positioning.
Poland's lubricant quality framework operates under EU REACH chemical registration requirements and the EU Green Deal's decarbonization mandates, which pressure reformulation toward lower-sulfur, higher-biodegradability base stocks. The Polish Committee for Standardization aligns national PN standards with ACEA and API sequences, creating compliance thresholds for imported and domestically blended products alike. BIS-equivalent metrology oversight ensures additive package disclosures meet labeling transparency rules. Stakeholders must monitor evolving OEM factory-fill specifications and the pace of electrification-driven lubricant demand displacement in passenger vehicle powertrains.
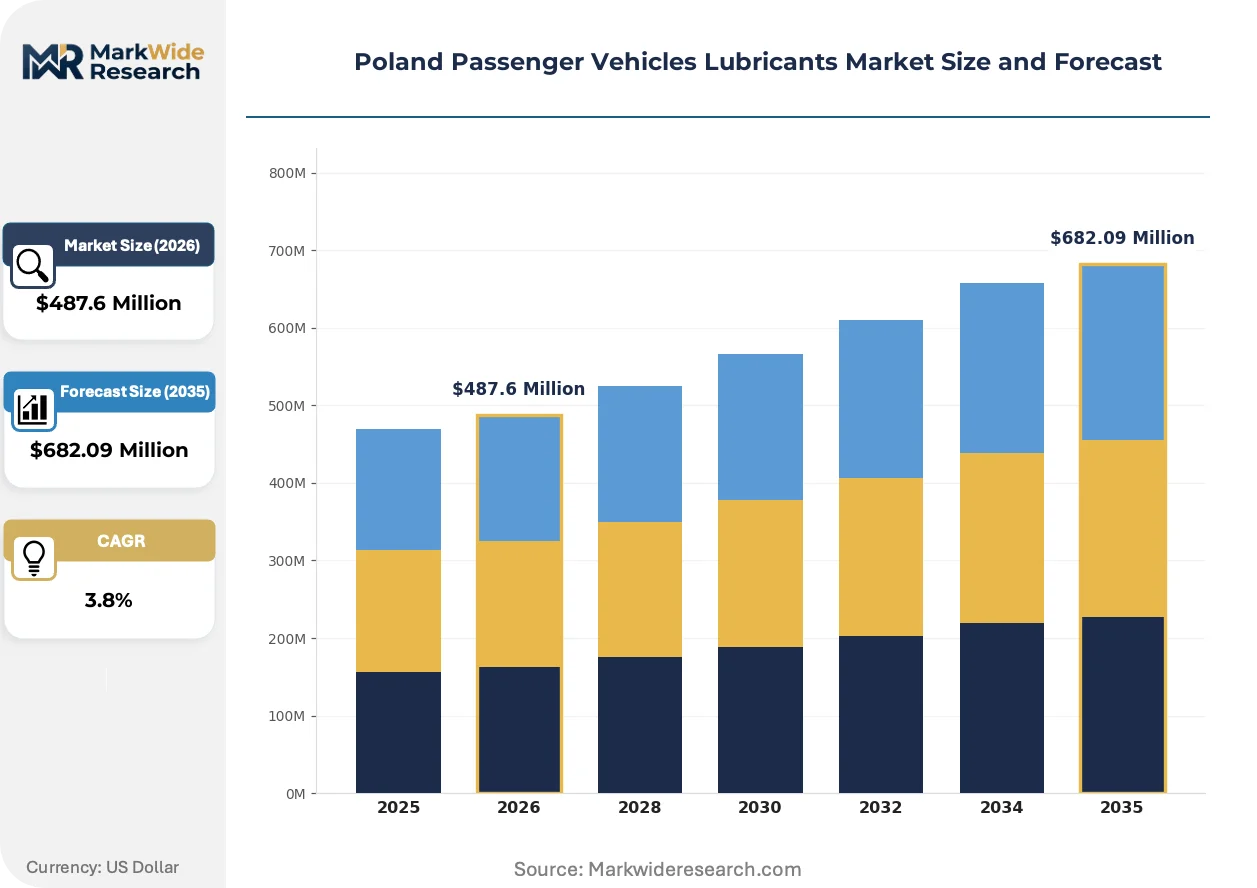
Market Dynamics
Fleet electrification timelines and EU Green Deal mandates are compressing demand for traditional engine oils while simultaneously tightening specifications for remaining internal combustion applications across Poland's automotive service network.
Growth Catalysts
- ACEA C6 Sequences:New low-viscosity specifications from the European Automobile Manufacturers' Association are forcing formulation upgrades that command premium pricing in Warsaw's independent garage sector.
- Silesian Manufacturing Cluster:Dense concentration of automotive OEM assembly plants generates factory-fill contracts and technical service bulletins that cascade into aftermarket specification lock-in.
- Extended Drain Intervals:Synthetic base oil technology enables 30,000-kilometer service cycles, reducing total cost of ownership for logistics operators running Mercedes-Benz and Volkswagen Group fleets.
Market Restraints
- Group II/III Base Oil Import Dependency:Poland lacks domestic API Group III capacity, exposing blenders to Rotterdam refinery pricing volatility and euro-zloty exchange rate pressure.
- Battery Electric Vehicle Parc Growth:Warsaw and Kraków municipal zero-emission zones are accelerating passenger EV adoption, eliminating engine oil demand entirely from powertrain service requirements.
- REACH Registration Burden:ECHA chemical substance dossier requirements impose six-figure euro compliance costs on additive package imports, favoring incumbent suppliers with existing registration portfolios.
Strategic Opportunities
- Subcarpathian Voivodeship:Underdeveloped service infrastructure along the A4 motorway corridor presents whitespace for automated lube bay networks targeting cross-border freight traffic.
- E-Fluid Formulations:Thermal management fluids for battery electric vehicle power electronics represent a product line extension with transferable blending equipment from engine oil operations.
- EU F-Gas Regulation Phase-Down:Refrigerant lubricant compatibility requirements for R1234yf air conditioning systems create specification complexity that technical specialists can monetize through certification programs.
Industry Challenges
- Additive Chemist Talent Pipeline:Specialized formulation expertise for ACEA sequences and OEM factory-fill approvals concentrates at PKN ORLEN and FUCHS, constraining independent blender R&D capacity.
- Used Oil Collection Infrastructure:Reverse logistics for waste lubricant regeneration requires depot network investment that competes for capital against core blending capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Passenger Vehicles Lubricants Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $682.09 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lubricant Type: Synthetic Oil, Mineral Oil, Semi-Synthetic Oil, Bio-Based Oil Application: Engine Oil, Transmission Fluid, Brake Fluid, Cooling System End User: Original Equipment Manufacturers, Independent Garages, Retail Consumers, Fleet Operators Distribution Channel: Online Sales, Retail Stores, Bulk Distributors, Service Stations |
| Companies Covered | BP PLC (Castrol), FUCHS, LOTOS OIL, PKN ORLEN (ORLEN oil), TotalEnergies, ExxonMobil Corporation, LIQUI MOLY, Royal Dutch Shell Plc, Motul, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Passenger Vehicles Lubricants Market Evolving Landscape
Formulation chemistry and distribution logistics are diverging sharply as electrification compresses addressable demand for conventional products while raising performance thresholds for remaining combustion applications.
Polyalphaolefin (PAO) and gas-to-liquid base stocks are rewriting viscosity-temperature performance envelopes in 0W-20 and 0W-16 grades. Premium synthetic formulations now dominate factory-fill specifications from Volkswagen Group and Stellantis manufacturing plants serving Polish consumers. The technology is compressing demand for mineral-based 5W-40 products in urban retail channels while enabling extended drain intervals that reduce service bay throughput for independent garages.
EU F-Gas Regulation mandates are tightening refrigerant lubricant compatibility requirements for vehicle air conditioning systems. The policy is forcing reformulation of polyalkylene glycol and polyol ester chemistries to match R1234yf thermal stability needs. Aftermarket service providers in Warsaw and Łódź metropolitan areas face equipment retrofit costs and technician certification requirements to handle hybrid and electric vehicle thermal management systems.
Fleet procurement offices are consolidating lubricant purchasing through national framework agreements with direct-to-depot delivery. Independent garage networks are losing volume to authorized service chains that capture captive maintenance contracts from leasing companies. The behavior shift is most visible along the A2 and A4 motorway corridors where logistics operators centralize maintenance scheduling at hub facilities rather than distributed service points.
Poland Passenger Vehicles Lubricants Market Segmentation
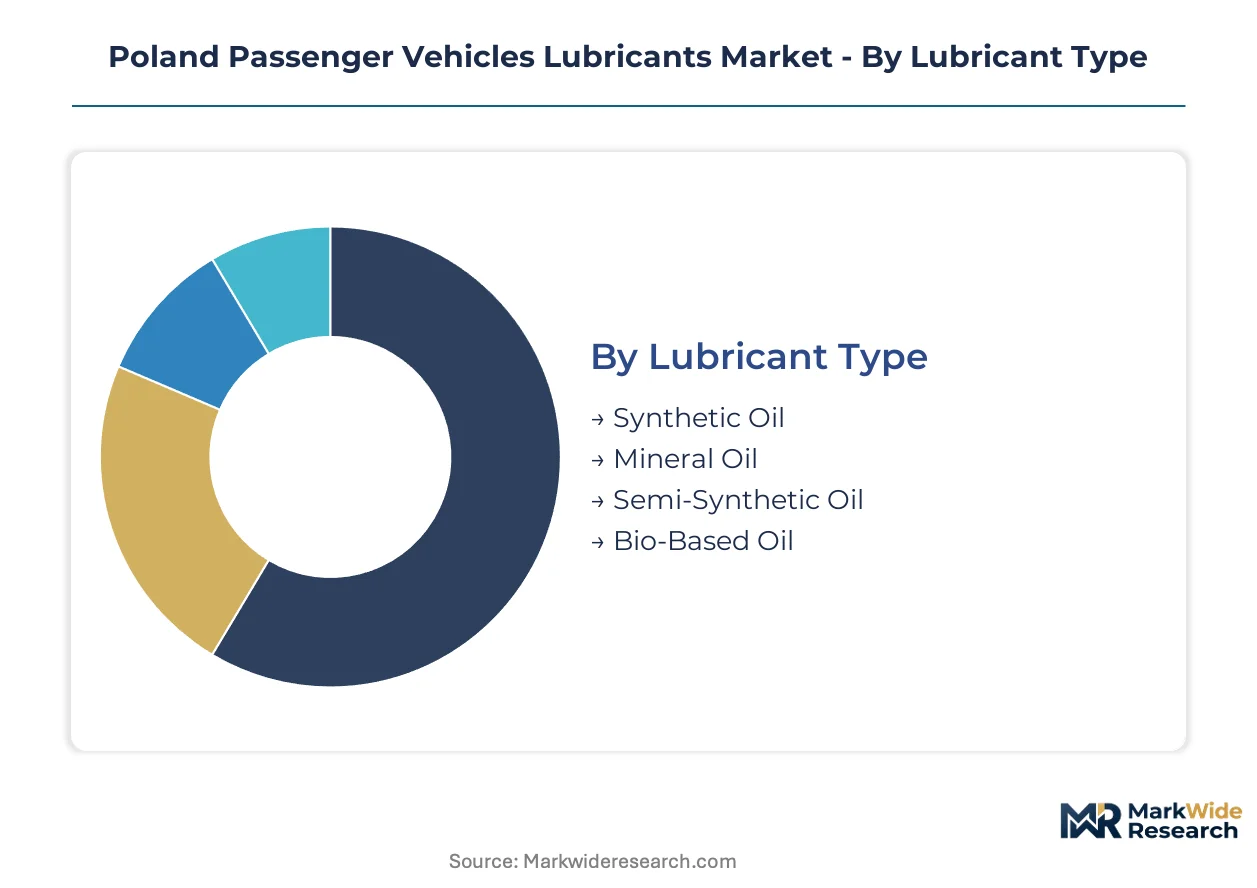
Poland's passenger vehicle lubricants market fragments across formulation chemistry, powertrain application, and procurement channel. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Lubricant Type:
Price-performance tradeoffs dominate fleet procurement decisions as ACEA sequences tighten and electrification compresses demand windows.
- Synthetic Oil:Formulated from Group III and PAO base stocks delivering thermal stability across extended drain intervals. Demand concentrates among Warsaw-based fleet operators running Volkswagen Group and Mercedes-Benz vehicles under factory-fill specifications. Premium positioning captures value as OEM warranties mandate low-viscosity grades.
- Mineral Oil:Refined from solvent-extracted Group I base stocks with higher sulfur content and narrower viscosity index. Volume leadership persists in Silesian independent garages serving aging vehicle parc where price sensitivity overrides performance specifications.
- Semi-Synthetic Oil:Blended formulations combining mineral and synthetic base stocks targeting mid-tier service intervals.
- Bio-Based Oil:Ester and vegetable-derived formulations responding to EU Green Deal biodegradability mandates.
Synthetic oil leads on scale; bio-based oil leads on momentum.
Application:
Powertrain electrification is redistributing fluid demand across thermal management and friction-reduction functions.
- Engine Oil:Internal combustion lubrication commanding dominant value share through crankcase, camshaft, and piston ring protection. Silesian manufacturing cluster generates factory-fill contracts that cascade specification lock-in through vehicle life cycles.
- Transmission Fluid:ATF and CVT formulations for gear set and torque converter lubrication. Demand climbs fastest among logistics operators extending service intervals for automated manual transmissions in long-haul corridors.
- Brake Fluid:Glycol-ether and silicone-based hydraulic fluids meeting DOT 4 and DOT 5.1 specifications.
- Cooling System:Antifreeze and thermal transfer fluids for radiator and HVAC circuits.
Engine oil leads on scale; transmission fluid leads on momentum.
End User:
Procurement consolidation is restructuring margin capture between captive maintenance networks and open aftermarket channels.
- Independent Garages:Brand-agnostic service providers aggregating bulk purchasing power across Warsaw and Łódź metropolitan areas. Margin concentration reflects technical certification requirements that filter supplier access.
- Fleet Operators:National logistics companies centralizing lubricant procurement through framework agreements with direct-to-depot delivery. Volume scale enables specification enforcement across Mercedes-Benz and MAN truck parc.
- Original Equipment Manufacturers:Factory-fill contracts at Silesian assembly plants serving Stellantis and Volkswagen Group production.
- Retail Consumers:Do-it-yourself purchasers through service station and automotive specialty retail channels.
Independent garages lead on scale; fleet operators lead on momentum.
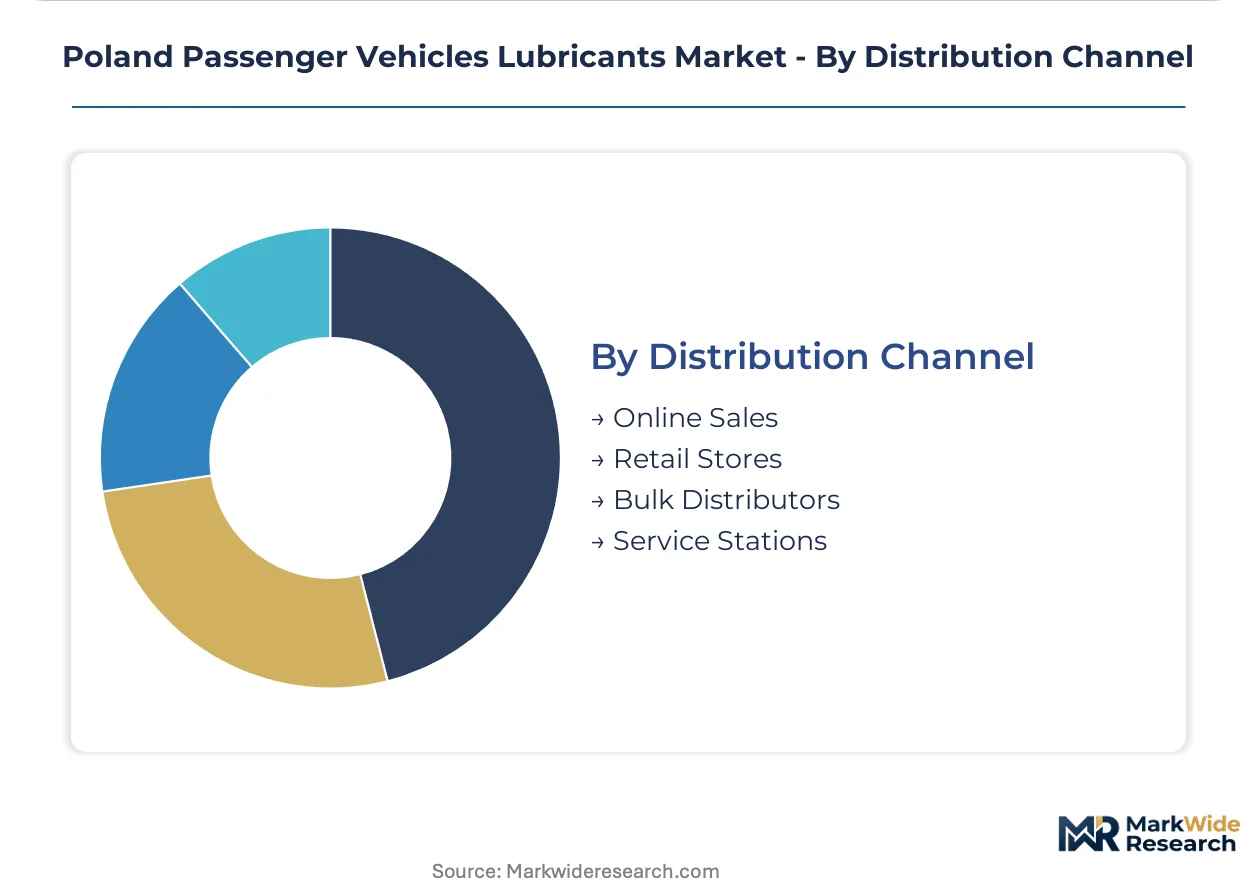
Distribution Channel:
Logistics efficiency and technical service bundling determine channel economics as procurement digitizes.
- Bulk Distributors:Regional blending and storage facilities supplying independent garage networks with tankwagon delivery. Geographic coverage along A2 and A4 motorway corridors matches fleet hub concentration.
- Service Stations:PKN ORLEN's captive retail network combining fuel sales with packaged lubricant merchandising. Nationwide coverage anchors brand visibility in premium synthetic grades.
- Online Sales:E-commerce platforms targeting price-transparent retail consumers with home delivery logistics.
- Retail Stores:Automotive specialty and hypermarket channels serving emergency purchase and seasonal demand.
Bulk distributors lead on scale; online sales lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage across Central Europe is redirecting lubricant blending capacity toward jurisdictions with streamlined chemical registration pathways. Poland's alignment with EU REACH through the Polish Committee for Standardization creates compliance cost advantages over non-EU neighbors. Production migrates to corridors where base oil import logistics and factory-fill proximity minimize working capital requirements.
Masovian Voivodeship
Warsaw-based fleet operators drive synthetic oil demand through centralized procurement offices serving Mercedes-Benz and Volkswagen Group parc. EU Green Deal decarbonization mandates pressure reformulation toward lower-sulfur base stocks in the metropolitan service network. The A2 motorway corridor concentrates logistics hub maintenance facilities where extended drain interval technologies reduce total cost of ownership.
Silesian Voivodeship
Automotive OEM assembly plants generate factory-fill contracts that cascade specification lock-in through vehicle life cycles. ACEA C6 sequences from the European Automobile Manufacturers' Association force formulation upgrades commanding premium pricing in the manufacturing cluster. Gliwice and Bielsko-Biała anchor technical service bulletins that shape aftermarket lubricant requirements across Central Europe.
Lesser Poland Voivodeship
Kraków municipal zero-emission zones accelerate passenger EV adoption, eliminating engine oil demand from powertrain service requirements. Battery electric vehicle parc growth compresses addressable market for traditional crankcase formulations in the urban core. The A4 motorway corridor toward Rzeszów presents whitespace for automated lube bay networks targeting cross-border freight traffic.
West Pomeranian Voivodeship
Szczecin port infrastructure handles Group II/III base oil imports from Rotterdam refineries, exposing blenders to euro-zloty exchange rate volatility. Maritime logistics operators centralize lubricant purchasing through framework agreements with direct-to-depot delivery. The region's underdeveloped service infrastructure relative to Warsaw creates pricing pressure on mineral oil volumes in price-sensitive aftermarket segments.
Subcarpathian Voivodeship
Underdeveloped service infrastructure along the A4 motorway corridor presents whitespace for automated lube bay networks targeting cross-border freight traffic. EU F-Gas Regulation phase-down creates refrigerant lubricant compatibility requirements for R1234yf air conditioning systems. Rzeszów's emerging logistics hub status attracts fleet operators extending service intervals for automated manual transmissions in long-haul corridors.
Poland Passenger Vehicles Lubricants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue e-fluid and thermal management specializations. The market structure reflects captive refining capacity alongside imported premium brands. Three archetypes dominate: integrated oil majors with downstream retail networks, independent blenders serving garage channels, and specialty formulators targeting OEM factory-fill approvals. Competitive moves concentrate on strategic partnerships for additive package access and portfolio diversification into electrification-adjacent fluids.
Among integrated oil majors, PKN ORLEN anchors the domestic tier through captive refining capacity and nationwide service station coverage. BP PLC (Castrol) exemplifies premium-brand positioning in urban retail channels. FUCHS occupies the technical specialist archetype, with formulation expertise concentrated at its Polish operations serving Central European OEM specifications.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| FUCHS |
| LOTOS OIL |
| PKN ORLEN (ORLEN oil) |
| TotalEnergies |
| ExxonMobil Corporation |
| LIQUI MOLY |
| Royal Dutch Shell Plc |
| Motul |
| Others |
Value Network & Pricing Analysis
Fleet procurement offices in Warsaw and the Silesian logistics corridor concentrate purchasing power through national framework agreements, anchoring a contract-based pricing model where volume scale overrides spot-market volatility. This buyer concentration forces suppliers to absorb euro-zloty exchange pressure rather than pass through Rotterdam base oil cost movements.
Pricing Analysis
Distributor margin compression runs through the independent garage channel as bulk purchasing power shifts toward fleet operators and authorized service chains. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral grades differentiates by ACEA certification level and OEM factory-fill alignment. Pricing pressure stems from Group II/III base oil import dependency and REACH registration cost absorption. Price sensitivity concentrates in Silesian independent garages serving aging vehicle parc, while Warsaw fleet operators prioritize total cost of ownership over unit price.
Supply Chain Analysis
Dual-sourcing requirements from major fleet operators mandate qualification of at least two additive package suppliers and two base oil sources, constraining single-source dependency despite limited domestic Group III capacity. Supply draws from Netherlands refineries for Group II/III base stocks, Germany for additive packages, and regional blending facilities in Poland. Single-source vulnerability concentrates in API Group III base oil imports through Rotterdam. Distribution runs through bulk distributors with tankwagon delivery to garage networks, supplemented by PKN ORLEN's captive service station retail coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's passenger vehicle lubricants market functions as a regulatory compounder where EU F-Gas Regulation phase-down and ACEA C6 sequence mandates continuously upgrade formulation requirements and compress demand windows for legacy products.
For Market Incumbents: Acquire captive additive formulation capability to reduce ECHA registration cost exposure and secure OEM factory-fill approval pipelines. PKN ORLEN should expand Group III base oil sourcing agreements with Rotterdam refineries to hedge euro-zloty volatility. FUCHS must deepen technical service relationships with Volkswagen Group and Stellantis assembly plants in Silesia to lock specification cascade into aftermarket channels.
For New Entrants and Emerging Players: Launch via automated lube bay networks targeting underdeveloped service infrastructure along the A4 motorway corridor in Subcarpathian Voivodeship. White-space concentrates in e-fluid formulations for battery electric vehicle thermal management systems where incumbent engine oil expertise does not directly transfer. Go-to-market should emphasize technician certification programs for R1234yf refrigerant lubricant compatibility under EU F-Gas mandates.
For Investors and Strategic Acquirers: Specialty chemical companies with automotive thermal management portfolios are the most active acquirer in this space, seeking formulation expertise transferable to e-fluids and power electronics cooling. Long-term viability hinges on electrification-adjacent product line extension rather than combustion engine oil volume defense. Acquisition target archetype: independent blenders with existing REACH registration portfolios and Central European OEM relationships. Signal to watch: pace of battery electric vehicle parc growth in Warsaw and Kraków municipal zero-emission zones.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Package Sourcing | Reduces ECHA REACH registration burden and secures formulation autonomy for ACEA sequence compliance. |
| E-Fluid Product Line Extension | Captures thermal management demand from battery electric vehicle power electronics in Warsaw fleet segments. |
| Automated Lube Bay Network Expansion | Addresses whitespace in Subcarpathian Voivodeship along A4 corridor cross-border freight routes. |
| Technician Certification Program Development | Monetizes EU F-Gas Regulation complexity through R1234yf refrigerant lubricant training revenue. |
| Long-Term Supply Agreement with Fleet Operators | Locks volume commitment from Mercedes-Benz and Volkswagen Group logistics contractors in Masovian hub. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant blenders, fleet procurement managers, independent garage operators, and OEM technical service personnel with secondary validation against ACEA oil sequence documentation, EU REACH registration databases, Polish Committee for Standardization PN standards, and vehicle production data from Silesian manufacturing cluster disclosures. Bottom-up volume modeling from end-user channel segmentation triangulated against top-down market value estimates.
Segment-weighting applied lubricant type, powertrain application, and procurement channel dimensions across the projection horizon, with synthetic versus mineral formulation splits calibrated to OEM factory-fill specification trends. CAGRs derived from elasticity modeling of vehicle parc age distribution, extended drain interval penetration, and electrification-driven demand displacement. Industry-specific inputs included ACEA C6 sequence adoption curves and EU F-Gas Regulation phase-down timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated battery electric vehicle adoption or Rotterdam refinery supply disruption scenarios. Deviation in EU Green Deal implementation pace or zloty depreciation against the euro would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Transfer Case Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Tow Bar Market
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Hydraulic Lash Adjuster Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Norway Automotive Engine Oils Market