
 Steel Cords for Radial Tyres Market | 2026-2036
Steel Cords for Radial Tyres Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Cords for Radial Tyres Market Insights
Direct supply contracts between steel cord producers and integrated tyre manufacturers is reconfiguring procurement patterns across the radial tyre value chain. Bekaert leverages its Belgian heritage and global wire technology leadership to sustain premium positioning in high-tensile reinforcement grades. Hyosung Advanced Materials anchors its competitive stance through backward integration into petrochemical-based raw materials and proprietary drawing technology. Jiangsu Xingda Steel Tyre Cord dominates cost-efficient volume production from its Jiangsu manufacturing base, serving both domestic Chinese tyre makers and export accounts.
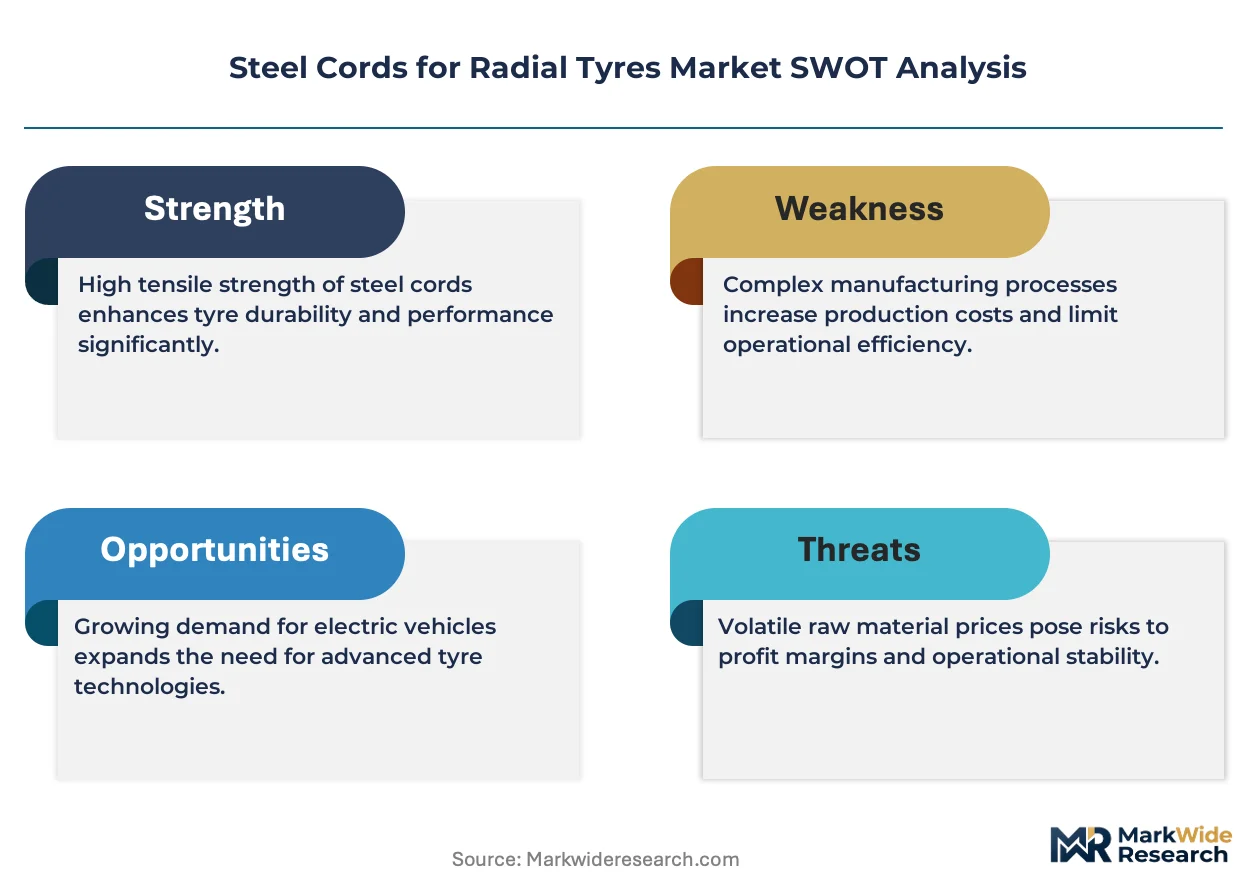
Steel cords for radial tyres are high-carbon steel filaments, typically 0.15–0.38 mm in diameter, drawn to extreme tensile strengths exceeding 2,800 MPa and brass- or bronze-plated to ensure rubber adhesion in belt and carcass plies. Their primary purpose is to replace fabric reinforcements in radial-ply tyres, converting circumferential and lateral loads into stable tread contact under dynamic stress. High carbon steel commands the largest volume share due to its established fatigue resistance and compatibility with conventional tyre building equipment, while copper coated variants are gaining traction where enhanced rubber-to-steel bonding is specified for high-performance or retreaded applications. Truck and bus tyres represent the deepest margin pool because fleet operators prioritize durability and casing retreadability over first-cost sensitivity.
China's SAMR enforces GB standards governing steel cord dimensional tolerances and adhesion performance, while the EU's REACH framework restricts certain chemical treatments in plating baths used during cord manufacturing. The US NHTSA maintains tyre safety ratings that indirectly dictate minimum belt reinforcement specifications for tyres sold in North America. Stakeholders must monitor how dual carbon goals in China's MEE regulations and the EU Green Deal's embodied-carbon tracking requirements will reshape material sourcing and energy-intensive wire drawing processes.
Market Dynamics
Direct supply contracts between steel cord producers and integrated tyre manufacturers are reconfiguring procurement patterns across the radial tyre value chain, compressing traditional distributor margins and locking in volume commitments through multi-year frameworks.
Growth Catalysts
- Heavy-duty fleet conversion:Truck and bus operators are mandating radial construction for fuel efficiency gains and casing retreadability, deepening specification requirements for high-tensile reinforcement grades.
- REACH compliance tightening:The EU's chemical framework is restricting certain plating bath treatments, pushing manufacturers toward certified low-carbon wire drawing processes that qualify for premium tyre supply contracts.
- India's domestic production scaling:OEM fitment demand and export market growth are concentrating steel cord procurement in Gujarat and Tamil Nadu manufacturing clusters.
Market Restraints
- Scrap steel price volatility:High-carbon wire rod feedstock costs fluctuate with electric arc furnace output and import tariff regimes, squeezing margin predictability for drawn filament producers.
- Supplier concentration in East Asia:Over half of brass-plated cord capacity sits within a 300-kilometer radius in Jiangsu Province, creating geographic risk exposure for global tyre makers.
- Adhesion performance ceiling:Conventional bronze plating chemistry hits bonding limits above 3,000 MPa tensile strength, constraining next-generation ultra-high-performance tyre architectures.
Strategic Opportunities
- Retread market penetration:Premium casing durability specifications in North American long-haul fleets are opening demand for copper-coated cords with enhanced rubber-to-steel bonding.
- Dual carbon alignment:China's MEE regulations and the EU Green Deal's embodied-carbon tracking are rewarding wire producers with renewable-powered drawing operations and certified scrap sourcing.
- Digital thread integration:Blockchain-tracked material certificates from melt shop to tyre plant are emerging as a procurement differentiator for OEM compliance documentation.
Industry Challenges
- Metallurgical talent scarcity:Wire drawing process engineers with expertise in sub-0.20 mm filament production are concentrated at a handful of legacy European and Japanese facilities.
- GB standard compliance timelines:China's SAMR updates to dimensional tolerance and adhesion testing protocols require 18-24 month recertification cycles for export-qualified production lines.
- Legacy equipment retrofit costs:Conventional tyre building machines require mechanical modifications to handle ultra-high-tensile cord stiffness without ply distortion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Cords for Radial Tyres Market |
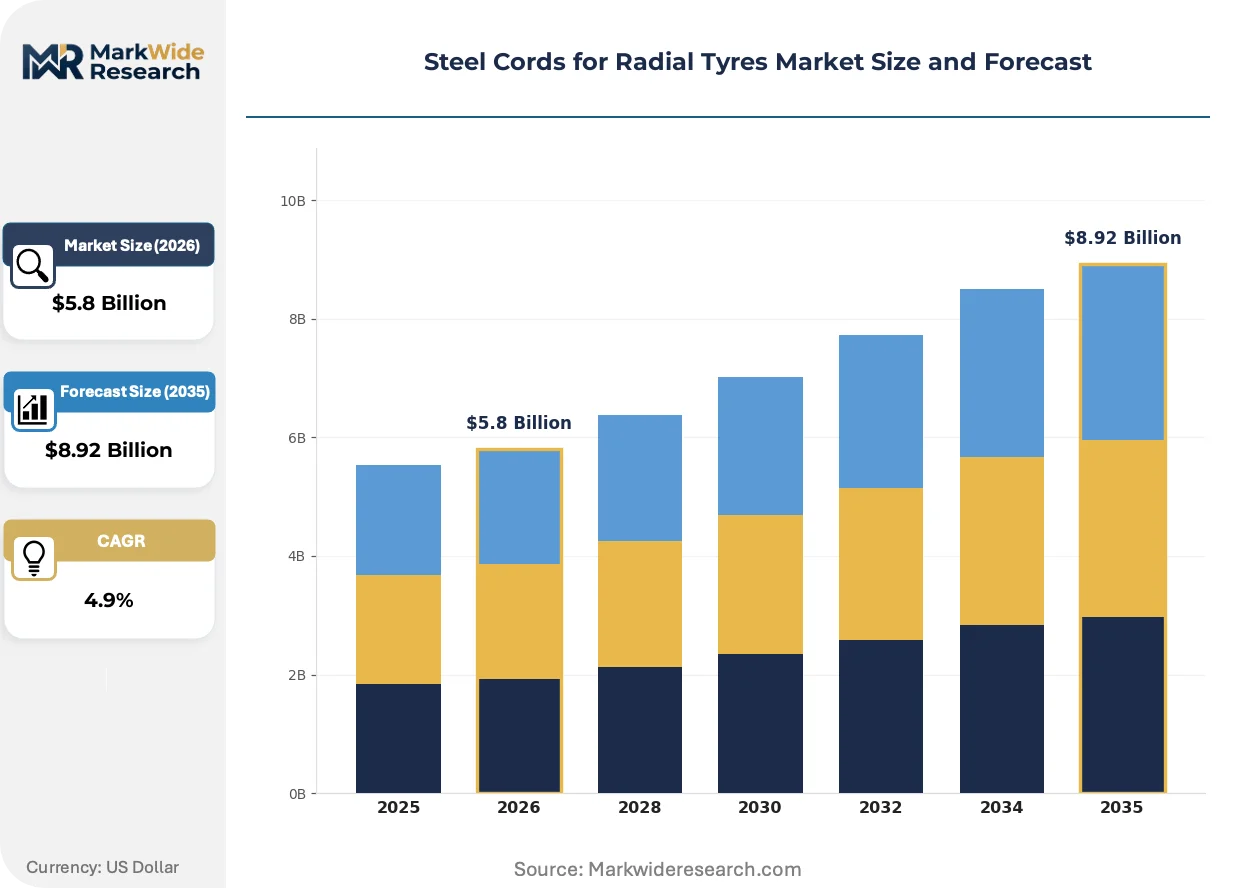
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.92 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Carbon Steel, Stainless Steel, Galvanized Steel, Copper Coated, Bronze Coated Application: Passenger Vehicle Tyres, Truck & Bus Tyres, Two-Wheeler Tyres, Agricultural Tyres, Mining Tyres End User: Tire Manufacturers, Tier-1 Suppliers, Aftermarket Vendors, Retreaders, OEMs Technology: Continuous Drawing, Cold Twisting, Heat Treatment, Electroplating, Coating |
| Companies Covered | ArcelorMittal, Bekaert, Hyosung Advanced Materials, Jiangsu Xingda Steel Tyre Cord, Sumitomo Electric Industries, Bridgestone Corporation, Tokusen Kogyo, Henan Hengxing Science & Technology, Shougang Century Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Cords for Radial Tyres Market Trends and Innovations
Material science advances and regulatory carbon accounting are converging to redefine competitive positioning in steel cord supply, with process innovation now outpacing product specification changes in strategic importance.
Ultra-high-strength filaments drawn above 3,500 MPa are collapsing the ply count requirements for heavy truck tyres, enabling lighter belt packages without sacrificing load capacity. Major fleet operators in Germany and the US are specifying these grades for new equipment purchases. The technology is compressing traditional multi-ply constructions into simplified two-belt designs that reduce raw material inputs per tyre.
REACH Annex XVII restrictions on hexavalent chromium in plating baths are forcing wire producers to migrate to trivalent or chromium-free adhesion systems. The industrial consequence is elevated capital expenditure for bath chemistry conversion and accelerated qualification testing with tyre makers. European premium tyre manufacturers are responding fastest, locking in supply contracts with certified conversion-complete wire plants.
Long-term offtake agreements are displacing spot market purchases as the dominant procurement mode among top-tier tyre makers. Direct mill-to-plant relationships are replacing layered distributor networks in Southeast Asia and Eastern Europe. The shift is most visible in India, where integrated tyre manufacturers are signing five-year volume commitments with steel cord producers for new greenfield capacity.
Steel Cords for Radial Tyres Market Segmentation
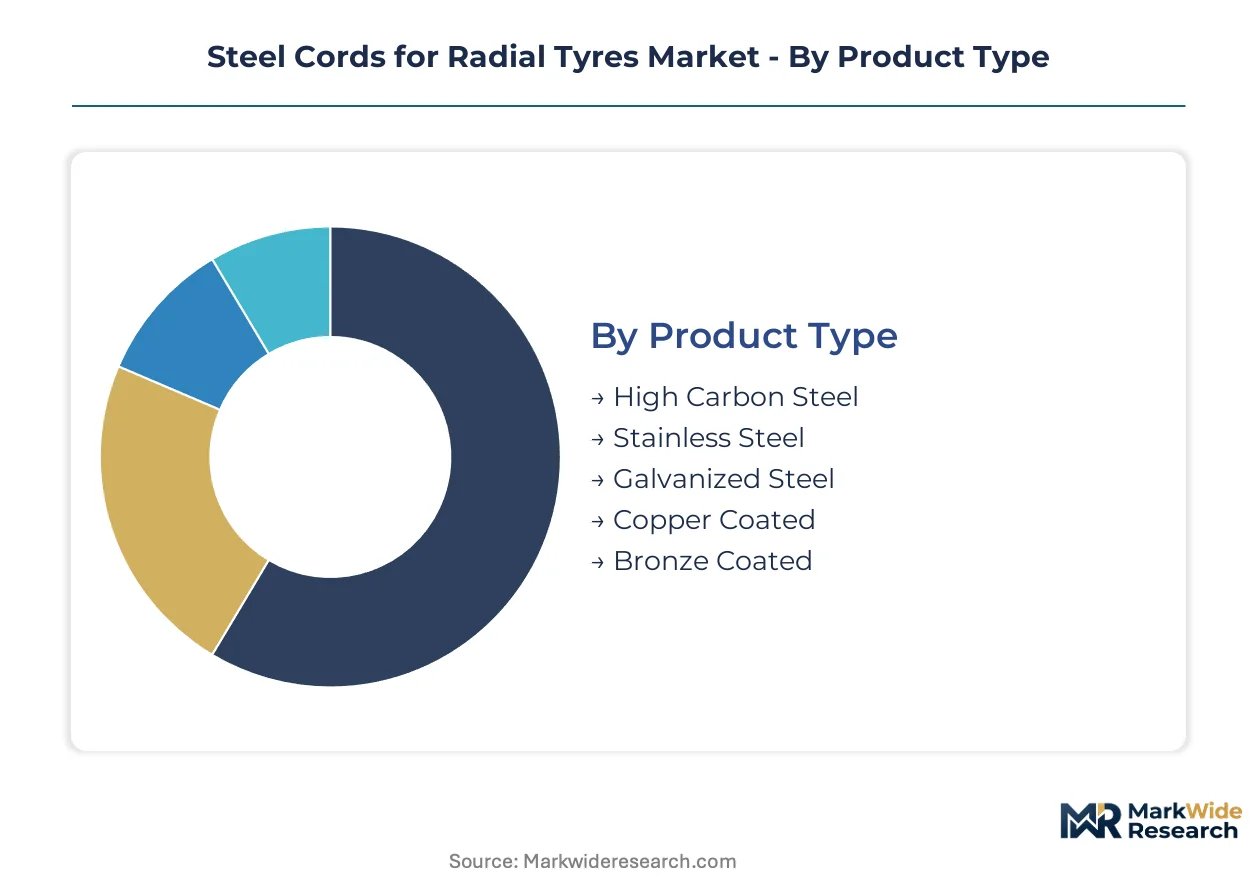
Segmentation in steel cords for radial tyres reveals how material specifications, end-use durability requirements, and manufacturing processes intersect to define procurement priorities. Each dimension carries distinct margin profiles and technical barriers that shape competitive positioning across the value chain.
Product Type:
Mature high-carbon grades anchor volume production while emerging coating technologies unlock premium pricing for specialized adhesion performance.
- High Carbon Steel:Filaments drawn to 2,800+ MPa tensile strength dominate belt and carcass ply applications through proven fatigue resistance. Truck and bus fleets in Germany and the US specify these grades for casing retreadability under sustained highway loads.
- Copper Coated:Enhanced rubber-to-steel bonding chemistry addresses ultra-high-performance architectures where conventional plating hits adhesion ceilings. North American long-haul operators are specifying copper-coated variants for premium casing durability in multi-life retread programs.
- Stainless Steel:Corrosion-resistant filaments serve mining and agricultural tyres exposed to moisture and chemical abrasion.
- Galvanized Steel:Zinc barrier protection extends service life in severe-duty off-highway applications.
- Bronze Coated:Traditional brass-bronze plating remains standard for passenger vehicle tyres with moderate stress requirements.
High Carbon Steel handles the majority of throughput; Copper Coated is expanding most quickly on share.
Application:
Cost tier stratification separates heavy-duty commercial specifications from price-sensitive consumer segments.
- Truck & Bus Tyres:Deep-belt constructions demand high-tensile reinforcement grades that withstand repeated retreading cycles. Fleet conversion to radial construction across India and Brazil is deepening specification requirements for durability-certified cord supplies.
- Passenger Vehicle Tyres:High-volume OEM fitment prioritizes dimensional consistency and adhesion reliability over extreme tensile performance. Japanese and South Korean tyre makers are locking in direct mill contracts for standardized high-carbon grades.
- Two-Wheeler Tyres:Lightweight ply constructions use finer-diameter filaments with reduced belt package weight.
- Agricultural Tyres:Flotation and traction designs require flexible carcass reinforcements resisting field debris penetration.
- Mining Tyres:Ultra-heavy load ratings specify specialized cord architectures for severe surface mining conditions.
Truck & Bus Tyres command the deepest margin pool; Passenger Vehicle Tyres move the largest absolute tonnage.
End User:
Customer type determines contract structure, with integrated manufacturers capturing volume through direct supply frameworks.
- Tire Manufacturers:Radial tyre plants in Gujarat and Tamil Nadu clusters are signing five-year offtake agreements for greenfield capacity ramp-ups serving both domestic OEM fitment and export markets.
- Retreaders:Premium casing inspection and buffing operations specify certified cord visibility for second-life tyre performance guarantees.
- Tier-1 Suppliers:Modular belt package assemblers intermediate between wire producers and final tyre builders.
- Aftermarket Vendors:Replacement tyre distributors source standard grades through residual spot market availability.
- OEMs:Vehicle manufacturers specify minimum belt reinforcement ratings for factory-fitment tyre supply contracts.
Tire Manufacturers consolidate procurement volume; Retreaders are gaining share fastest as circular economy regulations tighten.
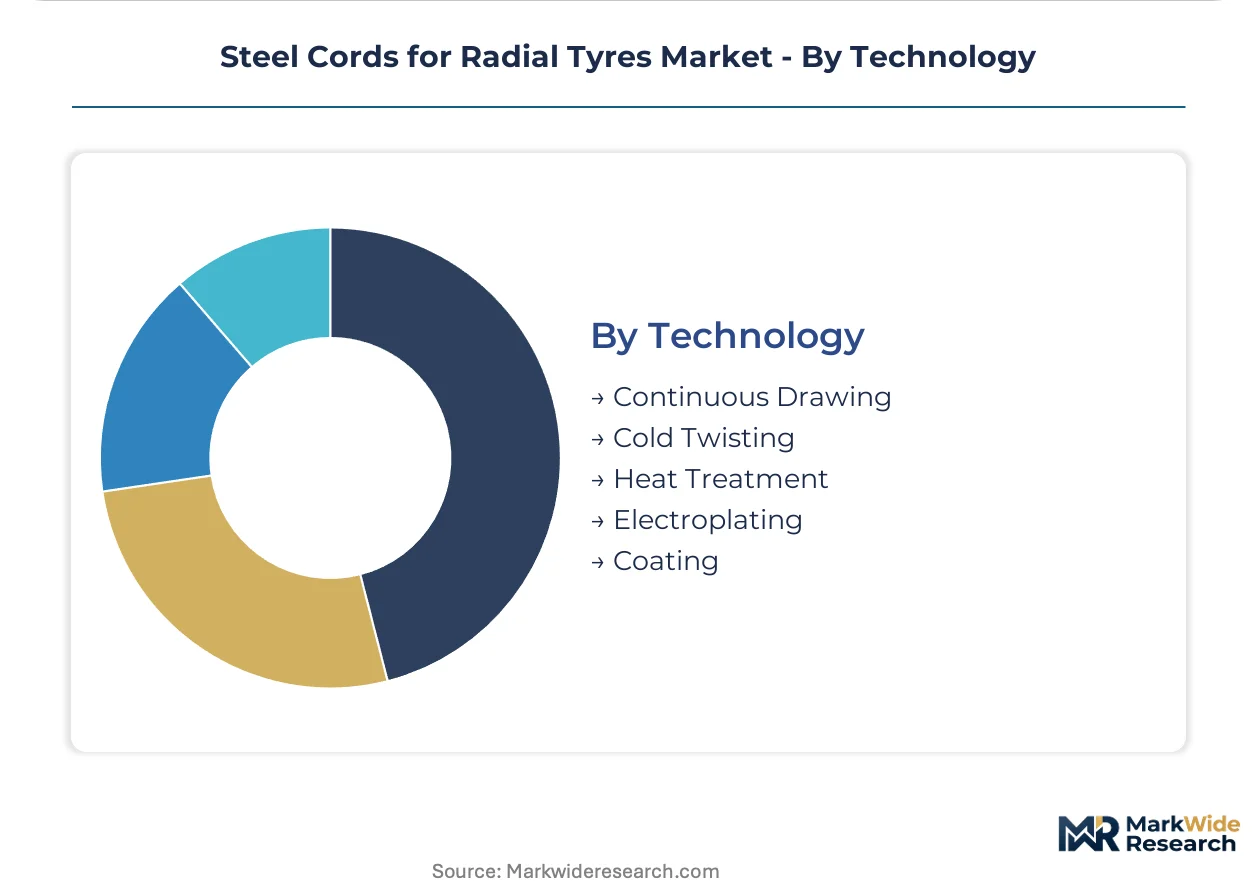
Technology:
Process innovation now outpaces product specification changes, with carbon-accounting compliance reshaping capital allocation.
- Continuous Drawing:Sub-0.20 mm filament production requires precision die sequences and metallurgical expertise concentrated at legacy European and Japanese facilities.
- Electroplating:REACH Annex XVII hexavalent chromium restrictions are forcing bath chemistry conversions to trivalent or chromium-free adhesion systems.
- Heat Treatment:Tensile strength optimization through controlled austenitizing and tempering cycles.
- Cold Twisting:Multi-filament strand construction for ply flexibility and load distribution.
- Coating:Advanced surface treatment layers for enhanced rubber penetration and bond durability.
Continuous Drawing governs quality differentiation; Electroplating faces the steepest regulatory transformation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao-Port of Shanghai shipping corridor underwrites East Asia's dominance in steel cord logistics, moving brass-plated filaments from Jiangsu manufacturing clusters to tyre plants across three continents.
China
Domestic tyre production scaling for export markets is concentrating demand in Jiangsu Province wire drawing facilities. SAMR's updated GB standards on dimensional tolerances require 18-24 month recertification cycles for export-qualified lines. Qingdao and Shanghai ports handle the bulk of brass-plated cord shipments to Southeast Asian tyre assembly plants.
India
OEM fitment expansion and export market growth are driving steel cord procurement toward Gujarat and Tamil Nadu manufacturing clusters. BIS certification alignment with international tyre safety protocols is tightening local specification requirements. Mundra Port infrastructure investments are reducing inland freight costs for wire rod imports from East Asian mills.
Germany
Long-haul fleet operators mandating radial construction for fuel efficiency are deepening specification requirements for high-tensile reinforcement grades. REACH Annex XVII restrictions on hexavalent chromium plating baths are forcing wire producers toward trivalent chemistry conversions. The Ruhr industrial corridor hosts qualified conversion-complete wire plants supplying premium tyre manufacturers.
United States
North American long-haul fleets specifying premium casing durability for multi-life retread programs are opening demand for copper-coated cord variants. NHTSA tyre safety ratings indirectly dictate minimum belt reinforcement specifications for domestic market entry. Gulf Coast petrochemical corridors provide backward integration opportunities for wire rod feedstock sourcing.
Japan
Precision tyre architectures for domestic OEM fitment prioritize dimensional consistency and adhesion reliability in procurement contracts. METI industrial standards govern surface treatment quality for high-performance radial applications. Nagoya and Osaka industrial zones concentrate metallurgical expertise in sub-0.20 mm filament production.
Steel Cords for Radial Tyres Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated wire-to-cord producers with captive steelmaking, specialized filament drawers with proprietary heat treatment, and regional volume fabricators serving cost-sensitive tyre makers. Belgian and South Korean groups represent the technology leadership archetype, while Chinese Jiangsu-based producers anchor the scale-driven tier. Competitive dynamics center on multi-year direct supply contracts displacing spot purchases, and REACH-compliant plating chemistry conversion racing against certification deadlines.
Among the named producers, Bekaert exemplifies the premium-tier archetype through its Belgian heritage and global wire technology positioning. Hyosung Advanced Materials occupies a position within the backward-integrated tier, leveraging petrochemical-based raw material control. Jiangsu Xingda Steel Tyre Cord anchors the volume-focused segment from its Jiangsu manufacturing base, serving both domestic Chinese tyre makers and export accounts. These three represent the competitive spectrum from high-tensile specialty grades to cost-efficient standardized production.
| Leading Market Players |
|---|
| ArcelorMittal |
| Bekaert |
| Hyosung Advanced Materials |
| Jiangsu Xingda Steel Tyre Cord |
| Sumitomo Electric Industries |
| Bridgestone Corporation |
| Tokusen Kogyo |
| Henan Hengxing Science & Technology |
| Shougang Century Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
Jiangsu Province wire drawing clusters control over half of global brass-plated cord capacity, concentrating margin capture with integrated producers who lock in multi-year direct supply contracts with tier-one tyre manufacturers. This geographic concentration shifts pricing power toward mill-to-plant relationships and away from traditional distributor intermediaries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with high-tensile grades for truck and bus retread applications commanding sustained premiums over passenger vehicle commodity specifications. Price differentiation rests on REACH-compliant plating chemistry certification and volume scale commitments, with five-year offtake agreements securing favorable terms. Cost compression in economy-grade high-carbon filaments is intensifying because Chinese domestic producers are expanding Jiangsu capacity for standardized export grades. Fleet operators in heavy-duty segments demonstrate lowest price sensitivity, prioritizing casing retreadability over first-cost.
Supply Chain Analysis
Long-term offtake agreements between Jiangsu-based wire producers and integrated tyre manufacturers in India, Germany, and the United States are displacing spot market purchases as the dominant procurement mode. Raw material supply draws from high-carbon wire rod feedstock tied to electric arc furnace output and brass plating chemistry subject to REACH Annex XVII hexavalent chromium restrictions. Single-source vulnerability concentrates in the 300-kilometer Jiangsu manufacturing radius, exposing global tyre makers to geographic disruption risk. Distribution runs through Qingdao and Shanghai port corridors to Southeast Asian assembly plants and Mundra Port for Indian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct supply contract platforms are reconfiguring procurement economics, with blockchain-tracked material certificates emerging as the interoperability layer that separates qualified suppliers from residual spot market participants.
For Market Incumbents: Build certification moats around REACH-compliant plating chemistry conversion and renewable-powered drawing operations to defend against emerging Chinese volume producers. Secure backward integration into wire rod feedstock through captive steelmaking or long-term mill partnerships. Deepen direct supply relationships with Indian tyre manufacturers scaling Gujarat and Tamil Nadu greenfield capacity. For New Entrants and Emerging Players: Pursue copper-coated cord specialization for North American long-haul retread markets where premium casing durability specifications remain underpenetrated by established Jiangsu volume producers. Target tier-two retreaders in Brazil and Southeast Asia seeking certified cord visibility for second-life performance guarantees. Lead with digital thread integration offering blockchain-tracked material certificates as a procurement differentiator. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electroplating bath chemistry conversion and renewable energy infrastructure for wire drawing operations, favoring scaled incumbents with balance sheet capacity. Acquisition targets should demonstrate completed REACH conversion certification and locked-in offtake agreements with tier-one tyre makers. Monitor quarterly contract renewal rates at European premium tyre manufacturers as the inflection signal for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Five-year offtake contracts with Indian tyre manufacturers secure volume through Gujarat and Tamil Nadu capacity ramp-ups. |
| Green Manufacturing Transition | Renewable-powered drawing operations qualify for EU Green Deal embodied-carbon tracking and premium supply contracts. |
| Backward Integration | Captive wire rod feedstock from electric arc furnace output reduces scrap steel price volatility exposure. |
| Joint Venture | Partnerships with Jiangsu-based producers enable technology transfer for sub-0.20 mm filament precision drawing. |
| Capacity Expansion | Conversion-complete plating capacity in the Ruhr corridor supplies REACH-certified cord to German premium tyre makers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAMR GB standard filings, REACH Annex XVII regulatory updates, and customs trade data for brass-plated cord shipments through Qingdao and Shanghai ports. Primary interviews engaged wire drawing process engineers, tyre manufacturer procurement leads, and retread facility operations managers across Belgium, South Korea, China, India, Germany, and the United States. Secondary validation drew from BIS certification records, NHTSA tyre safety rating databases, and SEC filings of listed steel cord producers. Bottom-up volume modeling triangulated against top-down value estimates derived from disclosed contract values and capacity utilization rates.
Forecast inputs incorporate product type segmentation across high-carbon, copper-coated, and emerging plating chemistries; application tiering across truck and bus, passenger vehicle, and two-wheeler constructions; and technology dimensions spanning continuous drawing precision and electroplating compliance status across the analysis window. CAGRs were derived from trend extrapolation of fleet conversion rates, regulatory compliance deadlines, and capacity expansion announcements. Industry-specific inputs include heavy-duty radial adoption curves in India and Brazil, and REACH conversion completion timelines at European wire plants.
Macroeconomic conditions sit as an overlay; deviation in scrap steel pricing, electric arc furnace output, or shipping corridor logistics costs would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement consistency and certification timeline adherence. Quarterly review of SAMR recertification progress, Mundra Port throughput volumes, and European premium tyre maker contract renewal announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market