
 Electric Coolant Pump Market | 2026-2036
Electric Coolant Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Coolant Pump Market Analysis
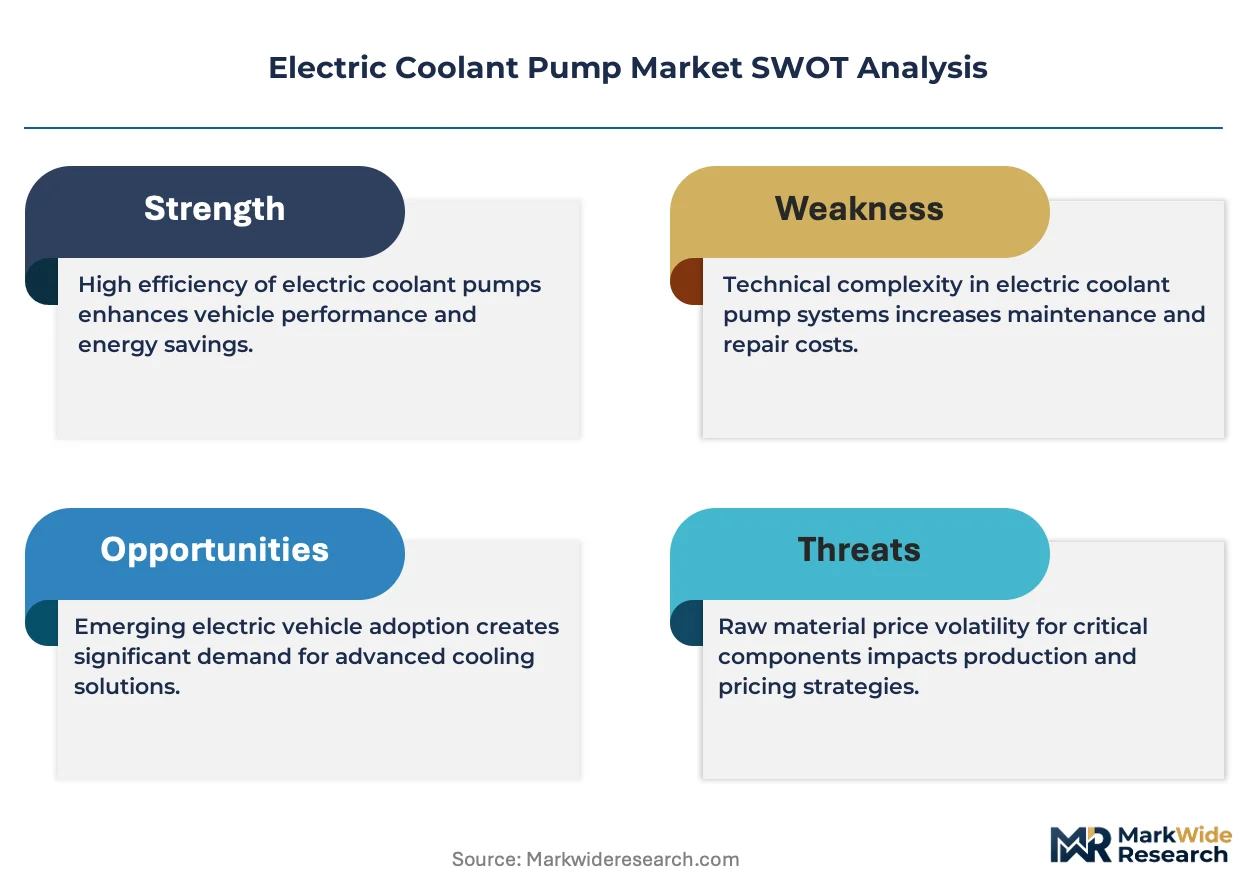
Project finance for EV thermal infrastructure is fragmenting the competitive landscape, allowing smaller suppliers to challenge legacy tier-ones. BorgWarner Inc. leverages its power electronics integration to bundle coolant pumps with inverter systems. Robert Bosch GmbH anchors its position through captive semiconductor sourcing for pump motor controllers. Valeo SA differentiates via its software-defined thermal management platform that optimizes pump speed against battery state-of-charge.
An electric coolant pump is a motor-driven fluid circulation device that maintains thermal equilibrium in electrified powertrains, typically operating at flow rates between 15 and 120 liters per minute and voltages from 12V to 800V depending on vehicle architecture. It replaces belt-driven mechanical pumps, enabling on-demand cooling that reduces parasitic losses and extends component life. Centrifugal pumps occupy the dominant share due to their efficiency across the broad flow-pressure curves required by automotive battery packs. Submersible pumps represent the fastest-growing product category as immersion cooling designs for high-energy-density batteries gain traction among OEMs. Within applications, automotive demand leads absolute volume while renewable energy installations, particularly grid-scale battery storage, offer higher margin pools per unit.
The EPA tailpipe emissions rules and the EU F-Gas Regulation are accelerating electrification mandates that expand addressable demand for electric coolant pumps across vehicle classes. China's MIIT new-energy vehicle credit system and GB standards for motor efficiency enforce minimum performance thresholds that favor electronically commutated designs over conventional alternatives. NHTSA fuel economy standards in the US push thermal efficiency gains that directly translate to pump electrification requirements. Stakeholders must monitor how battery chemistry shifts toward solid-state architectures will redefine flow rate and temperature precision specifications.
Market Dynamics
Thermal management electrification is compressing pump procurement cycles as OEMs redesign cooling architectures around 800V platforms and immersion-cooled battery packs. Suppliers must now engineer for flow precision tolerances that mechanical systems never required.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases forces automakers to abandon refrigerant-dependent thermal loops, accelerating demand for liquid-cooled systems with electric pump circulation.
- Solid-state battery commercialization:Next-generation cell chemistries require precise temperature uniformity that only variable-speed electric pumps can deliver across pack architectures.
- Jiangsu province cluster:Concentrated domestic supply capacity in China's eastern manufacturing belt reduces procurement lead times for global EV platforms.
Market Restraints
- Neodymium price volatility:Rare-earth magnet cost swings in the 30-40% range directly squeeze brushless DC motor margins, constraining pump pricing flexibility.
- Semiconductor foundry concentration:Motor controller chip supply remains bottlenecked at TSMC and Samsung Foundry facilities, exposing tier-two suppliers to allocation risk.
- Mechanical pump residual demand:Internal combustion engine platforms in commercial vehicle segments retain belt-driven cooling, limiting near-term electrification penetration.
Strategic Opportunities
- Grid-scale battery storage:Utility-scale BESS installations in Texas and California require thermal circulation systems with 20-year service intervals, opening premium aftermarket channels.
- EU Green Deal industrial heat pumps:Cross-application motor and controller platforms allow pump manufacturers to leverage EV scale in adjacent building thermal markets.
- Software-defined thermal management:Convergence of pump hardware with predictive battery health algorithms creates recurring revenue through over-the-air calibration services.
Industry Challenges
- Functional safety certification:ISO 26262 ASIL-D compliance for pump motor controllers demands 18-24 month validation timelines that delay platform launches.
- Legacy vehicle integration:Retrofit electric pumps into existing ICE cooling loops requires custom housing geometries that fragment production scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Coolant Pump Market |
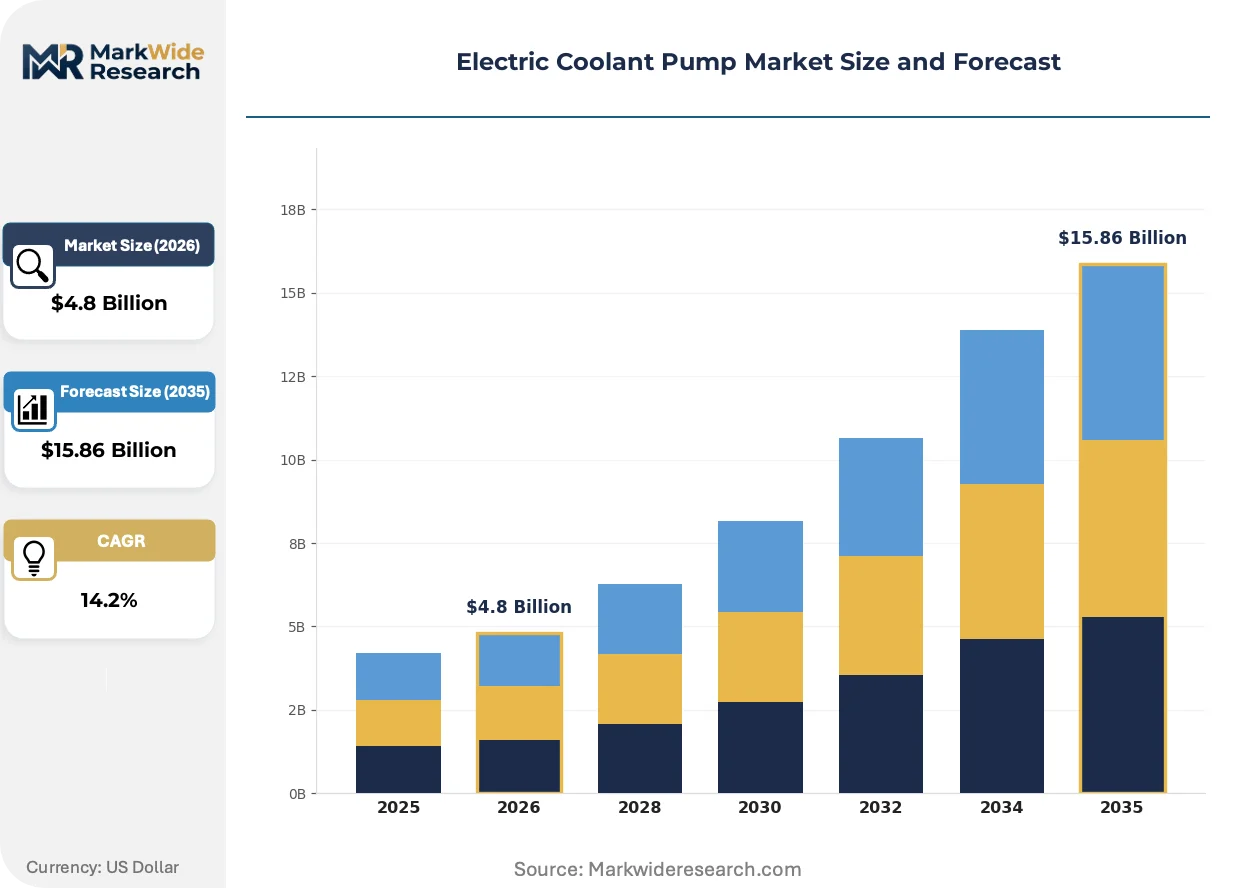
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Centrifugal Pumps, Positive Displacement Pumps, Diaphragm Pumps Application: Automotive, Industrial Machinery, HVAC Systems, Renewable Energy End User: OEMs, Aftermarket Providers, Industrial Users, Energy Sector Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | BorgWarner Inc., Valeo SA, Robert Bosch GmbH, Rheinmetall Automotive AG, Aisin Corporation, Denso Corporation, MAHLE GmbH, ZF Friedrichshafen AG, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Coolant Pump Market Emerging Trajectories
Electrified thermal architectures are fragmenting the supplier base as hardware commoditization forces differentiation through software and systems integration. Three concurrent developments are compressing traditional competitive moats.
Magnet-free synchronous reluctance motor topologies are hybridizing pump drivetrain designs, eliminating rare-earth dependency while maintaining efficiency above 93% across the 10-80 liter per minute operating envelope. Tier-one suppliers in Germany and Japan are qualifying these motors for 2027 platform launches. The technology is hybridizing procurement specifications as OEMs relax magnet content requirements in favor of supply security.
China's MIIT new-energy vehicle credit system is tightening thermal efficiency thresholds that directly cascade into pump power consumption mandates. Domestic OEMs must now document cooling system energy draw per kilometer, forcing suppliers to disclose motor efficiency maps. Battery electric passenger vehicles face the steepest compliance gradients, with Jiangsu-based pump manufacturers accelerating 12V-to-48V architecture transitions to meet 2025 credit thresholds.
Direct sourcing from pump specialists is displacing tier-one thermal module bundling as OEMs seek cost transparency. Volkswagen and BYD have established technical purchasing offices in Suzhou to engage domestic pump manufacturers without module integrator markups. This pattern is most visible in China's Yangtze River Delta, where OEM technical teams co-locate with supplier engineering centers to compress development cycles.
Electric Coolant Pump Market Segmentation
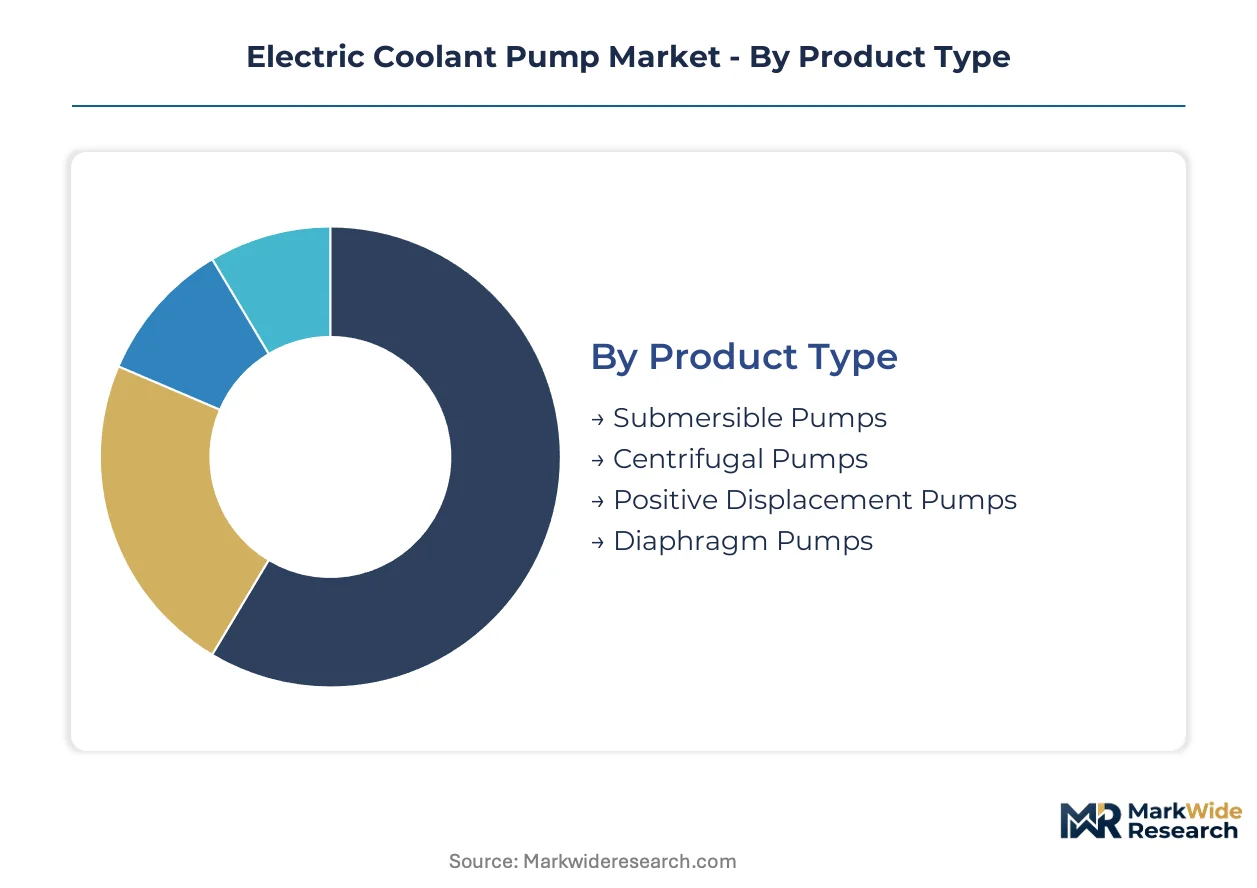
Segmentation in electric coolant pumps reveals how service intensity, technical specifications, and procurement channels fragment addressable value pools. Each dimension exposes distinct margin structures and captive demand patterns that reshape supplier positioning.
Product Type:
After-sales service intensity varies dramatically across pump architectures, with submersible designs demanding specialized field intervention while centrifugal units concentrate replacement revenue in predictable intervals.
- Submersible Pumps:Immersion-rated housings enable direct battery pack cooling without external plumbing. Jiangsu province suppliers are scaling these for 800V architectures where thermal uniformity tolerances tighten. Solid-state battery commercialization is accelerating procurement of these designs for next-generation EV platforms.
- Centrifugal Pumps:Radial impeller configurations dominate flow rates between 15 and 120 liters per minute across conventional battery thermal loops. German OEM procurement concentrates here for 400V platforms where proven reliability offsets efficiency premiums. EU F-Gas Regulation compliance is forcing refrigerant loop abandonment in favor of these liquid-cooled circulation systems.
- Positive Displacement Pumps:Reciprocating and rotary mechanisms deliver precise flow control for industrial heat recovery applications.
- Diaphragm Pumps:Seal-less construction suits aggressive coolant chemistries in grid-scale battery storage installations.
Centrifugal pumps hold the largest share; momentum sits with submersible pumps.
Application:
Cost tier stratification separates premium automotive specifications from commodity industrial deployments, with thermal precision requirements determining pricing power.
- Automotive:Passenger and commercial EV platforms specify variable-speed brushless DC motors with ISO 26262 ASIL-D functional safety certification. China's MIIT credit system enforces cooling energy draw documentation per kilometer, forcing motor efficiency map disclosure. NHTSA fuel economy standards in the US translate thermal efficiency gains directly into pump electrification mandates.
- Industrial Machinery:Machine tool and process equipment cooling tolerates wider flow variance than automotive applications. Japanese METI efficiency standards and JIS certification requirements filter supplier participation in precision manufacturing segments.
- HVAC Systems:Building thermal management repurposes EV-scale motor platforms for heat pump circulation.
- Renewable Energy:Utility-scale BESS in Texas and California demands 20-year service intervals with minimal maintenance access.
Automotive generates absolute volume; renewable energy offers the steepest expansion trajectory in margin per unit.
End User:
Customer type determines contract structure, with OEMs demanding systems integration and aftermarket channels rewarding inventory velocity.
- OEMs:Vehicle manufacturers specify pump-inverter bundles from tier-one suppliers with captive semiconductor sourcing. Volkswagen and BYD technical purchasing offices in Suzhou engage domestic manufacturers directly, bypassing module integrator markups. Direct sourcing is compressing development cycles through co-located engineering centers.
- Aftermarket Providers:Service networks prioritize interchangeability and diagnostic compatibility across vehicle generations. Replacement intervals concentrate revenue in high-mileage commercial fleets where thermal system failures carry downtime penalties.
- Industrial Users:Factory maintenance departments procure through distributor networks with technical support requirements.
- Energy Sector:Utility procurement favors long-term service agreements with guaranteed availability clauses.
OEMs command the dominant procurement volume; aftermarket providers are gaining share fastest as installed base ages.
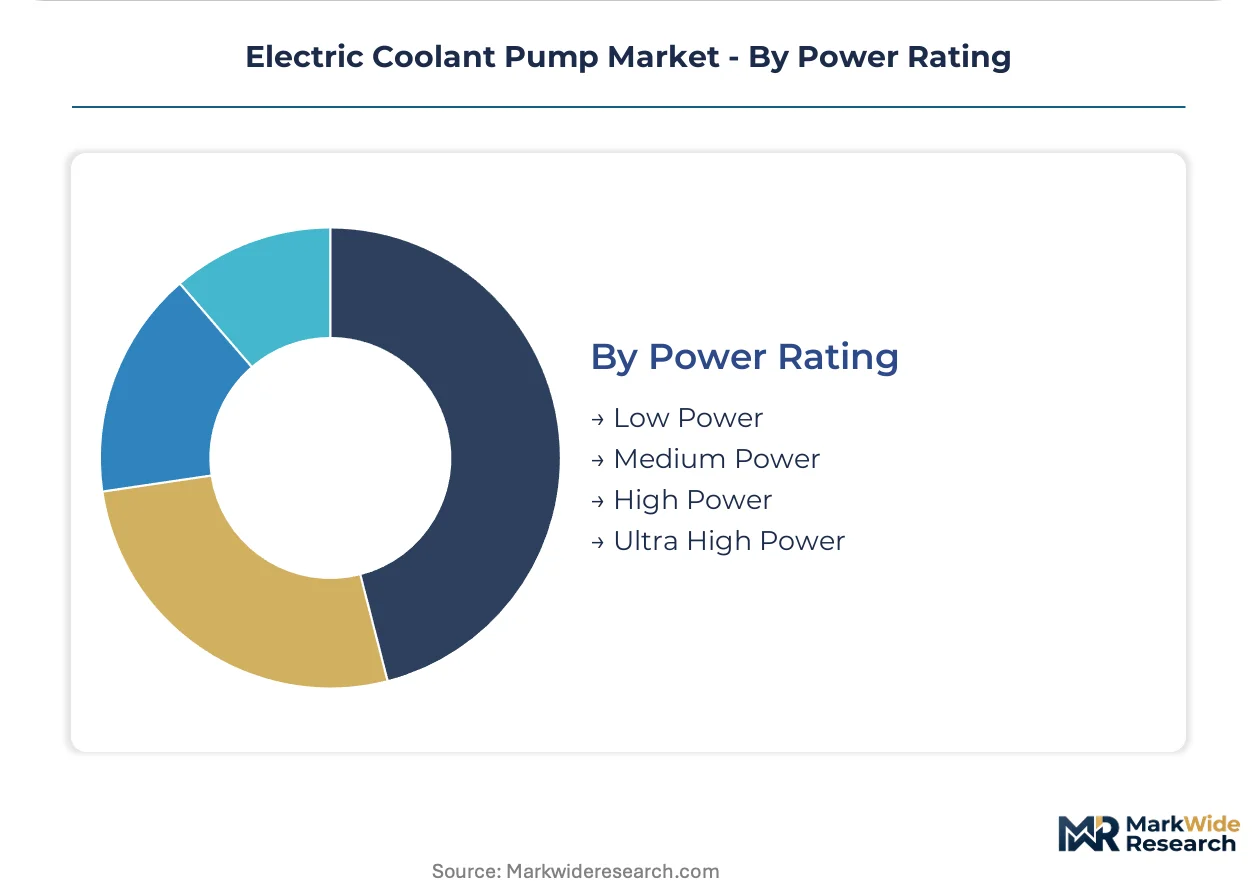
Power Rating:
Voltage architecture transitions from 12V to 48V and 800V platforms are redefining power segmentation boundaries and motor controller specifications.
- Low Power:12V brushless DC motors serve auxiliary cooling loops in hybrid vehicles and conventional thermal management. Jiangsu-based manufacturers are accelerating transitions to 48V architectures to meet MIIT credit thresholds.
- Medium Power:48V systems bridge legacy 12V networks and high-voltage traction architectures in mild-hybrid platforms.
- High Power:400V-rated pumps dominate current battery electric vehicle production with flow precision for liquid-cooled packs.
- Ultra High Power:800V architectures enable faster charging thermal management with reduced current and copper mass. TSMC and Samsung Foundry concentration for motor controller chips creates allocation risk for tier-two suppliers qualifying these designs.
High power ratings anchor current revenue; ultra high power ratings are climbing the fastest as 800V platforms multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs extract 15-20% pricing premiums over Jiangsu province suppliers for comparable 800V pump specifications. China's domestic manufacturers compensate through volume scale and compressed lead times for battery thermal management procurement.
China
MIIT credit thresholds enforce cooling energy draw documentation per kilometer for battery electric passenger vehicles. GB standards for motor efficiency favor electronically commutated pump designs over conventional alternatives. Jiangsu and Zhejiang province clusters scale production for domestic EV platforms while Suzhou hosts Volkswagen and BYD technical purchasing offices.
Germany
KBA type-approval requirements for 800V architectures drive demand for flow precision tolerances that variable-speed electric pumps deliver. EU F-Gas Regulation phases down fluorinated greenhouse gases, forcing abandonment of refrigerant-dependent thermal loops. Stuttgart and Munich anchor tier-one supplier engineering centers where BorgWarner and Robert Bosch GmbH bundle pump-inverter systems.
United States
NHTSA fuel economy standards translate thermal efficiency gains directly into pump electrification mandates across passenger and commercial vehicle classes. EPA tailpipe emissions rules accelerate fleet electrification timelines. Texas and California utility-scale BESS installations demand 20-year service interval pumps with minimal maintenance access.
Japan
METI efficiency standards and JIS certification requirements filter supplier participation in precision manufacturing segments for industrial machinery cooling. Automotive OEMs specify variable-speed brushless DC motors with ISO 26262 ASIL-D functional safety certification. Nagoya and Osaka manufacturing belts concentrate motor controller production for hybrid platform pumps.
South Korea
MFDS automotive safety standards align with international functional safety benchmarks for electrified powertrain components. Domestic battery manufacturers expand procurement of submersible pumps for immersion-cooled high-energy-density packs. Seoul Capital Area engineering centers co-locate with tier-one thermal module integrators to compress development cycles.
Electric Coolant Pump Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but faster qualification cycles. The vendor base separates into three strategic archetypes: captive tier-ones with semiconductor sourcing advantages, independent pump specialists with cost transparency appeal, and cross-application industrial players leveraging EV scale in adjacent markets. Dominant competitive moves include direct OEM technical purchasing engagement and magnet-free motor topology qualification to eliminate rare-earth dependency.
Within the captive tier-one tier, BorgWarner Inc., Robert Bosch GmbH, and Valeo SA exemplify platform bundling strategies where power electronics integration anchors customer relationships. German GmbH-structured entities occupy positions emphasizing captive semiconductor supply chains for motor controllers. French and US-incorporated competitors represent software-defined thermal management differentiation through predictive battery health algorithm convergence.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Valeo SA |
| Robert Bosch GmbH |
| Rheinmetall Automotive AG |
| Aisin Corporation |
| Denso Corporation |
| MAHLE GmbH |
| ZF Friedrichshafen AG |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries brushless DC pump assemblies from Jiangsu province to German OEM plants, with container rate fluctuations compressing margins for tier-two suppliers while amplifying price premiums for magnet-free motor configurations that bypass rare-earth volatility.
Pricing Analysis
Configured-to-order pricing for 800V submersible pumps commands a 35-50% premium over standard centrifugal catalog units due to ISO 26262 ASIL-D certification requirements and custom housing geometries. Three-tier pricing structure across premium, standard, and economy levels separates safety-critical automotive specifications from industrial heat pump circulation systems. Pricing pressure stems from neodymium magnet cost swings that squeeze brushless DC motor margins, forcing tier-two suppliers toward magnet-free reluctance topologies. Aftermarket providers exhibit highest price sensitivity due to interchangeability demands, while OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Export-control restrictions on wide-bandgap semiconductors limit motor controller chip flows from TSMC and Samsung Foundry facilities, constraining tier-two supplier access to 800V pump qualification. Manufacturing concentrates in China, Germany, and Japan, with Jiangsu province scaling submersible pump capacity for domestic EV platforms. The supply chain draws from rare-earth magnet feedstock, silicon carbide wafers, and precision-machined aluminum housings. Single-source vulnerability at foundry level exposes pump manufacturers to allocation risk during automotive platform ramps. Distribution runs through tier-one thermal module integrators and direct OEM technical purchasing offices in Suzhou.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric coolant pump markets are reconfiguring around software-defined thermal management services, where predictive battery health algorithms and over-the-air calibration subscriptions expand recurring revenue faster than hardware replacement cycles.
For Market Incumbents: Insulate semiconductor supply chains through captive sourcing arrangements or joint development agreements with foundry partners to secure motor controller allocation. Accelerate magnet-free synchronous reluctance motor qualification to eliminate rare-earth dependency and defend margin position against Jiangsu province cost competitors. Prioritize ISO 26262 ASIL-D certification maintenance as functional safety requirements harden procurement barriers.
For New Entrants and Emerging Players: Build out direct technical purchasing relationships with OEMs in Suzhou and Stuttgart, bypassing tier-one module integrator markups that fragment price transparency. Target grid-scale battery storage thermal circulation systems in Texas and California, where 20-year service interval specifications create premium aftermarket channels underserved by automotive-focused incumbents. Lead with software-defined thermal management platforms that bundle pump hardware with predictive maintenance algorithms.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming automotive thermal divisions that possess captive semiconductor relationships but lack EV-scale pump specialization. Five-to-ten year viability hinges on 800V platform penetration rates and solid-state battery commercialization timelines. Monitor TSMC and Samsung Foundry allocation announcements as inflection indicators for tier-two supplier distress opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnet-Free Motor Topology Qualification | Eliminates rare-earth dependency while maintaining efficiency above 93% across operating envelopes. |
| Direct OEM Technical Purchasing Engagement | Volkswagen and BYD co-locate engineering teams in Suzhou to compress development cycles. |
| Software-Defined Thermal Management Platform | Valeo SA converges pump hardware with predictive battery health algorithms for recurring revenue. |
| Grid-Scale BESS Thermal Circulation Entry | Texas and California utility installations demand 20-year service intervals with premium margins. |
| Captive Semiconductor Sourcing Arrangement | Robert Bosch GmbH anchors motor controller supply through backward integration into chip procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering teams, tier-one thermal module procurement, aftermarket service network managers, and Jiangsu province pump manufacturer executives. Primary interview insights were validated against vehicle production databases, MIIT new-energy vehicle credit filings, EU F-Gas Regulation implementation tracking, and SEC disclosures from listed automotive suppliers. Bottom-up pump shipment estimates were triangulated with top-down EV platform thermal system content analysis.
Calibration against historical adoption curves for 400V-to-800V architecture transitions informed flow rate and voltage segmentation modeling across the projection horizon. Segmentation dimensions included pump architecture type, application intensity tier, end-user procurement channel, and power rating classification. CAGRs were derived from installed base expansion, replacement cycle compression, and content-per-vehicle escalation for immersion-cooled battery packs. Solid-state battery commercialization timelines and EU Green Deal fleet emission trajectories served as scenario anchors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic suppliers or magnet-free motor specialists would shift outcomes. Material shifts in semiconductor foundry allocation policy, rare-earth export restrictions, or solid-state battery thermal specification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Odometer Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Global All Wheel Drive Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Passenger Car Accessories Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Japan Ceramic Ball Bearings Market
Automotive Parts
Nigeria Automotive Lubricants Market