
 Germany Automotive Pneumatic Actuators Market | 2026-2036
Germany Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Pneumatic Actuators Market Foresight
Software-defined calibration services for pneumatic valve timing is repositioning how suppliers capture lifetime value from actuator installations. Bosch Rexroth AG leverages its hydraulics heritage to anchor pneumatic product lines for powertrain automation. Festo AG & Co. KG dominates industrial pneumatic know-how and extends this expertise into vehicle assembly tooling. Continental AG competes through integrated mechatronic modules that combine sensing with pneumatic actuation.
Automotive pneumatic actuators convert compressed air into mechanical motion through cylinder-piston or diaphragm mechanisms, typically operating at pressures between 4 and 10 bar to control engine valves, clutch engagement, and brake modulation. Double acting actuators sustain the largest installed base due to their bidirectional force capability and reliability in engine control applications, while electro-pneumatic hybrids are gaining ground in transmission systems where precision shifting demands electronic-pneumatic coordination. Rack & pinion designs occupy critical positions in door mechanism automation where compact stroke-to-rotation conversion matters.
KBA type-approval requirements and EU F-Gas Regulation constrain refrigerant-based pneumatic alternatives and push manufacturers toward compressed-air systems with lower environmental footprints. Germany's implementation of CE marking under the EU Machinery Directive shapes product safety benchmarks that Tier-1 suppliers must satisfy for OEM qualification. Stakeholders should monitor how the EU AI Act's risk classification rules affect electro-pneumatic control algorithms in autonomous braking and transmission systems.
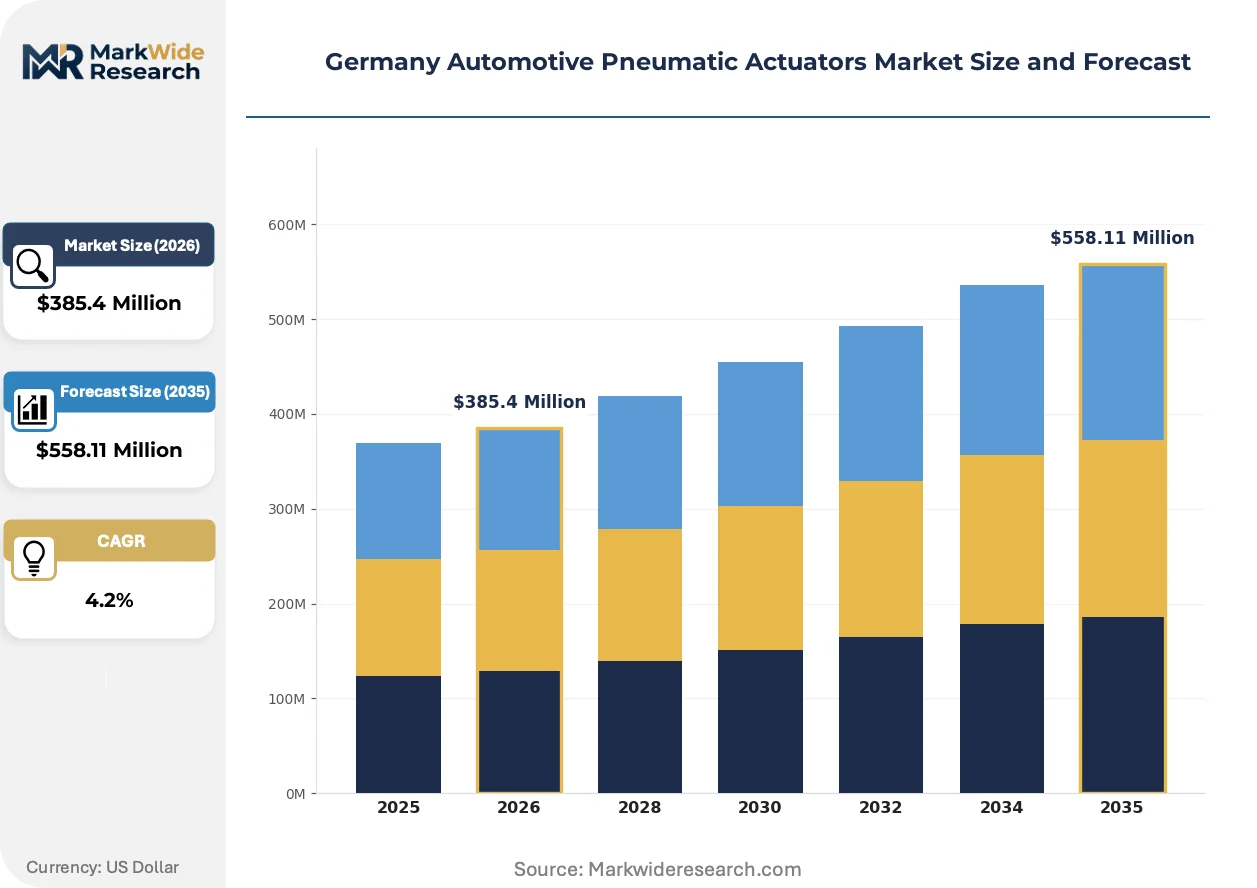
Market Dynamics
EU F-Gas Regulation and Germany's national emissions standards are compressing refrigerant-based pneumatic alternatives while pulling procurement toward compressed-air systems with certified environmental footprints. Tier-1 suppliers in Stuttgart's powertrain cluster and Wolfsburg's assembly operations face recalibrated sourcing timelines as KBA type-approval requirements tighten.
Growth Catalysts
- EU Green Deal implementation:Mandatory carbon footprint disclosures for automotive components accelerate demand for lightweight pneumatic solutions that reduce vehicle mass and emissions.
- Automated transmission proliferation:Commercial vehicle OEMs in Bavaria and Baden-Württemberg are expanding actuator procurement for clutch engagement and precision shifting systems.
- Powertrain cluster concentration:Stuttgart's dense supplier ecosystem enables rapid prototyping cycles and just-in-sequence delivery models for pneumatic module integration.
Market Restraints
- Aluminum and specialty polymer input volatility:Pneumatic cylinder housings and diaphragm materials face price swings tied to energy-intensive smelting and petrochemical feedstock costs.
- CE marking compliance friction:Germany's implementation of EU Machinery Directive safety benchmarks extends OEM qualification timelines by 8-14 months for new actuator designs.
- Electromechanical substitution pressure:High-precision servo motors are capturing transmission applications where electronic control eliminates pneumatic latency.
Strategic Opportunities
- Eastern German manufacturing expansion:Saxony and Thuringia offer underutilized industrial zones with skilled metalworking labor pools for actuator component fabrication.
- Electro-pneumatic hybrid convergence:Combining pneumatic force density with electronic valve timing creates premium positioning in autonomous braking and transmission coordination systems.
- Software-defined calibration services:Remote diagnostic and parameter adjustment capabilities extend lifetime value capture beyond hardware installation.
Industry Challenges
- Mechatronics integration complexity:Combining sensing, pneumatic actuation, and electronic control in single modules demands cross-functional engineering teams scarce in traditional pneumatic shops.
- KBA type-approval timeline compression:Accelerated vehicle development cycles clash with regulatory validation protocols for safety-critical braking and transmission actuators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Pneumatic Actuators Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Acting, Spring Return, Diaphragm, Rack & Pinion, Scotch Yoke Technology: Pneumatic, Electro-Pneumatic, Hydraulic, Servo, Piezoelectric Application: Engine Control, Suspension Systems, Door Mechanisms, Transmission Systems, Braking Systems End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Bosch Rexroth AG, Festo AG & Co. KG, SMC Corporation, Emerson Electric Co, Nidec Corporation, Denso Corporation, Continental AG, Camozzi Automation S.p.A., AVENTICS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Pneumatic Actuators Market Shifts & Advancements
Actuator architecture is bifurcating between proven pneumatic force delivery and electronically augmented precision control, with software layers increasingly determining competitive differentiation. This structural shift reconfigures how suppliers capture value across hardware lifecycles.
Electro-pneumatic valve timing systems is electrifying powertrain control by embedding solenoid-driven precision within pneumatic force circuits. Tier-1 suppliers serving Stuttgart's engine development centers are adopting these hybrids for dual-clutch transmissions where millisecond shift coordination matters. The technology is electrifying traditional pneumatic market positions by compressing the addressable space for pure compressed-air solutions in premium powertrain applications.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon-based pneumatic alternatives from automotive qualification pathways. Component suppliers must reformulate seal materials and lubricants to maintain CE marking compliance under tightened chemical safety thresholds. Powertrain actuator categories face the steepest reformulation costs as thermal and pressure specifications limit substitute material options.
Service unbundling is separating hardware procurement from lifetime calibration support, with OEMs negotiating multi-year software maintenance contracts independent of actuator unit purchases. Tier-1 suppliers in Wolfsburg's assembly corridor are piloting subscription-based parameter update models that displace traditional spare-part revenue streams. This behavioral shift is most visible in automated transmission programs where over-the-air valve timing adjustments reduce physical service visits.
Germany Automotive Pneumatic Actuators Market Segmentation
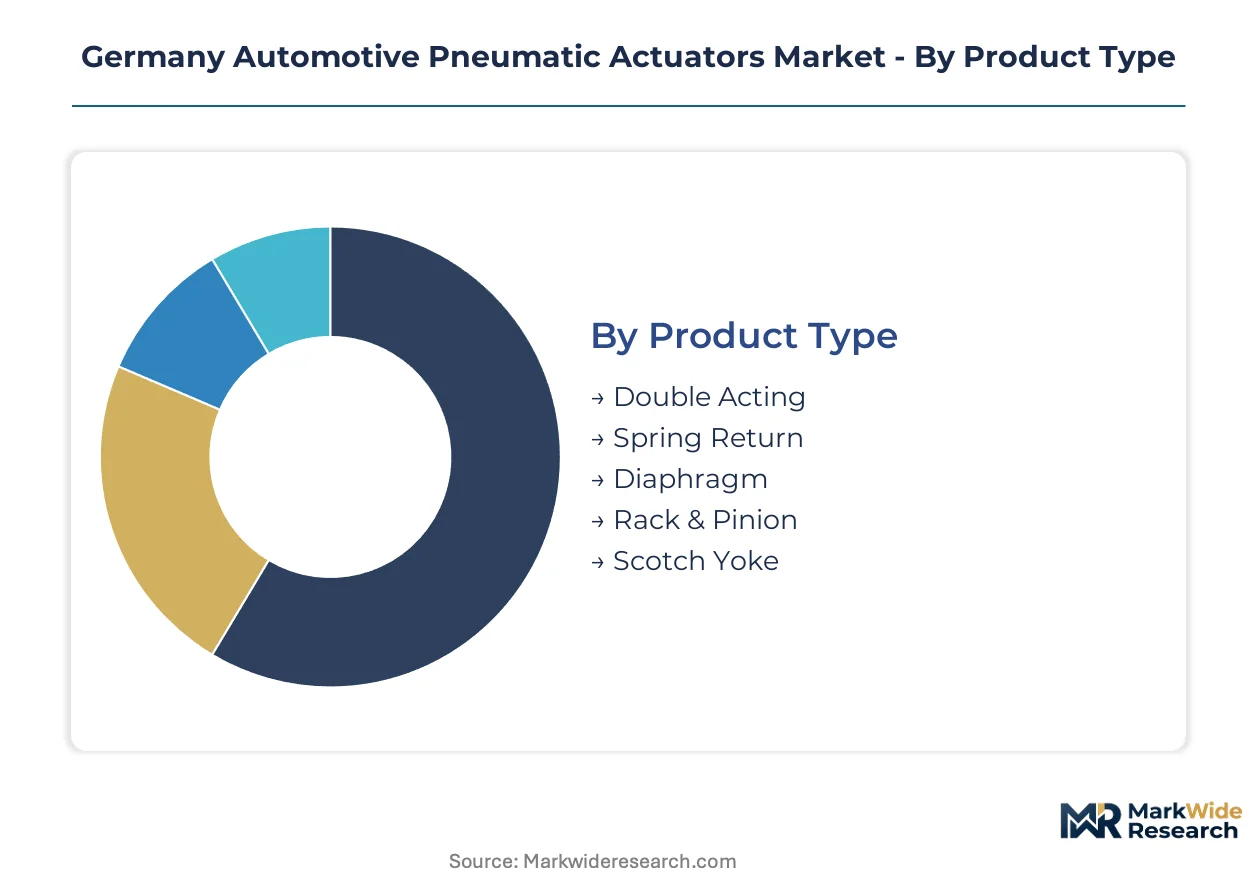
Pneumatic actuator segmentation in Germany tracks how compressed-air systems embed into vehicle architectures at varying depths of integration. Suppliers calibrate portfolio investments across standalone modules and embedded subsystems serving distinct OEM qualification pathways.
Product Type:
Standalone pneumatic cylinders dominate engine bay installations where service accessibility matters, while embedded diaphragm mechanisms integrate deeper into transmission housings requiring sealed environments.
- Double Acting:Bidirectional force capability through dual-pressure chambers enables precise valve positioning in engine control modules. Stuttgart powertrain clusters specify these for dual-clutch transmission coordination where rapid directional switching supports millisecond shift timing.
- Spring Return:Single-acting design with mechanical fail-safe reversion suits safety-critical braking applications where loss of air pressure must trigger automatic disengagement. Baden-Württemberg brake system suppliers favor these for pneumatic parking brake modules in commercial vehicle platforms.
- Diaphragm:Flexible membrane construction delivers smooth linear motion without piston seal friction, preferred for clutch engagement mechanisms in automated manual transmissions.
- Rack & Pinion:Compact stroke-to-rotation conversion occupies minimal packaging space in door latch automation where lateral swing clearance is constrained.
- Scotch Yoke:Crank-slider mechanism generates high torque at stroke extremes, specified for heavy-duty suspension height adjustment in commercial vehicle chassis.
Double Acting leads volumes today; Electro-Pneumatic hybrids in adjacent technology categories are gaining share fastest in premium powertrain applications.
Technology:
Cost tiers separate mature compressed-air implementations from electronically augmented precision systems commanding qualification premiums.
- Pneumatic:Pure compressed-air systems operating at 4-10 bar pressure ranges anchor economy-tier procurement for high-volume clutch and brake modulation. Wolfsburg assembly operations specify these for cost-optimized transmission lines where electronic coordination adds insufficient value.
- Electro-Pneumatic:Solenoid-driven precision layered onto pneumatic force circuits enables programmable valve timing. Bavarian commercial vehicle OEMs specify these for automated transmission systems where electronic shift maps override pneumatic baseline timing.
- Hydraulic:Fluid-power alternatives deliver higher force density for heavy-load suspension applications, competing at the premium tier against pneumatic solutions.
- Servo:All-electric precision systems displace pneumatic latency in next-generation autonomous braking prototypes, positioned at the highest cost tier.
- Piezoelectric:Ultra-fast response ceramic actuators serve niche fuel injection timing applications where nanosecond precision justifies extreme cost premiums.
Pneumatic technology commands the largest installed base; Electro-Pneumatic systems are climbing the fastest as transmission automation proliferates.
Application:
Volume concentration varies sharply between powertrain-critical functions requiring KBA type-approval and auxiliary systems with lighter regulatory burdens.
- Engine Control:Valve train actuation demands thermal resilience and contamination resistance in high-temperature bay environments. Stuttgart engine development centers specify pneumatic solutions for variable valve timing where cost constraints exclude full electromechanical substitution.
- Transmission Systems:Clutch engagement and gear selection coordination require precise force modulation synchronized with electronic control units. Saxony-based transmission specialists are expanding procurement for electro-pneumatic hybrids serving dual-clutch architectures.
- Braking Systems:Pneumatic brake modulation serves commercial vehicle air brake architectures with established safety validation frameworks.
- Suspension Systems:Height adjustment and damping control applications favor pneumatic solutions for ride-quality tuning in premium vehicle segments.
- Door Mechanisms:Latch automation and power sliding door actuation occupy lower-criticality positions with reduced qualification friction.
Transmission Systems applications are expanding most quickly; Engine Control retains the deepest supplier relationships.
End User:
Customer type determines procurement rhythm, with vehicle assemblers driving just-in-sequence delivery models distinct from aftermarket inventory patterns.
- OEMs:Original equipment manufacturers in Bavaria and Baden-Württemberg specify actuator modules directly for powertrain integration, negotiating multi-year frame contracts with embedded software maintenance terms.
- Tier-1 Suppliers:Stuttgart-based subsystem integrators aggregate pneumatic components into mechatronic modules, absorbing CE marking compliance burdens before OEM handoff.
- Vehicle Assemblers:Wolfsburg corridor operations focus on final assembly line fitting of pre-qualified pneumatic subsystems, minimizing in-house validation scope.
- Aftermarket Providers:Independent service networks stock replacement actuators for legacy commercial vehicle fleets, operating outside OEM qualification timelines.
Tier-1 Suppliers intermediate the largest volume flows; OEM direct procurement is expanding fastest as powertrain integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within Germany follows regulatory cost differentials, with actuator fabrication shifting toward eastern states offering streamlined CE marking pathways and lower environmental compliance burdens relative to western industrial zones.
Bavaria
Commercial vehicle OEMs in Munich and Ingolstadt are expanding electro-pneumatic procurement for automated transmission systems. KBA type-approval requirements tighten validation timelines for safety-critical braking actuators. The Nuremberg-Regensburg corridor hosts dense supplier networks serving powertrain integration programs.
Baden-Württemberg
Stuttgart's powertrain cluster drives demand for precision valve timing modules in dual-clutch architectures. EU F-Gas Regulation eliminates refrigerant-based pneumatic alternatives from automotive qualification pathways. Karlsruhe-based engineering centers prototype next-generation clutch engagement mechanisms for premium vehicle platforms.
Lower Saxony
Wolfsburg assembly operations specify cost-optimized pneumatic cylinders for high-volume transmission lines. Germany's national emissions standards accelerate lightweight actuator adoption to reduce vehicle mass. Braunschweig's research institutes collaborate with Tier-1 suppliers on mechatronic module integration.
Saxony
Eastern manufacturing zones attract actuator component fabrication with underutilized industrial capacity and skilled metalworking labor pools. REACH substance restrictions force seal material reformulation for CE marking compliance. Dresden-Chemnitz corridor suppliers specialize in transmission system subassemblies for Bavarian OEMs.
North Rhine-Westphalia
Ruhr Valley industrial heritage supports heavy-duty pneumatic systems for commercial vehicle brake modulation. EU Machinery Directive safety benchmarks extend qualification timelines for new actuator designs. Cologne-Düsseldorf logistics hubs enable just-in-sequence delivery to western German assembly plants.
Germany Automotive Pneumatic Actuators Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated mechatronic module providers capturing premium positioning while component fabricators serve cost-optimized volume tiers. Market structure tilts toward consolidation among Tier-1 subsystem integrators absorbing CE marking compliance burdens before OEM handoff. Three archetypes dominate: hydraulics-heritage diversifiers extending into pneumatic powertrain automation, industrial pneumatic specialists pivoting toward vehicle assembly tooling, and electronics-integrated mechatronics providers combining sensing with actuation. Competitive moves concentrate on electro-pneumatic hybrid convergence and software-defined calibration service unbundling.
Among Germany-based diversified industrials, Bosch Rexroth AG and Festo AG & Co. KG exemplify contrasting heritage-to-automation pathways, while Continental AG occupies a position within the integrated electronics tier. Bosch Rexroth AG represents the hydraulics-heritage archetype leveraging fluid-power expertise into powertrain automation applications. Festo AG & Co. KG anchors the industrial-to-automotive pivot, translating factory-floor pneumatic know-how into vehicle assembly tooling systems. Continental AG sits within the mechatronics convergence segment where electronic control integration determines competitive differentiation. SMC Corporation and AVENTICS represent international specialists competing on component scale and regional service density respectively.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Festo AG & Co. KG |
| SMC Corporation |
| Emerson Electric Co |
| Nidec Corporation |
| Denso Corporation |
| Continental AG |
| Camozzi Automation S.p.A. |
| AVENTICS |
| Others |
Supply & Pricing Matrix
Tier-1 subsystem integrators serving Stuttgart and Wolfsburg command disproportionate pricing leverage through multi-year frame contracts bundling hardware procurement with software maintenance terms. This buyer concentration compresses margins for component fabricators while rewarding integrated mechatronic module providers with premium positioning.
Pricing Analysis
Capacity additions in Saxony and Thuringia are reshaping price floors for pneumatic cylinder housings and diaphragm components. A three-tier pricing structure across premium, standard, and economy levels separates electro-pneumatic hybrids with embedded sensing from pure compressed-air systems and unbranded replacement parts. Cost compression in economy-tier clutch actuators is intensifying because aluminum smelting energy costs feed through to housing material prices. Commercial vehicle aftermarket providers exhibit the highest price sensitivity, while OEM powertrain procurement teams prioritize qualification reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in the Cologne-Düsseldorf corridor coordinate just-in-sequence delivery to western German assembly plants through hub-and-spoke patterns. Manufacturing draws from Germany, China, and Czech Republic for precision-machined cylinder bodies, specialty polymer diaphragms, and electronic valve control modules. Single-source vulnerability concentrates in high-grade aluminum alloy feedstock from energy-intensive European smelters. Distribution runs through Tier-1 subsystem integrators who absorb CE marking compliance burdens before OEM handoff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's automotive pneumatic actuator market represents a late-cycle quality story as EU Green Deal carbon disclosure requirements shift procurement toward lightweight, certified-environmental-footprint solutions over commodity compressed-air alternatives.
For Market Incumbents: Anticipate electromechanical substitution pressure in transmission applications by deepening software-defined calibration service offerings that extend lifetime value capture beyond hardware installation. Consolidate position through backward integration into aluminum alloy sourcing to hedge energy-cost volatility, while investing in CE marking pre-certification capabilities to compress OEM qualification timelines threatened by KBA type-approval tightening. For New Entrants and Emerging Players: Direct-to-Tier-1 digital sales channels bypass entrenched distributor relationships in the aftermarket segment. Target eastern German manufacturing zones where underutilized industrial capacity and skilled metalworking labor pools offer cost-advantaged entry points. Focus initial qualification efforts on door mechanism automation where KBA regulatory burden remains lighter than powertrain-critical applications. For Investors and Strategic Acquirers: Industrial automation conglomerates seeking automotive diversification represent the most active acquirer in this space. Five-to-ten year viability hinges on electro-pneumatic hybrid convergence capabilities combining force density with electronic precision. Monitor software maintenance contract attach rates as the inflection indicator separating sustainable recurring-revenue models from hardware-commoditization traps.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Pneumatic Hybrid Development | Combines Festo's pneumatic heritage with Bosch Rexroth's electronic control integration for transmission automation. |
| Software-Defined Calibration Services | Enables Continental AG to capture subscription revenue from over-the-air valve timing adjustments. |
| Eastern German Manufacturing Footprint | Saxony's skilled metalworking labor pools reduce actuator housing fabrication costs. |
| CE Marking Pre-Certification Investment | Compresses OEM qualification timelines by 8-14 months under EU Machinery Directive benchmarks. |
| Lightweight Material Transition | EU Green Deal carbon disclosures accelerate demand for aluminum alloy and polymer diaphragm solutions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged Tier-1 supplier procurement directors, OEM platform engineers in Bavaria and Baden-Württemberg, aftermarket distribution channel heads, and CE marking compliance consultants. Secondary validation drew from KBA type-approval databases, EU F-Gas Regulation implementation notices, vehicle production statistics, and SEC filings of listed automotive component suppliers. Bottom-up actuator shipment estimates triangulated against top-down powertrain content-per-vehicle models.
Historical reference periods anchored the projection framework against known production volumes and technology adoption curves across the analysis window. Segmentation dimensions modeled include product architecture, technology tier, application criticality, and end-user procurement pattern. CAGRs derived from logistic diffusion curves fitted to electro-pneumatic hybrid penetration rates and lightweight material substitution elasticities. Forecast inputs incorporated EU Green Deal implementation timelines and REACH substance restriction phase-down schedules.
The model assumes a particular technology adoption path; alternative pathways for full electromechanical substitution in transmission systems would alter the outlook. Forecasts reflect documented assumptions regarding KBA regulatory stability and aluminum energy-cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Philippines Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Automotive All Wheel Drive Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Canada Automotive Actuators Market
Automotive Parts
Motor Bearings Market
Automotive Parts
Synchronous Timing Belts Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Friction Pads Market
Automotive Parts
Automotive Propeller Shaft Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market