
 Tappet Market | 2026-2036
Tappet Market Size, Share, and Industry Trends Forecast 2026-2036
Tappet Market Analysis
Maintenance-contract bundling with valve-train component supply is restructuring how tappet vendors monetize long-term customer relationships. Schaeffler Group leverages its integrated bearing-tappet portfolio to anchor aftermarket service agreements across European commercial fleets. Eaton Corporation competes through hydraulic lash adjuster technology leadership in North American heavy-duty applications. SKF extends its position by combining tappet distribution with predictive maintenance software for industrial engine operators.
A tappet is a cylindrical component that transfers camshaft motion to open engine valves, typically manufactured from chilled cast iron or through-hardened steel with surface finishes below 0.4 micrometers Ra to minimize friction wear against cam lobes. Its primary purpose is to translate rotary cam profile geometry into precise linear valve displacement while maintaining lash tolerance under thermal and mechanical load cycling. Roller tappet architectures command the highest margin pools as OEMs prioritize friction reduction for fuel-economy compliance, while flat tappet demand sustains volume in cost-sensitive aftermarket channels. Aluminum material grades gain share in motorcycle and small-displacement automotive engines where reciprocating mass reduction directly improves power density.
EPA Tier 4 and Euro VI emission frameworks compel tappet manufacturers to certify surface treatments and material compositions for durability under elevated combustion pressures and EGR thermal stress. China's MIIT integrates valve-train efficiency into corporate average fuel consumption calculations, creating regulatory pull for low-friction roller designs in domestic engine platforms. India's BIS aligns with AIS emission norms that tighten particulate thresholds for commercial vehicles, shaping tappet specification requirements for Bharat Stage VI-compliant powertrains. Stakeholders must monitor how carbon-border adjustment mechanisms and localized content rules in major automotive manufacturing jurisdictions reshape supplier qualification criteria and sourcing geography decisions.
Market Dynamics
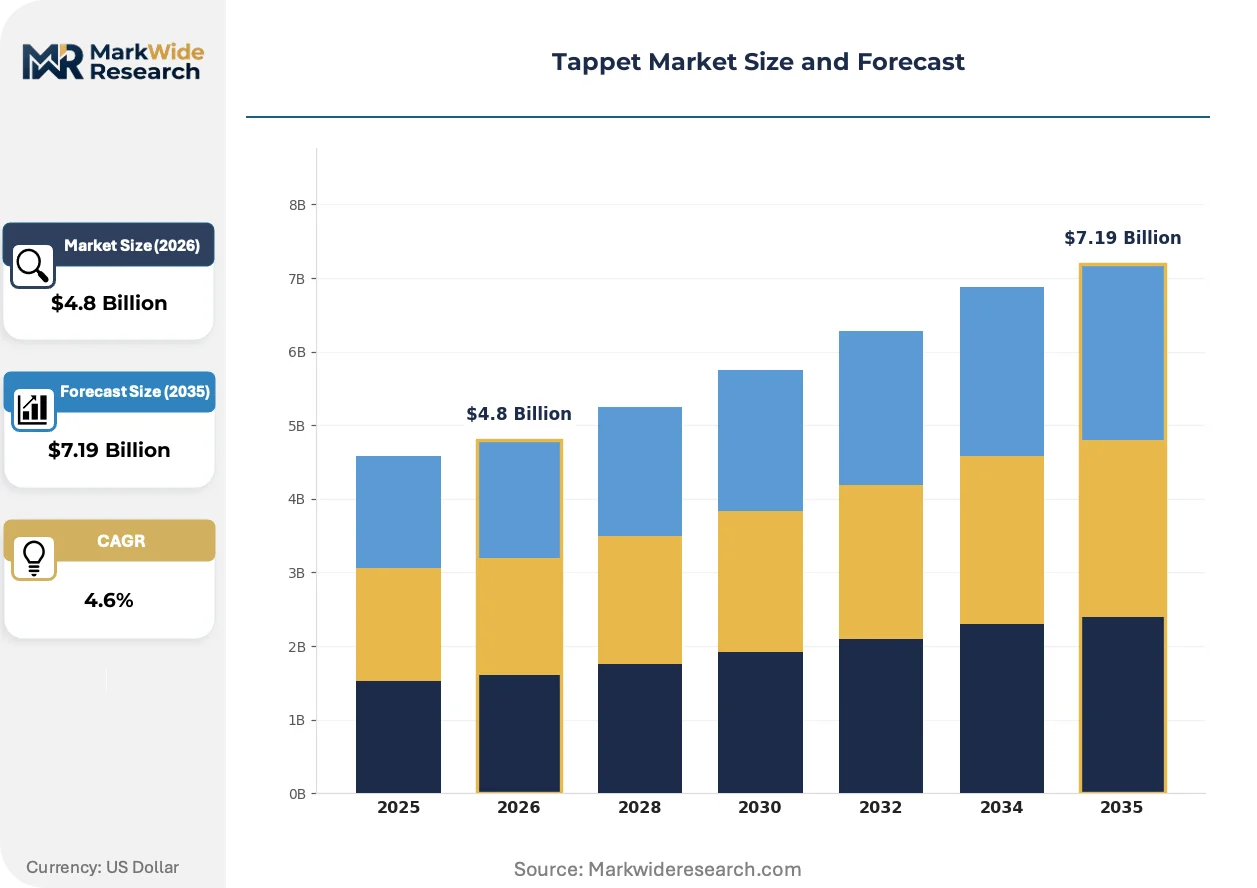
Friction-reduction mandates from China's MIIT and India's BIS are compressing specification cycles for valve-train components, forcing tappet manufacturers to recalibrate material portfolios and surface treatment investments ahead of traditional platform refresh timelines.
Growth Catalysts
- Roller tappet architectures:China's MIIT corporate average fuel consumption calculations now weight valve-train efficiency, pulling domestic OEMs toward low-friction roller designs over legacy flat configurations.
- Commercial vehicle OEM procurement:Heavy-duty truck assembly corridors near Pune and Chennai concentrate demand for Bharat Stage VI-compliant tappet specifications.
- Aluminum material grades:Reciprocating mass reduction requirements in motorcycle and small-displacement automotive engines expand application scope for lightweight tappet variants.
Market Restraints
- Chilled cast iron input volatility:Foundry-grade pig iron pricing swings compress margin buffers for flat tappet producers serving cost-sensitive aftermarket channels.
- Surface treatment certification backlog:EPA Tier 4 and Euro VI durability testing queues extend qualification timelines for new coating chemistries by 8-14 months.
- EGR thermal stress tolerance:Elevated combustion pressures in modern diesel architectures limit material substitution options, trapping suppliers in higher-cost through-hardened steel grades.
Strategic Opportunities
- Predictive maintenance software bundling:Industrial engine operators seek tappet distribution partnerships with condition-monitoring platforms to reduce unplanned downtime.
- Maintenance-contract anchoring:European commercial fleets negotiate multi-year valve-train service agreements that lock in component supply volumes.
- Carbon-border adjustment positioning:Localized content rules in major automotive manufacturing jurisdictions reward suppliers with captive heat treatment and finishing capacity.
Industry Challenges
- Surface finish metrology talent scarcity:Sub-0.4 micrometer Ra specification enforcement requires specialized profilometry technicians concentrated in German and Japanese supplier bases.
- Lash tolerance calibration complexity:Thermal expansion coefficient matching between tappet bodies and camshaft lobes demands iterative dyno validation that strains R&D throughput.
- Legacy hydraulic lash adjuster integration:North American heavy-duty applications resist full roller conversion, forcing parallel production of two architectural families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tappet Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Tappet, Roller Tappet, Hydraulic Tappet, Pneumatic Tappet Material: Aluminum, Steel, Cast Iron, Composite Application: Automotive Engines, Marine Engines, Industrial Engines, Motorcycle Engines End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Maintenance Shops |
| Companies Covered | Schaeffler Group, Eaton Corporation, Federal-Mogul (Tenneco Inc.), NSK Ltd., SKF, MAHLE GmbH, Otics Corporation, Competition Cams, Inc., Rane Engine Valve Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tappet Market Emerging Trajectories
Active material substitution and regulatory compression of specification cycles are restructuring how tappet suppliers allocate capital between product architectures, with surface engineering investments now preceding platform commitments.
Roller tappet architectures is overtaking flat designs in OEM specifications where friction reduction directly impacts fuel-economy compliance calculations. Commercial vehicle manufacturers in China and India specify roller configurations for new Bharat Stage VI and MIIT-aligned platforms. This transition is compressing flat tappet volume into aftermarket channels and concentrating margin pools with roller-capable suppliers.
REACH substance restrictions and EU Green Deal carbon-intensity disclosures are forcing requalification of phosphate coating chemistries and hardening process emissions. Tappet manufacturers must document supply-chain carbon footprints to maintain qualification with European commercial fleet OEMs. Roller tappet producers with in-house heat treatment capacity gain preferential sourcing status under these protocols.
Service-contract bundling now displaces transactional component sales in European commercial fleet procurement. Valve-train vendors anchor multi-year agreements through integrated bearing-tappet portfolios and predictive maintenance software. This pattern concentrates procurement authority with integrated suppliers and compresses spot-market volumes for standalone tappet distributors.
Tappet Market Segmentation
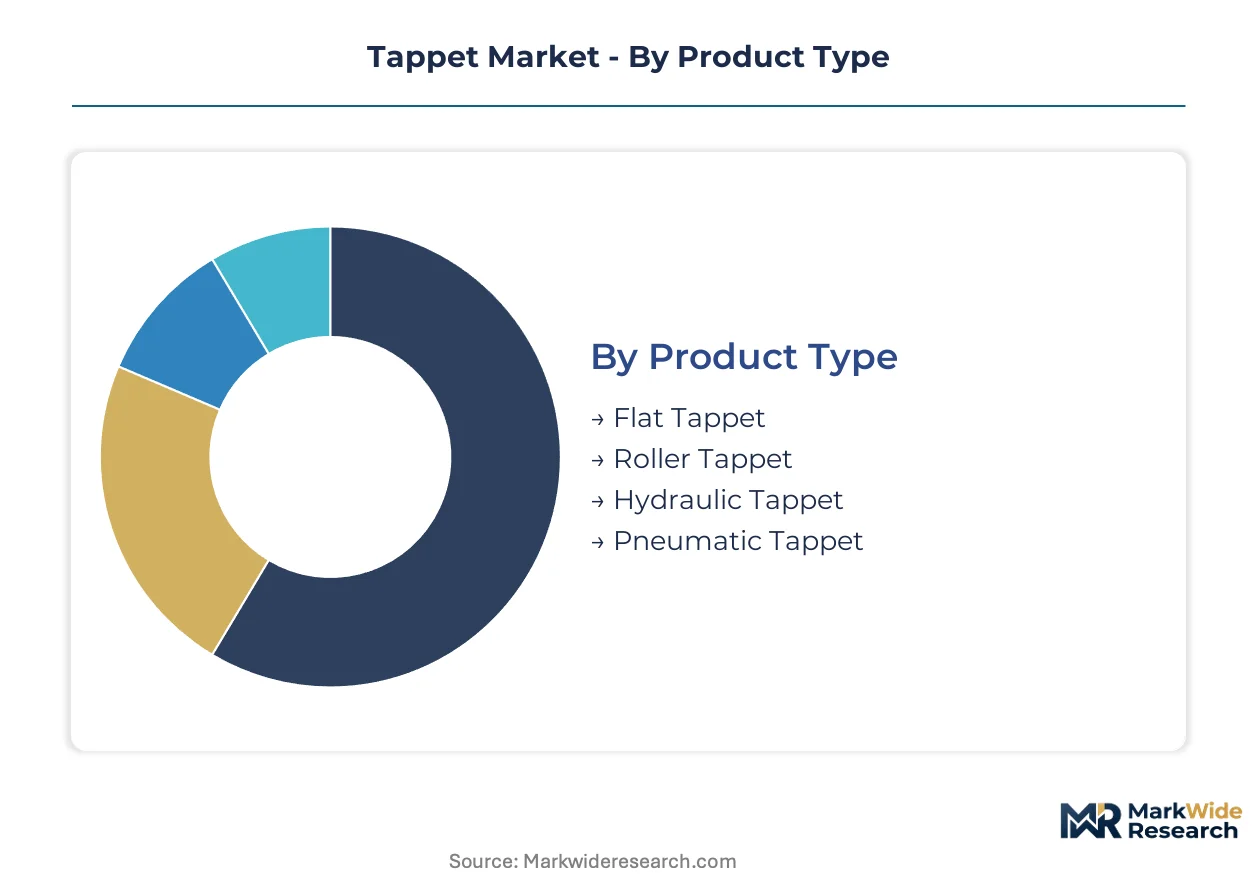
Tappet procurement patterns diverge sharply across product architectures and material grades, with regulatory pressure on valve-train friction creating tiered demand pools. OEMs prioritize roller configurations for fuel-economy compliance while aftermarket channels sustain flat tappet volumes in cost-sensitive replacement cycles.
Product Type:
Buyer differentiation centers on friction-reduction requirements versus legacy system compatibility and total installed cost.
- Roller Tappet:Cylindrical bearing elements replace sliding contact with rolling motion, cutting friction coefficients by 40-60% versus flat designs. China's MIIT corporate average fuel consumption calculations weight valve-train efficiency heavily, pulling domestic OEMs toward roller configurations for new engine platforms.
- Flat Tappet:Simple cylindrical profile with direct cam-lobe sliding contact, manufactured from chilled cast iron or through-hardened steel. Cost-sensitive aftermarket channels in India and Southeast Asia sustain volume demand where Bharat Stage VI retrofit economics favor repair-over-replace strategies.
- Hydraulic Tappet:Self-adjusting lash compensation via internal oil pressure eliminates manual valve clearance maintenance. North American heavy-duty applications resist full roller conversion, preserving parallel demand for hydraulic architectures in legacy diesel platforms.
- Pneumatic Tappet:Compressed-air actuation enables variable valve timing without mechanical camshaft dependency. Experimental adoption concentrates in high-performance racing and specialized industrial engine prototypes seeking extreme RPM operation.
Flat tappet leads volumes today; roller tappet is gaining share fastest.
Material:
Material selection trades off reciprocating mass, thermal durability, and foundry input cost volatility across application tiers.
- Steel:Through-hardened alloy grades deliver maximum durability under EGR thermal stress and elevated combustion pressures. Euro VI and EPA Tier 4 durability testing requirements trap suppliers in higher-cost steel grades where surface treatment certification backlogs extend qualification timelines.
- Aluminum:Lightweight alloys reduce reciprocating mass by 50-65% versus ferrous alternatives. Motorcycle and small-displacement automotive engines in Japan and Italy specify aluminum tappets where power density improvements justify premium material costs.
- Cast Iron:Chilled cast iron offers lowest unit cost with adequate wear resistance for moderate-duty cycles. Foundry-grade pig iron pricing swings compress margin buffers for producers serving price-sensitive aftermarket distributors in Brazil and Mexico.
- Composite:Polymer-matrix or ceramic-reinforced materials target extreme thermal insulation in specialized racing applications. Limited commercial penetration reflects bonding interface challenges with metallic valve-train components.
Steel dominates OEM specifications; aluminum is expanding most quickly in lightweighting-focused segments.
Application:
Engine displacement and duty cycle intensity create divergent specification requirements across mobility and stationary power sectors.
- Automotive Engines:Passenger car and light commercial platforms drive precision manufacturing investments for sub-0.4 micrometer Ra surface finishes. China's MIIT enforcement of stricter fuel-efficiency mandates favors roller tappet architectures in domestic engine production.
- Industrial Engines:Stationary power generation and compressor applications prioritize predictive maintenance integration. SKF and Schaeffler Group bundle tappet supply with condition-monitoring software to reduce unplanned downtime for European industrial operators.
- Marine Engines:Saltwater corrosion resistance demands specialized surface treatments and material specifications. Classification society certification requirements extend qualification timelines for new coating chemistries in marine applications.
- Motorcycle Engines:High-RPM operation and severe space constraints favor aluminum material grades for reciprocating mass reduction. Indian and Vietnamese assembly corridors concentrate demand for small-displacement tappet specifications.
Automotive engines anchor procurement volumes; industrial engines show the steepest expansion trajectory through maintenance-contract bundling.
End User:
Procurement authority and technical specification control vary dramatically across direct manufacturing versus service-channel relationships.
- OEMs:Original equipment manufacturers dictate material certifications, surface treatments, and architectural roadmaps through multi-year platform supply agreements. European commercial fleet OEMs now require documented supply-chain carbon footprints under EU Green Deal disclosure protocols.
- Aftermarket Providers:Independent distributors and private-label suppliers compete on inventory breadth and price positioning. Flat tappet volume concentrates here as roller architectures remain captive to OEM service networks during warranty periods.
- Vehicle Assemblers:Contract manufacturers and knock-down assembly operations procure tappets through tiered supplier qualification programs. India's heavy-duty truck assembly corridors near Pune and Chennai concentrate Bharat Stage VI-compliant specification demand.
- Maintenance Shops:Independent repair facilities drive spot-market demand with limited technical specification influence. REACH substance restrictions force requalification of phosphate coating chemistries accessible through aftermarket channels.
OEMs command specification authority; aftermarket providers capture volume scale in mature replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT enforcement of stricter fuel-efficiency mandates outpaces India's BIS emission timeline compression, yet both regulators are pulling Asian OEM procurement toward low-friction roller architectures. European commercial fleets anchor maintenance-contract bundling, while North American heavy-duty applications preserve hydraulic lash adjuster demand.
China
Domestic engine platforms from SAIC and Geely specify roller tappet configurations to meet MIIT corporate average fuel consumption calculations. The regulator weights valve-train efficiency heavily in compliance scoring, forcing rapid specification shifts. Yangtze River Delta manufacturing clusters near Shanghai concentrate heat treatment and surface finishing investments for roller-capable suppliers.
India
Heavy-duty truck assembly corridors near Pune and Chennai concentrate Bharat Stage VI-compliant tappet procurement as OEMs expand commercial vehicle capacity. BIS alignment with AIS emission norms tightens particulate thresholds, shaping material specifications for through-hardened steel grades. Domestic suppliers face qualification backlogs for surface treatment chemistries under new durability testing protocols.
Germany
Commercial fleet OEMs require documented supply-chain carbon footprints under EU Green Deal disclosure protocols, favoring suppliers with captive heat treatment capacity. REACH substance restrictions force requalification of phosphate coating chemistries. Bavaria and Baden-Württemberg anchor integrated bearing-tappet manufacturing for European aftermarket service agreements.
United States
EPA Tier 4 durability testing requirements trap suppliers in higher-cost steel grades where surface treatment certification queues extend qualification timelines. North American heavy-duty diesel platforms resist full roller conversion, preserving parallel demand for hydraulic lash adjuster architectures. Midwestern foundry clusters supply chilled cast iron for cost-sensitive aftermarket channels.
Japan
Motorcycle and small-displacement automotive engine manufacturers specify aluminum tappet grades to reduce reciprocating mass and improve power density. METI efficiency standards accelerate material substitution away from ferrous alternatives. Aichi Prefecture manufacturing corridors near Nagoya concentrate precision finishing investments for sub-0.4 micrometer Ra surface specifications.
Tappet Market Vendor Landscape
Top-tier vendors anchor specification-setting relationships with global OEMs, while mid-tier fabricators compete on aftermarket volume and regional qualification speed. The vendor base stratifies across integrated bearing-tappet portfolios, standalone component specialists, and foundry-linked producers serving cost-sensitive replacement channels. Strategic archetypes include predictive maintenance software bundlers, captive heat treatment operators, and regional qualification specialists. Dominant competitive moves center on maintenance-contract anchoring and carbon-border adjustment positioning through localized finishing capacity.
Within the integrated portfolio tier, Schaeffler Group and SKF represent the convergence of bearing manufacturing with valve-train component supply, anchoring multi-year service agreements through combined hardware and condition-monitoring offerings. Otics Corporation occupies a position among Japanese specialists focused on precision surface finishing for sub-0.4 micrometer Ra specifications. These three exemplify how competitive positioning now depends on bundling component supply with predictive maintenance platforms rather than transactional volume alone.
| Leading Market Players |
|---|
| Schaeffler Group |
| Eaton Corporation |
| Federal-Mogul (Tenneco Inc.) |
| NSK Ltd. |
| SKF |
| MAHLE GmbH |
| Otics Corporation |
| Competition Cams, Inc. |
| Rane Engine Valve Limited |
| Others |
Supply Flow & Price Mechanics
Chilled cast iron input volatility cascades through flat tappet pricing tiers as foundry-grade pig iron swings compress margin buffers for aftermarket producers serving cost-sensitive distributors in Brazil and Mexico, while roller-capable suppliers in Germany and Japan capture premium positioning through captive heat treatment investments.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for roller tappet architectures as domestic MIIT compliance deadlines accelerate specification shifts. Three-tier pricing structure across premium roller, standard hydraulic, and economy flat configurations stratifies by surface finish certification and thermal durability grade. Cost compression in flat tappet channels intensifies because foundry input volatility strips pricing power from non-integrated producers. Aftermarket distributors exhibit highest price sensitivity; OEM platform engineers prioritize friction-reduction performance over unit cost.
Supply Chain Analysis
Specialized profilometry technician scarcity in German and Japanese supplier bases constrains throughput for sub-0.4 micrometer Ra surface finish enforcement. Manufacturing concentrates in China, Germany, and India where heat treatment and precision finishing investments cluster. Supply chains draw from through-hardened steel alloys, foundry-grade pig iron, and aluminum billet feedstocks. Single-source vulnerability sits with chilled cast iron foundries in emerging market corridors. Distribution runs through tiered supplier qualification programs anchored by OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory pressure into procurement authority concentration as China's MIIT corporate average fuel consumption calculations and India's BIS Bharat Stage VI timelines compress specification cycles ahead of traditional platform refresh timelines.
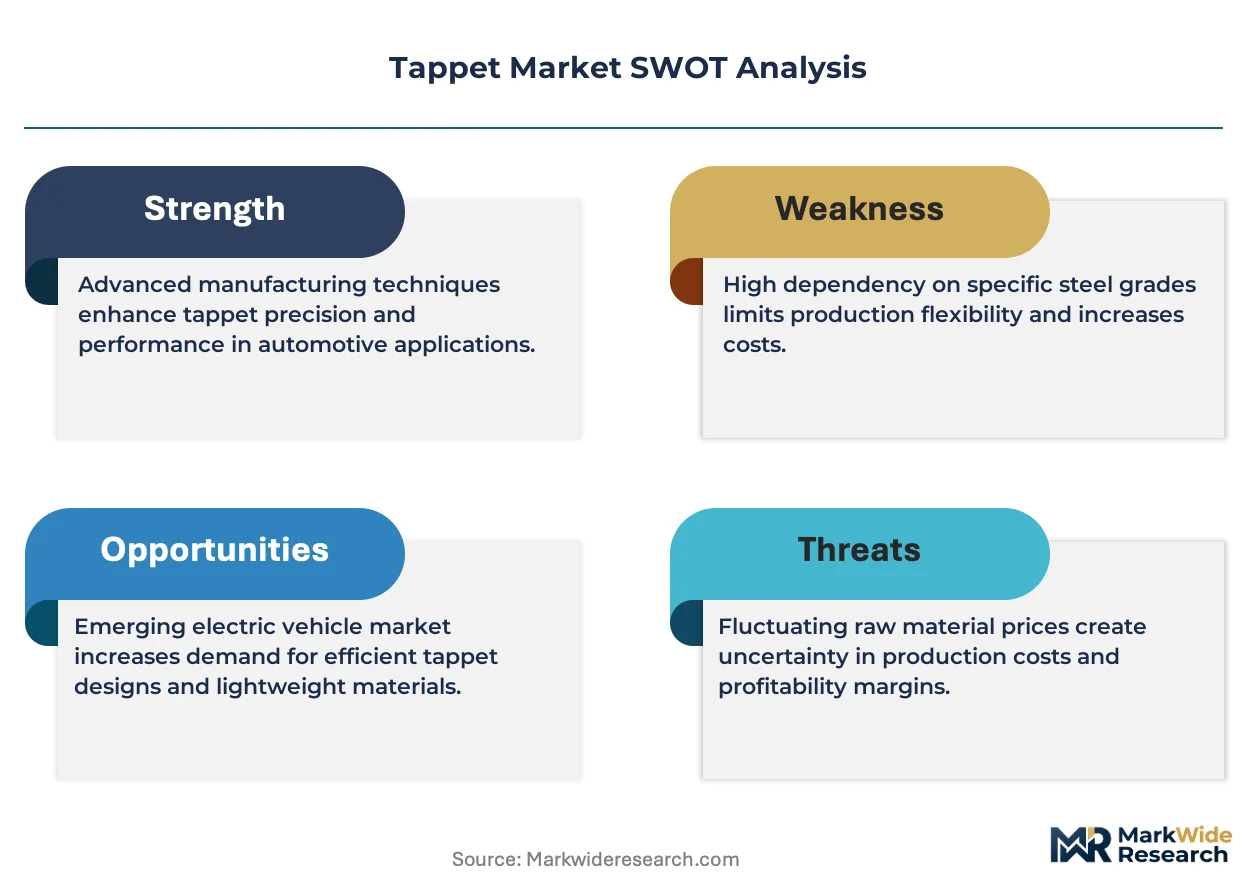
For Market Incumbents: Lock in multi-year maintenance-contract anchoring with European commercial fleets before predictive maintenance software bundling consolidates procurement authority with integrated bearing-tappet portfolios. Add captive surface treatment capacity in carbon-border adjustment exposed jurisdictions to defend margin position against localized content rules. Prioritize roller tappet architecture R&D throughput ahead of flat tappet volume erosion in OEM channels.
For New Entrants and Emerging Players: Direct-to-industrial-operator digital channels offer lowest barrier entry for predictive maintenance software partnerships that bundle tappet supply with condition-monitoring platforms. Target aftermarket flat tappet distributors in Southeast Asia where Bharat Stage VI retrofit economics sustain repair-over-replace demand. Pursue rapid surface treatment certification in India to exploit domestic qualification backlogs.
For Investors and Strategic Acquirers: Consolidation pressure builds where captive heat treatment capacity separates qualified roller tappet suppliers from margin-compressed flat tappet fabricators. Mid-cap specialists with in-house finishing investments and established OEM platform relationships present viable acquisition profiles over a multi-year horizon. Watch EPA Tier 4 and Euro VI durability testing queue lengths as inflection signals for supplier qualification bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat Treatment Investment | Localized finishing capacity secures preferential sourcing under EU Green Deal carbon-intensity disclosure protocols. |
| Predictive Maintenance Software Bundling | Industrial engine operators in Europe reduce unplanned downtime through integrated valve-train condition monitoring. |
| Surface Treatment Certification Acceleration | Indian suppliers bypass qualification backlogs for phosphate coating chemistries under BIS durability testing protocols. |
| Roller Tappet Architecture Conversion | Chinese OEMs meet MIIT fuel-efficiency mandates through low-friction valve-train configurations. |
| Maintenance-Contract Anchoring | Schaeffler Group and SKF lock in multi-year European commercial fleet agreements through integrated portfolios. |
Methodological Framework
Multiple input streams — primary interviews with OEM platform engineers, aftermarket procurement directors, and surface treatment R&D leads; secondary validation through EPA Tier 4 filings, Euro VI durability test records, and MIIT corporate fuel consumption disclosure databases; plus customs trade data for foundry-grade pig iron and through-hardened steel alloys — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including product architecture, material grade, application intensity, and regional regulatory cluster. CAGRs were derived from platform-level procurement volume trajectories and aftermarket replacement cycle analysis. Forecast inputs incorporated EGR thermal stress tolerance limits and surface finish metrology capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for full roller tappet conversion in North American heavy-duty diesel platforms would alter the outlook. Forecasts reflect assumptions about MIIT enforcement timelines and BIS qualification queue resolution. Material deviation in carbon-border adjustment implementation or foundry input cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Automotive Grease Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Odometer Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Mobile Emission Catalysts Market