
 Automotive Heated Seat Market | 2026-2036
Automotive Heated Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Heated Seat Market Analysis
ISO 9001 automotive quality certification is unwinding the supplier base, favoring manufacturers with proven traceability systems. Gentherm leverages its thermal technology portfolio to sustain leadership across North American and European OEM programs. Lear Corporation anchors significant share through its seating division's direct pipeline to Detroit and Stuttgart automakers. Panasonic competes on integrated electronics, combining seat heating with sensor arrays for climate management.
Automotive heated seats embed resistive heating elements—typically carbon fiber or wire-based conductors—within foam and upholstery layers, drawing 12V or 48V electrical current to raise surface temperatures. OEM installation dominates volume, while aftermarket kits capture margin in regions with shorter vehicle replacement cycles. Electric heat sources lead technology adoption, displacing fluid-based systems due to faster response times and simpler packaging. Luxury cars and passenger vehicles concentrate value, though commercial truck specifications are expanding in Nordic and Canadian fleets.
NHTSA enforces flammability resistance under FMVSS 302, while ECE R14 governs seat structural integrity across European type approvals, directly shaping heating element anchoring and wire routing. China's MIIT integrates heated seat energy draw into new energy vehicle efficiency calculations, influencing supplier qualification. Stakeholders must monitor 48V electrical architecture migration and polymer heating film advances that could redraw the competitive map.
Market Dynamics
The migration from 12V to 48V electrical architectures is compressing heating element design cycles and forcing suppliers to recalibrate power density specifications across their product portfolios.
Growth Catalysts
- Premium EV specification in China:Domestic brands including NIO and Li Auto now factory-fit heated seats across mid-tier trims, expanding addressable volume beyond luxury segments.
- ECE R14 anchoring requirements:European type-approval rules for seat structural integrity are standardizing heating element mounting protocols, reducing engineering validation costs for cross-platform programs.
- Carbon fiber conductor maturation:Advanced weaving techniques are improving thermal uniformity and reducing cold spots, enabling thinner foam stacks and weight reduction targets.
Market Restraints
- Copper and nickel price volatility:Resistive wire and terminal connector input costs fluctuate with London Metal Exchange pricing, compressing margin on fixed-price OEM contracts.
- Single-source foam substrate concentration:Two German chemical suppliers control specialized flame-retardant polyurethane formulations, creating vulnerability for tier-two heating element assemblers.
- Fluid-based system residual demand:Some heavy-duty truck fleets in Russia and Central Asia continue specifying coolant-fed seat heating due to extreme cold-start conditions and 24V electrical limitations.
Strategic Opportunities
- India's nascent premium passenger segment:Local assembly of German and Korean luxury models is creating first-mover advantage for suppliers establishing technical centers in Pune and Chennai.
- Climate-zone sensor integration:Convergence of heating elements with occupant detection and humidity sensing enables predictive thermal management, differentiating supplier value propositions.
- MIIT efficiency credit mechanisms:China's Ministry of Industry and Information Technology rewards heated seat energy optimization in corporate average fuel consumption calculations, incentivizing low-draw designs.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-rated expertise for heated seat control modules commands premium salaries, constraining supplier expansion timelines.
- Legacy 12V platform integration:Dual-voltage engineering requirements extend development cycles as OEMs maintain parallel architectures during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Heated Seat Market |
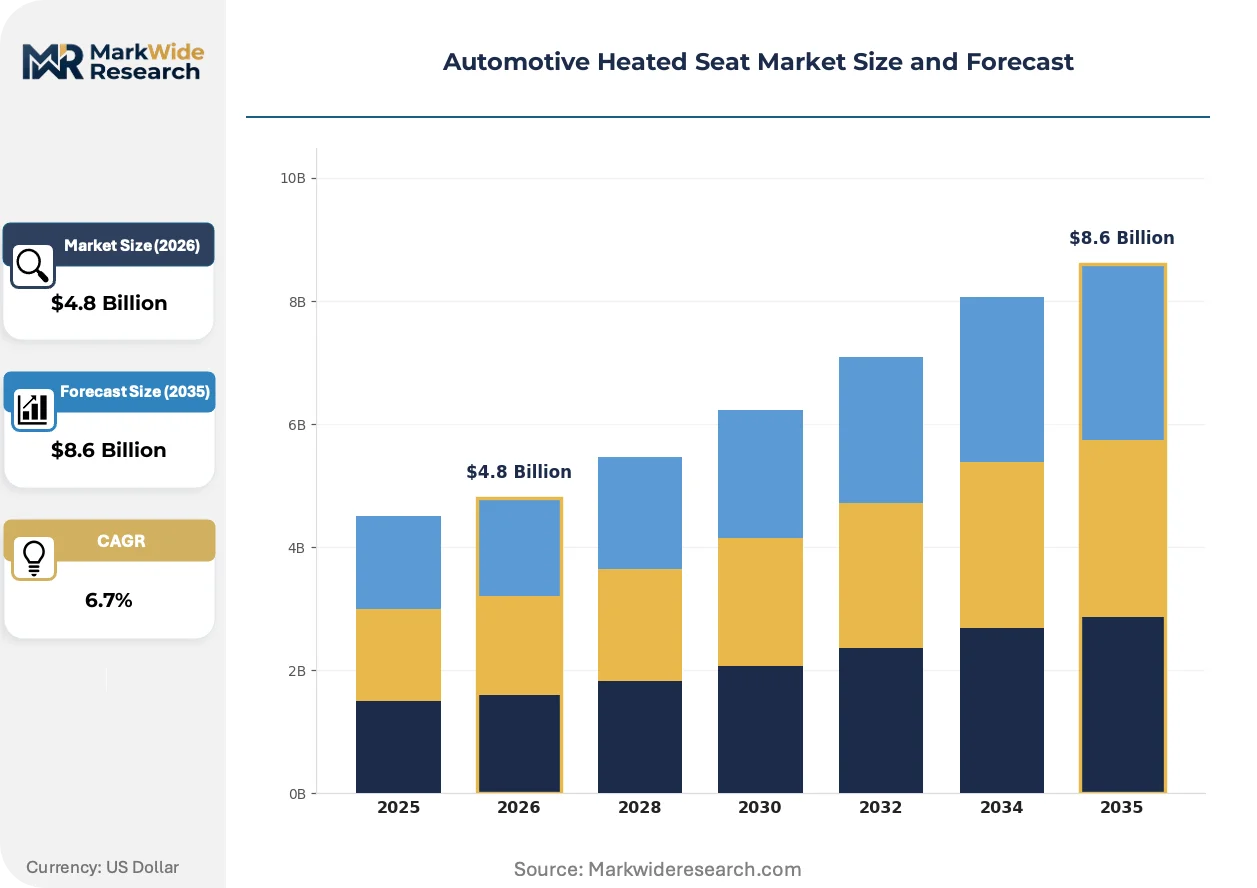
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Systems, Seat Covers, Aftermarket Kits, Customized Solutions Installation Type: OEM, Aftermarket, Retrofitting, Standard Installation Heat Source: Electric, Fluid-Based, Gas, Hybrid End User: Passenger Vehicles, Commercial Trucks, Buses, Luxury Cars |
| Companies Covered | Panasonic, Seat Comfort Systems, Gentherm, Tachibana, Champion, Kongsberg Automotive, Lear Corporation, Golden Time, I.G. Bauerhin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Heated Seat Market Emerging Trajectories
Material science advances and electrical architecture transitions are fragmenting the competitive landscape between incumbent wire-based suppliers and polymer film entrants. Three developments are restructuring supplier positioning and buyer procurement criteria.
Polymer heating film technology is bifurcating the market between traditional wire-woven solutions and printed conductive layers. Korean and Chinese component suppliers are accelerating qualification programs with European luxury OEMs, seeking to displace carbon fiber mats in next-generation seat platforms. The technology's thinner profile enables reduced foam thickness, supporting lightweighting targets while compressing incumbent equipment utilization rates.
REACH substance restrictions on flame retardants are forcing reformulation of polyurethane foam substrates and adhesive bonding agents. German and French regulators are tightening enforcement of SVHC disclosure requirements, extending compliance documentation burdens through tier-three material suppliers. Seat manufacturers serving Stuttgart and Munich OEMs are consolidating supplier panels to reduce traceability audit complexity.
Fleet procurement of heated seats is unbundling from bundled interior packages, enabling line-item specification by rental and corporate buyers. North American fleet managers are negotiating direct supplier relationships for aftermarket retrofits, bypassing traditional dealer channel markups. This disintermediation is most visible in Canadian and Nordic markets where cold-climate functionality drives residual value calculations.
Automotive Heated Seat Market Segmentation
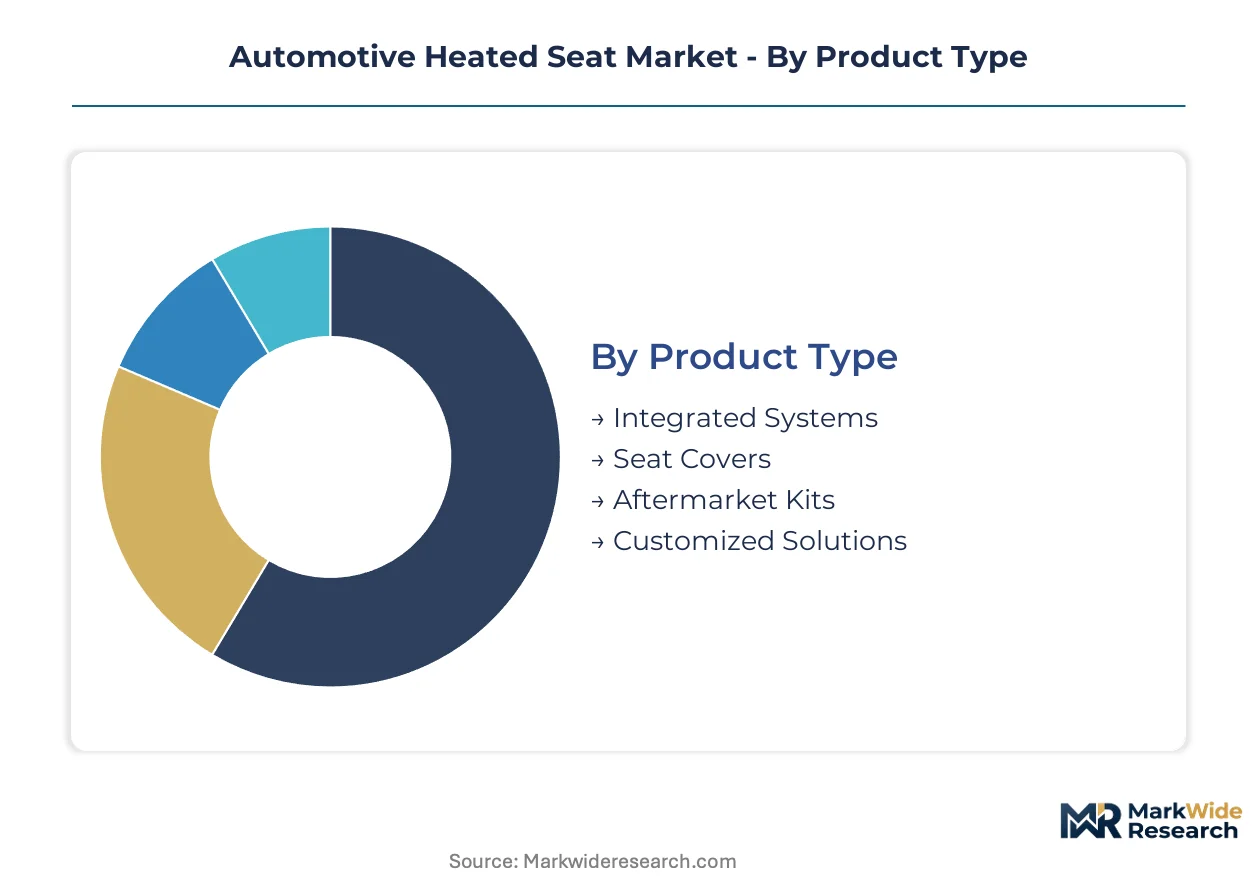
Segmentation in the automotive heated seat market reveals how technology transitions and procurement patterns fragment supplier opportunities across distinct value chains. Understanding these divides exposes where incumbent wire-based suppliers face displacement pressure from polymer film entrants and where aftermarket channels capture margin from OEM-dominated volume.
Product Type:
Integrated systems face the strongest substitution threat as polymer heating film technology enables thinner-profile alternatives that reduce foam stack depth and weight.
- Integrated Systems:Factory-installed heating elements embedded within seat foam and upholstery layers during vehicle assembly. Demand concentrates in German and Japanese luxury OEM programs where NHTSA flammability standards and ECE R14 anchoring requirements drive qualification complexity for tier-one suppliers.
- Seat Covers:Aftermarket slip-on products with embedded heating elements for existing unheated seats. These products capture margin in Canadian and Nordic consumer markets where cold-climate functionality drives residual value calculations and bypasses dealer channel markups.
- Aftermarket Kits:Retrofit heating element packages requiring professional installation into existing seat structures.
- Customized Solutions:Bespoke heating configurations for specialty vehicle applications including ambulances and executive transport.
Integrated systems anchor the volume base while aftermarket kits gain share at the steepest rate as fleet procurement unbundles from bundled interior packages.
Installation Type:
Cost tier differentiation separates premium factory-fit programs from price-sensitive retrofit channels, with margin compression most acute in standard installation commoditization.
- OEM:Direct supply to vehicle manufacturers for factory installation during assembly. OEM programs concentrate in China's premium electric vehicle segment where domestic brands including NIO and Li Auto factory-fit heated seats across mid-tier trims, expanding addressable volume beyond traditional luxury segments.
- Aftermarket:Post-purchase installation through independent channels and retail distribution. North American fleet managers negotiate direct supplier relationships for aftermarket retrofits, particularly in Canadian markets where climate functionality influences resale value.
- Retrofitting:Professional installation of heating elements into vehicles not originally equipped.
- Standard Installation:Basic fitment protocols using universal mounting hardware and simplified wiring harnesses.
OEM installation commands the revenue concentration while aftermarket channels expand most quickly through fleet disintermediation trends.
Heat Source:
Technology maturity curves separate electric dominance from residual fluid-based demand in heavy-duty applications with electrical architecture constraints.
- Electric:Resistive heating elements drawing 12V or 48V current through carbon fiber or wire-based conductors. Electric systems displace fluid-based alternatives due to faster response times and simpler packaging, though the migration from 12V to 48V architectures compresses heating element design cycles and forces power density recalibration.
- Fluid-Based:Coolant-fed heat exchangers integrated with engine thermal management systems. Some heavy-duty truck fleets in Russia and Central Asia continue specifying coolant-fed seat heating due to extreme cold-start conditions and 24V electrical limitations that constrain electric alternatives.
- Gas:Combustion-based heating elements for off-road and remote-operation vehicles.
- Hybrid:Dual-mode systems combining electric and thermal storage approaches.
Electric heat sources anchor the technology base while polymer film variants within this category climb the fastest as Korean and Chinese suppliers accelerate European luxury OEM qualification programs.
End User:
Application-specific requirements fragment engineering specifications between passenger comfort optimization and commercial durability demands.
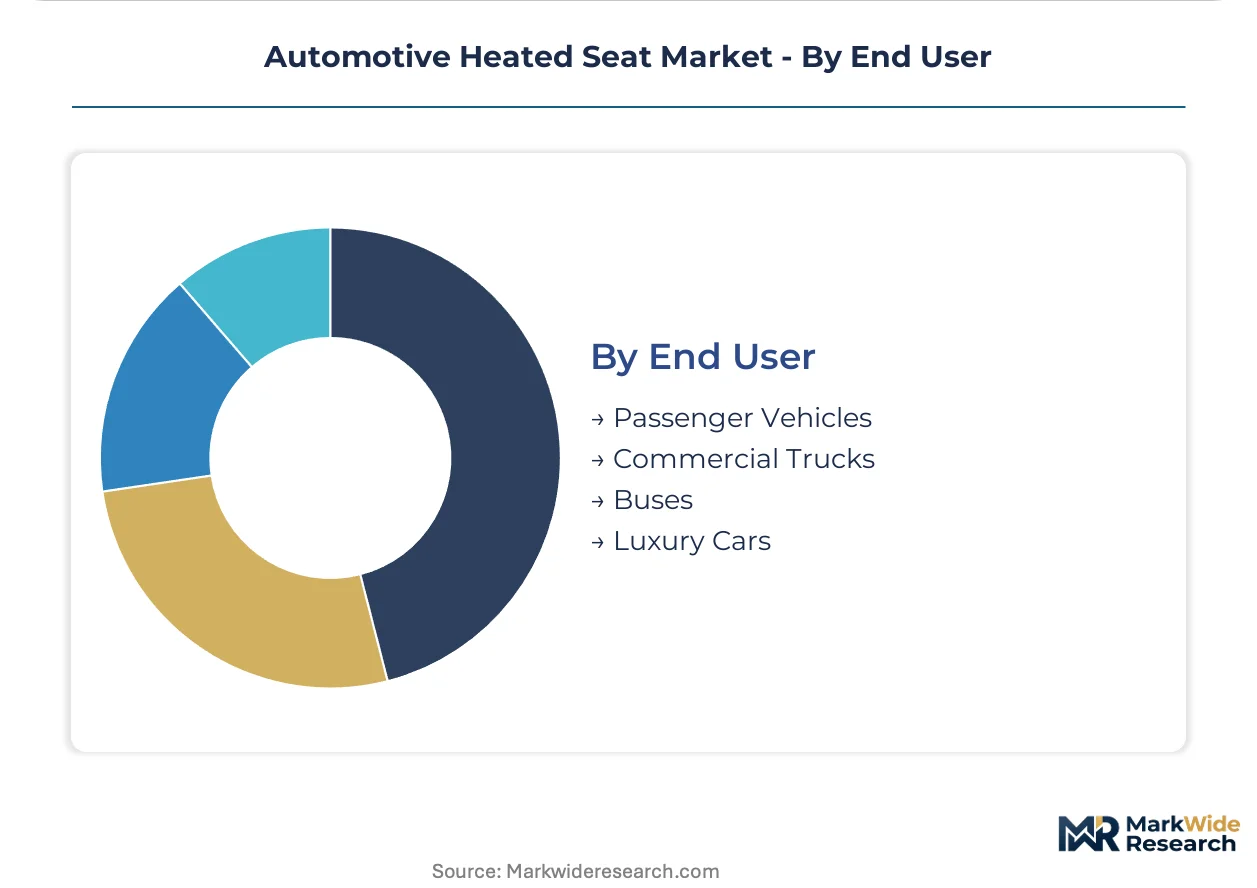
- Passenger Vehicles:Light-duty automotive applications prioritizing occupant comfort and energy efficiency. China's MIIT integrates heated seat energy draw into new energy vehicle efficiency calculations, directly influencing supplier qualification and low-draw design incentives in this segment.
- Luxury Cars:Premium segment vehicles with multi-zone climate integration and sensor arrays. Stuttgart and Munich OEMs consolidate supplier panels to reduce REACH substance restriction traceability audit complexity, favoring manufacturers with proven ISO 9001 certification systems.
- Commercial Trucks:Heavy-duty fleet applications requiring extended operational durability.
- Buses:High-occupancy transit vehicles with centralized heating distribution systems.
Passenger vehicles generate the volume foundation while luxury cars deliver the steepest margin expansion as climate-zone sensor integration enables predictive thermal management differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government efficiency mandates and cold-climate operational requirements are redrawing procurement patterns across major automotive manufacturing bases. MIIT credit mechanisms in China, NHTSA flammability enforcement in the United States, and ECE R14 harmonization in Europe each reshape supplier qualification criteria and factory-fit penetration rates.
China
NIO and Li Auto factory-fit heated seats across mid-tier trims, expanding volume beyond traditional luxury segments. MIIT efficiency credits reward low-draw heating designs in corporate average fuel consumption calculations. Yangtze River Delta suppliers cluster around Shanghai and Suzhou to serve domestic EV brands.
Germany
Stuttgart and Munich OEMs consolidate supplier panels to reduce REACH substance restriction audit complexity. ECE R14 seat anchoring standards standardize heating element mounting protocols across European type approvals. Bavaria's automotive engineering corridor anchors thermal technology development for luxury vehicle programs.
United States
Detroit automakers maintain direct pipeline relationships with seating divisions for factory-fit integration. NHTSA enforces FMVSS 302 flammability resistance standards that shape heating element materials and wire routing specifications. Midwest manufacturing clusters in Michigan and Ohio concentrate tier-one assembly operations.
Japan
Luxury manufacturers expand factory-fit heated seat penetration across domestic and export programs. METI industrial standards influence thermal management system integration with vehicle electronics architectures. Kanto region suppliers around Tokyo coordinate with OEMs on multi-zone climate control development.
Canada
Fleet managers negotiate direct supplier relationships for aftermarket retrofits to maximize cold-climate residual value. Provincial safety regulations align with federal transport standards for heating element installation protocols. Ontario's automotive supplier corridor serves both domestic fleet retrofit demand and cross-border OEM programs.
Automotive Heated Seat Market Vendor Landscape
Player mix skews toward diversified thermal technology specialists with cross-platform OEM relationships. The supplier base concentrates around three tiers: integrated seating system providers, standalone heating element fabricators, and electronics-integrated thermal module developers. Consolidation pressures favor manufacturers with ISO 9001 traceability systems and proven 48V architecture qualification. Dominant competitive moves include strategic partnerships for polymer film technology access and geographic expansion into China's premium EV supply chain.
Among diversified thermal technology specialists, Gentherm and Lear Corporation exemplify the integrated seating system archetype, while Panasonic occupies a position bridging electronics integration with climate management modules. These three companies represent the competitive spectrum from pure-play thermal engineering to diversified automotive component manufacturing, with each anchoring distinct qualification pathways into major OEM programs.
| Leading Market Players |
|---|
| Panasonic |
| Seat Comfort Systems |
| Gentherm |
| Tachibana |
| Champion |
| Kongsberg Automotive |
| Lear Corporation |
| Golden Time |
| I.G. Bauerhin |
| Others |
Supply Flow & Price Mechanics
Factory utilization rates above eighty percent at German and Japanese seating system plants compress margin flexibility for tier-two heating element assemblers, creating asymmetric pricing power that favors integrated OEM suppliers with captive foam substrate access while squeezing standalone component vendors on fixed-price contracts.
Pricing Analysis
Certification level creates the primary spread across the supplier base, with ISO 26262 ASIL-rated modules commanding substantial premiums over uncertified alternatives while REACH-compliant material traceability adds further tiering. Three-tier pricing structure across premium, standard, and economy levels reflects these compliance gradients, with OEM direct programs capturing the premium tier and aftermarket channels absorbing price erosion from copper and nickel volatility on the London Metal Exchange. Fleet procurement managers in Canada exhibit the highest price sensitivity, negotiating direct supplier relationships that bypass dealer markups, whereas Stuttgart and Munich luxury OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Germany and China anchor specialized flame-retardant polyurethane foam production, with two Bavarian chemical suppliers controlling formulations that meet NHTSA FMVSS 302 flammability standards. Carbon fiber conductor weaving and resistive wire drawing feed from South Korean and Japanese precision manufacturing, creating dependency on East Asian thermal material expertise. Single-source foam substrate concentration presents the dominant structural risk, as tier-two assemblers lack alternative qualified suppliers for REACH-compliant substrates. Distribution runs through tier-one seating system integrators for OEM channels, while aftermarket kits reach Canadian and Nordic end-users through direct fleet procurement relationships and independent installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity stems from China's premium EV specification shift, where domestic brands factory-fit heated seats across mid-tier trims—creating supplier niches outside traditional luxury OEM qualification pathways that reward agile entrants with polymer film technology.
For Market Incumbents: Fortify certification moats by accelerating ISO 26262 ASIL-rated control module development before functional safety engineer scarcity worsens, while securing captive supply of REACH-compliant foam substrates through backward integration into German chemical supplier relationships to defend against polymer film displacement. For New Entrants and Emerging Players: CE marking fast-track programs for polymer heating film technology unlock European luxury OEM qualification pathways currently held by carbon fiber mat incumbents, with white-space concentration in India's nascent premium passenger segment where Pune and Chennai technical centers enable first-mover positioning alongside domestic EV supply chain clustering in China's Yangtze River Delta. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-one seating system integrators with direct OEM pipeline relationships, positioning these archetypes for durable cash flow across the 48V architecture transition; acquisition screening should prioritize 48V-qualified thermal module developers with proven traceability systems, with the inflection signal being MIIT efficiency credit mechanism adjustments that reweight heated seat energy draw in corporate average fuel consumption calculations.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Film Technology Qualification | Korean and Chinese suppliers accelerate European luxury OEM penetration, displacing carbon fiber mats. |
| 48V Architecture Migration | Power density recalibration compresses design cycles and consolidates supplier panels around qualified integrators. |
| Climate-Zone Sensor Integration | Predictive thermal management convergence differentiates supplier value propositions in Stuttgart and Munich programs. |
| MIIT Efficiency Credit Optimization | Low-draw heating designs capture corporate average fuel consumption rewards in China's premium EV segment. |
| India Technical Center Establishment | Pune and Chennai engineering presence secures first-mover advantage in local German and Korean luxury assembly. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership operations specialists converged on the working assumptions, with secondary validation drawing from vehicle production databases, IHS Markit registration data, NHTSA FMVSS compliance filings, and ECE type-approval records; bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include vehicle class, propulsion architecture, heat source technology, installation type, and regional production cluster, with CAGRs derived from trend extrapolation of factory-fit penetration rates and aftermarket retrofit intensity; forecast inputs incorporated MIIT efficiency credit mechanism evolution and 48V electrical architecture migration timelines without specifying transition years.
Decision-makers should treat outputs as directional under assumptions of stable NHTSA flammability enforcement and ECE R14 harmonization; material deviation in copper and nickel price volatility or REACH substance restriction expansion would warrant model refresh, with recalibration cycles aligning with material shifts in electrical architecture standards and polymer film qualification milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Automotive Fabric Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market