
 Automotive in-Vehicle Air Purifier Market | 2026-2036
Automotive in-Vehicle Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive in-Vehicle Air Purifier Market Analysis
ISO 16890 air filter certification is redrawing competitive boundaries for component suppliers seeking OEM qualification. MANN+HUMMEL leverages its filtration R&D depth to sustain dual certification across automotive and building HVAC standards. DENSO Corporation anchors its position through captive integration with climate control modules, while Panasonic Corporation differentiates via proprietary nanoe ionization technology bundled with its cabin comfort systems.
An automotive in-vehicle air purifier is a cabin-integrated or portable air treatment device designed to remove particulate matter, volatile organic compounds, and biological contaminants from enclosed vehicle interiors, typically achieving PM2.5 capture efficiencies exceeding 99.97% through multi-stage media stacks combining HEPA filtration with activated carbon adsorption layers. HEPA filters dominate value capture due to mandatory OEM specification for premium vehicle platforms, while ionic purifiers represent the fastest-expanding technology segment as Chinese EV producers adopt plasma cluster discharge modules to neutralize cabin pathogens without filter replacement burdens. Photocatalytic systems remain niche but command margin premiums in aftermarket retrofit channels targeting ride-hail fleet operators.
The US EPA sets ambient air quality benchmarks that cascade into NHTSA cabin safety consultations, while China's MEE enforces GB standards that directly mandate in-cabin PM2.5 monitoring displays on new energy vehicles. REACH compliance in Europe restricts certain activated carbon feedstocks, compelling suppliers to requalify supply chains for coconut-shell and synthetic polymer alternatives. Stakeholders must monitor divergence between regional certification regimes to avoid platform engineering redundancy across export markets.
Market Dynamics
China's GB/T 27630 cabin air quality standard and tightening European F-Gas Regulation are forcing simultaneous HVAC architecture redesigns across export-bound vehicle platforms, compressing supplier qualification timelines while expanding addressable filter-integrated system volumes.
Growth Catalysts
- HEPA-grade mandates:Domestic EV manufacturers in China's Yangtze River Delta automotive cluster now specify high-efficiency cabin filtration as standard equipment, normalizing premium air purification across mass-market price tiers.
- F-Gas Regulation pressure:Europe's tightening restrictions on refrigerant-based climate systems accelerate filter-integrated HVAC module development, creating specification pull-through for compliant purification components.
- Plasma cluster discharge:Chinese EV producers adopt ionic neutralization modules to eliminate pathogen loads without consumable filter replacement, reducing total cost of ownership for fleet operators.
Market Restraints
- Activated carbon feedstock volatility:REACH compliance in Europe restricts traditional carbon sources, compelling requalification of supply chains around coconut-shell and synthetic polymer alternatives at elevated input costs.
- Certification fragmentation:Divergence between ISO 16890 automotive HVAC standards and regional building ventilation regimes forces redundant engineering for suppliers serving dual end-markets.
- Filter replacement economics:HEPA media stacks require periodic servicing that conflicts with extended EV service intervals, creating aftermarket friction for OEM-integrated systems.
Strategic Opportunities
- Ride-hail fleet retrofit:Photocatalytic aftermarket systems command margin premiums among commercial vehicle operators seeking cabin pathogen mitigation without OEM platform dependence.
- Dual certification leverage:Component suppliers achieving simultaneous ISO 16890 automotive and building HVAC qualification access expanded specification pools across mobility and infrastructure verticals.
- MEE display mandates:China's Ministry of Ecology and Environment requirements for in-cabin PM2.5 monitoring displays on new energy vehicles create bundled sensor-purifier integration opportunities.
Industry Challenges
- Multi-regime engineering redundancy:Platform teams must maintain parallel certification documentation for EPA ambient benchmarks, GB standards, and REACH substance restrictions without common technical baselines.
- Integration complexity:Legacy climate control architectures resist seamless incorporation of nanoe ionization and plasma discharge modules without substantial controller software revision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive in-Vehicle Air Purifier Market |
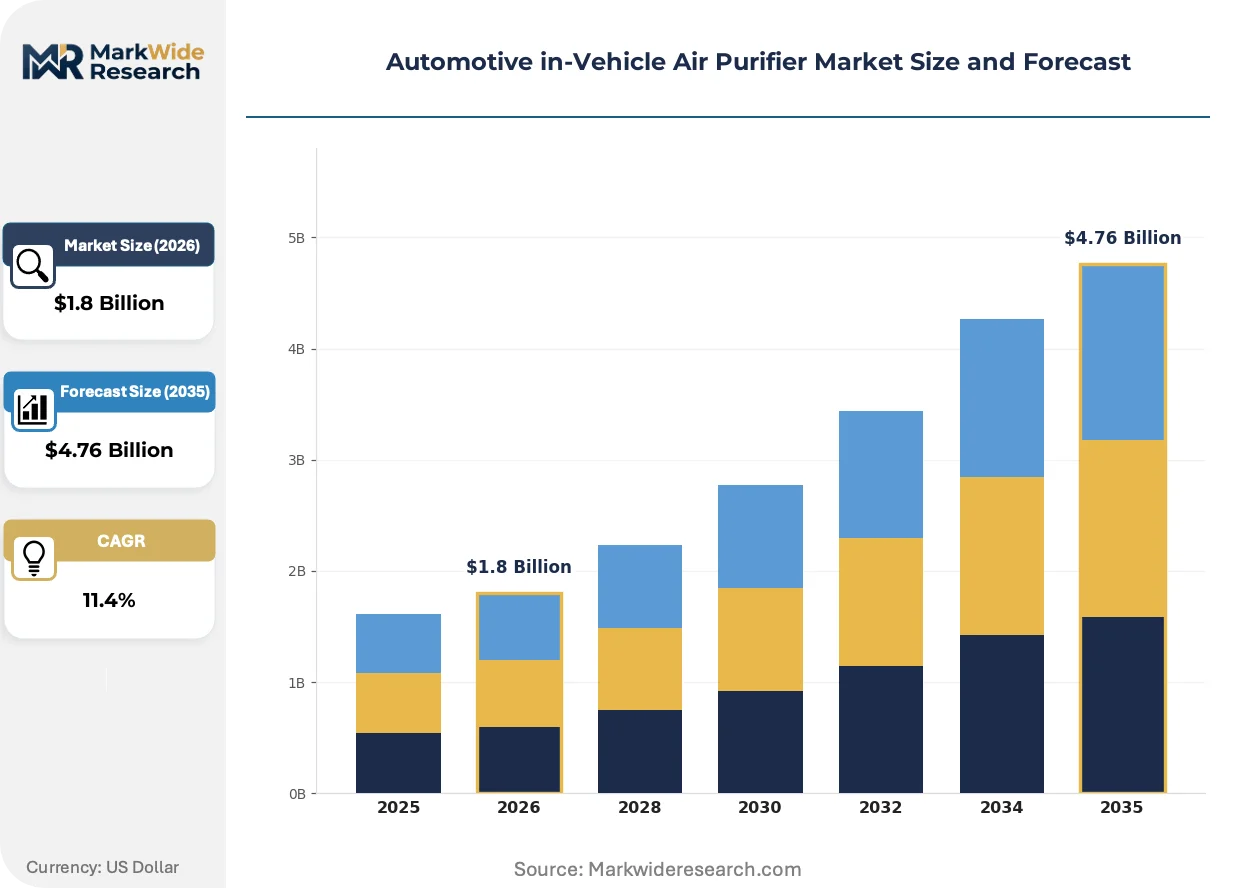
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon, Ionic Purifiers, UV-C Purifiers Technology: Filtration, Photocatalytic, Ionization, Electrostatic End User: OEMs, Aftermarket Providers, Fleets, Private Vehicle Owners Installation Type: Built-in, Portable, Retrofit Solutions, Integrated Systems |
| Companies Covered | Honeywell International Inc., DENSO Corporation, 3M, Panasonic Corporation, Sharp Corporation, Koninklijke Philips N.V., Eureka Forbes, MANN+HUMMEL, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive in-Vehicle Air Purifier Market Emerging Trajectories
Convergence between cabin comfort systems and health-monitoring sensors is dissolving traditional boundaries between HVAC hardware and interior electronics, creating new specification categories that bundle air treatment with environmental data visibility.
Multi-stage media stacks combining HEPA filtration with activated carbon adsorption layers are decomposing the historical separation between particulate capture and volatile organic compound management. Luxury passenger vehicle OEMs specify these integrated configurations to differentiate cabin experience. The technology is decomposing standalone purifier categories into unified climate control modules.
Europe's F-Gas Regulation on refrigerant-based climate systems is compelling HVAC suppliers to redesign thermal management architectures around filter-integrated approaches. This regulatory pressure cascades into expanded specification opportunities for purification component manufacturers. Premium vehicle platforms in Germany and France are responding with accelerated supplier qualification timelines for compliant system variants.
Fleet procurement patterns among commercial ride-hail operators are compressing replacement cycles for cabin air treatment components. These buyers now unbundle after-sales service from initial equipment supply, favoring modular purifier designs with field-serviceable media stacks. This shift is most visible in urban China where platform economics dominate vehicle utilization rates.
Automotive in-Vehicle Air Purifier Market Segmentation
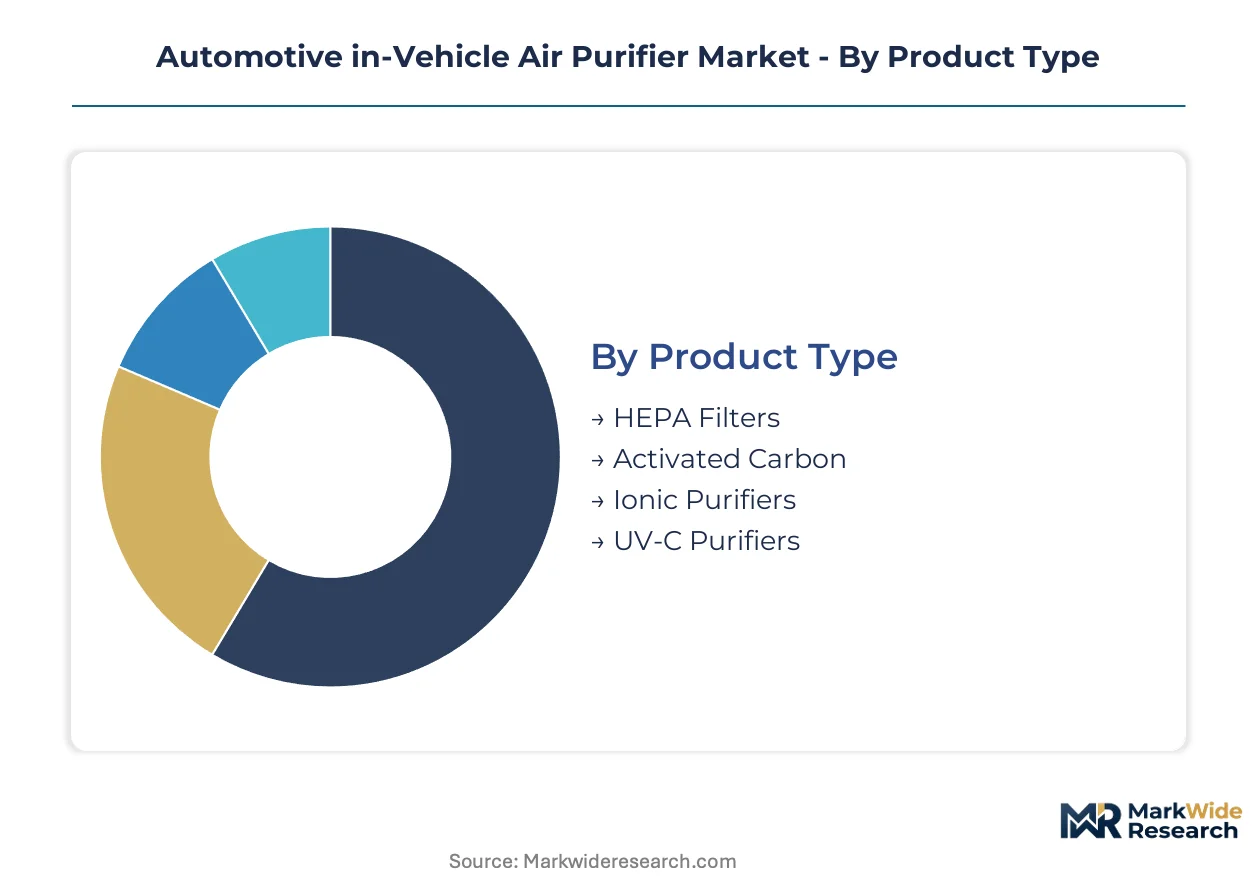
Segmentation in automotive cabin air purification reveals how specification authority flows from factory-fit mandates through aftermarket retrofit channels. Channel mix varies sharply by product maturity and regulatory pressure intensity.
Product Type:
Factory-fit channels concentrate specification authority around HEPA and activated carbon media, while aftermarket and fleet procurement gravitates toward ionic and UV-C alternatives with lower lifecycle service burdens.
- HEPA Filters:Multi-layer fibrous media achieving 99.97% PM0.3 capture efficiency through mechanical interception, impaction, and diffusion mechanisms. Demand concentrates in China's Yangtze River Delta EV manufacturing cluster, where GB/T 27630 compliance mandates factory-fit HEPA integration as standard equipment across mass-market vehicle tiers.
- Activated Carbon:Porous carbonaceous substrates with high surface area for VOC and odor adsorption, typically laminated to HEPA substrates in multi-stage configurations. European OEMs specify coconut-shell derived grades to satisfy REACH substance restrictions, compressing supplier qualification timelines for compliant feedstock alternatives.
- Ionic Purifiers:Plasma cluster discharge modules generating bipolar ions for pathogen neutralization without consumable media replacement.
- UV-C Purifiers:Germicidal ultraviolet emitters targeting biological contaminant inactivation, primarily specified in aftermarket retrofit channels for commercial fleet operators.
By volume, HEPA Filters lead. By growth pace, Ionic Purifiers are expanding most quickly.
Technology:
Cost tier stratification separates mature filtration approaches from emerging electrochemical and photocatalytic methods commanding margin premiums in premium vehicle platforms.
- Filtration:Physical media-based particulate capture using fibrous mats, membranes, or granular beds. OEMs in Germany and France specify ISO 16890-certified configurations to satisfy tightening F-Gas Regulation compliance requirements for integrated HVAC modules.
- Photocatalytic:Titanium dioxide catalysts activated by UV illumination to generate reactive oxygen species for VOC oxidation. Ride-hail fleet operators in urban China procure aftermarket photocatalytic retrofits to mitigate pathogen transmission risks without OEM platform dependence.
- Ionization:Bipolar ion generation for airborne contaminant neutralization through charge aggregation and precipitation.
- Electrostatic:Charged collection surfaces attracting oppositely charged particulate matter with minimal pressure drop penalties.
Filtration dominates unit shipments. Photocatalytic commands the steepest expansion trajectory among emerging technologies.
End User:
Customer type determines specification authority concentration, with OEMs controlling upstream design integration and fleets driving modular aftermarket procurement patterns.
- OEMs:Original equipment manufacturers integrating purification modules during vehicle assembly, specifying HEPA-activated carbon stacks for climate control module suppliers. China's domestic EV producers now mandate cabin PM2.5 monitoring displays per MEE requirements, bundling sensor-purifier integration into platform architectures.
- Fleets:Commercial vehicle operators unbundling after-sales service from initial equipment supply, favoring field-serviceable modular designs with compressed replacement cycles. Platform economics in China's ride-hail markets dominate utilization rates and procurement specifications.
- Aftermarket Providers:Independent distributors and installers serving retail replacement and upgrade demand.
- Private Vehicle Owners:Individual consumers purchasing portable or retrofit solutions through retail channels.
OEMs anchor value capture. Fleets are gaining share fastest as commercial mobility platforms expand.
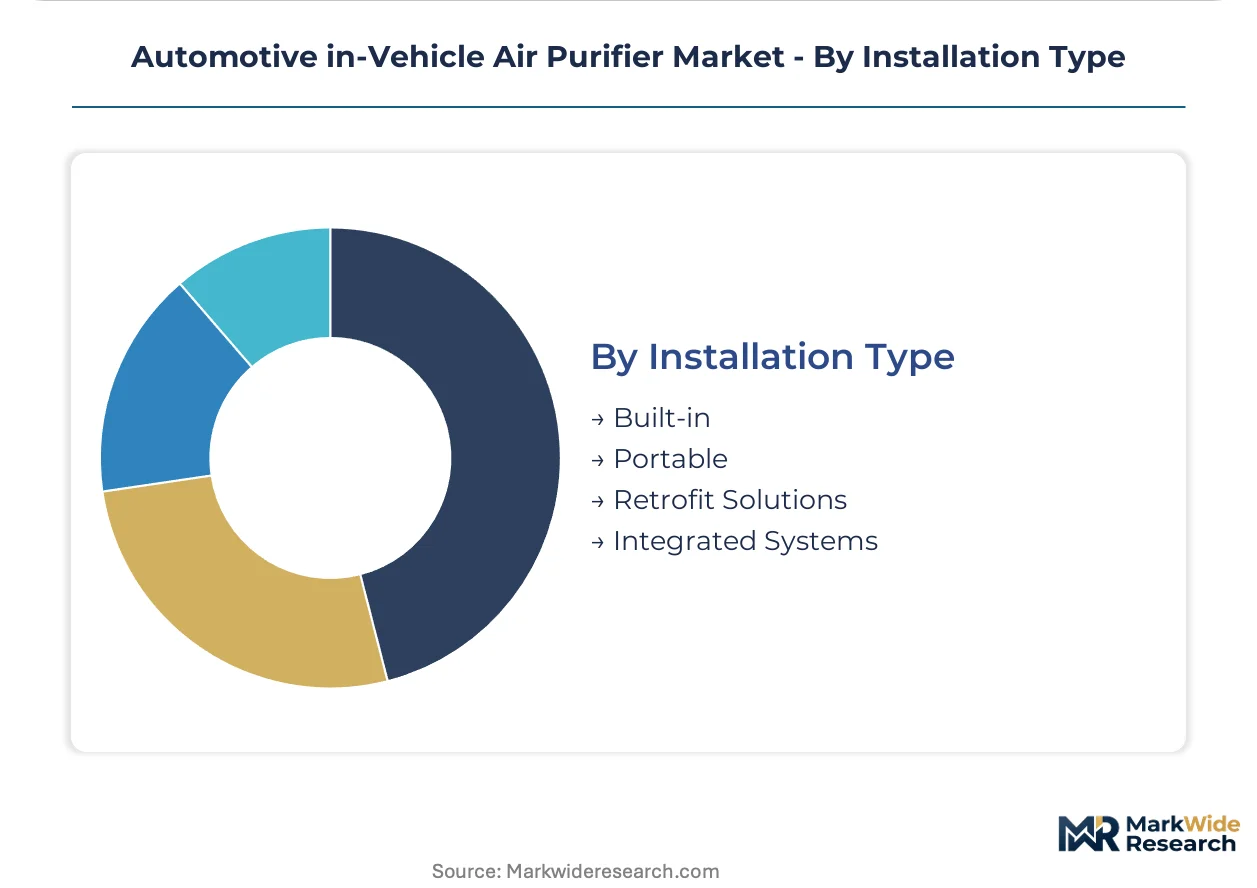
Installation Type:
Supply concentration in integrated climate control module manufacturing favors built-in and integrated system specifications over portable alternatives.
- Built-in:Factory-integrated purification hardware embedded within dashboard or console structures during vehicle assembly. DENSO Corporation and climate control specialists supply these configurations to German and French premium vehicle platforms responding to accelerated F-Gas Regulation compliance timelines.
- Integrated Systems:Purification functionality unified with HVAC thermal management and sensor networks through common controller architectures. China's GB standards for in-cabin air quality monitoring drive bundled specification of sensor-purifier-controller integration in Yangtze River Delta EV production.
- Portable:Self-contained plug-in units for 12V or USB power operation, positioned in cup holders or seat-back locations.
- Retrofit Solutions:Aftermarket hardware adapting legacy vehicles without factory purification capability.
Integrated Systems lead by specification value. Portable alternatives climb fastest in aftermarket channels serving vehicle parc extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB/T 27630 cabin air quality standard and Europe's F-Gas Regulation are compressing supplier qualification timelines across export-bound vehicle platforms, forcing parallel engineering for multi-regime compliance.
China
Domestic EV manufacturers in the Yangtze River Delta automotive cluster specify HEPA-grade cabin filtration as standard equipment across mass-market tiers. The Ministry of Ecology and Environment mandates in-cabin PM2.5 monitoring displays on new energy vehicles, bundling sensor-purifier integration into platform architectures. Shanghai and Suzhou host concentrated EV production where factory-fit purification now differentiates cabin experience.
Germany
Premium vehicle OEMs in Bavaria and Baden-Württemberg accelerate supplier qualification timelines for F-Gas Regulation-compliant HVAC modules. The KBA enforces refrigerant restrictions that cascade into filter-integrated thermal management redesigns. Stuttgart's automotive engineering cluster drives ISO 16890 certification requirements for climate control component suppliers.
United States
The EPA's ambient air quality benchmarks inform NHTSA cabin safety consultations, creating specification pressure for particulate capture efficiency. Michigan and Ohio-based OEM engineering centers integrate purification modules into domestic platform architectures. Detroit's supplier ecosystem adapts to dual certification demands spanning automotive and building HVAC standards.
Japan
METI guidelines on vehicle interior environmental quality support adoption of ionization technologies for pathogen neutralization. Nagoya's automotive manufacturing corridor specializes in plasma cluster discharge modules for export-bound vehicles. Toyota City suppliers develop nanoe ionization systems bundled with climate control modules for premium platforms.
South Korea
Seoul Capital Area EV producers specify cabin air quality monitoring as competitive differentiation against Chinese imports. The MFDS influences interior material emissions standards that indirectly pressure purification system integration. Gyeonggi Province hosts concentrated battery-electric vehicle manufacturing where HEPA specification now spans mid-market price tiers.
Automotive in-Vehicle Air Purifier Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive climate control divisions, creating tiered competition between integrated system suppliers and specialized filtration component manufacturers. Tier-one automotive suppliers anchor the premium specification segment through HVAC module integration, while independent filter specialists compete on media certification breadth. Two strategic archetypes dominate: climate control integrators bundling purification with thermal management, and filtration specialists pursuing dual automotive-building certification. Competitive moves concentrate on strategic partnerships for sensor-purifier bundling and geographic expansion into China's Yangtze River Delta EV manufacturing cluster.
Among diversified industrial conglomerates, Honeywell International Inc. and DENSO Corporation exemplify the climate control integration archetype, leveraging captive HVAC module relationships to secure factory-fit specification. MANN+HUMMEL occupies a position representing the filtration specialist tier, sustaining dual certification across automotive and building ventilation standards to access expanded specification pools. Panasonic Corporation anchors the ionization technology vector, differentiating through proprietary approaches bundled with cabin comfort systems.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| DENSO Corporation |
| 3M |
| Panasonic Corporation |
| Sharp Corporation |
| Koninklijke Philips N.V. |
| Eureka Forbes |
| MANN+HUMMEL |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at China's Yangtze River Delta HEPA media manufacturing plants shapes both supplier concentration and price floors for cabin filtration components. Scale advantages among integrated climate control module producers compress margins for independent filter specialists while elevating barriers for new qualification cycles.
Pricing Analysis
Certification level (ISO 16890-grade versus uncertified aftermarket) creates the primary spread between premium factory-fit and economy retrofit tiers. Three-tier pricing structure across premium, standard, and economy levels reflects bundling with HVAC modules versus standalone media replacement. Cost compression in the standard tier is intensifying because Chinese EV producers mandate HEPA specification across mass-market price points. Fleet operators exhibit highest price sensitivity due to compressed replacement cycles, while luxury OEMs prioritize certification breadth over unit cost.
Supply Chain Analysis
China and Germany anchor HEPA media and climate control module production respectively, with South Korea supplying specialized ionization components. Coconut-shell activated carbon feedstock draws from Southeast Asian processing centers, while synthetic polymer alternatives rest on petrochemical supply chains. Single-source vulnerability concentrates in REACH-compliant carbon substrates following European feedstock restrictions. Distribution runs through captive Tier 1 supplier networks into OEM assembly plants, with aftermarket channels fragmenting across e-commerce and fleet service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation among China's ride-hail platforms shifts buyer power upstream, compressing supplier margins while elevating specification authority for modular, field-serviceable designs.
For Market Incumbents: Secure dual ISO 16890 certification across automotive and building HVAC standards to access expanded specification pools beyond factory-fit channels. Deepen backward integration into synthetic activated carbon production to insulate against REACH-driven feedstock volatility. Prioritize sensor-purifier bundling capabilities to capture China's MEE display mandate specifications before platform standardization locks out modular competitors. For New Entrants and Emerging Players: Aftermarket photocatalytic retrofit gaps among commercial fleet operators in urban China offer the most penetrable entry vector. Target ride-hail procurement teams with subscription-based service models that unbundle equipment from consumable replacement. Lead with pathogen-neutralization efficacy data to differentiate against incumbent HEPA-centric positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors filtration specialists with captive certification infrastructure over climate control generalists facing software-defined vehicle displacement. Long-term viability hinges on sensor integration capabilities and geographic exposure to China's EV production cluster. Monitor F-Gas Regulation compliance timelines as inflection indicator for European HVAC module redesign cycles and associated supplier qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | ISO 16890 qualification across automotive and building HVAC standards expands addressable specification pools. |
| Sensor-Purifier Integration | China's MEE PM2.5 display mandates create bundled hardware opportunities for climate control suppliers. |
| Synthetic Carbon Feedstock Qualification | REACH-compliant coconut-shell and polymer alternatives secure European OEM qualification timelines. |
| Plasma Cluster Module Development | Chinese EV producer adoption of ionic neutralization drives fastest-expanding technology segment capture. |
| Fleet Service Network Expansion | Ride-hail platform economics favor modular designs with compressed replacement cycles in urban China. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet operations managers anchored the qualitative base. Primary interviews triangulated against vehicle production databases, IHS Markit registration data, customs filtration import records, and SEC supplier filings. Bottom-up segment sizing across product type, technology, end user, and installation type dimensions converged with top-down market validation.
Sensitivity analysis tested volume and value outputs across the projection horizon against regulatory acceleration scenarios and feedstock price volatility assumptions. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from fitted growth curves incorporating technology substitution rates and mandate implementation timelines. Industry-specific inputs encompassed GB/T 27630 compliance penetration curves and F-Gas Regulation redesign cycle schedules.
Underlying assumptions cover regulatory implementation pace, feedstock substitution elasticity, and EV platform standardization trajectories, with deviation risk concentrated in REACH substance restriction expansion and sensor-purifier bundling adoption rates. Recalibration cycles align with material shifts in Chinese EV production volumes and European HVAC module qualification windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market
Automotive Interior & Exterior
Automotive 3D Surface Display Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Automotive Heat Shield Market