
 Passenger Vehicle Dashboard Camera Market | 2026-2036
Passenger Vehicle Dashboard Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Vehicle Dashboard Camera Market Analysis
4K resolution capture is unwinding the low-definition legacy installed base across the passenger vehicle dashboard camera category. Nextbase leverages its UK retail presence to sustain premium positioning in dual-channel configurations. Viofo competes on raw specification density, anchoring enthusiast demand with superior sensor performance at mid-market price points. Garmin differentiates through integrated GPS logging and driver awareness alerts, occupying the safety-conscious consumer segment.
A passenger vehicle dashboard camera is a windshield-mounted digital video recorder engineered with CMOS image sensors, loop recording firmware, and G-force collision detection algorithms, designed to capture continuous forward-facing and cabin footage for accident reconstruction and insurance documentation. Dual-channel systems lead product type demand as consumers prioritize simultaneous front and rear coverage, while cloud-enabled connectivity represents the fastest-growing attachment as real-time upload and remote access shift from fleet-only to retail adoption. OEM integrated solutions command the highest margin pools due to vehicle warranty alignment and factory calibration requirements.
The US National Highway Traffic Safety Administration and the European Union's General Safety Regulation shape product standards by mandating event data recording and driver monitoring capabilities in new vehicle categories, directly expanding addressable hardware demand. China's Ministry of Industry and Information Technology enforces GB standards for electromagnetic compatibility and imaging quality, creating compliance barriers for uncertified imports. The EU AI Act introduces algorithmic transparency requirements for dashcam systems employing facial recognition or behavioral analysis. Stakeholders must monitor divergent certification timelines across Washington, Brussels, and Beijing to align product roadmaps with market entry requirements.
Market Dynamics
The transition from standalone aftermarket devices to embedded OEM systems is compressing hardware margins while elevating software and calibration revenue pools across the passenger vehicle dashboard camera value chain.
Growth Catalysts
- EU General Safety Regulation:Mandates event data recorders and driver monitoring in new vehicle categories, directly expanding factory-fit camera demand across member states.
- Video telematics in fleet management:Commercial operators in the United States are adopting dual-channel systems to reduce liability exposure and negotiate lower insurance premiums.
- CMOS sensor advancement:Improved low-light sensitivity and HDR processing are enabling reliable capture without supplemental illumination, expanding usable hours per device.
Market Restraints
- Memory semiconductor volatility:NAND flash pricing swings directly impact bill-of-materials stability for 4K-capable recorders.
- Chinese supply concentration:Image sensor packaging and lens module assembly cluster in Guangdong and Jiangsu provinces, creating geographic risk exposure.
- Privacy regulation fragmentation:Divergent consent requirements for cabin-facing cameras across Germany, France, and California complicate product standardization.
Strategic Opportunities
- India passenger vehicle market:Low dashcam penetration in the world's fourth-largest automotive market creates first-mover positioning for localized distribution partnerships.
- ADAS convergence:Integration of dashcam footage with lane-keeping and collision-warning algorithms creates bundled value propositions for Tier 1 suppliers.
- Usage-based insurance channels:Telematics data exchange agreements with underwriters in the United Kingdom and South Korea are opening B2B2C distribution paths.
Industry Challenges
- Firmware security certification:EU Cyber Resilience Act requirements for connected devices are extending development timelines and testing costs.
- Thermal management in compact form factors:4K recording at 60 frames per second generates heat loads that challenge sealed automotive-grade enclosures.
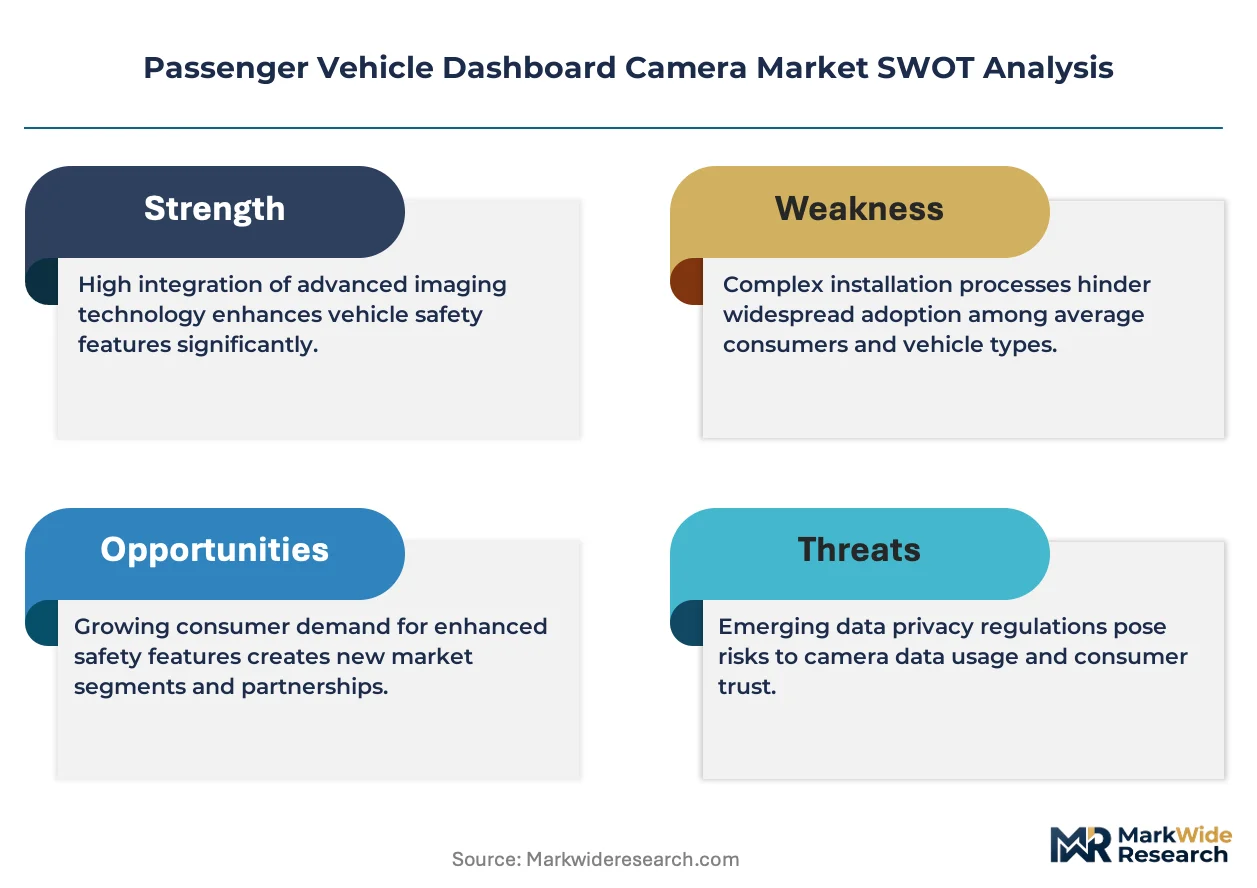
- Legacy vehicle integration:Retrofit installation complexity in older electrical architectures limits aftermarket expansion in aging vehicle populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Vehicle Dashboard Camera Market |
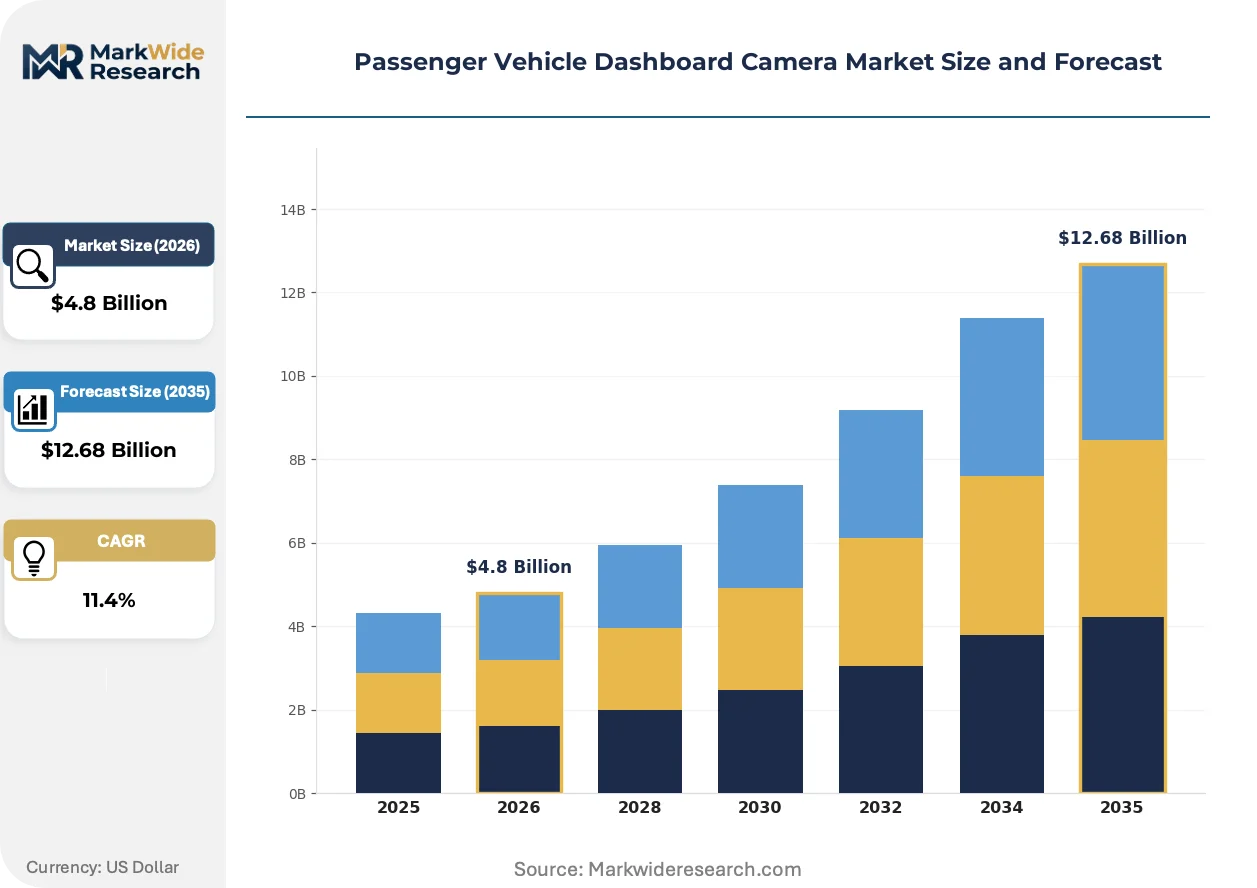
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front-facing, Dual-channel, Rearview, 360-degree Integration Level: Standalone, OEM Integrated, Aftermarket Add-on, Fleet Solutions Connectivity: Bluetooth, Wi-Fi, USB, Cloud-enabled End User: Individual Consumers, Commercial Fleets, Insurance Companies, Rental Services |
| Companies Covered | BlackVue, Garmin, Viofo, Nextbase, 70mai, Samsara, Vantrue, Thinkware, Verizon Connect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Vehicle Dashboard Camera Market Emerging Trajectories
Resolution escalation and connectivity integration are redefining hardware specifications while regulatory mandates accelerate the shift from consumer electronics to automotive-grade systems.
AI-powered incident detection is supplanting simple G-force triggers as the primary collision identification method. Fleet operators and safety-conscious consumers are adopting neural-network-based analysis that distinguishes genuine impacts from road vibrations and speed bumps. This capability is compressing false-positive rates and reducing storage waste, enabling longer effective retention periods without proportional memory expansion.
China's GB standards for electromagnetic compatibility and imaging quality are tightening certification requirements for both domestic and imported devices. Manufacturers must demonstrate resistance to automotive electrical noise and consistent performance across temperature extremes. European and North American suppliers are responding by establishing in-country testing facilities and partnering with MIIT-recognized laboratories to accelerate market entry.
Direct-to-consumer e-commerce platforms are capturing share from traditional automotive retail channels in volume markets. Chinese domestic brands leverage live-streaming commerce and short-video marketing to bypass distributor margins and build brand recognition. This channel shift is most visible in Southeast Asian markets where mobile-first purchasing behavior and price sensitivity favor digitally native vendors over established retail networks.
Passenger Vehicle Dashboard Camera Market Segmentation
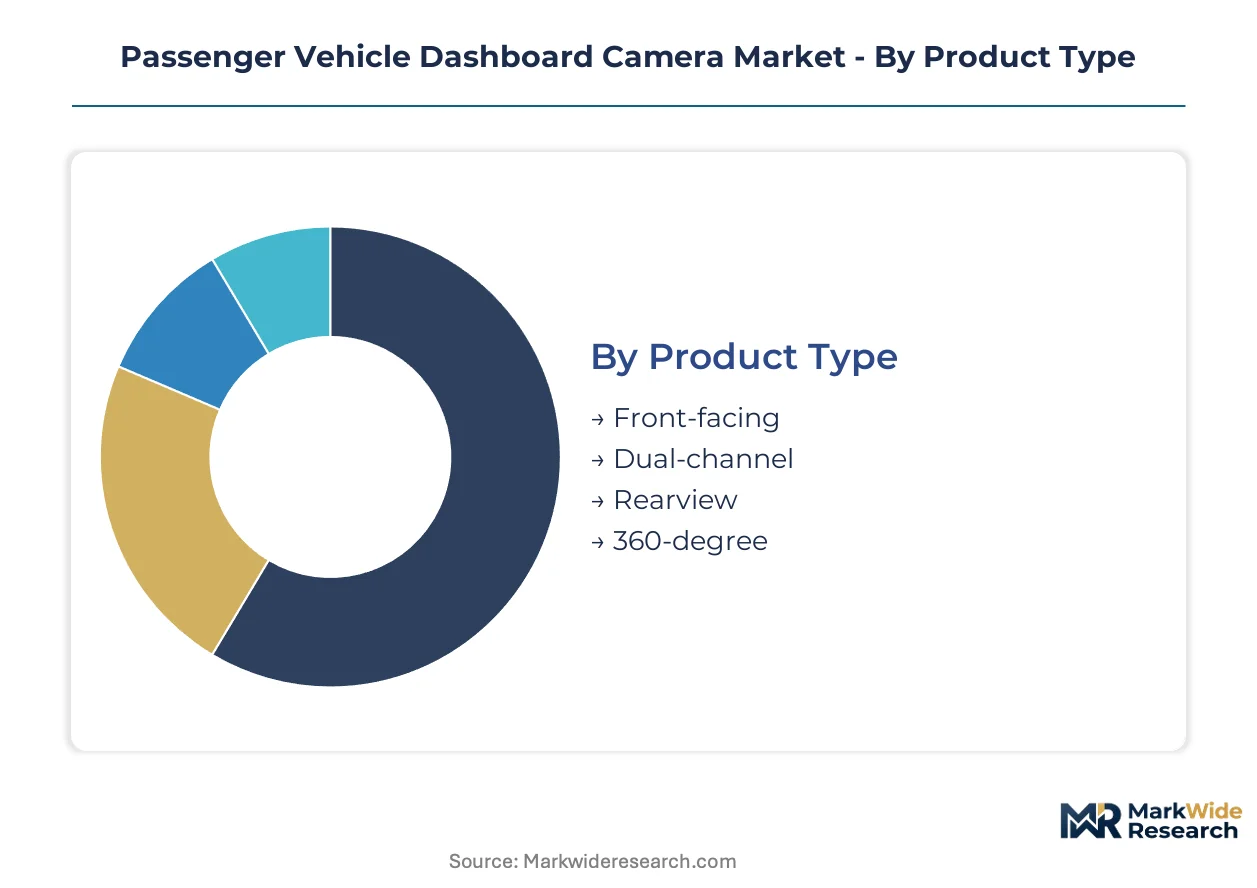
Passenger vehicle dashboard camera segmentation reveals where hardware commoditization pressures concentrate and where software-enabled differentiation creates defensible margin pools. Understanding these fault lines guides portfolio allocation between volume segments and premium tiers.
Product Type:
Dual-channel systems face the strongest substitution pressure from single-channel alternatives as consumers weigh incremental cost against perceived rear-coverage value, while 360-degree configurations threaten to collapse front-facing and rearview segments into unified capture platforms.
- Dual-channel:Simultaneous front and rear recording via discrete CMOS sensors with synchronized timestamping. Demand concentrates among safety-conscious private owners in Germany and the United Kingdom where insurers offer premium discounts for comprehensive coverage documentation. CMOS sensor advancement enabling reliable low-light rear capture without supplemental IR illumination reinforces this segment's value proposition against single-channel alternatives.
- Front-facing:Single forward-mounted recorder with loop recording and G-force collision detection. Cost-sensitive consumers in India and Southeast Asia drive volume through e-commerce platforms where sub-$50 pricing anchors mass-market penetration. This segment faces margin compression as smartphone dashcam apps and OEM-integrated basic recorders erode standalone aftermarket relevance.
- Rearview:Dedicated rear-window or license-plate-mounted recorder, often sold as add-on to front-facing systems. Commercial fleet operators in the United States specify these for liability protection against rear-end collision disputes.
- 360-degree:Multi-lens array capturing full vehicle perimeter with stitched panoramic output. Premium vehicle owners in China and the UAE adopt these for parking surveillance and vandalism documentation in unmonitored locations.
Front-facing systems anchor the volume base while dual-channel configurations gain share at the steepest rate.
Integration Level:
Cost tier stratification separates factory-calibrated premium positioning from price-pressured aftermarket alternatives, with standalone devices occupying the most vulnerable cost position as OEM integration accelerates.
- OEM Integrated:Factory-installed systems with vehicle warranty alignment, dedicated power architecture, and calibration to windshield optical properties. European and Chinese automakers lead specification as EU General Safety Regulation mandates expand addressable hardware demand. This segment commands the highest margin pools due to validation requirements and long-term supply agreements.
- Standalone:Self-contained devices with internal battery or cigarette-lighter power, requiring no vehicle modification. Individual consumers in emerging markets favor these for portability between vehicles and avoidance of installation complexity.
- Aftermarket Add-on:Professionally installed systems tapping vehicle electrical architecture with hardwired power management. North American specialty retailers and mobile electronics installers distribute these to owners of older vehicles lacking factory camera provision.
- Fleet Solutions:Bulk-provisioned systems with centralized management platforms, remote firmware updates, and telematics integration. Commercial operators in the United States and United Kingdom negotiate these through usage-based insurance channels to reduce liability exposure and premium costs.
Standalone devices retain the broadest geographic penetration while OEM integrated systems expand most quickly in regulated markets.
Connectivity:
Application-driven connectivity requirements separate real-time upload scenarios from local-only recording, with cloud-enabled architectures capturing the steepest expansion trajectory as fleet management and consumer remote-access demands converge.
- Cloud-enabled:Cellular or Wi-Fi upload capability enabling remote footage access, real-time incident alerts, and centralized fleet oversight. Fleet operators and safety-conscious consumers adopt these as telematics data exchange agreements with underwriters in the United Kingdom and South Korea open B2B2C distribution paths. Neural-network-based incident detection compressing false-positive rates reduces storage waste and enables longer effective retention.
- Wi-Fi:Local wireless connectivity for smartphone app pairing and footage retrieval without cellular subscription. Mid-market consumers favor these for balance between convenience and avoidance of recurring connectivity fees.
- Bluetooth:Short-range pairing for basic device configuration and emergency footage flagging. Entry-level systems in price-sensitive markets specify this to minimize hardware cost.
- USB:Wired connection for footage transfer and device power, prevalent in legacy systems and budget configurations where wireless modules are omitted.
Wi-Fi connectivity dominates current installed base while cloud-enabled systems climb the fastest as subscription revenue models mature.
End User:
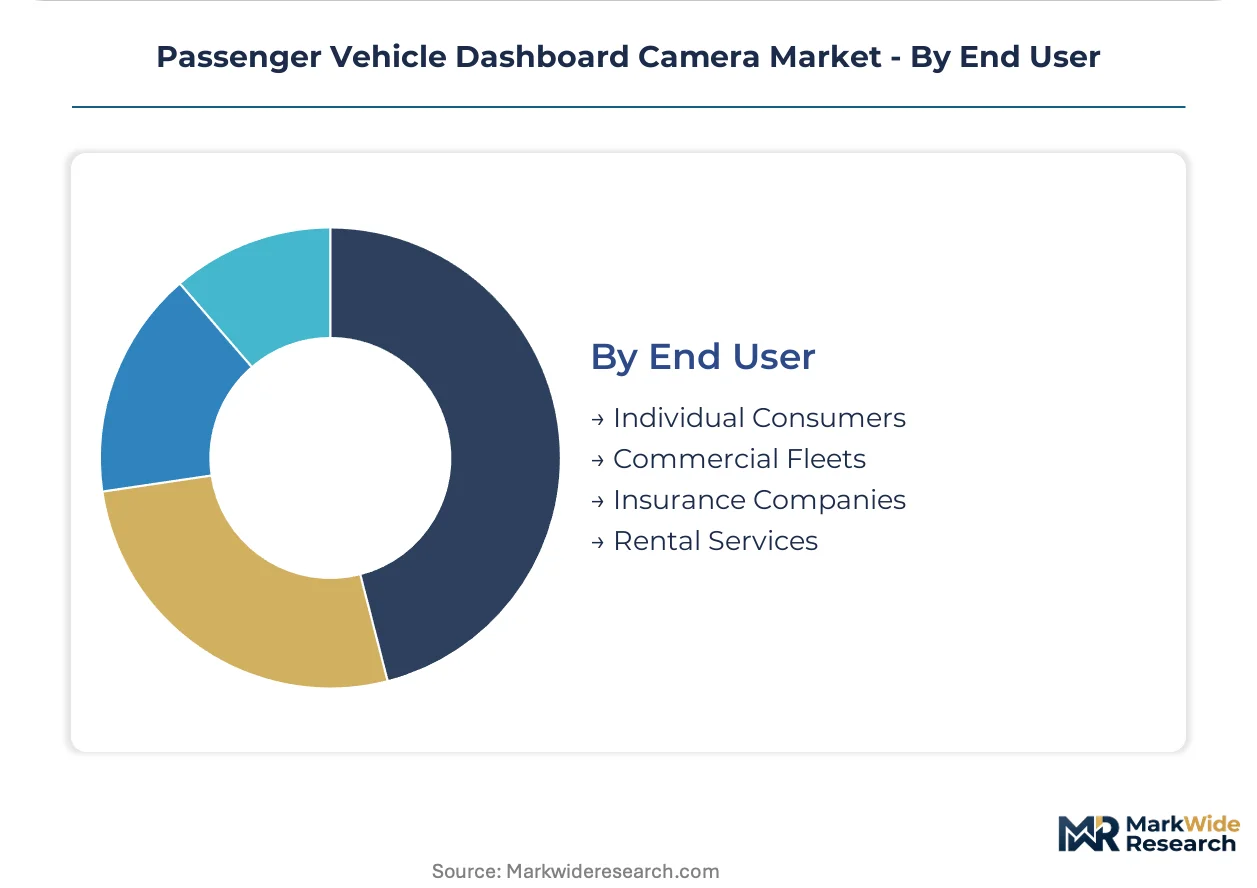
Customer type segmentation maps divergent procurement patterns, with commercial fleets driving specification density and insurance companies emerging as influential channel gatekeepers through telematics data partnerships.
- Commercial Fleets:Multi-vehicle operators specifying dual-channel systems with centralized management, driver behavior monitoring, and integration with dispatch platforms. Video telematics adoption among United States logistics and service fleets reduces liability exposure and enables insurance premium negotiation. EU General Safety Regulation mandates for driver monitoring directly expand hardware demand among European fleet operators.
- Individual Consumers:Private vehicle owners purchasing through retail, e-commerce, or automotive aftermarket channels. Chinese domestic brands leverage live-streaming commerce and short-video marketing to capture this segment in Southeast Asian markets.
- Insurance Companies:Underwriters specifying or subsidizing dashcam provision as condition of usage-based policies. Telematics data exchange agreements in the United Kingdom and South Korea position these entities as B2B2C channel controllers.
- Rental Services:Vehicle rental and car-sharing operators deploying cameras for damage documentation and dispute resolution. Airport-based operators in the United States and Europe specify these to accelerate checkout incident processing.
Individual consumers anchor the volume base while commercial fleets gain share at the steepest rate as video telematics standardizes across logistics operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies, with Chinese consumers driving volume through sub-$50 e-commerce pricing while German and British buyers absorb premium dual-channel systems for insurance discounts. This divergence shapes where manufacturers deploy feature-rich versus stripped-down product variants.
United States
Fleet operators in Texas and California anchor commercial demand, deploying video telematics to reduce liability exposure and negotiate insurance premiums. NHTSA guidelines on event data recording shape product specifications for aftermarket suppliers. Detroit-area automotive electronics clusters host validation facilities serving Tier 1 integration programs.
Germany
Private owners in Bavaria and North Rhine-Westphalia prioritize dual-channel systems with comprehensive coverage documentation for premium discounts. EU General Safety Regulation mandates for driver monitoring expand factory-fit camera demand across German automaker supply chains. Stuttgart's automotive engineering ecosystem supports OEM calibration and windshield optical integration.
China
Domestic manufacturers 70mai and others exploit aggressive pricing through live-streaming commerce and short-video marketing to capture mass-market volume. MIIT enforces GB standards for electromagnetic compatibility and imaging quality, creating compliance barriers for uncertified imports. Shenzhen and Dongguan lens module assembly clusters concentrate image sensor packaging capacity.
United Kingdom
Nextbase leverages established retail presence to sustain premium positioning in dual-channel configurations across England and Scotland. Telematics data exchange agreements with underwriters position insurance companies as B2B2C channel controllers. Midlands distribution networks serve both consumer electronics retail and fleet management procurement.
South Korea
Usage-based insurance channels drive cloud-enabled system adoption among safety-conscious consumers in Seoul and Busan. MFDS-aligned quality expectations elevate product reliability standards for market entry. Pangyo Techno Valley hosts connected device development centers supporting real-time upload and remote access functionality.
Passenger Vehicle Dashboard Camera Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the passenger vehicle dashboard camera market. The vendor base fragments between premium-tier specialists emphasizing integrated GPS logging and driver awareness alerts, mid-market specification competitors, and volume-driven domestic brands exploiting e-commerce distribution. Three strategic archetypes dominate: automotive-grade OEM integrators, aftermarket feature specialists, and digitally native cost leaders. Competitive moves concentrate on strategic partnerships with insurance underwriters and backward integration into CMOS sensor sourcing.
Within the premium-tier vector, Garmin exemplifies safety-conscious consumer positioning through integrated ecosystem approaches. Viofo occupies a specification-density position anchoring enthusiast demand with sensor performance emphasis at mid-market price points. 70mai represents the digitally native cost-leadership archetype, exploiting China's manufacturing base and mobile-first commerce channels to compress distributor margins and build brand recognition in Southeast Asian markets.
| Leading Market Players |
|---|
| BlackVue |
| Garmin |
| Viofo |
| Nextbase |
| 70mai |
| Samsara |
| Vantrue |
| Thinkware |
| Verizon Connect |
| Others |
Supply Flow & Price Mechanics
Guangdong lens module assembly at 70-plus percent utilization anchors global cost floors for CMOS-based capture devices, compressing margins for non-integrated competitors while elevating pricing power for OEM-calibrated suppliers. This scale concentration bifurcates the market between volume-driven e-commerce tiers and automotive-grade premium positioning.
Pricing Analysis
EU General Safety Regulation dictates the pricing tier structure across member states, separating factory-integrated systems with warranty alignment from aftermarket alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in standalone devices intensifies as smartphone dashcam apps erode sub-$50 positioning. Fleet operators exhibit lowest price sensitivity due to insurance premium negotiation leverage, while Southeast Asian e-commerce consumers anchor highest sensitivity.
Supply Chain Analysis
Shenzhen-Dongguan corridor chokepoints underwrite image sensor packaging capacity for global dashcam production. Manufacturing concentrates in China, South Korea, and Taiwan with CMOS sensors, NAND flash memory, and automotive-grade enclosures as critical inputs. Single-source vulnerability in Guangdong lens module assembly creates geographic risk exposure. Distribution runs through direct-to-consumer e-commerce platforms in volume markets and Tier 1 supplier networks for OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where EU General Safety Regulation compliance creates switching costs that lock OEMs into validated supplier relationships.
For Market Incumbents: Shield factory-fit calibration capabilities through backward integration into CMOS sensor sourcing and MIIT-recognized laboratory partnerships. Expand capacity in Stuttgart and Pangyo Techno Valley clusters to serve Tier 1 integration programs. Emerging Chinese domestic brands threaten volume-tier positioning through live-streaming commerce channels. For New Entrants and Emerging Players: Cloud-enabled fleet management service layers represent the most penetrable white space, as incumbents under-serve real-time upload and telematics integration demands. Target United States commercial logistics operators through usage-based insurance channel partnerships. Pursue B2B2C distribution agreements with underwriters rather than consumer retail buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-enabled fleet solution providers with subscription-based remote access and centralized management platforms. Long-term viability favors automotive-grade OEM integrators with validated calibration capabilities and multi-year supply agreements. Monitor EU Cyber Resilience Act implementation timelines as inflection indicator for firmware security certification cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Investment | GB standards compliance unlocks China market entry for imported devices against domestic competitors. |
| Telematics Data Partnership | Usage-based insurance channel agreements with UK and South Korean underwriters open B2B2C distribution paths. |
| Backward Integration into Sensors | Captive CMOS supply reduces NAND flash pricing volatility exposure and stabilizes bill-of-materials. |
| Fleet Management Platform Launch | Centralized oversight and neural-network incident detection compress false-positive rates for commercial operators. |
| OEM Calibration Facility Expansion | Stuttgart and Detroit validation centers serve Tier 1 integration programs for EU and North American automakers. |
Methodological Framework
Desk research of automotive production databases, customs and trade records, and regulatory filing repositories preceded structured interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and fleet management technology directors. Primary fieldwork combined with secondary validation from NHTSA guidelines, EU General Safety Regulation documentation, and MIIT GB standards publications. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, integration level, connectivity, and end user segmentation dimensions.
Variance decomposition across volume and value outputs reflects analytical framework segmentation by vehicle class, OEM tier, content per vehicle, and regional production cluster. CAGRs derive from installed base replacement cycles, regulatory mandate phase-in schedules, and telematics adoption curve modeling. Forecast inputs incorporate NAND flash pricing trajectories and EU Cyber Resilience Act compliance cost assumptions.
Forecasts assume regulatory continuity in EU General Safety Regulation implementation, NHTSA event data recording guidelines, and MIIT electromagnetic compatibility enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as EU AI Act algorithmic transparency requirements and China GB standards revision timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Automotive Split-View Camera Module Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Japan Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market