
 Automotive Exterior Materials Market | 2026-2036
Automotive Exterior Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exterior Materials Market Intelligence
The transition toward multi-material vehicle architectures is fragmenting traditional material hierarchies in automotive design. This shift creates opportunities for specialized material suppliers to displace incumbent metals. BASF SE leverages its deep chemical expertise to supply advanced composites and engineering plastics for lightweighting initiatives. Magna International Inc. competes by offering complete exterior systems, from bumpers to body panels, that integrate various materials for original equipment manufacturers. Plastic Omnium specializes in complex plastic components and modules, including intelligent bumpers with embedded sensors.
Automotive exterior materials comprise the portfolio of metals, plastics, composites, and glass engineered for a vehicle's outer shell. These materials must provide high resistance to ultraviolet radiation, chemical corrosion, and physical impact while meeting specific Class A surface finish standards. Their primary purpose is to deliver aesthetic appeal, aerodynamic performance, and structural protection for the vehicle and its occupants. While traditional steel and aluminum still form a significant part of the material mix, advanced plastics and composites represent the fastest-growing material types. Bumpers and body panels are the leading applications driving innovation in material science and manufacturing processes like injection molding.
Global regulations directly shape material selection and design specifications. The European Union's End-of-Life Vehicles (ELV) Directive encourages the use of recyclable and recoverable materials, influencing polymer and composite development. In parallel, safety standards from the US National Highway Traffic Safety Administration (NHTSA) dictate impact resistance for bumpers and front-end modules. Material suppliers must balance these competing requirements of sustainability, safety, and cost to secure specifications on new vehicle platforms.
Market Dynamics
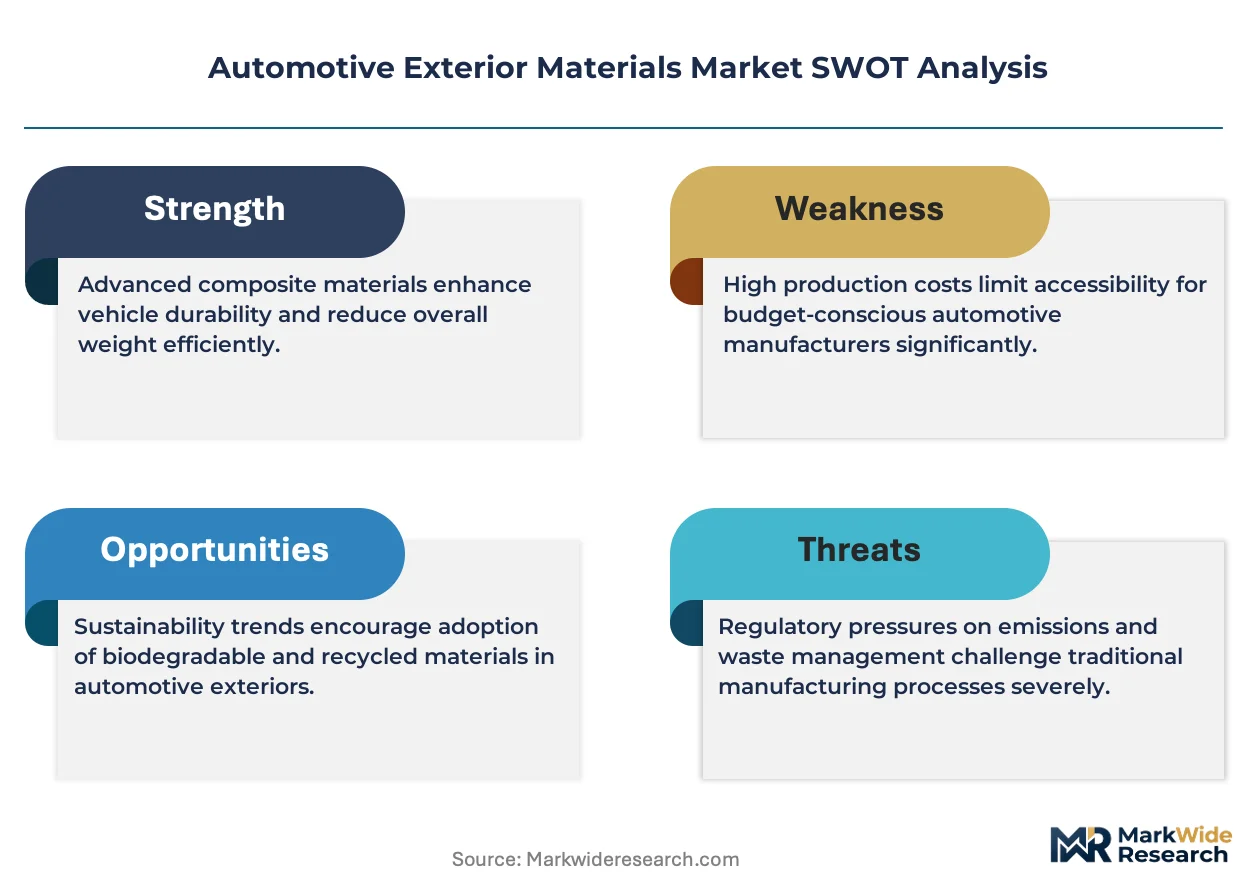
The imperative for vehicle lightweighting, driven by electric vehicle battery range extension and stringent emissions targets, is the central force shaping the automotive exterior materials market. This creates a direct conflict with demands for cost containment and increased material recyclability, forcing a complex trade-off in material selection for new vehicle platforms.
Growth Catalysts
- Regulatory Mandates:Emissions standards from the US EPA and the EU Green Deal framework compel automakers to reduce vehicle weight to improve fuel or energy efficiency, directly stimulating demand for lightweight plastics, composites, and advanced aluminum alloys.
- Electric Vehicle Adoption:The rapid expansion of the EV segment, particularly in China, creates significant demand for non-metallic body panels and battery enclosures that offer weight savings, thermal management, and design flexibility.
- Advanced Manufacturing Processes:Innovations in injection molding, multi-material joining, and automated composite layup are reducing the cycle times and costs associated with producing complex exterior components from advanced materials, making them viable for mass-market vehicles.
Market Restraints
- High Material and Processing Costs:The cost of raw materials like carbon fiber and the associated capital-intensive manufacturing processes remain a significant barrier to their widespread adoption in high-volume, cost-sensitive vehicle segments compared to conventional steel.
- Recycling and Repair Complexity:Multi-material components and thermoset composites pose significant challenges for end-of-life recycling, conflicting with regulations like the EU's ELV Directive. Repairing composite panels is also more complex and costly than traditional metal bodywork.
- Long Validation Cycles:The automotive industry's rigorous and lengthy testing and validation protocols for new materials can delay the introduction of innovative solutions, slowing the pace of displacement of incumbent materials like steel and aluminum.
Strategic Opportunities
- Bio-Based and Recycled Polymers:Developing polymers and composites with high percentages of recycled or bio-based content offers a direct path for suppliers to meet OEM sustainability targets and comply with circular economy regulations.
- Smart Surfaces and Integrated Functionality:The integration of sensors, lighting, and heating elements directly into exterior panels, such as polycarbonate glazing or intelligent bumpers, creates new value propositions beyond structural and aesthetic functions.
- Commercial Vehicle Lightweighting:The application of lightweight exterior materials to commercial trucks and buses is a relatively underpenetrated area that offers substantial fuel savings and payload capacity improvements, representing a significant growth vector.
Industry Challenges
- Dissimilar Material Joining:Ensuring the long-term durability and structural integrity of joints between different materials, such as aluminum to carbon fiber or steel to plastic, presents significant engineering challenges related to thermal expansion and galvanic corrosion.
- Supply Chain Scalability:Scaling up the production of advanced materials like carbon fiber composites to meet the demands of mass-market vehicle platforms requires substantial investment in raw material supply and manufacturing capacity.
- Lack of Repair Standards:A deficit in standardized, cost-effective repair procedures for composite body parts creates uncertainty for insurers, repair shops, and consumers, potentially hindering adoption on mainstream vehicles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exterior Materials Market |
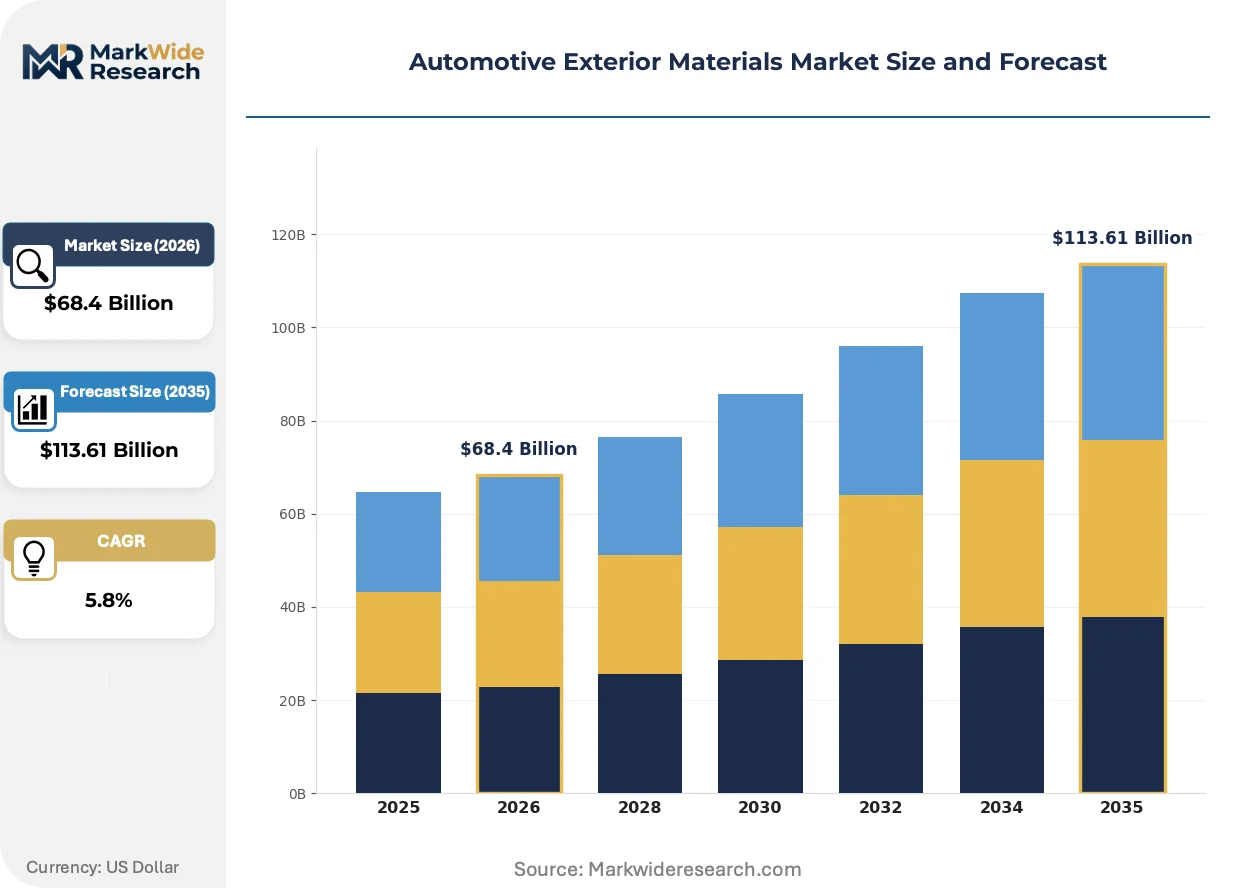
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Metal, Plastic, Composite, Glass Application: Body Panels, Bumpers, Windows, Roofs Manufacturing Process: Injection Molding, Stamping, Extrusion, Casting Finish Type: Painted, Polished, Textured, Coated |
| Companies Covered | Akzo Nobel N.V., Nippon Paint Holdings Co., Ltd., PPG Industries, Inc., Kansai Paint Co., Ltd., Magna International Inc., BASF SE, The Sherwin-Williams Company, Plastic Omnium, Axalta Coating Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exterior Materials Market Strategic Shifts & Innovations
Material development is increasingly focused on lifecycle performance, extending beyond initial aesthetics and impact resistance to include ease of recycling and disassembly. This whole-lifecycle approach is fundamentally altering supplier-OEM relationships and the very definition of a high-performance material.
Advanced multi-material adhesives provide the critical enabling technology for modern lightweight vehicle construction. Automotive body engineers are rapidly adopting these specialized bonding agents to join disparate materials like aluminum, high-strength steel, and carbon fiber reinforced plastics without traditional welding. This integration of advanced bonding agents is collapsing the traditional design silos between metallic and non-metallic components, allowing for more holistic vehicle architectures.
The European Union's End-of-Life Vehicles (ELV) Directive is a primary regulatory driver influencing material innovation. This framework mandates high recovery and recycling rates, pushing suppliers toward developing thermoplastics and composites that can be easily reclaimed. Bumpers and liftgates are the segments most affected, with a visible design shift towards mono-material solutions or components engineered for simplified disassembly at the end of the vehicle's life.
A notable shift in OEM strategy involves sourcing complete exterior modules rather than individual components or raw materials. This disrupts the traditional Tier 2 supplier model, concentrating power with large Tier 1 system integrators capable of delivering pre-assembled front-end modules, doors, or liftgates. This modular procurement trend is most pronounced in North America and Europe, where it helps automakers simplify final assembly and reduce supply chain complexity.
Automotive Exterior Materials Market Segmentation
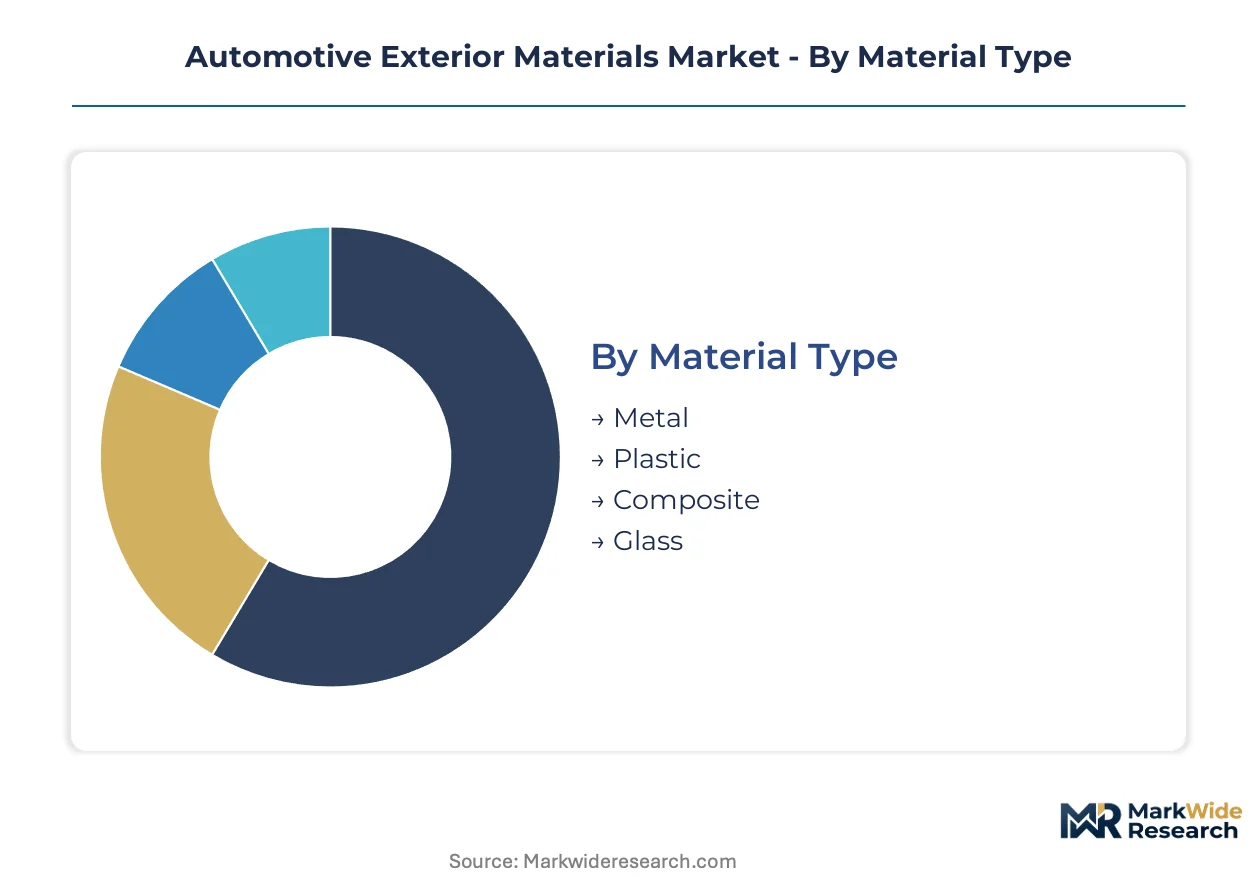
The automotive exterior materials market segments reflect the diverse engineering requirements for vehicle aesthetics, performance, and protection. Material selection directly influences vehicle weight, aerodynamic efficiency, and crashworthiness, impacting both regulatory compliance and consumer appeal. Understanding these distinct segments allows manufacturers to target specific performance envelopes and cost structures across different vehicle platforms.
Material Type:
The material type segmentation highlights the maturity spectrum of automotive exterior components, ranging from established metals to emerging advanced composites.
- Plastic:These materials, including engineering plastics and thermoplastics, offer exceptional design flexibility, corrosion resistance, and are critical for lightweighting initiatives in electric vehicles. Demand for plastic components is concentrating in China, where EV production volumes are highest, driven by the need for battery range extension.
- Composite:Advanced composites, such as carbon fiber reinforced polymers, provide superior strength-to-weight ratios and are increasingly adopted for high-performance and premium vehicle body panels. Their application is expanding rapidly in European luxury vehicle platforms, driven by stringent emissions targets and performance demands.
- Metal:Traditional steel and aluminum alloys form the structural backbone of many exterior components, valued for cost-effectiveness.
- Glass:Specialized glass formulations are engineered for windows and panoramic roofs, providing optical clarity and structural integrity.
Metal handles the majority of throughput; Composite is the fastest mover on share.
Application:
Application segments are primarily driven by volume requirements and the specific functional demands placed on each exterior component.
- Body Panels:These large surface area components define vehicle aesthetics and aerodynamics, requiring materials with excellent surface finish and impact resistance. Demand for lightweight body panels is concentrating in North America, as automakers seek to meet increasingly stringent fuel efficiency standards for trucks and SUVs.
- Bumpers:Bumpers integrate safety features and aesthetic design, often utilizing multi-material architectures to meet impact absorption and pedestrian safety regulations. Innovation in bumper materials is accelerating in Germany, driven by the country's leading automotive OEMs and their focus on advanced safety systems.
- Windows:Vehicle windows require high optical clarity, scratch resistance, and thermal insulation properties.
- Roofs:Roofs range from traditional metal structures to panoramic glass or lightweight composite panels, influencing rigidity and weight.
Body Panels represent the largest volume segment; Bumpers are gaining share fastest due to integrated sensor technology.
Manufacturing Process:
The manufacturing process segmentation reflects the supply concentration of specialized equipment and technical expertise required for material transformation.
- Injection Molding:This high-volume process shapes complex plastic and composite components, enabling intricate designs and functional integration for exterior parts like grilles and trim. Its adoption is heavily concentrated in Asian manufacturing hubs, particularly in South Korea and Japan, due to advanced tooling capabilities.
- Stamping:Stamping involves forming metal sheets into precise shapes for body panels and structural components, a foundational process for high-strength steel and aluminum parts. This process remains a cornerstone in US automotive production, supporting large-scale vehicle assembly lines.
- Extrusion:Extrusion shapes materials into continuous profiles, used for sealing systems, trim, and structural elements.
- Casting:Casting processes produce complex metal components, like brackets and housings, for specific exterior applications.
Stamping maintains the largest production footprint; Injection Molding exhibits the steepest expansion trajectory for new designs.
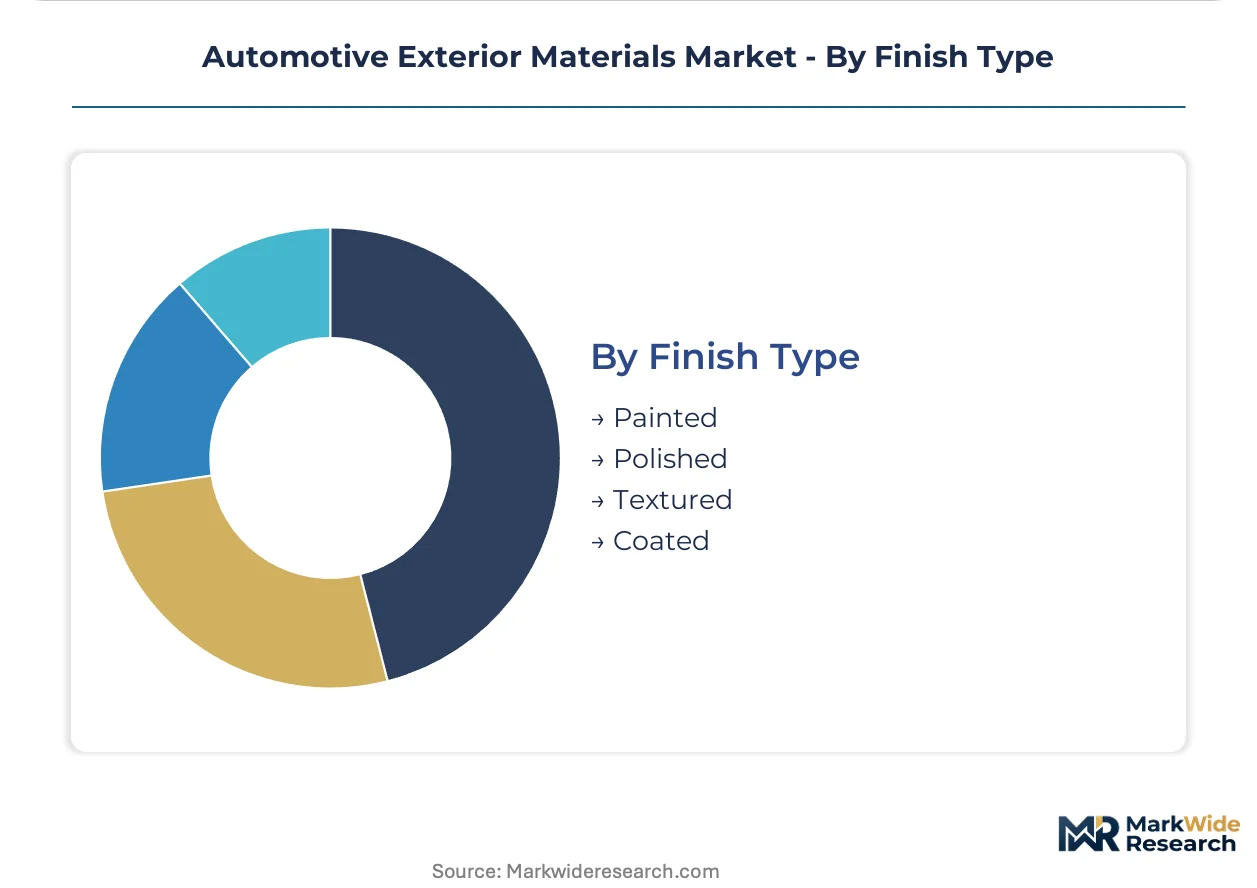
Finish Type:
Finish type segmentation often aligns with cost tiering and aesthetic requirements, influencing both durability and visual appeal of automotive exteriors.
- Painted:The most prevalent finish, painting provides extensive color options, UV protection, and a crucial barrier against environmental corrosion for metal and plastic surfaces. This finish dominates the mass-market segment globally, with significant volumes processed in Mexico for North American vehicle exports.
- Coated:Various coatings, including clear coats, anti-scratch layers, and specialized functional films, enhance durability, gloss, and specific performance attributes like hydrophobic properties. Demand for advanced coatings is rising in premium vehicle segments across Europe, driven by consumer expectations for long-term finish integrity.
- Polished:Polished finishes, applied to chrome or bright metal accents, deliver a high-gloss, reflective aesthetic.
- Textured:Textured finishes provide a non-glossy, tactile surface, used for functional components like grilles or unpainted trim.
Painted finishes command the highest market share; Coated finishes are expanding most quickly due to functional integration demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturers, as primary buyers, concentrate demand for exterior materials in regions with robust vehicle production and stringent regulatory environments. This geographic clustering drives material innovation and supply chain development, particularly for lightweighting solutions and advanced aesthetic finishes. The focus on electric vehicle production in key markets further amplifies this regional demand.
China
Demand for plastic components and advanced exterior materials is concentrating significantly in China, driven by its leading position in electric vehicle manufacturing. The country's dual carbon goals and GB standards compel automakers to prioritize lightweighting and sustainable materials for energy efficiency. Major automotive manufacturing hubs like the Yangtze River Delta are seeing rapid adoption of non-metallic body panels and battery enclosures.
United States
Lightweight body panels are seeing concentrated demand in the United States, as automakers strive to meet stringent US EPA emissions standards and fuel efficiency requirements for trucks and SUVs. The National Highway Traffic Safety Administration (NHTSA) also dictates impact resistance for bumpers, influencing material selection. Michigan's automotive corridor, particularly around Detroit, remains a focal point for material science innovation and vehicle platform integration.
Germany
Innovation in bumper materials is accelerating in Germany, driven by the country's leading automotive OEMs and their focus on advanced safety systems and luxury vehicle platforms. The EU Green Deal framework encourages the use of recyclable materials and lightweight composites, impacting design choices. Bavaria, home to major premium automakers, leads in the application of advanced composites for high-performance exterior components.
South Korea
Advanced tooling capabilities in injection molding for complex plastic and composite components are heavily concentrated in South Korea. The country's robust automotive industry, supported by national quality standards, drives demand for high-precision exterior parts. Gyeonggi Province, with its dense network of manufacturing and R&D facilities, serves as a hub for sophisticated material transformation processes.
Mexico
Painted finishes command significant market share in Mexico, primarily supporting mass-market vehicle exports to North America. The country's automotive production relies on cost-effective material solutions that meet regional quality and aesthetic standards. The Bajío region, with its numerous automotive assembly plants, represents a major processing center for exterior material finishing and component integration.
Automotive Exterior Materials Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure for automotive exterior materials. Traditional material hierarchies are fragmenting, opening pathways for specialized material suppliers to displace incumbent metals. Strategic archetypes include large system integrators, chemical specialists providing advanced materials, and coating solution providers. Dominant competitive moves involve strategic partnerships with OEMs and continuous portfolio diversification into lightweight and sustainable solutions.
Large system integrators like Canada-based Magna International Inc. exemplify the trend toward offering complete exterior systems, from bumpers to body panels, integrating various materials for original equipment manufacturers. France's Plastic Omnium occupies a position as a specialist in complex plastic components and modules, including intelligent bumpers with embedded sensors. Germany's BASF SE anchors the chemical specialist segment, leveraging deep chemical expertise to supply advanced composites and engineering plastics for lightweighting initiatives across the industry.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| PPG Industries, Inc. |
| Kansai Paint Co., Ltd. |
| Magna International Inc. |
| BASF SE |
| The Sherwin-Williams Company |
| Plastic Omnium |
| Axalta Coating Systems Ltd. |
| Others |
Cost & Logistics Intelligence
China's extensive manufacturing capacity for automotive components influences supplier behavior and pricing posture across the automotive exterior materials market. This scale enables cost-effective production, impacting material procurement decisions globally.
Pricing Analysis
Cost-plus contracts, often indexed to raw material prices like polymer and metal commodity rates, define pricing for automotive exterior materials. Price differentiation stems from Class A surface finish requirements, customization for integrated functionality, and volume commitments from OEMs. Pricing pressure stems from automaker demands for lightweighting solutions at competitive costs, particularly for electric vehicle platforms. Mass-market vehicle segments exhibit higher price sensitivity compared to premium and luxury vehicle manufacturers seeking advanced composites.
Supply Chain Analysis
Supply chain scalability for advanced materials like carbon fiber composites presents a significant structural risk, requiring substantial investment in raw material production. Geographic supply concentrates in China for plastics, South Korea for injection molding capabilities, and Germany for high-performance composites. The market draws from diverse inputs including engineering plastics, aluminum alloys, and specialized chemical coatings. Distribution runs through direct OEM engagements and increasingly via large Tier 1 system integrators providing complete exterior modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive exterior materials market is at a platform-economics inflection, driven by the integration of smart surfaces and functional modules into holistic vehicle architectures. This shift demands interoperability between material science, sensor technology, and manufacturing processes.
For Market Incumbents: Build a system integration moat by investing heavily in advanced multi-material joining technologies and modular assembly capabilities. This defends against fragmentation from specialized material suppliers and addresses OEM demands for simplified procurement. Strategic partnerships with automakers for co-development of new vehicle platforms secure long-term specifications. Continued R&D into recyclable composites also mitigates regulatory threats like the EU ELV Directive.
For New Entrants and Emerging Players: Build out specialized capabilities in bio-based and recycled polymers to meet OEM sustainability targets and circular economy regulations. The commercial vehicle lightweighting segment offers an underpenetrated white space for material innovation, promising significant fuel savings. Target specific niches like intelligent bumpers with integrated sensors, leveraging rapid prototyping and advanced manufacturing processes for market entry. Focus on offering compelling lifecycle performance and ease of recycling as a differentiator.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized material science firms possessing proprietary intellectual property in advanced composites or smart surface integration. These companies demonstrate strong long-term viability within the accelerating shift towards lightweight, sustainable, and intelligent exterior components. Acquisitions should target Tier 1 system integrators with established OEM relationships and modular manufacturing expertise. The signal to watch is the increasing proportion of non-metallic body panels specified for new mass-market electric vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Composites R&D | Develops lighter, stronger materials crucial for EV range extension. |
| Multi-Material Joining Technology | Enables durable integration of disparate materials in vehicle structures. |
| Bio-Based Polymer Development | Meets circular economy mandates and OEM sustainability objectives. |
| Modular System Integration | Simplifies OEM assembly and reduces supply chain complexity. |
| Smart Surface Functionality | Creates new value propositions by embedding sensors and lighting into panels. |
Research Approach
The analysis maps material types including metals, plastics, composites, and glass, each validated through primary interviews with OEM platform engineers and Tier 1 procurement leads. Secondary data sources, such as US EPA standards, EU ELV Directive documents, and automotive industry association reports, provide market context. This approach integrates insights from material science R&D directors and regulatory compliance officers. Bottom-up data collection and top-down market sizing ensure robust triangulation.
Assumptions regarding electric vehicle adoption rates and regulatory mandate stringency were held fixed, while material-specific cost curves and manufacturing process efficiencies were varied. The quantitative framework models market volume and value across the analysis window. Segmentation dimensions include material type, application, manufacturing process, finish type, and regional adoption patterns. Compound annual growth rates derive from historical trends and projected shifts in material preference.
Stress conditions across raw material price volatility and geopolitical trade tensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions concerning technological advancements and regulatory enforcement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Glazing for Automotive Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Automotive Sunroof Market