
 Asia-Pacific Automotive Seat Market | 2026-2036
Asia-Pacific Automotive Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Seat Market Outlook
Software-defined seat adjustment and climate-control subscriptions is broadening the recurring revenue model beyond hardware sales. Toyota Boshoku Corporation leverages its captive supply relationship with Toyota Motor to dominate Japan's premium seating tier. TS Tech Co., Ltd. anchors its position through deep R&D intensity in thin-profile seat frames for compact vehicle platforms. Bharat Seats Ltd competes on manufacturing scale across India's northern and western automotive clusters.
An automotive seat is an engineered occupant support system comprising a metal frame, cushioning foam, suspension mechanisms, and trim materials designed to meet specified crashworthiness and ergonomic parameters. The assembly must absorb collision energy through controlled deformation while maintaining occupant position relative to restraint systems. Leather-trimmed configurations command the strongest margin pools among material categories, while fabric variants sustain the highest unit volumes across mass-market OEM programs. Sport seat types are gaining share within performance-oriented electric vehicle lineups, whereas standard configurations remain the mature baseline for fleet and economy segments.
China's SAMR enforces GB standards for seat strength and flammability that dictate foam chemistry and textile selection across domestic supply chains. Japan's METI coordinates JIS certification requirements that shape export eligibility for seating components bound for ASEAN assembly plants. India's BIS mandates seatbelt anchorage integration testing that influences frame design and welding protocols for suppliers serving Maruti Suzuki and Hyundai Motor India. Stakeholders must monitor how dual carbon goals across China, Japan, and South Korea are redirecting polyurethane sourcing toward bio-based feedstocks and recycled polyester textiles.
Market Dynamics
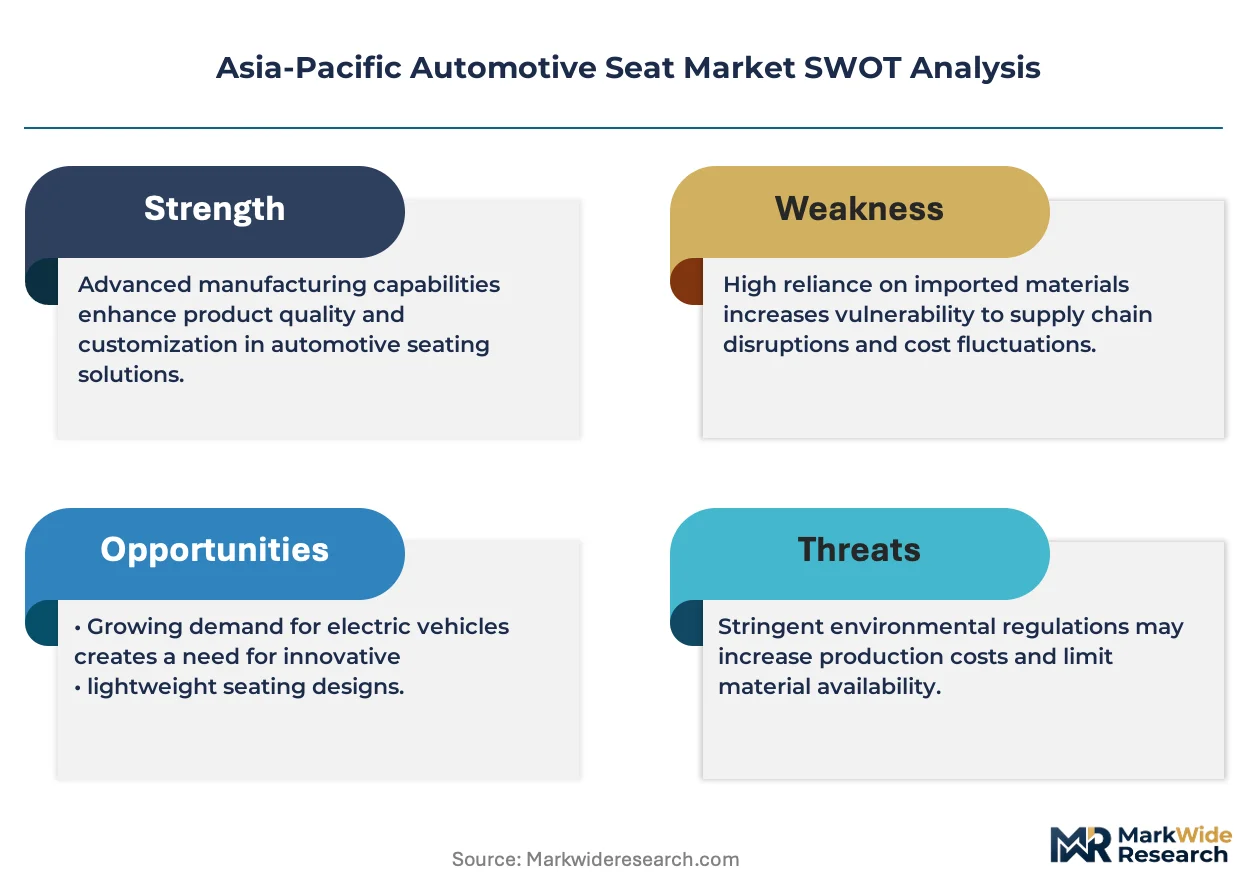
Electric vehicle platform architectures are compressing seat frame z-height requirements while expanding power integration demands, forcing suppliers to redesign structural load paths and thermal management interfaces simultaneously.
Growth Catalysts
- GB Standard 15083:China's revised seat anchorage strength mandates are accelerating high-tensile steel adoption across domestic supply chains, requiring frame weld protocol upgrades.
- Bio-based polyurethane feedstocks:Dual carbon goals across China, Japan, and South Korea are redirecting foam chemistry toward plant-derived polyols and recycled polyester textiles.
- Chennai-Pune corridor concentration:India's passenger vehicle assembly clusters are generating localized demand surges for just-in-time seat module delivery.
Market Restraints
- Steel and aluminum price volatility:Frame material cost swings compress margin buffers for suppliers locked into annual OEM pricing agreements.
- Single-source foam chemical dependency:Polyol supply concentrates among three regional petrochemical groups, creating input vulnerability during plant turnaround cycles.
- JIS certification timeline friction:METI export requirements for ASEAN-bound components extend qualification periods by four to six months.
Strategic Opportunities
- Software-defined seat subscriptions:Climate-control and position-memory services are creating recurring revenue streams beyond hardware sales.
- Vietnam and Indonesia assembly greenfields:Emerging ASEAN vehicle production hubs lack mature seating supply bases, opening first-mover positioning.
- Thin-profile frame architectures:Compact EV platforms are demanding 20-30mm z-height reductions, rewarding R&D-intensive frame engineering capabilities.
Industry Challenges
- Multi-material welding expertise scarcity:Steel-aluminum hybrid frames require friction-stir and laser-welding skill sets that outpace regional vocational training output.
- GB-BIS-METI regulatory divergence:Incompatible crash-test and flammability standards force parallel certification tracks for pan-Asia-Pacific suppliers.
- Legacy seat controller integration:New power-adjustment modules must interface with decade-old vehicle electrical architectures without full system redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Seat Market |
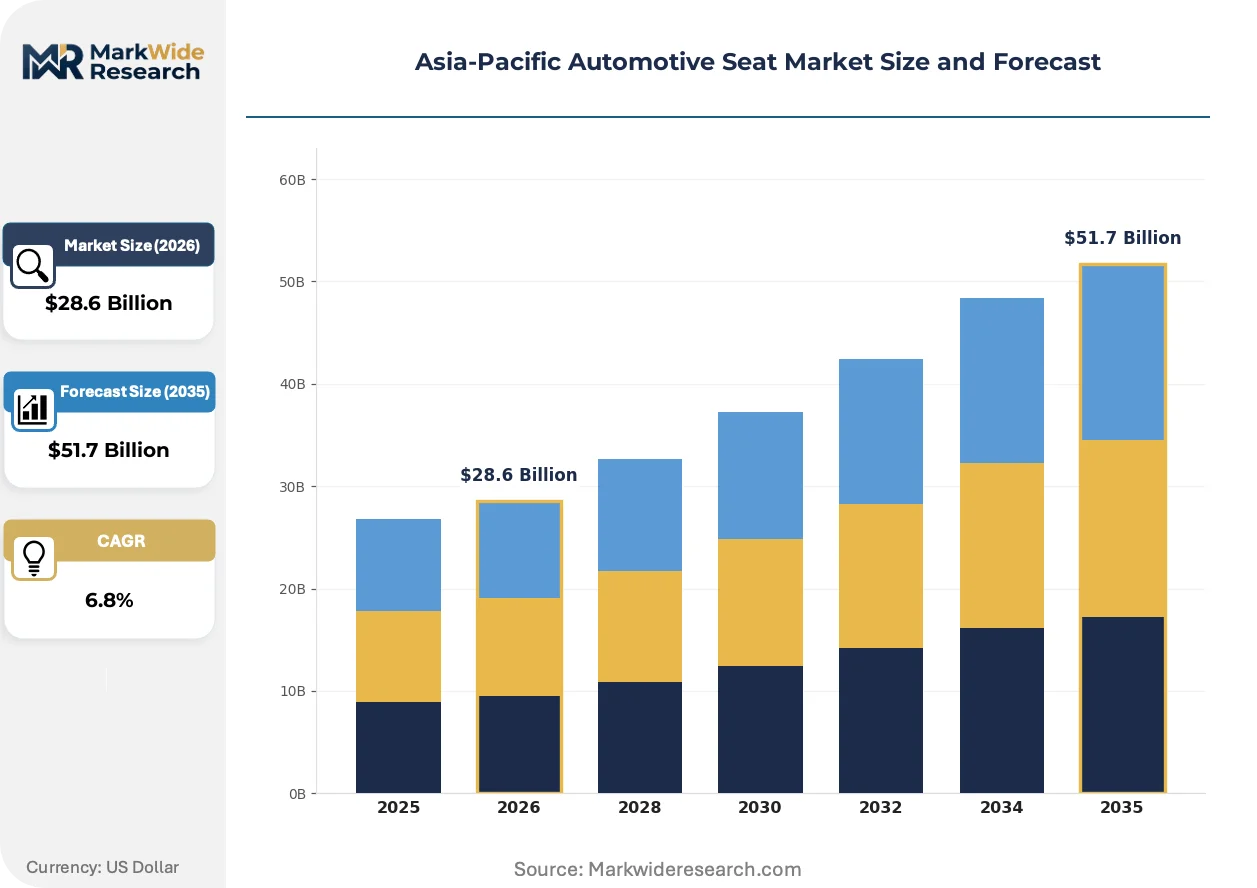
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fabric, Leather, Vinyl, Foam Seat Type: Standard, Sport, Additional, Bucket End User: OEMs, Aftermarket Providers, Suppliers, Distributors Installation Type: Front, Rear, Adjustable, Fixed |
| Companies Covered | Toyota Boshoku Corporation, TS Tech Co., Ltd., Adient PLC, Magna International Inc., NHK Spring Co., Ltd., Forvia, TACHI-S Co., Ltd., Bharat Seats Ltd, Lear Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Seat Market Strategic Shifts
Active materials and embedded electronics are transforming seats from passive structural components into dynamic occupant interfaces that respond to biometric and environmental inputs in real time.
Smart foam systems incorporating pressure-mapping sensors and microclimate ventilation are electrifying seat comfort architecture. Premium EV lineups in China and South Korea are adopting these configurations at twice the rate of mass-market hybrids. The technology is electrifying supplier R&D allocation toward mechatronics integration and away from pure mechanical engineering.
SAMR's enforcement of GB 8410 flammability standards for automotive textiles is eliminating halogenated flame retardants from seat cover specifications. Foam suppliers are reformulating with phosphorus-based alternatives at accelerated qualification timelines. Leather-trimmed configurations face the steepest chemistry transition costs, while fabric variants adapt more rapidly through existing textile partnerships.
Fleet operators and ride-hailing platforms are compressing seat replacement cycles from seven-year vehicle life to three-year durability warranties. This pattern concentrates demand for heavy-duty fabric grades and modular trim replacement systems. The shift is most visible in India's commercial vehicle and shared mobility procurement channels around Delhi-NCR and Bengaluru.
Asia-Pacific Automotive Seat Market Segmentation
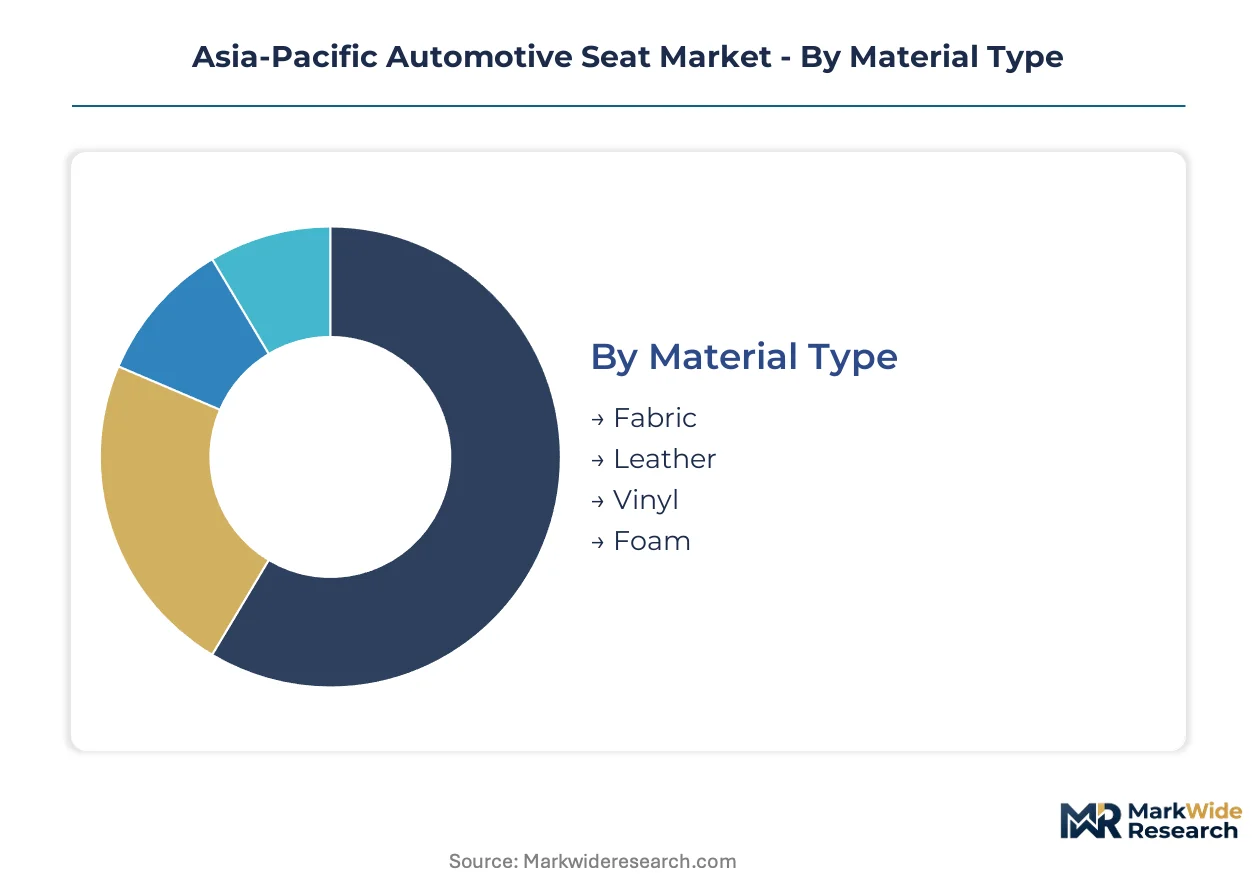
Seat material selection dictates margin structure and regulatory compliance pathways across Asia-Pacific supply chains. Installation positioning determines power integration complexity and crashworthiness engineering requirements.
Material Type:
Buyer decisions here pivot on durability warranties and dual carbon sourcing mandates from Chinese and South Korean OEMs.
- Fabric:Woven polyester and nylon blends dominate mass-market OEM programs across India's Chennai-Pune corridor. Maruti Suzuki and Hyundai Motor India procurement teams prioritize this category for fleet and economy vehicle lines where unit volumes outweigh per-unit margin capture.
- Leather:Full-grain and corrected-grain hides command premium positioning within Toyota's Lexus lineup and Chinese EV manufacturers' flagship tiers. GB 8410 flammability enforcement is forcing phosphorus-based tanning chemistry transitions that compress supplier margins during qualification periods.
- Vinyl:Polyvinyl chloride formulations serve commercial vehicle and shared mobility segments requiring sanitizable surfaces and compressed replacement cycles.
- Foam:Polyurethane cushioning systems integrate plant-derived polyol feedstocks under Japan-South Korea dual carbon procurement directives.
Volume sits with fabric configurations across mass-market programs; growth tilts toward bio-based foam chemistry adoption.
Seat Type:
Application context—fleet duty cycles versus private ownership—shapes structural reinforcement and adjustment mechanism specifications.
- Standard:Fixed-back configurations with manual height adjustment anchor economy and fleet segments across ASEAN assembly plants. These units minimize electrical architecture integration costs for legacy vehicle platforms still prevalent in Indonesian and Vietnamese production.
- Sport:Bolstered side supports and integrated headrests address lateral acceleration loads in performance-oriented electric vehicle architectures from Chinese and South Korean manufacturers. Thin-profile frame engineering enables these units to meet compressed z-height requirements without sacrificing occupant retention.
- Additional:Third-row and auxiliary seating modules serve multi-purpose vehicle segments concentrated in Indian and Indonesian family transportation markets.
- Bucket:Individual contour designs dominate premium front-row positioning across Japanese and South Korean OEM lineups.
Standard configurations retain the highest unit shipments; sport variants are climbing the fastest within EV platform launches.
End User:
Supply chain position determines whether specifications originate from vehicle manufacturer engineering centers or aftermarket retrofit channels.
- OEMs:Toyota Motor, Hyundai Motor Group, and SAIC Motor dictate frame weld protocols, foam density specifications, and textile flammability compliance through captive supplier relationships and annual pricing agreements.
- Aftermarket Providers:Independent distributors serving India's Delhi-NCR and Bengaluru commercial vehicle corridors concentrate on heavy-duty fabric grades with modular trim replacement systems.
- Suppliers:Tier-1 manufacturers like Toyota Boshoku and TS Tech Co. translate OEM specifications into production-ready seat modules.
- Distributors:Regional logistics operators manage just-in-time delivery to assembly plants across the Chennai-Pune manufacturing belt.
OEMs capture the steepest expansion trajectory as platform consolidation concentrates procurement authority; aftermarket channels sustain steady replacement demand.
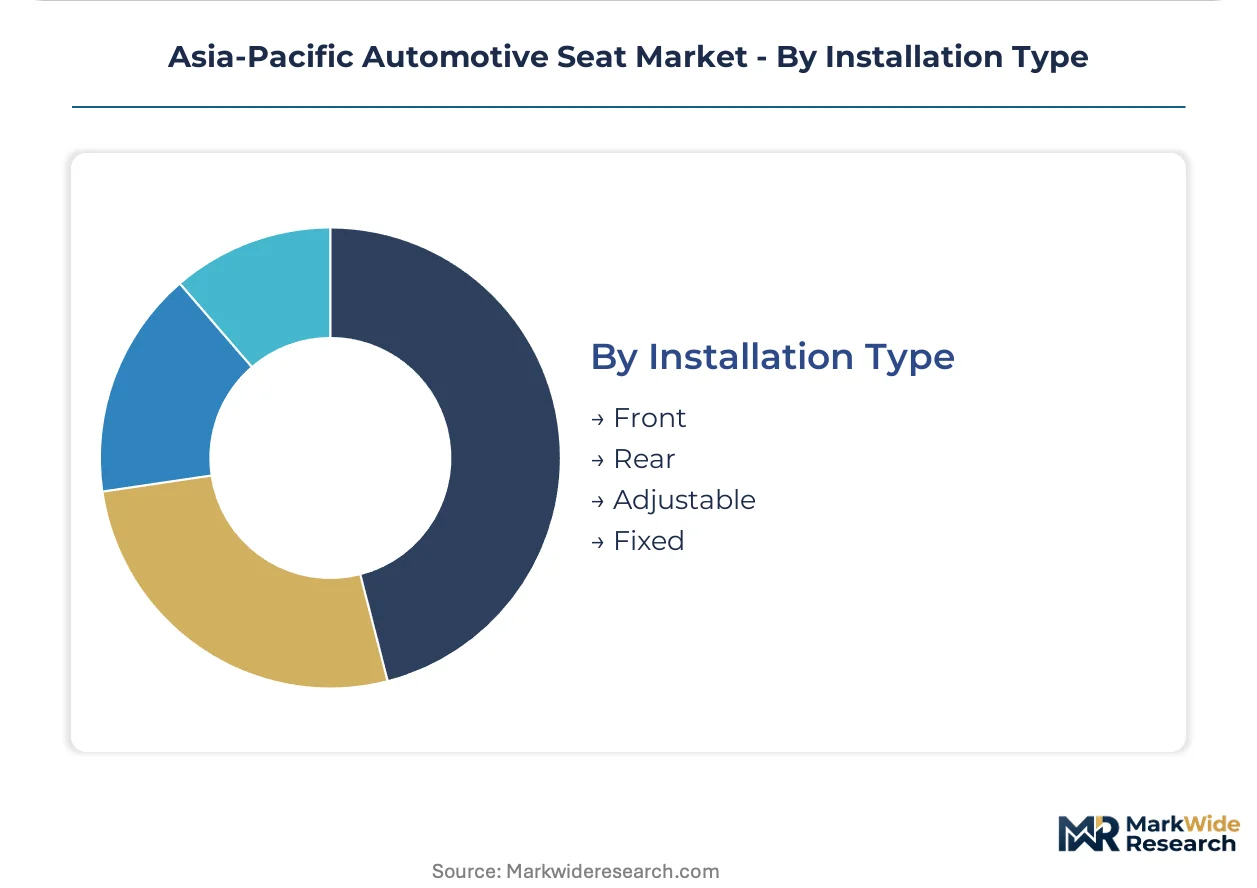
Installation Type:
Vehicle architecture constraints and occupant safety positioning determine structural load path engineering.
- Front:Power-adjustment modules with memory and climate functions integrate with vehicle electrical architectures across Chinese and South Korean premium EV lineups. These units face legacy controller compatibility challenges when interfacing with decade-old electrical systems.
- Rear:Bench and split-folding configurations prioritize cargo flexibility over occupant support in ASEAN-market multi-purpose vehicles.
- Adjustable:Multi-way power mechanisms with lumbar and thigh extension serve long-wheelbase executive sedans concentrated in Chinese urban centers.
- Fixed:Non-adjustable bucket and bench units minimize cost and weight in entry-level hatchbacks across Indian and Indonesian markets.
Front installations absorb the majority of R&D investment; adjustable mechanisms are gaining share fastest within premium EV segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of Asia-Pacific automotive seat modules while Japan and South Korea concentrate on premium component exports. India absorbs expanding domestic vehicle assembly demand across its industrial corridors.
China
Electric vehicle platform launches from SAIC Motor and BYD are compressing seat z-height specifications while expanding power integration requirements. SAMR enforces GB 15083 anchorage strength mandates that accelerate high-tensile steel adoption across Yangtze River Delta supply chains. Shanghai and Jiangsu province house dense clusters of frame welding facilities serving domestic OEMs.
Japan
Lightweight thin-profile seat architectures for compact EV platforms anchor export competitiveness. METI coordinates JIS certification requirements that shape component eligibility for ASEAN-bound shipments. Toyota Boshoku and TS Tech anchor production networks across Aichi and Shizuoka prefectures with captive supply relationships.
India
Passenger vehicle assembly expansion by Maruti Suzuki and Hyundai Motor India concentrates procurement authority around Chennai and Pune. BIS mandates seatbelt anchorage integration testing that influences frame welding protocols for northern and western automotive clusters. Bharat Seats operates manufacturing scale across Haryana and Maharashtra to serve just-in-time delivery requirements.
South Korea
Hyundai Motor Group and Kia Corporation platform consolidation drives demand for smart foam systems with embedded climate control. Dual carbon procurement directives redirect polyurethane sourcing toward bio-based polyols. Gyeonggi-do and Busan-Ulsan regions concentrate R&D-intensive seat module engineering for premium EV lineups.
Vietnam
Emerging vehicle assembly greenfields lack mature seating supply bases, opening positioning for tier-1 module suppliers. General functional descriptors for national automotive regulators shape import compliance requirements for frame and foam components. Ho Chi Minh City and Hanoi industrial zones attract logistics operators managing regional distribution.
Asia-Pacific Automotive Seat Market Competitive Environment
Top-tier vendors anchor premium and mass-market OEM supply relationships, while mid-scale fabricators compete on regional cost positioning and just-in-time delivery capabilities. The vendor base stratifies across captive automotive group suppliers, independent tier-1 module manufacturers, and regional specialists serving single-country markets. Three archetypes dominate: integrated seating-system suppliers with full-frame-to-trim capabilities; component specialists concentrating on foam chemistry or frame engineering; and regional scale players leveraging manufacturing proximity to assembly plants. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for EV platform qualification.
Within the integrated-system tier, Toyota Boshoku Corporation and TS Tech Co., Ltd. exemplify captive supply structures aligned with major Japanese OEMs. Bharat Seats Ltd occupies a position representing regional scale fabrication serving India's concentrated vehicle assembly corridors. These anchors illustrate how competitive positioning depends on supply relationship depth, R&D intensity in lightweight architectures, and manufacturing scale aligned with corridor-specific demand.
| Leading Market Players |
|---|
| Toyota Boshoku Corporation |
| TS Tech Co., Ltd. |
| Adient PLC |
| Magna International Inc. |
| NHK Spring Co., Ltd. |
| Forvia |
| TACHI-S Co., Ltd. |
| Bharat Seats Ltd |
| Lear Corporation |
| Others |
Value Chain & Pricing Dynamics
Thin-profile frame engineering for compact EV platforms is compressing supplier margins while concentrating procurement authority among OEMs with captive R&D capabilities. This dual squeeze simultaneously elevates cost-down pressure on component specialists and rewards integrated manufacturers with backward control over high-tensile steel sourcing and weld protocol development.
Pricing Analysis
Margin tightening in mass-market fabric seats reflects annual OEM pricing agreements that lock suppliers into fixed rates despite steel and aluminum input volatility. Three-tier pricing structure across premium leather, standard fabric, and economy vinyl configurations separates margin pools by certification grade and volume scale. Cost-down pressure on frame components accelerates because GB 15083 anchorage mandates require high-tensile steel upgrades without corresponding price relief. Fleet operators in India's commercial vehicle corridors exhibit the highest price sensitivity, while Chinese EV manufacturers' flagship tiers show the least.
Supply Chain Analysis
Polyol feedstock supply rests on Japanese, Chinese, and South Korean petrochemical producers, creating concentrated dependency for polyurethane foam chemistry. Raw material flows draw from high-tensile steel mills, aluminum extrusion facilities, and phosphorus-based flame retardant specialists. Single-source vulnerability in foam chemical inputs exposes suppliers to plant turnaround disruptions. Distribution runs through just-in-time module delivery networks serving Chennai-Pune and Yangtze River Delta assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific automotive seat supply is consolidating around integrated manufacturers with captive OEM relationships and R&D depth in lightweight architectures. GB standard tightening and EV platform qualification barriers are forcing mid-scale fabricators toward exit or acquisition.
For Market Incumbents: To counter margin compression from annual OEM pricing agreements, deepen backward integration into high-tensile steel sourcing and friction-stir welding capabilities. Secure JIS certification pre-qualification for ASEAN-bound shipments to compress METI timeline friction by four to six months. For New Entrants and Emerging Players: The premium-economy price-point gap in Vietnam and Indonesia assembly greenfields offers first-mover positioning where mature seating supply bases remain absent. Target modular trim replacement systems for India's compressed three-year fleet warranty cycles. Lead with bio-based polyurethane chemistry to meet dual carbon procurement directives from Chinese and South Korean OEMs. For Investors and Strategic Acquirers: Re-rating potential sits with R&D-intensive frame engineering specialists given thin-profile z-height reduction demands across compact EV platforms. Long-term viability favors manufacturers with demonstrated GB-BIS-METI multi-certification track records. Watch for EV platform consolidation announcements as inflection indicators for seat module procurement authority concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Sourcing | High-tensile steel mills in Jiangsu province anchor frame weld protocol control for Yangtze Delta suppliers. |
| JIS Certification Pre-Qualification | METI export requirements shape component eligibility for ASEAN-bound shipments from Aichi prefecture. |
| Bio-Based Polyurethane Transition | Plant-derived polyol feedstocks align with Japan-South Korea dual carbon procurement directives. |
| Thin-Profile Frame R&D Investment | 20-30mm z-height reductions reward suppliers serving SAIC Motor and BYD compact EV architectures. |
| Just-in-Time Delivery Network Expansion | Chennai-Pune corridor concentration generates localized demand surges for Maruti Suzuki and Hyundai Motor India. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads combined with SAMR GB standard documentation, METI JIS certification records, and BIS anchorage test protocols. Vehicle production databases and IHS Markit registration data provided shipment verification. Bottom-up seat module unit economics and top-down automotive production forecasts were triangulated for consistency.
Data-stream reconciliation across material type, seat type, end user, and installation type segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to verified baseline values. Content per vehicle and propulsion architecture variations informed industry-specific forecast inputs throughout the modeling period.
Inputs from regulatory agencies and trade associations were available through the study window; gaps in real-time steel and aluminum price series introduce uncertainty bands around frame component cost assumptions. Forecasts reflect documented assumptions about EV platform launch schedules and GB standard enforcement timelines. Regulatory divergence between SAMR, METI, and BIS frameworks warrants ongoing watch as a revision trigger.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Automotive Cowl Panel Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Power Sunroof Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market