
 Automotive Console Box Market | 2026-2036
Automotive Console Box Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Console Box Market Outlook
Premium-grade console specifications with integrated wireless charging and soft-touch surfaces is redrawing competitive priorities for interior suppliers. Continental AG leverages its electronics-integration expertise to anchor high-value cockpit module contracts. Yanfeng International Automotive Technology Co. Ltd. dominates China-centric OEM programs through manufacturing scale and localized engineering. Faurecia SA differentiates via sustainable material portfolios that align with European OEM decarbonization targets.
An automotive console box is a structural cockpit component, typically manufactured through injection-molded thermoplastics or compression-formed composites with wall thicknesses of 2.5–4.0 mm, designed to house storage compartments, electronic interfaces, and climate controls between vehicle occupants. Center console configurations generate the largest revenue pool due to their central placement and electronics density, while wireless charging consoles represent the fastest-expanding feature category as smartphone integration becomes standard. Plastic materials maintain volume leadership through cost-engineering, though leather and wood trim variants capture disproportionate margin in premium vehicle segments.
EPA fuel-economy standards and NHTSA safety regulations in the United States compel weight reduction in interior components, directly influencing composite material selection for console boxes. ECHA REACH restrictions on volatile organic compounds constrain adhesive and coating formulations used in European-sourced console assemblies. China's GB standards for in-vehicle electromagnetic compatibility add certification layers for connectivity-integrated console designs. Stakeholders must monitor evolving material compliance thresholds and electronics-integration requirements across these regulatory jurisdictions to preserve market access and avoid redesign cycles.
Market Dynamics
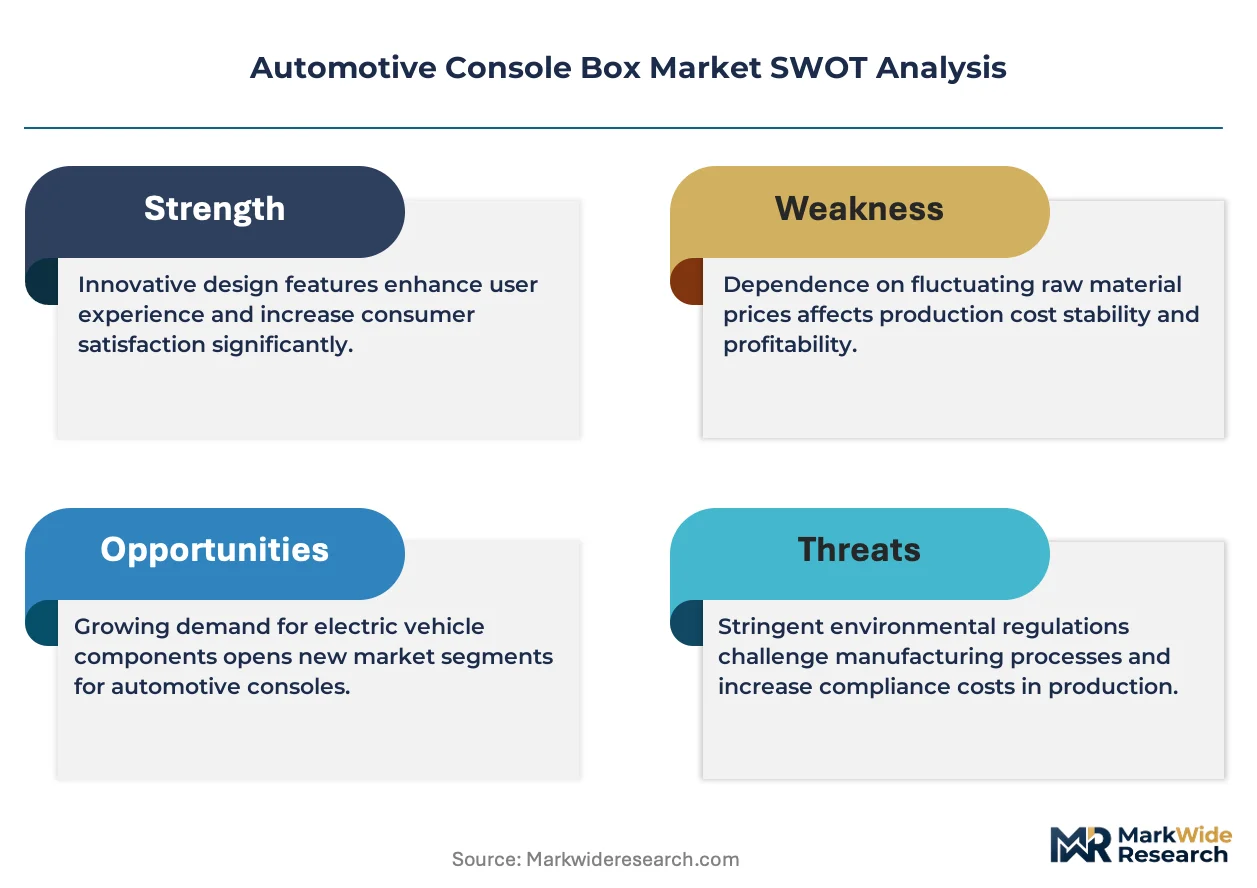
Electronics integration into cockpit architecture is compressing console box margins while elevating supplier technical requirements, as OEMs demand unified modules combining storage, charging, and thermal management in single assemblies.
Growth Catalysts
- EPA fuel-economy mandates:NHTSA-aligned weight reduction targets in the United States accelerate composite material substitution in console structures, expanding addressable volume for lightweight thermoplastic suppliers.
- Biometric storage integration:Luxury OEMs in Germany and Japan are specifying fingerprint-activated compartments, creating premium tier demand for security-enhanced console configurations.
- MIIT dual carbon policy:China's manufacturing decarbonization framework compels domestic OEMs to source recycled-content console assemblies, opening specification windows for sustainable material providers.
Market Restraints
- Polypropylene price volatility:Crude-linked resin costs swing console box margins unpredictably, forcing Tier-1 suppliers to absorb input spikes or renegotiate annual contracts.
- Tooling concentration in East Asia:Injection mold fabrication clusters heavily in China's Yangtze Delta and South Korea's Gyeonggi Province, creating single-source vulnerability for European and North American console programs.
- REACH adhesive restrictions:ECHA volatile organic compound limits constrain bonding chemistries for leather-wrapped console variants, extending European product development cycles.
Strategic Opportunities
- India's premium vehicle ramp:Domestic luxury OEM programs in Pune and Chennai remain underpenetrated by integrated console module suppliers, offering first-mover positioning for cockpit integrators.
- Wireless charging standardization:Qi2 protocol convergence with vehicle power electronics creates specification pull for OEMs seeking supplier-consolidated charging-storage modules.
- EU Green Deal procurement:CSRD-linked supplier sustainability scoring elevates console manufacturers with verified recycled content and carbon-accounted logistics.
Industry Challenges
- Mechatronics talent scarcity:Console suppliers compete with consumer electronics and medical device sectors for firmware engineers capable of integrating capacitive touch, haptic feedback, and thermal sensors.
- GB/T electromagnetic compatibility certification:China's in-vehicle radio frequency standards add 4-6 month validation timelines for connectivity-integrated console designs, compressing program launch windows.
- Legacy platform integration:12V electrical architectures in existing vehicle fleets constrain feature rollout for 48V-dependent advanced console electronics, forcing dual-development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Console Box Market |
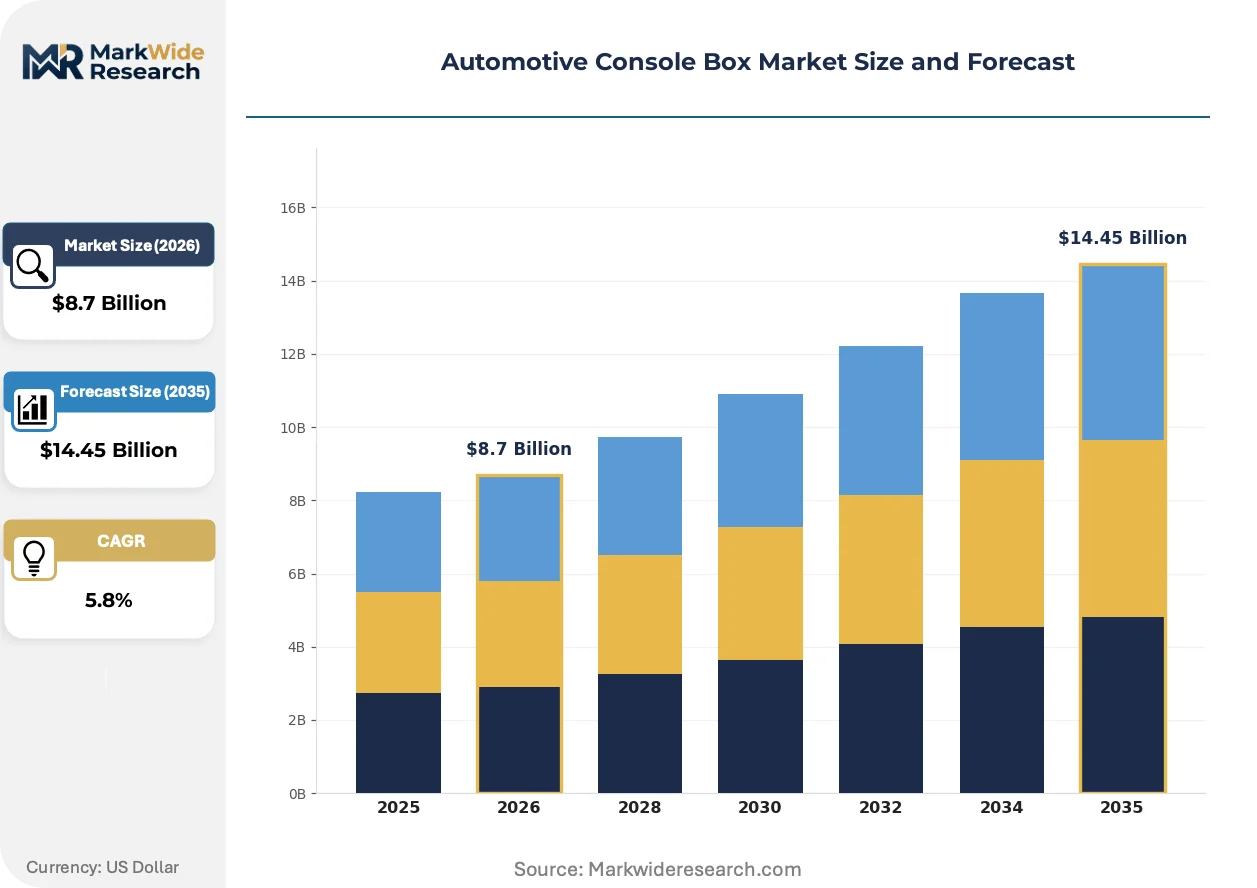
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Center Console, Overhead Console, Armrest Console, Wireless Charging Console Material: Plastic, Metal, Leather, Wood End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Feature: Storage Space, Connectivity Options, Customization, Safety Features |
| Companies Covered | Continental AG, Alps Electric Co. Ltd., Faurecia SA, Yanfeng International Automotive Technology Co. Ltd., Calsonic Kansei Corp., Lear Corporation, AGM Automotive LLC, Grammer AG, Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Console Box Market Strategic Shifts
Active grille shutter technology and thermal management integration are redefining console box functional scope, as climate control hardware migrates from dashboard to center tunnel architecture.
Thermoplastic composite formulations with continuous glass fiber reinforcement are fragmenting traditional metal bracket supply chains in console structural applications. Tier-1 seating suppliers in Michigan and Stuttgart are qualifying these materials for load-bearing hinge and latch mechanisms. The shift is fragmenting established stamping and welding equipment investments across interior component manufacturing footprints.
REACH substance restrictions on phthalate plasticizers and heavy metal pigments are tightening formulation specifications for soft-touch console surfaces. European compounders in Belgium and the Netherlands are accelerating bio-based TPU development to maintain specification access. Luxury vehicle programs with extended leather-trim console options face disproportionate reformulation cost exposure under these evolving ECHA thresholds.
Fleet procurement centralization among ride-hailing operators and corporate leasing pools is compressing console specification diversity. Buyers in São Paulo and Jakarta are standardizing on single trim grade across vehicle classes to simplify parts logistics and reduce downtime. This concentration is marginalizing premium console variants in volume-focused B-segment and C-segment vehicle configurations.
Automotive Console Box Market Segmentation
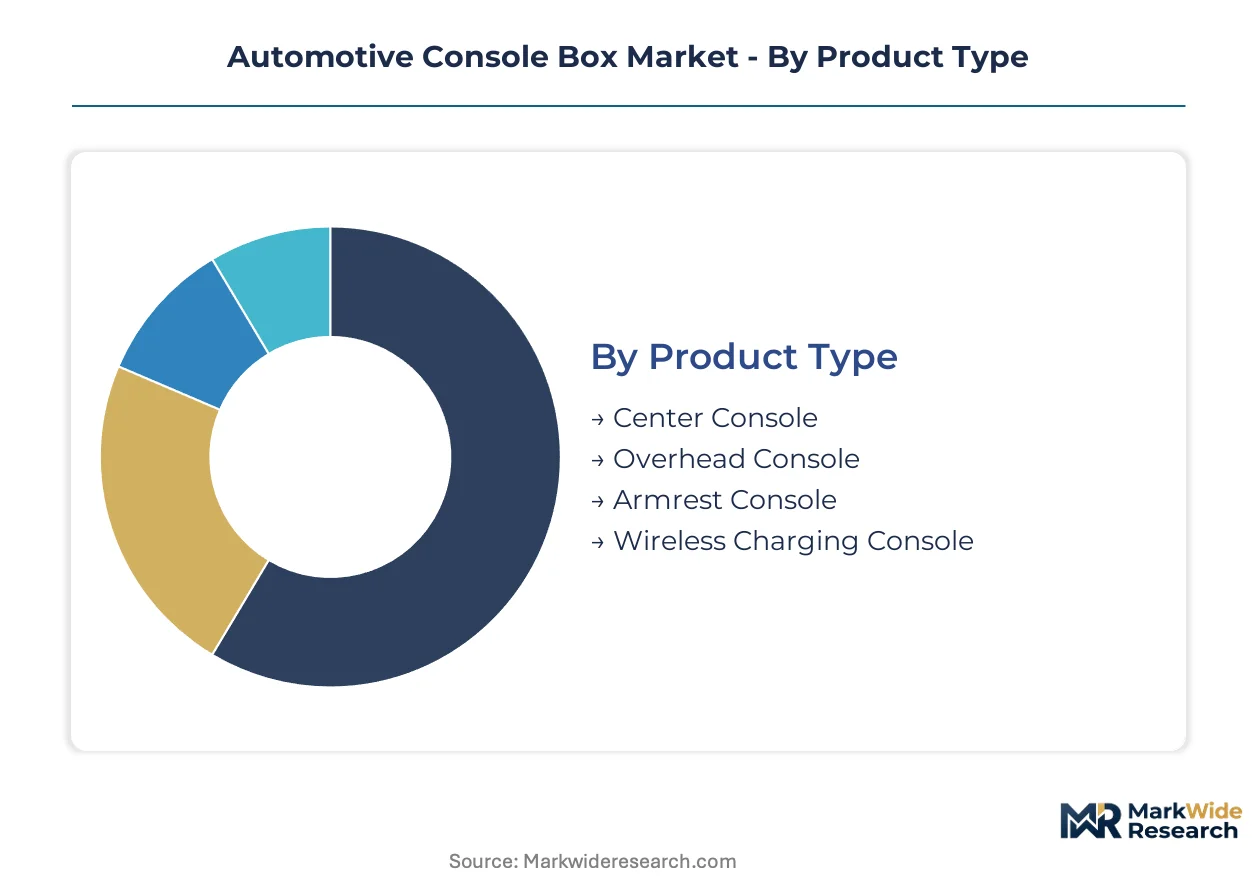
Console box configurations diverge sharply across vehicle price tiers, with material selection and electronics density determining supplier margin structures. Understanding segment boundaries clarifies where engineering investment yields sustainable pricing power versus commodity exposure.
Product Type:
Margin pools concentrate in configurations commanding central cockpit placement and integrated electronics modules.
- Center Console:Injection-molded thermoplastic assemblies with 2.5–4.0 mm wall thickness house storage compartments, climate controls, and USB interfaces between front occupants. German and Japanese luxury OEMs specify soft-touch surfaces and biometric latches here, extracting premium pricing through unified module consolidation.
- Wireless Charging Console:Qi2-protocol integrated units combine inductive power pads with thermal management and capacitive touch interfaces. Demand concentrates in United States electric vehicle platforms where smartphone integration has become standard equipment, forcing Tier-1 suppliers to absorb firmware development costs.
- Overhead Console:Roof-mounted variants incorporate dome lighting, sunglasses storage, and microphone arrays for voice control.
- Armrest Console:Hinged-lid designs with sliding mechanisms prioritize ergonomic adjustability over electronics density.
The dominant share belongs to Center Console, while Wireless Charging Console is closing the gap fastest.
Material:
Cost tiers stratify sharply between mass-market thermoplastics and specification-controlled premium finishes.
- Plastic:Polypropylene and ABS formulations dominate volume through injection molding cost efficiency, though crude-linked resin volatility compresses margins unpredictably. EPA-aligned weight reduction targets in the United States accelerate glass-fiber reinforced thermoplastic substitution for structural brackets.
- Leather:Nappa and semi-aniline hides wrapped over foam substrates command disproportionate margin in premium segments. ECHA REACH restrictions on volatile organic compounds in European adhesive formulations extend development cycles for these variants.
- Metal:Aluminum stampings and magnesium die-castings retain position in hinge mechanisms and latch hardware.
- Wood:Veneer and open-pore finishes satisfy heritage luxury positioning in limited production runs.
Plastic maintains volume leadership, though Leather captures the steepest margin expansion trajectory.
End User:
Procurement concentration determines contract structure complexity and technical qualification barriers.
- OEMs:Vehicle manufacturers in Stuttgart and Toyota City specify integrated cockpit modules combining console boxes with instrument panels and displays. These programs demand consolidated supplier responsibility for electronics integration, thermal management, and crash safety validation.
- Tier-1 Suppliers:Seating and interior module specialists in Michigan source console subassemblies for just-in-sequence delivery to final assembly plants. Their procurement power concentrates specification authority for material grades and surface finishes.
- Aftermarket Providers:Independent distributors serve collision repair and vehicle customization channels with lower technical entry barriers.
- Vehicle Assemblers:Contract manufacturers in emerging production hubs purchase pre-validated console modules to minimize engineering overhead.
OEMs dominate specification authority, while Tier-1 Suppliers are consolidating procurement influence fastest.
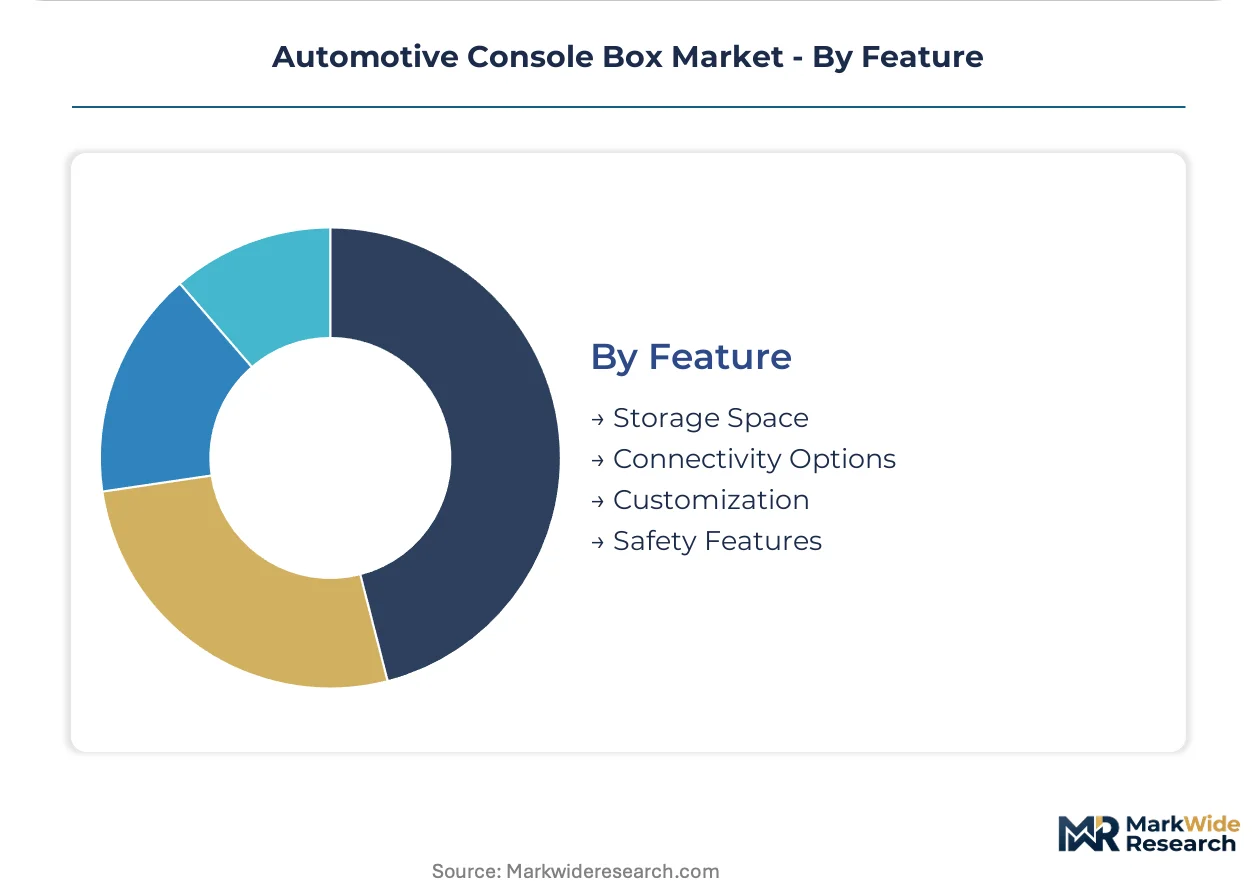
Feature:
Functional prioritization separates fleet-standard configurations from retail-customer premium offerings.
- Storage Space:Compartment volume, cup holder arrays, and cooled bins address practical utility requirements. Ride-hailing fleet operators in São Paulo and Jakarta standardize on single storage-grade specification to simplify logistics, compressing variant diversity.
- Connectivity Options:USB-C ports, wireless charging pads, and antenna integration for vehicle-to-device communication represent the fastest-expanding engineering priority. China's GB/T electromagnetic compatibility standards add validation timeline pressure for these configurations.
- Customization:Interchangeable trim panels and ambient lighting programming serve retail customer preference segmentation.
- Safety Features:Impact-absorbing structures and airbag deployment clearances meet NHTSA crashworthiness protocols.
Storage Space retains installed base dominance, while Connectivity Options is gaining specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injection mold fabrication clusters heavily in China's Yangtze Delta and South Korea's Gyeonggi Province, creating single-source vulnerability for European and North American console programs. OEMs in Stuttgart, Toyota City, and Detroit specify integrated cockpit modules that demand consolidated supplier responsibility across multiple jurisdictions.
United States
EPA fuel-economy mandates and NHTSA-aligned weight reduction targets accelerate composite material substitution in console structures. Domestic OEMs in Michigan prioritize connected cockpit modules for electric vehicle platforms. Detroit-based Tier-1 seating suppliers qualify glass-fiber reinforced thermoplastics for load-bearing hinge mechanisms.
Germany
Luxury automakers expand premium center console configurations with integrated wireless charging and biometric storage. ECHA REACH restrictions on volatile organic compounds constrain adhesive formulations for leather-wrapped variants. Stuttgart-headquartered OEMs specify unified modules combining storage, charging, and thermal management.
China
MIIT dual carbon goals accelerate lightweight material substitution in console manufacturing while GB/T electromagnetic compatibility standards add validation timelines. Domestic OEMs source recycled-content console assemblies under manufacturing decarbonization frameworks. Yangtze Delta mold fabrication clusters concentrate tooling investment for global console programs.
Japan
Luxury OEMs in Toyota City specify fingerprint-activated compartments, creating premium tier demand for security-enhanced configurations. METI industrial policy supports advanced materials development for cockpit integration. Kanto-based electronics suppliers anchor high-value module contracts for biometric-enabled console variants.
India
Domestic luxury OEM programs in Pune and Chennai remain underpenetrated by integrated console module suppliers. BIS standards for automotive components add certification requirements for imported assemblies. Tamil Nadu-based vehicle assemblers purchase pre-validated console modules to minimize engineering overhead.
Automotive Console Box Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered supplier structure. Electronics-integrated cockpit modules command premium positioning while commodity thermoplastic suppliers compete on scale and logistics efficiency. Three archetypes dominate: diversified automotive Tier-1s with cockpit integration capabilities, specialized interior module suppliers with regional manufacturing scale, and materials-focused compounders with sustainable formulation portfolios. Consolidation through strategic partnerships and vertical integration into firmware development represent the dominant competitive moves.
Among Germany-based diversified suppliers, Continental AG exemplifies the electronics-integration archetype, while Faurecia SA occupies a position within the sustainable materials tier. Yanfeng International Automotive Technology Co. Ltd. represents the China-centric scale-driven archetype dominating domestic OEM programs through localized engineering. These three anchors illustrate the geographic and capability segmentation that defines supplier positioning across premium and volume vehicle segments.
| Leading Market Players |
|---|
| Continental AG |
| Alps Electric Co. Ltd. |
| Faurecia SA |
| Yanfeng International Automotive Technology Co. Ltd. |
| Calsonic Kansei Corp. |
| Lear Corporation |
| AGM Automotive LLC |
| Grammer AG |
| Magna International Inc. |
| Others |
Value Chain & Pricing Dynamics
Injection mold capacity utilization in China's Yangtze Delta and South Korea's Gyeonggi Province anchors both supply concentration and price floors for console box manufacturing. Scale economies at these fabrication clusters compress unit costs for thermoplastic assemblies while elevating switching costs for OEMs seeking dual-source qualification.
Pricing Analysis
EPA fuel-economy mandates dictate the pricing tier structure across the United States market, separating glass-fiber reinforced thermoplastic specifications from commodity polypropylene grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with Qi2-protocol wireless charging modules commanding premium positioning. Cost compression in standard-grade plastic consoles is intensifying because crude-linked resin volatility forces Tier-1 suppliers to absorb margin erosion. Fleet procurement operators in São Paulo and Jakarta exhibit highest price sensitivity, while German luxury OEMs in Stuttgart show least sensitivity to biometric-enabled premium configurations.
Supply Chain Analysis
Port congestion along the Shanghai-Ningbo corridor and container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for European and North American console programs. Manufacturing gravity centers on China, South Korea, and Germany, with mold fabrication and electronics integration capabilities concentrated in these jurisdictions. Raw material dependencies rest on polypropylene resin, continuous glass fiber reinforcement, and bio-based TPU compounds for soft-touch surfaces. Single-source vulnerability in Yangtze Delta tooling clusters creates structural risk for global OEM programs. Distribution runs through just-in-sequence delivery networks anchored by Tier-1 seating suppliers in Michigan and Stuttgart.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronics integration into cockpit architecture fragments established supply relationships, creating niche entry points for specialists combining firmware development with thermoplastic manufacturing scale.
For Market Incumbents: Consolidate procurement influence through captive mold fabrication investments in South Korea's Gyeonggi Province or backward integration into glass-fiber compound production. Defend against emerging Chinese electronics integrators by securing Qi2 protocol certification ahead of standardization convergence. Prioritize firmware engineering capacity in Kanto and Stuttgart development centers to maintain specification authority with German and Japanese luxury OEMs. For New Entrants and Emerging Players: Lead with sustainable material portfolios targeting EU Green Deal procurement criteria and CSRD-linked supplier sustainability scoring. India's domestic luxury OEM programs in Pune and Chennai represent the most penetrable geography, with BIS certification requirements creating qualification barriers that favor first movers establishing local engineering presence. Position through recycled-content console assemblies aligned with MIIT dual carbon policy frameworks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors materials-focused compounders with verified bio-based TPU development capabilities and carbon-accounted logistics infrastructure. Long-term viability hinges on differentiation from commodity thermoplastic suppliers facing margin compression from resin volatility. Acquisition target archetype: mid-scale interior module suppliers with established OEM relationships but limited electronics integration capabilities. Signal to watch: GB/T electromagnetic compatibility certification timelines extending program launch windows, favoring suppliers with pre-validated connectivity-integrated designs.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Unifies console module specifications across electric vehicle architectures, reducing engineering overhead for Detroit-based OEMs. |
| Battery Supply Agreement | Secures 48V power electronics capacity for advanced console features, bypassing legacy 12V architecture constraints. |
| Software-Defined Vehicle Investment | Integrates capacitive touch and haptic feedback firmware into consolidated cockpit modules for Toyota City luxury programs. |
| Geographic Manufacturing Footprint | Establishes mold fabrication presence in Tamil Nadu to serve India's underpenetrated domestic OEM assembly plants. |
| Charging Infrastructure Partnership | Aligns Qi2 protocol development with vehicle power electronics roadmaps for United States electric vehicle platforms. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations managers; and secondary validation against vehicle production databases, IHS Markit registration data, customs records for resin and composite imports, and SEC filings from listed automotive suppliers. Bottom-up modeling of console content per vehicle by propulsion architecture and OEM tier triangulated against top-down market value reconstruction.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from trend extrapolation of electronics integration rates and lightweight material substitution patterns, cross-referenced against EPA fuel-economy compliance trajectories and MIIT dual carbon policy implementation timelines. Forecast inputs included glass-fiber reinforced thermoplastic adoption curves and Qi2 protocol penetration rates in premium vehicle segments.
Forecasts assume regulatory continuity in EPA, ECHA REACH, and MIIT frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Mlccs for Automotive Electronics Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Automotive AR HUD Market