
 Automotive Center Stack Display Market | 2026-2036
Automotive Center Stack Display Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Center Stack Display Market Outlook
Electric vehicle cabin digitization is shifting procurement priorities toward unified center stack modules. Samsung Display leverages its OLED panel expertise to anchor supply relationships with premium EV programs. Continental AG competes through its integrated cockpit domain controller architecture that bundles display, haptics, and software layers. Robert Bosch GmbH specializes in thermal management and optical bonding processes that sustain display clarity under extreme automotive operating conditions.
Automotive center stack displays are multifunctional human-machine interface panels mounted in the vehicle dashboard median, typically incorporating capacitive touch layers, anti-reflective coatings, and operating temperature ranges from minus 40 to 85 degrees Celsius to manage navigation, infotainment, and climate systems. Touchscreen displays dominate volume shipments while OLED technology captures expanding share in luxury and electric vehicle segments where contrast ratio and form factor flexibility command premium positioning. TFT panels maintain cost-sensitive mass-market applications across OEM and Tier-1 supplier channels.
NHTSA distraction guidelines and FMVSS compliance requirements shape display placement, response latency thresholds, and driver attention management protocols in the United States. Europe's Ecodesign Directive and REACH substance restrictions constrain adhesive, backlight, and semiconductor material selections for center stack assemblies sold across EU member states. Stakeholders must monitor evolving cybersecurity standards for connected vehicle interfaces as regulatory bodies integrate display systems into broader vehicle-type approval frameworks.
Market Dynamics
Passenger vehicle electrification is compressing center stack design cycles from five-year refreshes to two-year over-the-air update cycles, forcing display suppliers to modularize hardware layers for software-defined cabin architectures.
Growth Catalysts
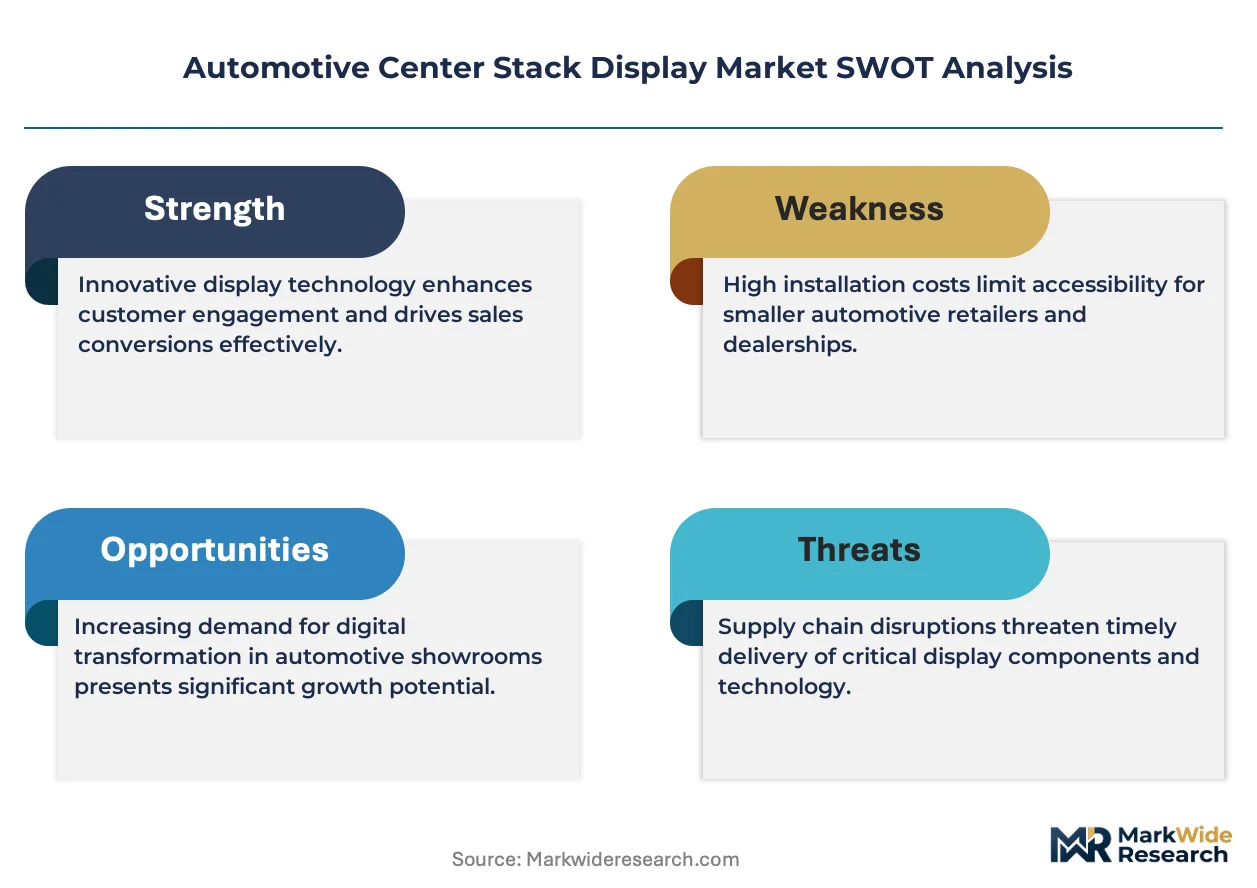
- EV cabin digitization mandates:China's MIIT new energy vehicle certification protocols now require integrated human-machine interface compliance, compelling domestic OEMs to specify premium display modules as standard equipment.
- REACH substance phase-outs:Europe's ECHA restrictions on hexavalent chromium in display bonding adhesives are accelerating adoption of laser-welded optical stacks that eliminate chemical fasteners entirely.
- OLED form factor flexibility:Curved and free-form display geometries enabled by plastic substrate technology are penetrating luxury electric vehicle segments where dashboard integration demands non-rectangular screen configurations.
Market Restraints
- Indium supply concentration:Over 80 percent of indium tin oxide feedstock for transparent conductive layers originates from Chinese smelter complexes, exposing display manufacturers to export quota volatility.
- Thermal management capex:Automotive-qualified OLED panels require active cooling subsystems operating at minus 40 to 85 degrees Celsius, doubling module cost structures versus consumer-grade alternatives.
- NHTSA distraction compliance:Response latency thresholds below 250 milliseconds for touch inputs impose firmware validation burdens that extend development timelines by eight to fourteen months.
Strategic Opportunities
- Software-defined vehicle architectures:Domain controller consolidation is creating demand for zonal display hubs that aggregate multiple cabin functions through single high-resolution panels.
- India PLI scheme incentives:Production-linked incentive allocations for automotive electronics manufacturing are attracting display module assembly investments targeting domestic OEM supply chains.
- Haptic feedback integration:Ultrasonic surface actuation technology converging with capacitive touch layers enables eyes-off operation that satisfies emerging European type-approval requirements for driver attention management.
Industry Challenges
- Optical bonding skill scarcity:Vacuum lamination technicians capable of eliminating air gaps between display and cover glass without particle contamination command premium wages exceeding 40 percent above regional manufacturing averages.
- Cybersecurity certification timelines:UN R155 vehicle-type approval for connected display interfaces requires penetration testing protocols that add nine to twelve months to program validation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Center Stack Display Market |
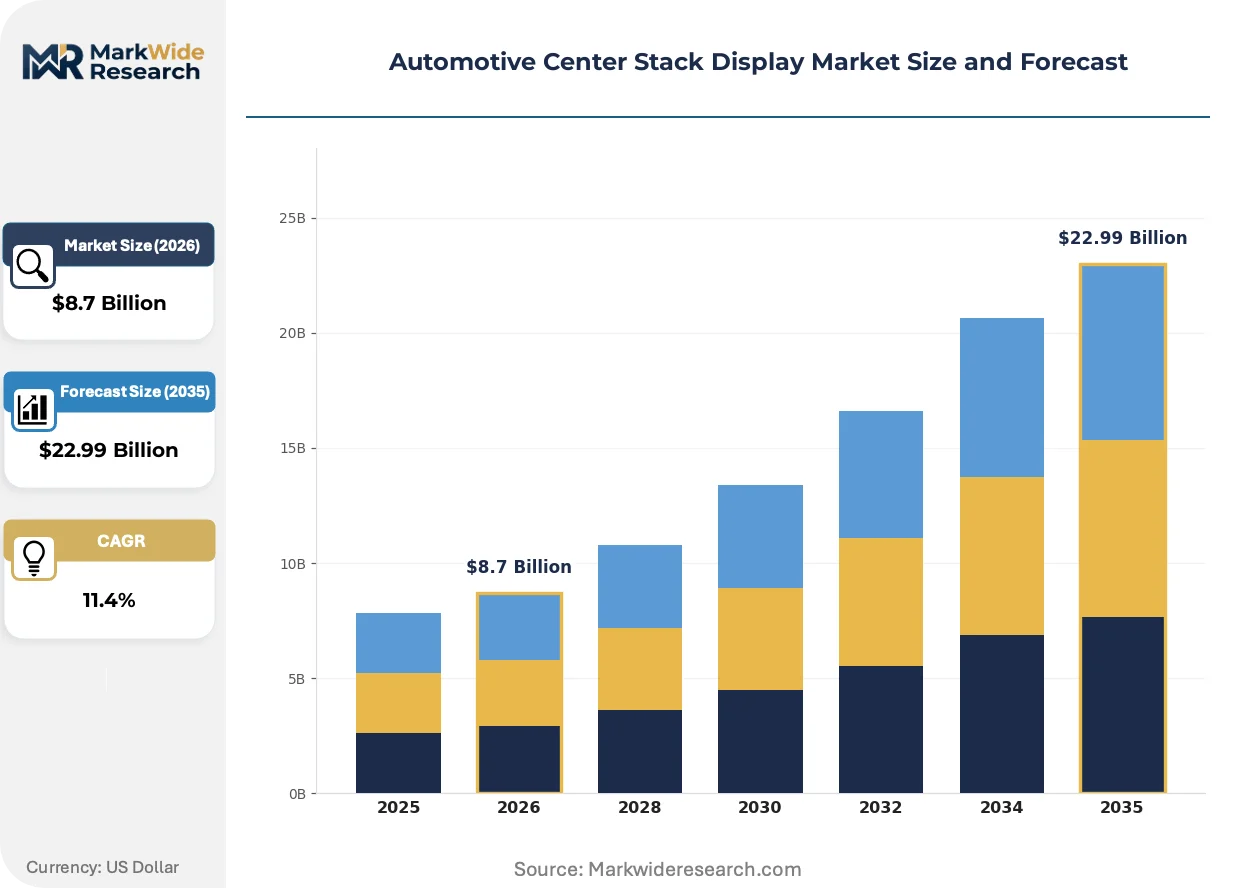
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen Displays, LCD Displays, LED Displays, Analog Displays Technology: OLED, TFT, QLED, E-Ink End User: OEMs, Aftermarket Providers, Automotive Tier-1 Suppliers, Vehicle Assemblers Feature: Navigation Systems, Audio Controls, Climate Controls, Connectivity Options |
| Companies Covered | Samsung Display, Magna International, Continental AG, Denso, Alpine Electronics, Visteon Corporation, Robert Bosch GmbH, LG Display, Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Center Stack Display Market Strategic Shifts
Automotive center stack technology is bifurcating between cost-optimized TFT platforms for mass-market internal combustion vehicles and premium OLED architectures for electric vehicle cabins, with intermediate technologies struggling to justify positioning.
Local dimming mini-LED backlights are overtaking conventional edge-lit configurations in upper-midrange electric vehicle programs. Mercedes-Benz EQS and BMW iX platforms specify thousands of discrete dimming zones that deliver OLED-contrast performance without burn-in susceptibility. This backlight architecture is compressing the price-performance gap that previously separated premium OLED from commodity TFT supply tiers.
Europe's F-Gas Regulation phasedown of hydrofluorocarbon refrigerants is forcing thermal management redesigns for display cooling loops. Automotive suppliers must validate CO2-based heat pump integration that maintains panel operating temperatures below 35 degrees Celsius during rapid charging cycles. German KBA type-approval timelines have extended six months as OEMs document alternative refrigerant compatibility across cabin electronics.
Fleet procurement of standardized display modules is displacing bespoke OEM-specific designs in commercial vehicle segments. Daimler Truck and Volvo Group have consolidated center stack specifications across multiple nameplates, forcing Tier-1 suppliers to absorb customization costs within volume pricing structures. This concentration is most visible in European long-haul tractor programs where total cost of ownership calculations dominate specification decisions.
Automotive Center Stack Display Market Segmentation
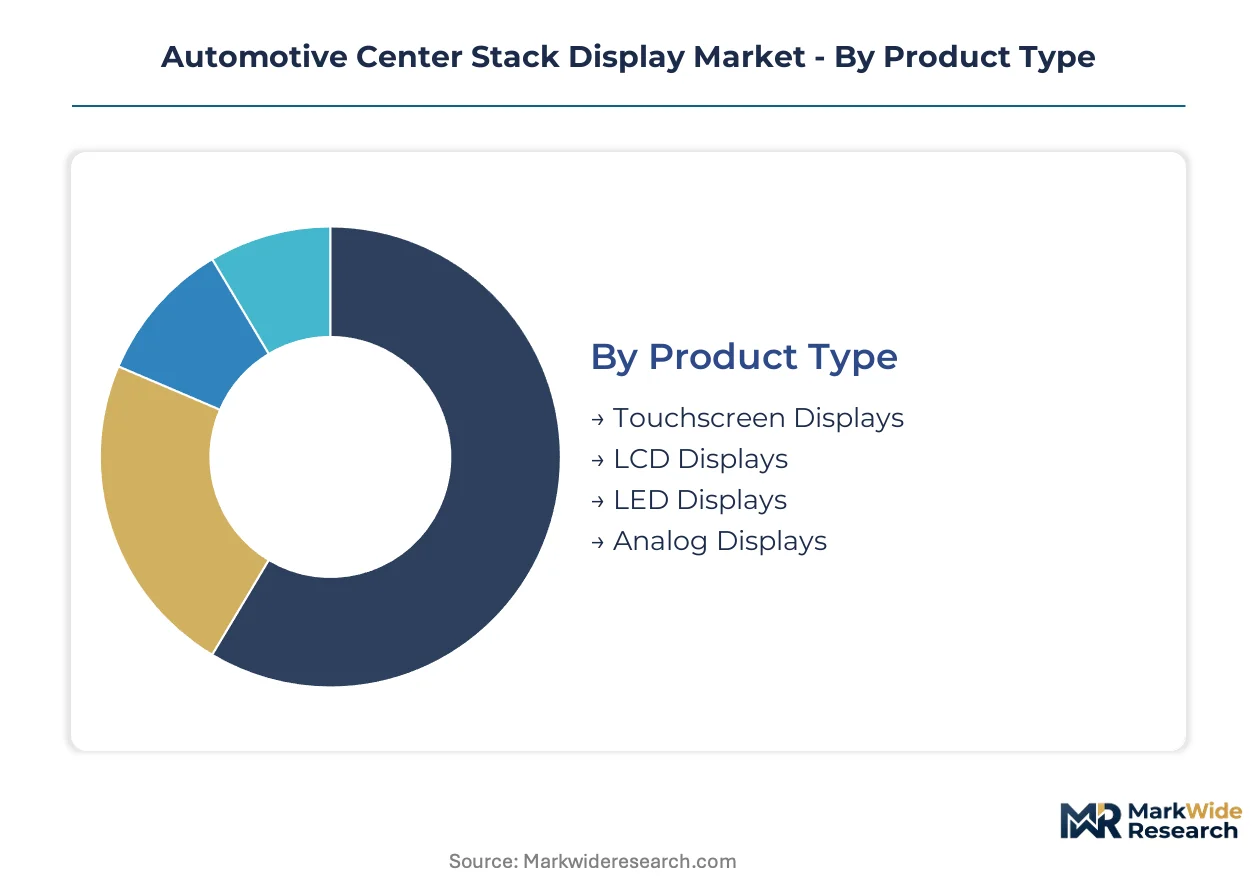
Center stack display procurement splits sharply between standardized modules for high-volume programs and customized solutions for luxury differentiation. Segmentation reveals how material choices, integration depth, and functional scope reshape supplier margins across passenger vehicle electrification.
Product Type:
Customization intensity varies from fully bespoke curved OLED assemblies to commodity TFT panels shared across multiple nameplates.
- Touchscreen Displays:Capacitive multi-layer panels with projected capacitive touch controllers dominate EV cabin architectures. China's domestic EV brands specify these as standard equipment under MIIT certification protocols, compressing refresh cycles to two-year software-defined update windows.
- LCD Displays:Twisted nematic and in-plane switching variants retain cost-sensitive mass-market positioning. European long-haul commercial fleets consolidate specifications across nameplates, forcing Tier-1 suppliers to absorb customization costs within volume pricing.
- LED Displays:Direct-view LED matrices serve heavy-duty commercial segments requiring extreme brightness for outdoor visibility.
- Analog Displays:Physical gauge clusters persist in emerging market entry vehicles where electromagnetic interference resilience outweighs digitization pressure.
Leading the category by volume: LCD Displays. Growing fastest: Touchscreen Displays.
Technology:
Cost tiers separate premium self-emissive architectures from backlit transmissive alternatives, with intermediate mini-LED configurations compressing the price-performance gap.
- OLED:Plastic substrate technology enables curved and free-form geometries for luxury electric vehicle cabins. Active cooling subsystems operating across minus 40 to 85 degrees Celsius thermal ranges double module cost structures versus consumer-grade alternatives.
- TFT:Amorphous silicon and low-temperature polysilicon backplanes anchor high-volume production for internal combustion vehicle programs. Indium tin oxide feedstock concentration in Chinese smelter complexes exposes manufacturers to export quota volatility.
- QLED:Quantum dot-enhanced films deliver expanded color gamut for upper-midrange electric vehicle segments seeking OLED visual performance without burn-in susceptibility.
- E-Ink:Bistable electrophoretic displays serve secondary information panels where sunlight readability and minimal power draw outweigh refresh rate requirements.
Highest margin concentration: OLED. Steepest expansion trajectory: QLED.
End User:
Integration depth determines whether display modules ship as standalone components or as consolidated cockpit domain controllers.
- OEMs:Vehicle manufacturers specifying premium center stacks increasingly demand unified modules bundling display, haptics, and software layers. Domain controller consolidation creates procurement leverage that compresses supplier margins.
- Aftermarket Providers:Retrofit specialists serve vehicle parc extension markets where aging fleet digitization outpaces replacement cycles. Regulatory fragmentation across type-approval jurisdictions constrains cross-border product portability.
- Automotive Tier-1 Suppliers:Continental AG and Robert Bosch GmbH intermediate between panel manufacturers and vehicle assemblers, absorbing optical bonding and thermal management integration risks.
- Vehicle Assemblers:Contract manufacturing operations in India leverage PLI scheme incentives to localize display module assembly for domestic OEM supply chains.
Dominant procurement channel: OEMs. Fastest-growing engagement model: Automotive Tier-1 Suppliers.
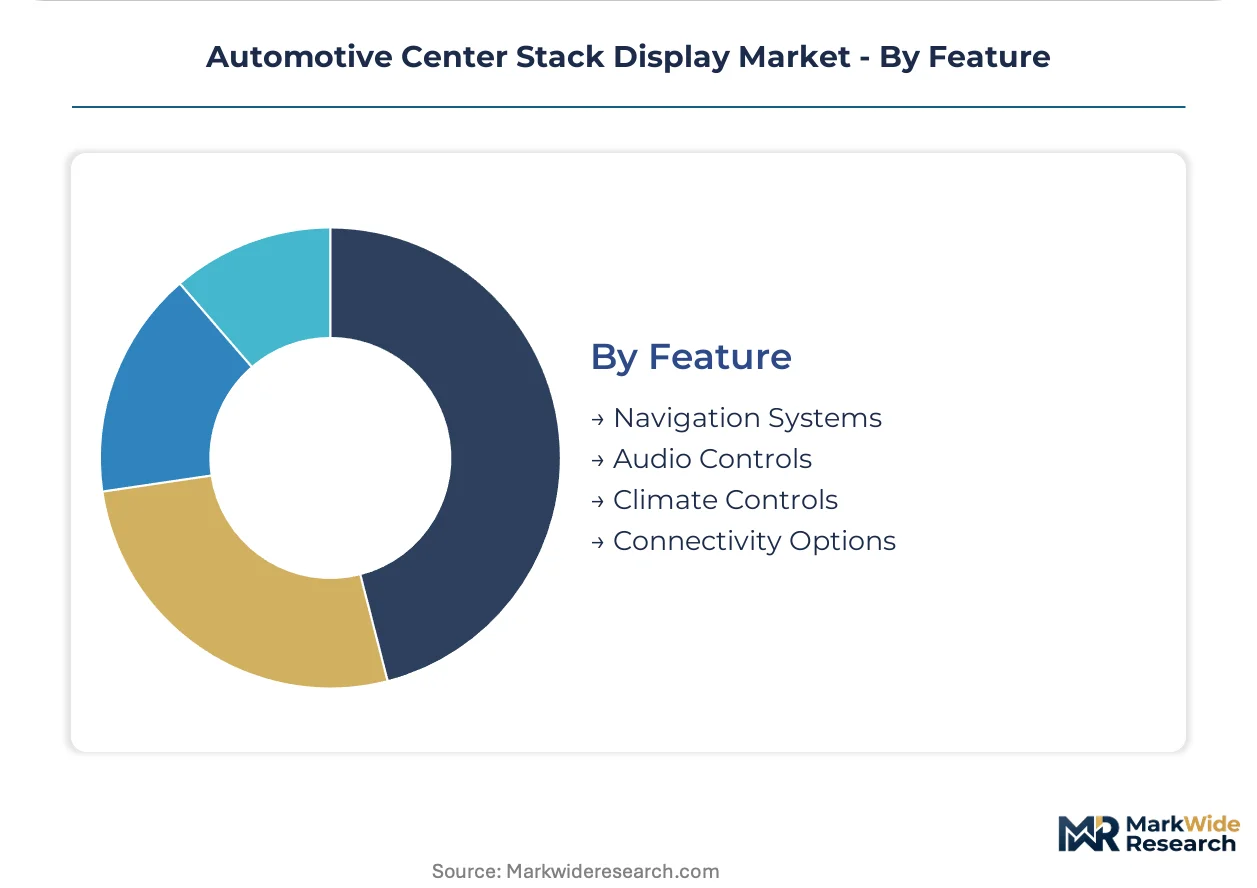
Feature:
Functional scope expansion drives display real estate allocation between mandated safety interfaces and discretionary infotainment.
- Navigation Systems:Real-time mapping and augmented reality overlays demand high-resolution panels with sub-250-millisecond touch response latency. NHTSA distraction guidelines impose firmware validation burdens extending development timelines.
- Audio Controls:Streaming service integration and spatial audio processing interfaces occupy secondary screen zones. Haptic feedback integration enables eyes-off operation satisfying emerging European type-approval requirements.
- Climate Controls:HVAC management interfaces migrate from physical knobs to touchscreen layers, increasing driver attention management complexity.
- Connectivity Options:Smartphone mirroring and vehicle-to-everything communication status displays require cybersecurity certification under UN R155 vehicle-type approval frameworks.
Largest functional footprint: Navigation Systems. Fastest feature integration: Connectivity Options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT new energy vehicle certification zones concentrate display procurement leverage. German KBA type-approval frameworks reshape thermal management compliance. India's PLI scheme allocations attract module assembly investments. South Korea's display technology clusters anchor OLED supply relationships.
China
Domestic EV brands specify premium OLED center stacks as standard equipment under MIIT certification protocols. SAMR enforces cybersecurity standards for connected vehicle interfaces. Shanghai and Shenzhen industrial corridors host display module integration facilities serving BYD and NIO supply chains.
Germany
Luxury OEMs demand curved and free-form display geometries for dashboard integration. KBA type-approval timelines extended six months as manufacturers document CO2-based heat pump compatibility. Stuttgart and Munich clusters concentrate Continental AG and Robert Bosch GmbH cockpit domain controller development.
United States
NHTSA distraction guidelines impose sub-250-millisecond touch response latency thresholds. FMVSS compliance requirements shape display placement and driver attention management protocols. Michigan and California automotive corridors host Tier-1 supplier validation laboratories.
India
Production-linked incentive allocations attract display module assembly investments targeting domestic OEM supply chains. BIS certification requirements constrain cross-border product portability. Tamil Nadu and Gujarat manufacturing zones localize supply for Mahindra and Tata Motors programs.
South Korea
OLED panel expertise anchors supply relationships with premium EV programs. MFDS frameworks govern material compliance for automotive electronics exports. Gyeonggi-do and Seoul Capital Area clusters concentrate Samsung Display and LG Display production facilities.
Automotive Center Stack Display Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. Display panel fabricators and cockpit integrators occupy distinct value chain positions. Three archetypes dominate: Korean display technology leaders, German cockpit domain specialists, and diversified Japanese electronics conglomerates. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Within the display technology tier, Samsung Display and LG Display occupy positions as Korean panel specialists leveraging OLED substrate capabilities. Continental AG exemplifies the German cockpit integration archetype, bundling display, haptics, and software layers. Robert Bosch GmbH represents thermal management and optical bonding specialization, sustaining display clarity under extreme automotive operating conditions.
| Leading Market Players |
|---|
| Samsung Display |
| Magna International |
| Continental AG |
| Denso |
| Alpine Electronics |
| Visteon Corporation |
| Robert Bosch GmbH |
| LG Display |
| Panasonic Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Korean chaebol-backed display specialists anchor module pricing through captive OLED substrate production, compressing margins for European cockpit integrators dependent on external panel sourcing. Sovereign wealth-funded Chinese manufacturers leverage indium tin oxide feedstock security to undercut spot-market procurement for TFT assemblies serving mass-market internal combustion programs.
Pricing Analysis
Premium lead-time pricing governs spot procurement for curved OLED assemblies serving German luxury EV platforms, while standardized TFT panels trade at volume discounts through two-year contract offtakes. Price differentiation centers on thermal management certification grade and optical bonding customization level. Cost compression in mid-range QLED configurations intensifies as mini-LED backlights narrow the performance gap with premium tiers. Mass-market OEM procurement teams exhibit highest price sensitivity, whereas luxury EV platform engineers prioritize form-factor flexibility over unit economics.
Supply Chain Analysis
Vacuum lamination technician scarcity in Shanghai and Shenzhen industrial corridors constrains optical bonding throughput for curved display assemblies. Manufacturing gravity centers on China, South Korea, and Germany for panel fabrication, cockpit integration, and thermal subsystem validation respectively. Supply chains draw from concentrated indium smelter complexes, polarizer film Japanese producers, and German adhesive specialists. Single-source vulnerability in transparent conductive oxide feedstock exposes Tier-1 suppliers to export quota disruption. Distribution runs through OEM direct procurement and Tier-1 supplier channels with limited aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive center stack procurement is becoming a vertical-integration race as panel fabricators push downstream into cockpit domain controllers and integrators seek upstream display technology access. Korean and Chinese producers are deploying captive OLED capacity to capture software-defined vehicle architecture value pools.
For Market Incumbents: Deploy haptic feedback integration capabilities to defend against ultrasonic surface actuation specialists entering from consumer electronics. Secure optical bonding technician pipelines through apprenticeship partnerships in Shanghai and Stuttgart industrial clusters. Absorb REACH-compliant adhesive development costs to preempt regulatory displacement of hexavalent chromium bonding chemistries. For New Entrants and Emerging Players: Launch via India PLI scheme manufacturing zones to intercept domestic OEM procurement localization mandates. Target commercial vehicle fleet standardization programs where Daimler Truck and Volvo Group consolidation creates volume entry points. Emphasize CO2 heat pump thermal management compatibility to exploit German KBA type-approval timeline extensions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap cockpit integrators with established OEM relationships in European luxury segments. Long-term viability rests on software-defined vehicle architecture positioning rather than hardware commodity exposure. Watch MIIT certification protocol evolution as inflection signal for Chinese domestic EV display specification intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Domain controller consolidation bundles display, haptics, and software layers into unified procurement packages. |
| Battery Supply Agreement | Thermal management subsystem sourcing secures panel operating temperature stability during rapid charging cycles. |
| Platform Standardization | Fleet procurement consolidation across Daimler Truck and Volvo Group compresses customization cost absorption. |
| Geographic Manufacturing Footprint | India PLI scheme incentives localize module assembly for Mahindra and Tata Motors domestic supply chains. |
| Charging Infrastructure Partnership | Vehicle-to-everything communication interfaces require UN R155 cybersecurity certification for connected display systems. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automotive center stack display market assessment. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and optical bonding technicians combined with vehicle production databases, MIIT certification registries, and KBA type-approval documentation. Bottom-up panel shipment aggregation and top-down cockpit system value triangulation validated segment-level outputs.
Granularity-level modeling distinguished touchscreen, LCD, LED, and analog display categories by technology tier, vehicle class, propulsion architecture, and regional production cluster across the analysis window. CAGRs derived from production volume trajectories and content-per-vehicle escalation curves for electrified platforms. Forecast inputs incorporated MIIT new energy vehicle certification protocol adoption rates and Ecodesign Directive material compliance phase-out schedules.
MIIT protocol revision, REACH substance restriction acceleration, and indium export quota volatility are the dominant revision risks to projection assumptions. Material deviation in named triggers warrants pause and re-evaluation of module demand and pricing trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Automotive Intelligent Lighting System Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market