
 Automotive Smart Seating Systems Market | 2026-2036
Automotive Smart Seating Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Seating Systems Market Outlook
ISO 26262 functional safety certification is bifurcating the supplier landscape into qualified tier-ones and excluded aspirants. Adient PLC leverages its vertical integration across foam chemistry and mechatronics to sustain program wins with premium German OEMs. Lear Corporation anchors North American supply through control of just-in-time seating assembly adjacent to major light-truck plants. Faurecia competes on smart fabric integration, embedding capacitive sensors directly into textile weaves rather than bolting on discrete modules.
Automotive smart seating systems combine electromechanical actuators, sensor arrays, climate-control elements, and embedded software to modulate occupant position, temperature, and pressure distribution in real time. Typical configurations integrate 8-16 motors per seat with CAN bus or Ethernet backbone connectivity to vehicle domain controllers, enabling centralized adjustment profiles and predictive comfort algorithms. Massaging seats command the highest value per unit among product type categories, while integrated sensors represent the fastest-expanding technology dimension as OEMs pursue occupant health monitoring and autonomous-ready interior sensing. Heated seats remain the most mature segment with compressed margins, whereas wireless connectivity modules are gaining share as over-the-air feature activation becomes a recurring revenue strategy.
NHTSA occupant classification mandates and EU General Safety Regulation crash-performance requirements shape structural design priorities and sensor redundancy levels for suppliers seeking multi-region approval. EPA and REACH jointly restrict flame-retardant chemistries and volatile organic compound emissions from seating materials, forcing reformulation of polyurethane foams and synthetic leather coatings. Stakeholders must monitor how pending FMVSS updates and EU AI Act liability frameworks for automated driving interiors will redefine the boundary between comfort feature and safety-critical system.
Market Dynamics
ISO 26262 functional safety certification is bifurcating the supplier landscape, separating qualified tier-one integrators from excluded aspirants as OEMs demand ASIL-rated seat control modules for autonomous vehicle interiors.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon propellants accelerates adoption of CO2-based foam blowing agents in polyurethane cushioning, forcing material reformulation across German and French supply bases.
- China's Yangtze River Delta cluster:Domestic EV brands specify heated and ventilated smart seats as standard equipment, concentrating procurement volume in Ningbo and Shanghai metropolitan manufacturing zones.
- Capacitive sensor arrays:Integration of health-monitoring electrodes into seat textiles enables predictive occupant wellness algorithms, creating new recurring revenue streams for system integrators.
Market Restraints
- Memory chip allocation:Automotive-grade microcontroller scarcity constrains motor control unit output, with tier-two suppliers facing 26-week lead times for Infineon and NXP components.
- Polyol price volatility:Propylene oxide feedstock fluctuations transmit directly to polyurethane foam costs, compressing margins for seating suppliers without backward integration into chemical production.
- REACH substance restrictions:ECHA classification of legacy flame retardants as SVHCs forces immediate reformulation of synthetic leather coatings, requiring multi-year requalification cycles with OEMs.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive electronics attract seating system assembly to Tamil Nadu and Gujarat, serving domestic OEMs and export markets.
- Over-the-air feature activation:Wireless connectivity modules enable subscription-based unlocking of massage and ventilation functions, transforming one-time hardware sales into recurring software revenue.
- Occupant classification sensor convergence:Integration of capacitive and pressure-sensing technologies into unified modules reduces wiring harness complexity while enabling NHTSA-compliant airbag deployment decisions.
Industry Challenges
- ASIL-D certification timelines:Functional safety validation for seat-based occupant detection systems requires 18-24 month development cycles, delaying program launches for non-incumbent suppliers.
- Legacy CAN bus integration:Smart seat architectures must maintain backward compatibility with 500 kbps vehicle networks while migrating to Ethernet backbone connectivity, doubling software validation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Seating Systems Market |
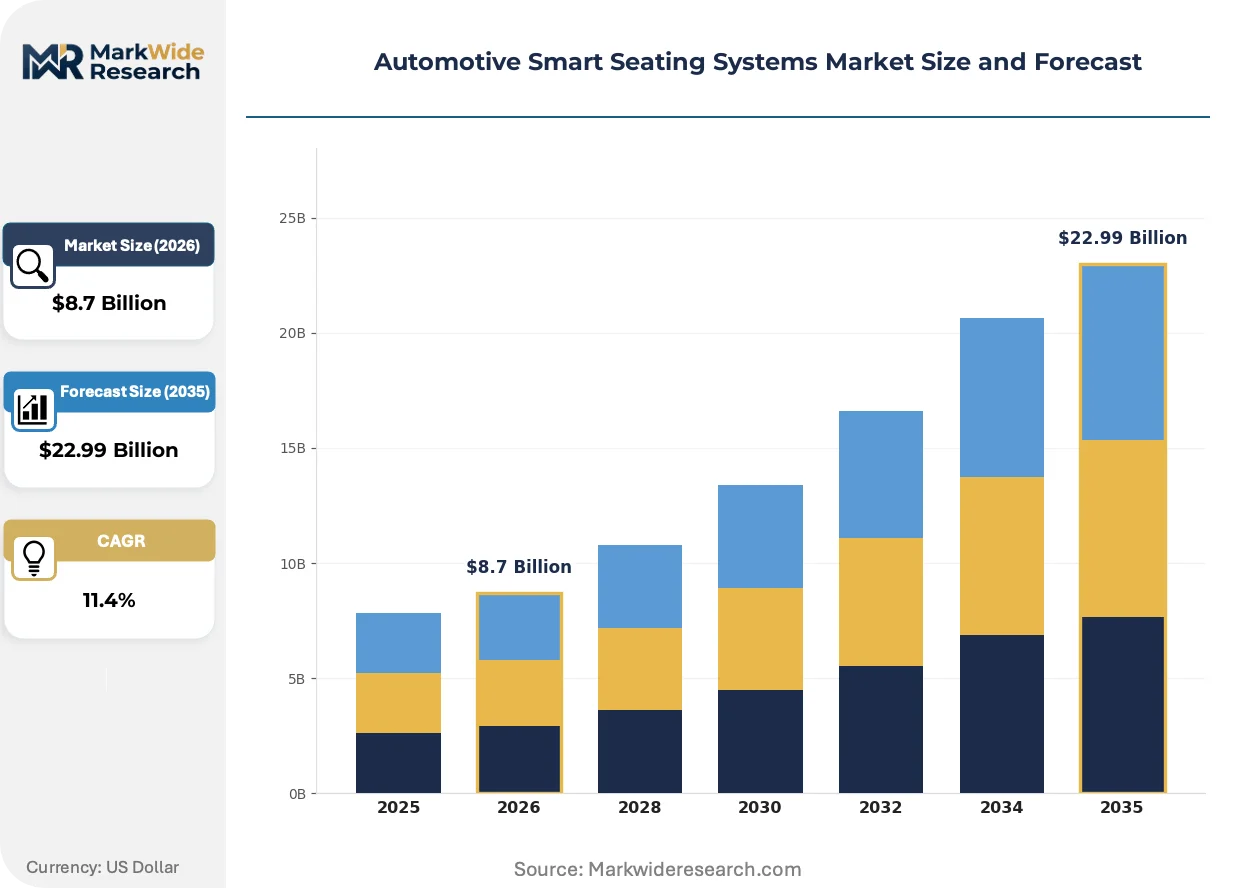
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-End Seats, Lumbar Support Seats, Massaging Seats, Heated Seats Technology: Wireless Connectivity, Integrated Sensors, Smart Fabric, Power Recline End User: Passenger Cars, Commercial Vehicles, Luxury Vehicles, SUV/Crossover Installation: OEM Installation, Aftermarket Upgrade, Assembly Line Integration, Retrofitting |
| Companies Covered | Adient PLC, Lear Corporation, Faurecia, Magna International Inc, Toyota Boshoku Corporation, Continental AG, DURA Automotive Systems, Grammer AG, RECARO Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Seating Systems Market Strategic Shifts
Smart seating architectures are converging health sensing, climate control, and structural safety into unified domain-controlled systems, compressing the traditional separation between comfort features and safety-critical functions.
Sensor fusion is fragmenting discrete module architectures. Capacitive electrodes, pressure mats, and temperature probes now embed directly into textile weaves rather than bolting onto foam substrates. Luxury German OEMs specify these integrated configurations for 2026 model year vehicles. This consolidation is fragmenting the supplier base between textile-integrated specialists and legacy discrete component manufacturers.
EPA vehicle interior air quality standards are tightening volatile organic compound limits for seating materials. The 2024 proposed rulemaking reduces formaldehyde and benzene emission thresholds by 40 percent from 2019 baselines. Foam and synthetic leather suppliers serving US light-truck programs are accelerating water-based adhesive and low-VOC coating transitions to maintain multi-year supply contracts.
Fleet procurement departments now specify total cost of ownership metrics rather than unit price alone. Rental car operators and corporate fleet managers in North America prioritize seat durability warranties and predictive maintenance data feeds. This recalibration favors suppliers offering embedded diagnostic capabilities and extended service agreements over pure hardware vendors.
Automotive Smart Seating Systems Market Segmentation
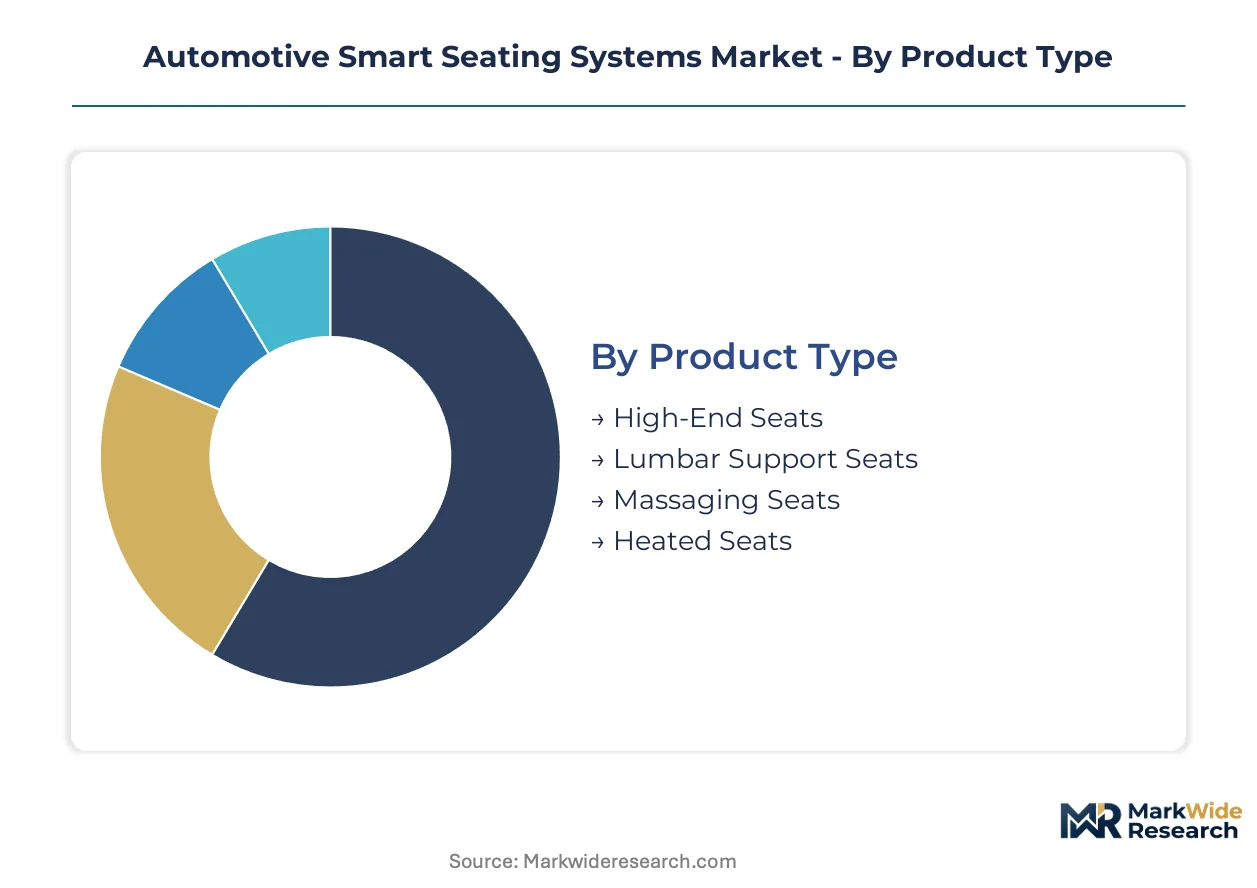
Smart seating architectures fragment across four dimensions that determine supplier qualification requirements and program economics. Product type and technology selections drive material cost structures, while end-user and installation channels dictate validation protocols and margin capture mechanisms.
Product Type:
Margin pools concentrate in configurations commanding premium pricing for occupant wellness and autonomous interior sensing.
- Massaging Seats:These systems integrate 8-16 pneumatic or electromechanical actuators with CAN bus motor control units to deliver programmable pressure sequences. Procurement from luxury German and Japanese OEMs concentrates specification volume here, driven by occupant wellness positioning in premium vehicle segments.
- High-End Seats:Full-feature configurations combine climate control, power adjustability, and embedded sensor arrays into unified domain-controlled architectures. China's Yangtze River Delta EV manufacturers specify these as standard equipment, compressing cost trajectories while expanding addressable volume.
- Lumbar Support Seats:Active pneumatic or mechanical lumbar mechanisms address ergonomic positioning for long-duration driving.
- Heated Seats:Resistive heating elements represent the most mature technology category with standardized supply chains and compressed supplier margins.
Massaging Seats hold installed capacity. High-End Seats is rotating up the share rankings.
Technology:
Revenue concentration tracks toward modules enabling recurring software monetization and predictive health algorithms.
- Integrated Sensors:Capacitive electrodes and pressure mats embed directly into seat substrates for occupant classification, health monitoring, and airbag deployment decisions. NHTSA mandates and EU General Safety Regulation crash-performance requirements are accelerating specification of these modules across multi-region vehicle platforms.
- Wireless Connectivity:Over-the-air activation modules transform fixed hardware sales into subscription revenue streams for massage, ventilation, and memory functions. Fleet procurement departments in North America prioritize diagnostic data feeds enabled by these connectivity layers.
- Smart Fabric:Textile-integrated capacitive sensing replaces discrete bolt-on modules with woven electrode configurations.
- Power Recline:Electromechanical recline actuators with position feedback represent baseline comfort functionality with established supply competition.
Integrated Sensors commands development investment. Wireless Connectivity is climbing the fastest.
End User:
Application segmentation separates safety-critical validation tiers from comfort-feature development cycles.
- Luxury Vehicles:German OEMs and Japanese premium brands specify ASIL-rated seat control modules with full sensor fusion and massage functionality. EU F-Gas Regulation material compliance and ISO 26262 functional safety certification requirements concentrate supplier qualification barriers in this segment.
- SUV/Crossover:North American light-truck platforms prioritize durability warranties and predictive maintenance capabilities for fleet operators. Lear Corporation's just-in-time assembly proximity to major plants secures program access here.
- Passenger Cars:Volume manufacturers balance feature content against cost targets with selective smart seating adoption.
- Commercial Vehicles:Long-haul trucking applications emphasize ergonomic support and driver alertness monitoring.
Luxury Vehicles maintains specification leadership. SUV/Crossover is expanding most quickly.
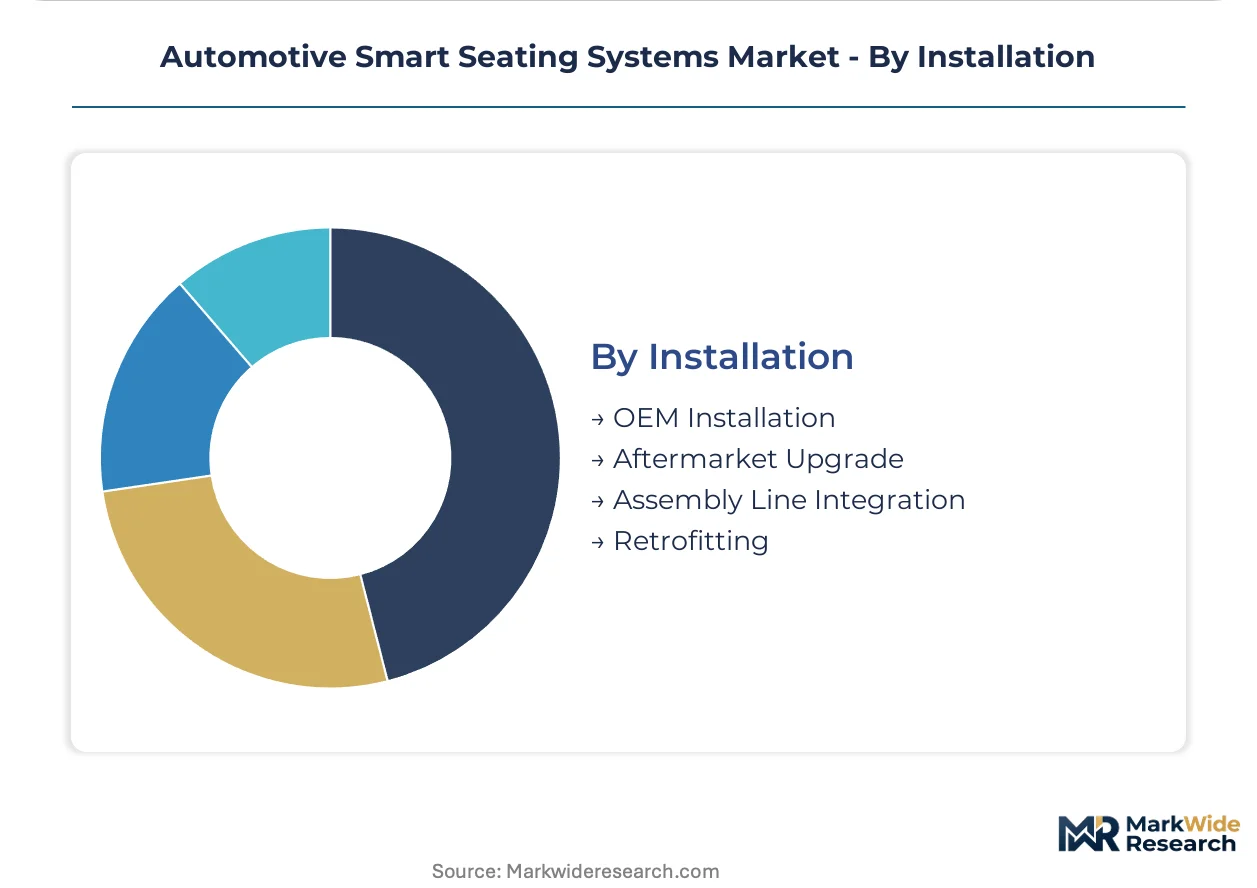
Installation:
Channel economics diverge between warranty-integrated OEM supply and price-sensitive aftermarket retrofit.
- OEM Installation:Factory-integrated smart seating systems undergo full vehicle-level validation with multi-year supply agreements. Adient PLC leverages foam chemistry and mechatronics integration to sustain wins with premium German OEMs in this channel.
- Assembly Line Integration:Sequenced module delivery adjacent to final assembly enables just-in-time inventory and reduces logistics overhead.
- Aftermarket Upgrade:Dealer-installed retrofit kits face compressed margins and limited feature activation compared to factory configurations.
- Retrofitting:Third-party installation of heating or lumbar support modules serves aging vehicle parc with basic functionality additions.
OEM Installation captures warranty value. Assembly Line Integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury vehicle OEMs in Germany and Japan drive specification volume for massaging and lumbar configurations, while China's Yangtze River Delta cluster concentrates procurement for domestic EV brands demanding heated and ventilated seats as standard.
Germany
Premium German OEMs accelerate procurement of ASIL-rated seat control modules with integrated sensor fusion. The EU F-Gas Regulation mandates CO2-based foam blowing agents, forcing polyurethane reformulation across Bavarian and Baden-Württemberg supply bases. Stuttgart and Munich metropolitan zones concentrate mechatronics integration capacity for 2026 model year programs.
China
Domestic EV manufacturers in the Yangtze River Delta specify high-end smart seats as standard equipment, compressing cost trajectories while expanding volume. The country's dual carbon goals tighten material compliance requirements for synthetic leather coatings. Ningbo and Shanghai manufacturing clusters host sequenced module delivery operations serving BYD, NIO, and XPeng production lines.
United States
North American light-truck platforms prioritize durability warranties and predictive maintenance capabilities for rental and corporate fleet operators. NHTSA occupant classification mandates shape sensor redundancy requirements for multi-region approval. Lear Corporation anchors supply through just-in-time seating assembly adjacent to major plants in Michigan and Kentucky.
Japan
Japanese premium brands specify massage functionality and capacitive sensor arrays for occupant wellness positioning. METI industrial standards guide functional safety validation protocols for seat-based health monitoring systems. Toyota City and Nagoya manufacturing corridors concentrate textile-integrated sensor production for 2026 vehicle launches.
India
Domestic OEMs and export-oriented suppliers leverage production-linked incentives for advanced automotive electronics assembly. The PLI scheme for auto components attracts seating system manufacturing to Tamil Nadu and Gujarat. Chennai and Ahmedabad industrial zones develop capacitive sensor module capacity for regional vehicle programs and Middle East export markets.
Automotive Smart Seating Systems Market Competitive Environment
Player mix skews toward vertically integrated tier-one integrators with captive foam chemistry and mechatronics capabilities. The supplier landscape bifurcates around ISO 26262 functional safety certification, separating qualified ASIL-rated module providers from excluded aspirants. Three archetypes dominate: full-system integrators controlling foam-to-software stacks, textile-embedded sensor specialists, and just-in-time assembly operators proximate to OEM plants. Competitive dynamics center on strategic partnerships for domain controller integration and backward integration into polyurethane chemical production.
Within the certified tier-one tier, Adient PLC exemplifies the vertically integrated archetype through combined foam chemistry and mechatronics capabilities. Lear Corporation anchors the just-in-time assembly model with proximity-based supply to North American light-truck programs. Faurecia occupies a position representing textile-integrated sensor specialization, embedding capacitive arrays directly into woven substrates rather than discrete bolt-on modules. These three entities collectively illustrate the strategic segmentation between chemical-mechanical integration, logistics-proximate assembly, and smart fabric innovation vectors reshaping supplier qualification.
| Leading Market Players |
|---|
| Adient PLC |
| Lear Corporation |
| Faurecia |
| Magna International Inc |
| Toyota Boshoku Corporation |
| Continental AG |
| DURA Automotive Systems |
| Grammer AG |
| RECARO Automotive |
| Others |
Value Chain & Pricing Dynamics
ISO 26262 functional safety certification gates both supplier qualification and price differentiation simultaneously, concentrating margin capture among ASIL-rated tier-ones while excluding aspirants from premium program access. The bifurcation creates a pricing hierarchy where certified integrators command cost-plus premiums indexed to polyol and semiconductor input volatility, while uncertified competitors face compressed margins in commoditized heated-seat segments.
Pricing Analysis
Cost-plus contracts with polyol and microcontroller indexation dominate long-term supply agreements between tier-ones and German luxury OEMs. Price differentiation separates ASIL-D certified modules from standard comfort features, with the former capturing software-enabled recurring revenue through over-the-air activation. Pricing pressure stems from memory chip allocation constraints transmitting directly to motor control unit costs. Fleet procurement departments exhibit highest price sensitivity, prioritizing total cost of ownership metrics over unit price, while luxury OEMs remain least sensitive due to wellness-feature positioning requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate OEM-integrated seating assembly, with Lear Corporation's proximity to Michigan and Kentucky light-truck plants exemplifying the model over strategic stockpiling. Supply concentrates in Germany, China, and the United States for foam chemistry, mechatronics integration, and final assembly respectively. Raw material dependencies center on propylene oxide feedstocks, automotive-grade microcontrollers, and synthetic leather coatings. Single-source vulnerability in Infineon and NXP semiconductor allocation represents the primary structural risk. Distribution runs through sequenced module delivery adjacent to final vehicle assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
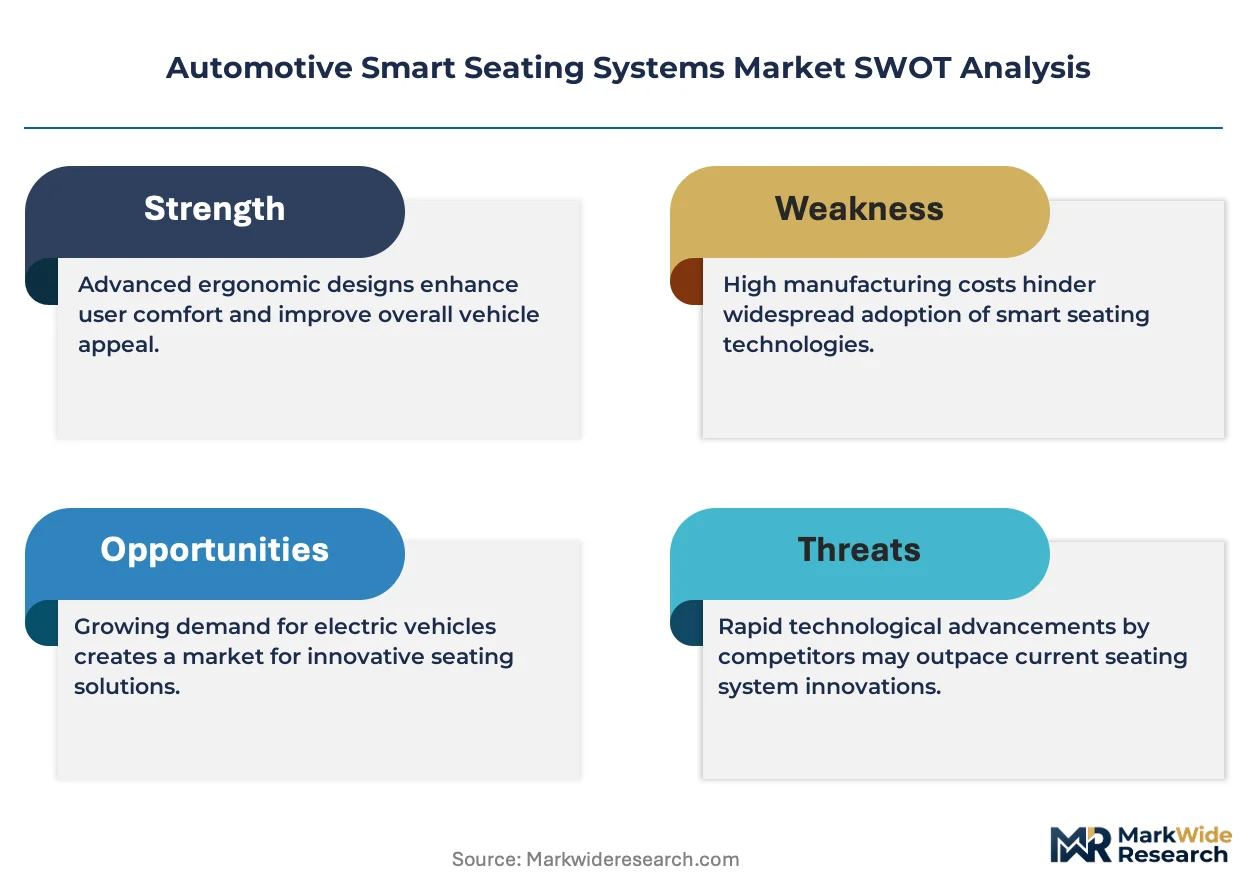
This market presents a defensive moat anchored in regulatory entrenchment, where ISO 26262 certification timelines and OEM requalification cycles create switching costs that protect incumbent positions for multi-year program horizons.
For Market Incumbents: Fortify ASIL-rated certification portfolios through accelerated validation cycles for seat-based occupant detection systems, countering emerging textile-integrated sensor specialists. Deepen backward integration into polyurethane chemical production to offset polyol price volatility compressing margins. Prioritize domain controller integration partnerships to maintain software stack control against silicon vendor encroachment.
For New Entrants and Emerging Players: ISO 26262 fast-track certification programs offer the most viable entry pathway for tier-two suppliers facing 18-24 month development cycles. Target India's PLI scheme for auto components assembly in Tamil Nadu and Gujarat, serving domestic OEMs and Middle East export markets with capacitive sensor module production. Pursue white-space in commercial vehicle driver alertness monitoring, where ergonomic support mandates create specification pull with lower certification barriers than luxury autonomous interiors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across textile-integrated sensor production as Faurecia-style smart fabric capabilities require specialized weaving equipment and electrode embedding processes. Five-to-ten year viability favors acquiring mid-cap specialists with captive foam-to-textile integration rather than pure hardware assemblers. Monitor Infineon and NXP allocation announcements as the critical signal for tier-two supplier distress and consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | ISO 26262 validation separates qualified tier-ones from excluded aspirants in autonomous interior programs. |
| Backward Integration into Foam Chemistry | Captive polyurethane production insulates margins from propylene oxide feedstock volatility. |
| Smart Fabric Sensor Development | Textile-embedded capacitive arrays displace discrete bolt-on modules in 2026 German OEM specifications. |
| Over-the-Air Connectivity Deployment | Wireless modules transform fixed hardware sales into subscription revenue for massage and ventilation functions. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Gujarat assembly serves domestic OEMs and Middle East export markets with government incentive support. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of seating system suppliers, and EU regulatory filings on F-Gas compliance. Bottom-up segment sizing triangulated against top-down OEM program volume estimates.
Across the analysis window, the forecasting framework modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs were derived from segment-level trajectory blending rather than aggregate extrapolation. Key inputs included NHTSA occupant classification mandate implementation timelines and EU General Safety Regulation crash-performance requirement phase-ins.
Decision-makers should treat outputs as directional under base assumptions of sustained semiconductor allocation constraints and REACH substance restriction compliance; material deviation would warrant model refresh. Specific risk factors include pending FMVSS updates redefining seat-based systems as safety-critical and EU AI Act liability framework interpretations for automated driving interiors. Revision becomes warranted when polyol price volatility or memory chip lead times cross stability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market