
 Automotive 3D Surface Display Market | 2026-2036
Automotive 3D Surface Display Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive 3D Surface Display Market Outlook
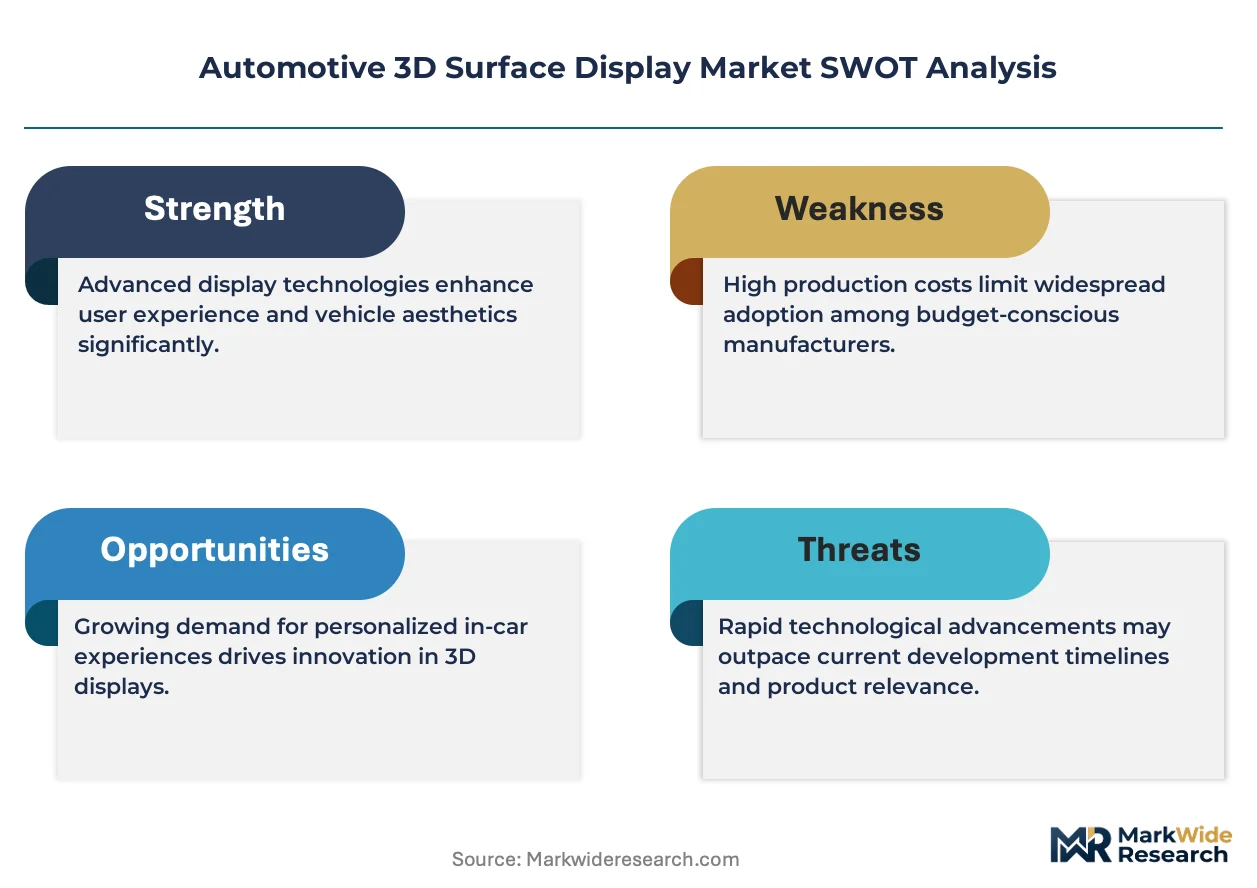
A shortage of optical bonding specialists and curved-glass process engineers is redrawing competitive boundaries across the supply base. Robert Bosch leverages its captive semiconductor and sensor portfolio to integrate display modules with ADAS data streams. Samsung Display anchors high-volume OLED capacity for curved automotive panels, while LG Display competes aggressively on LTPO backplane technology for power-efficient instrument clusters.
Automotive 3D surface displays are contoured, non-planar visualization interfaces fabricated through thermoformed glass substrates, optical bonding with liquid optically clear adhesive, and multi-layer lamination to achieve radii of curvature below 500mm while maintaining touch sensitivity and optical clarity. These systems serve as the primary human-machine interface for instrument readout, navigation, and infotainment in modern vehicle cabins. Head-up displays and instrument clusters command the highest margin pools due to stringent optical performance requirements and safety-critical validation cycles. OLED display technology is displacing LCD in premium segments where contrast ratio and form-factor flexibility justify unit cost premiums, while integrated installation types dominate OEM programs for new vehicle platforms.
NHTSA distraction guidelines and ECE R121 regulations on driver information systems directly shape pixel density, response time, and placement specifications for 3D surface displays in vehicles sold across the United States and European markets. Japan's METI has issued roadmap directives on next-generation mobility interfaces that incentivize domestic display makers to develop automotive-qualified flexible panel technologies. Stakeholders must monitor how software-defined vehicle architectures reshape hardware refresh cycles and whether tier-1 suppliers can retain value capture as OEMs pursue direct display sourcing relationships.
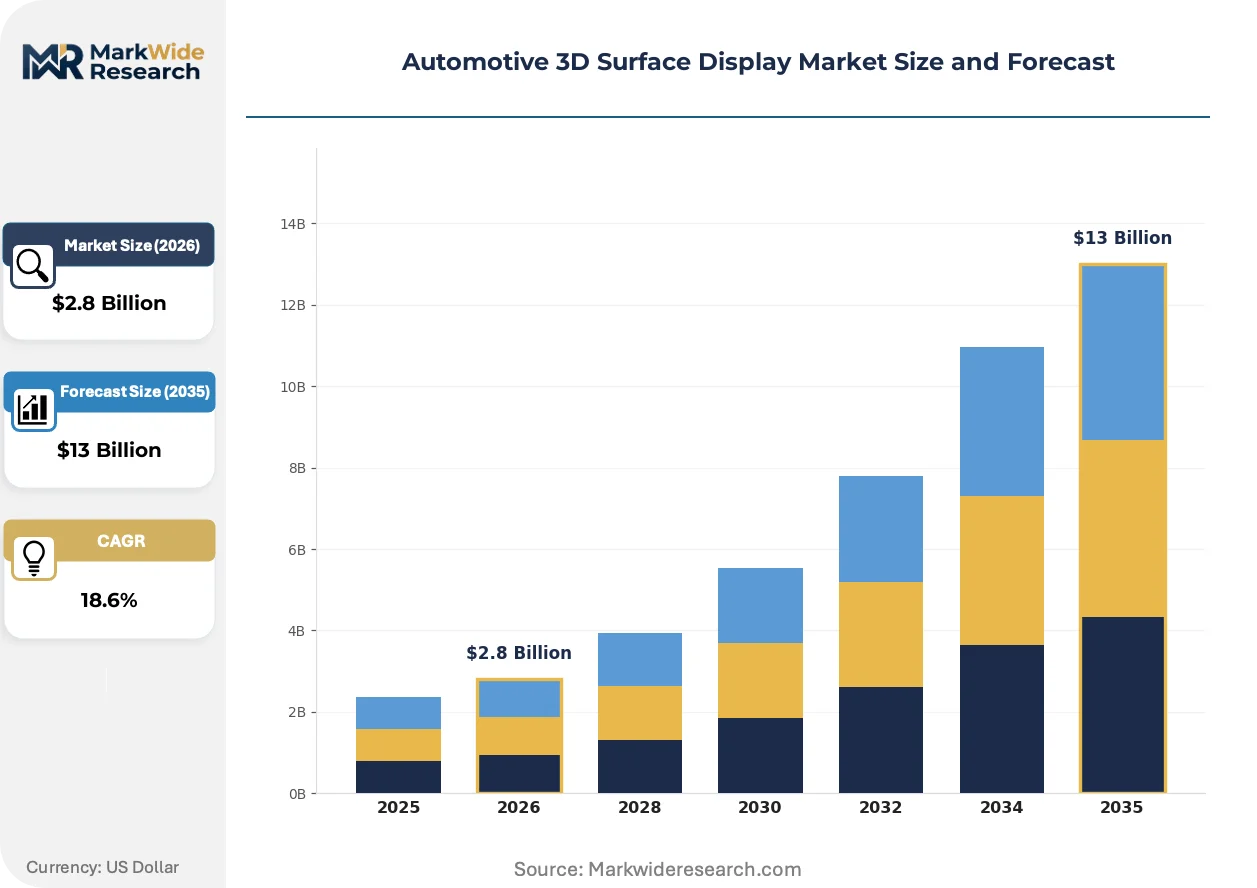
Market Dynamics
Optical bonding capacity scarcity is concentrating supply power among display integrators with in-house lamination capabilities, while NHTSA and ECE R121 safety mandates accelerate hardware refresh cycles for cockpit HMI systems.
Growth Catalysts
- EU vehicle safety protocols:ECE R121 regulations on driver information systems mandate minimum pixel density and response time thresholds for instrument clusters, compelling OEMs to upgrade to curved 3D surface displays.
- Software-defined vehicle architectures:Centralized compute platforms enable over-the-air updates that extend display hardware lifecycles while demanding higher-resolution, more responsive touch interfaces.
- South Korea OLED ecosystem:Concentrated R&D investment in flexible organic light-emitting diode backplane technologies reduces panel thickness and enables radii of curvature below 300mm for freeform dashboard integration.
Market Restraints
- Liquid optically clear adhesive volatility:Optical bonding material costs fluctuate with petrochemical feedstock prices, compressing module integrator margins during supply shocks.
- Thermoformed glass process concentration:Curved-glass substrate fabrication expertise clusters in German and Japanese precision optics hubs, creating single-source dependencies for tier-1 suppliers.
- LCD substitution pressure:Mature liquid crystal display technologies retain cost advantages in mid-market vehicle segments, delaying OLED penetration outside premium platforms.
Strategic Opportunities
- India domestic manufacturing incentives:PLI scheme allocations for automotive electronics assembly attract display module investment toward the country's expanding passenger vehicle production base.
- Head-up display convergence:Windshield-projection systems integrating augmented reality navigation with 3D instrument readouts open new application categories beyond traditional dashboard mounting.
- Japan METI mobility interface roadmap:Government-directed flexible panel development programs subsidize automotive-qualified OLED qualification, accelerating domestic supplier capability building.
Industry Challenges
- Optical bonding specialist scarcity:Liquid optically clear adhesive lamination engineers command premium compensation, constraining tier-1 supplier capacity expansion.
- ADAS integration complexity:Safety-critical validation cycles for instrument clusters displaying autonomous system status extend development timelines and certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive 3D Surface Display Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Up Displays, Instrument Clusters, Infotainment Screens, Navigation Displays Display Technology: LCD, LED, OLED, DLP End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation Type: Integrated, Retrofit, Modular, Custom Solutions |
| Companies Covered | Robert Bosch, Visteon, DENSO Corporation, Panasonic Automotive, Delphi Technologies, Continental AG, LG Display, Samsung Display, AU Optronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive 3D Surface Display Market Strategic Shifts
Display module architectures are fragmenting as software-defined vehicle platforms decouple hardware refresh cycles from traditional model-year cadences, enabling continuous HMI evolution.
Thermoformed glass substrates with sub-500mm curvature radii are decomposing the planar display paradigm that has dominated automotive cockpits for three decades. Premium passenger vehicle OEMs in Germany and Japan are adopting freeform instrument clusters at accelerated program cadences. This technology is decomposing the distinction between decorative interior surfacing and functional information displays, enabling seamless dashboard integration.
NHTSA distraction guidelines and ECE R121 performance specifications are tightening pixel density, luminance uniformity, and touch-response latency requirements for driver-facing displays. Compliance validation now demands specialized optical metrology equipment and extended test protocols. Head-up display and instrument cluster segments face the steepest certification burdens, compressing supplier development schedules.
Direct sourcing relationships between OEMs and panel manufacturers are bypassing traditional tier-1 module integrators in high-volume programs. Hyundai Motor Group and Volkswagen Group have established preferred supplier agreements with Samsung Display and LG Display respectively. This channel restructuring concentrates procurement power in South Korea and concentrates margin pressure on European and Japanese system integrators.
Automotive 3D Surface Display Market Segmentation
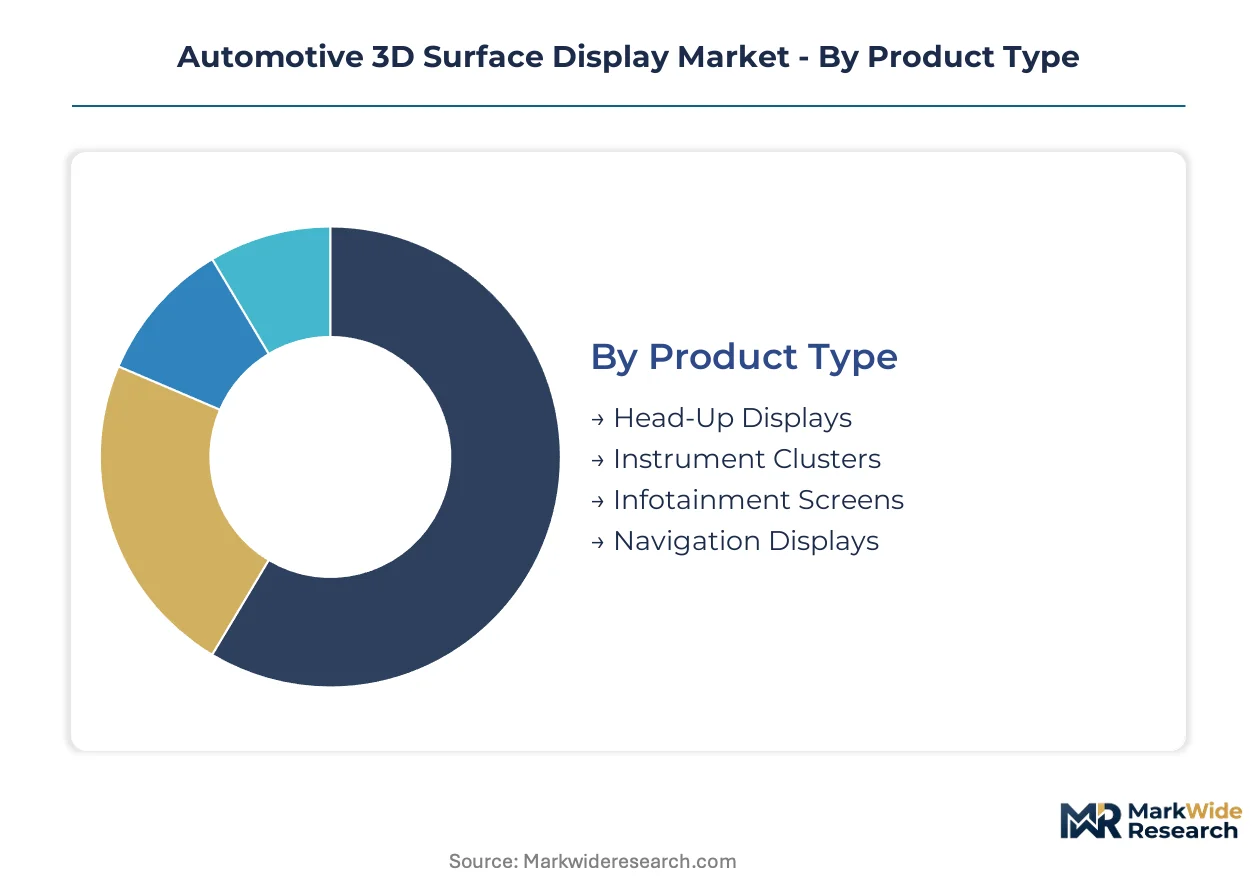
Automotive 3D surface displays fragment across four distinct taxonomies that shape procurement patterns and margin structures. Product type and display technology determine hardware specifications and safety certification burdens, while end-user channels and installation approaches govern commercial access routes and pricing power.
Product Type:
German OEM programs anchor domestic demand for head-up displays and instrument clusters, whereas infotainment and navigation displays serve broader export markets with shorter validation cycles.
- Head-Up Displays:Windshield-projection systems employing curved combiner optics and waveguide architectures deliver augmented reality navigation overlays. Demand concentrates in premium German and Japanese vehicle platforms where ECE R121 compliance mandates minimum luminance thresholds of 15,000 cd/m² for daylight visibility.
- Instrument Clusters:Driver-facing freeform displays with sub-500mm curvature radii integrate speedometer, tachometer, and ADAS status readouts. South Korean and Japanese OEMs are accelerating adoption of full-digital replacements for analog gauge clusters.
- Infotainment Screens:Center-stack touch interfaces prioritize media control and smartphone integration over safety-critical validation.
- Navigation Displays:Route-guidance panels with reduced optical performance requirements serve mid-market vehicle segments.
Head-up displays command the established base. The steepest expansion runs through instrument clusters.
Display Technology:
Cost tier stratification separates premium OLED adoption from volume LCD deployment, with LED and DLP occupying intermediate positions in specialized applications.
- LCD:Mature liquid crystal modules with edge-lit or direct-lit backlighting retain cost advantages in mid-market instrument clusters. Chinese and Indian vehicle assemblers specify LCD for price-sensitive platforms where contrast ratio requirements remain below 1000:1.
- OLED:Organic light-emitting diode panels with self-emissive pixels and flexible polyimide substrates enable radii of curvature below 300mm. South Korean display makers dominate supply for German and Japanese premium OEMs where infinite contrast ratios justify unit cost premiums.
- LED:Direct-view LED arrays serve large-format dashboard applications with high ambient luminance requirements.
- DLP:Digital light processing technology enables compact head-up display optics through micro-mirror array projection.
LCD retains volume leadership. OLED is climbing the fastest as premium platform adoption accelerates.
End User:
Customer type determines technical specification authority and contract duration, with OEM direct sourcing reshaping traditional tier-1 intermediary roles.
- OEMs:Vehicle manufacturers including Volkswagen Group and Hyundai Motor Group negotiate preferred supplier agreements directly with Samsung Display and LG Display, bypassing module integrators for high-volume curved panel procurement.
- Tier-1 Suppliers:System integrators such as Robert Bosch and Continental retain value capture in optical bonding and ADAS data stream integration where specialized process engineering creates defensive moats.
- Aftermarket Providers:Independent installers serve vehicle retrofit and customization segments with reduced validation requirements.
- Vehicle Assemblers:Contract manufacturers without captive design centers rely on tier-1 specifications for display module integration.
Tier-1 suppliers command the established base. The steepest expansion runs through OEM direct relationships.
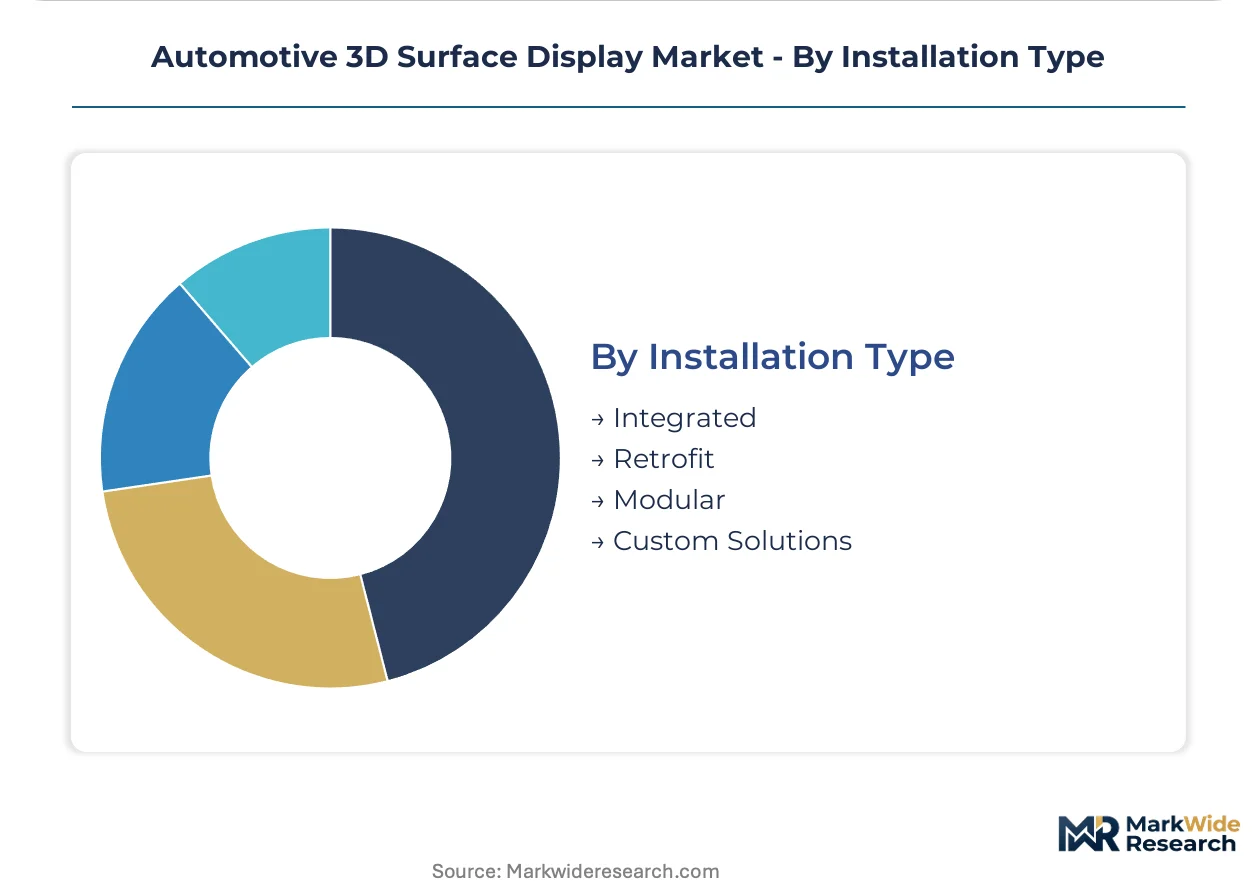
Installation Type:
Application approach dictates development timeline and hardware refresh flexibility, with integrated solutions dominating new platform engineering.
- Integrated:Factory-installed displays engineered into dashboard architecture during vehicle platform development. German and Japanese OEMs specify integrated 3D surface displays for model-year introductions with five-to-seven-year platform lifecycles.
- Modular:Standardized display units with common mounting interfaces enable supplier interchangeability and reduced tooling costs.
- Retrofit:Post-production installation serves vehicle fleet upgrades and customization markets.
- Custom Solutions:Bespoke display geometries for limited-production luxury vehicles and concept demonstrators.
Integrated installations command the established base. The steepest expansion runs through modular architectures as software-defined vehicle platforms decouple hardware from model-year cadences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, South Korea, and Japan consume automotive 3D surface displays through fundamentally different deployment patterns. German OEMs prioritize head-up displays and instrument clusters for premium platforms. South Korean manufacturers concentrate on high-volume OLED panel output for export markets. Japanese suppliers emphasize integrated cockpit systems with METI-backed flexible panel development.
Germany
Volkswagen Group and BMW drive demand for curved instrument clusters and augmented reality head-up displays. ECE R121 regulations mandate minimum luminance thresholds of 15,000 cd/m² for daylight visibility. Stuttgart and Munich anchor precision optics clusters where thermoformed glass fabrication expertise concentrates among tier-1 system integrators.
South Korea
Hyundai Motor Group and Kia specify freeform OLED panels for next-generation vehicle platforms. The national industrial policy channels R&D investment into flexible organic light-emitting diode backplane technologies. Gyeonggi Province hosts concentrated display manufacturing capacity where Samsung Display and LG Display maintain high-volume curved panel production.
Japan
Toyota, Honda, and Nissan accelerate adoption of full-digital instrument clusters replacing analog gauge assemblies. METI roadmap directives subsidize automotive-qualified flexible panel qualification programs. Nagoya and Tokyo metropolitan areas concentrate domestic display maker R&D facilities for next-generation mobility interface development.
United States
General Motors and Ford integrate 3D surface displays into electric vehicle platforms with software-defined architectures. NHTSA distraction guidelines shape pixel density and touch-response latency specifications for driver-facing displays. Michigan and California host validation laboratories where specialized optical metrology equipment supports compliance testing.
China
BYD, NIO, and XPeng specify large-format curved displays for intelligent cockpit differentiation. MIIT standards on vehicle information systems establish domestic performance benchmarks for human-machine interface hardware. Shenzhen and Shanghai concentrate module assembly capacity where tier-1 suppliers establish joint ventures with domestic panel manufacturers.
Automotive 3D Surface Display Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in automotive 3D surface display supply. Panel manufacturers with captive semiconductor and sensor portfolios command procurement power through direct OEM relationships. Specialist module integrators retain defensive positions in optical bonding and ADAS data stream integration where process engineering creates scarcity premiums. Dominant competitive moves include preferred supplier agreements between vehicle manufacturers and display makers, plus in-house lamination capability investments among tier-1 system integrators.
Within the integrated leader tier, Robert Bosch and Continental AG represent European system integrators with broad automotive electronics portfolios. Samsung Display and LG Display anchor South Korean panel manufacturing capacity. These companies exemplify divergent strategic positioning: Bosch and Continental occupy module integration roles emphasizing optical bonding and software integration, while Samsung Display and LG Display represent upstream panel supply positions with direct OEM channel access.
| Leading Market Players |
|---|
| Robert Bosch |
| Visteon |
| DENSO Corporation |
| Panasonic Automotive |
| Delphi Technologies |
| Continental AG |
| LG Display |
| Samsung Display |
| AU Optronics |
| Others |
Value Chain & Pricing Dynamics
High-volume OLED capacity utilization in Gyeonggi Province concentrates bargaining power among South Korean panel manufacturers while establishing cost floors that module integrators struggle to compress. German and Japanese tier-1 suppliers absorb margin pressure through optical bonding premiums as liquid optically clear adhesive volatility feeds into module pricing.
Pricing Analysis
Long-term offtake agreements between Hyundai Motor Group and Samsung Display anchor pricing stability for high-volume curved panel programs. Three-tier pricing structure across premium OLED instrument clusters, standard LCD infotainment modules, and economy-grade navigation displays reflects ECE R121 certification burdens. Cost compression in mid-market LCD tiers is intensifying because Chinese vehicle assemblers specify sub-1000:1 contrast ratio panels. Tier-1 suppliers face acute price sensitivity, while OEM direct buyers leverage scale for preferential terms.
Supply Chain Analysis
Just-in-time inventory strategies dominate South Korean panel output destined for German OEM assembly plants, while strategic stockpiling of optical bonding materials occurs among Japanese tier-1 suppliers exposed to petrochemical feedstock volatility. Manufacturing concentrates in South Korea, Germany, and Japan where thermoformed glass fabrication expertise clusters. Supply chains draw from liquid optically clear adhesive chemistries, flexible polyimide substrates, and precision optics equipment. Single-source vulnerability runs through German thermoformed glass hubs. Distribution runs through direct OEM procurement channels and tier-1 system integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM direct sourcing relationships are consolidating procurement power among vehicle manufacturers, fragmenting traditional tier-1 intermediary roles. This buyer-power shift compresses margins for module integrators lacking defensive process engineering capabilities.
For Market Incumbents: Fortify optical bonding capacity through in-house lamination investments in Stuttgart and Munich precision optics clusters. Acquire curved-glass process engineering talent pools to defend against panel manufacturer backward integration into module assembly. Prioritize ADAS data stream integration capabilities where safety-critical validation cycles create switching costs. For New Entrants and Emerging Players: ECE R121 certification fast-tracks for instrument cluster applications offer entry pathways into premium German OEM supply chains. Target India's PLI-subsidized automotive electronics assembly capacity for cost-competitive module production. Pursue white-space in aftermarket head-up display retrofit segments where validation requirements remain reduced. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-1 suppliers with captive optical bonding capabilities and long-term OEM service contracts. Long-term viability hinges on software-defined vehicle architecture adaptation. Monitor OEM direct panel procurement ratios as inflection indicator for integrator margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Bonding Capacity Expansion | In-house lamination capabilities at Robert Bosch and Continental AG defend against margin erosion from direct OEM-panel relationships. |
| OLED Backplane Technology Investment | LG Display's LTPO development for power-efficient instrument clusters targets ECE R121 compliance thresholds. |
| Software-Defined Vehicle Partnership | Integration with centralized compute platforms enables over-the-air HMI updates extending display hardware lifecycles. |
| India Manufacturing Footprint | PLI scheme allocations attract module assembly investment toward expanding domestic passenger vehicle production. |
| Head-Up Display Convergence | Windshield-projection AR navigation opens application categories beyond traditional dashboard mounting for premium platforms. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement leads, optical bonding process specialists, and aftermarket distributors and refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed display manufacturers, and ECE R121 regulatory documentation. Bottom-up demand modeling across vehicle class, propulsion architecture, content per vehicle, and regional production clusters triangulated with top-down market sizing.
Variance decomposition across segmentation dimensions isolated instrument cluster, head-up display, infotainment, and navigation product categories alongside LCD, OLED, LED, and DLP technology splits. CAGRs were derived from installed base growth, replacement cycles, and technology substitution curves. Forecast inputs incorporated software-defined vehicle architecture penetration, ECE R121 compliance phase-in timelines, and OLED capacity expansion schedules across the analysis window.
Decision-makers should treat outputs as directional under assumptions of sustained premium vehicle production in Germany, South Korea, and Japan; material deviation would warrant model refresh. Revision becomes warranted when OEM direct sourcing ratios cross thresholds that structurally disintermediate tier-1 integrators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market