
 Auto Glass Encapsulation Market | 2026-2036
Auto Glass Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Glass Encapsulation Market Insights
Electric vehicle platforms are redrawing buyer priorities in auto glass encapsulation. Fleet operators and EV-focused automakers now specify larger, curved glass panels with integrated sealing systems that reduce wind noise and assembly steps. AGC Inc. leverages its integrated float glass and chemical strengthening operations to supply complete windshield modules directly to Japanese and European OEMs. Saint-Gobain sustains leadership in acoustic interlayer films, anchoring its position through proprietary PVB formulations that dampen road noise in premium sedans.
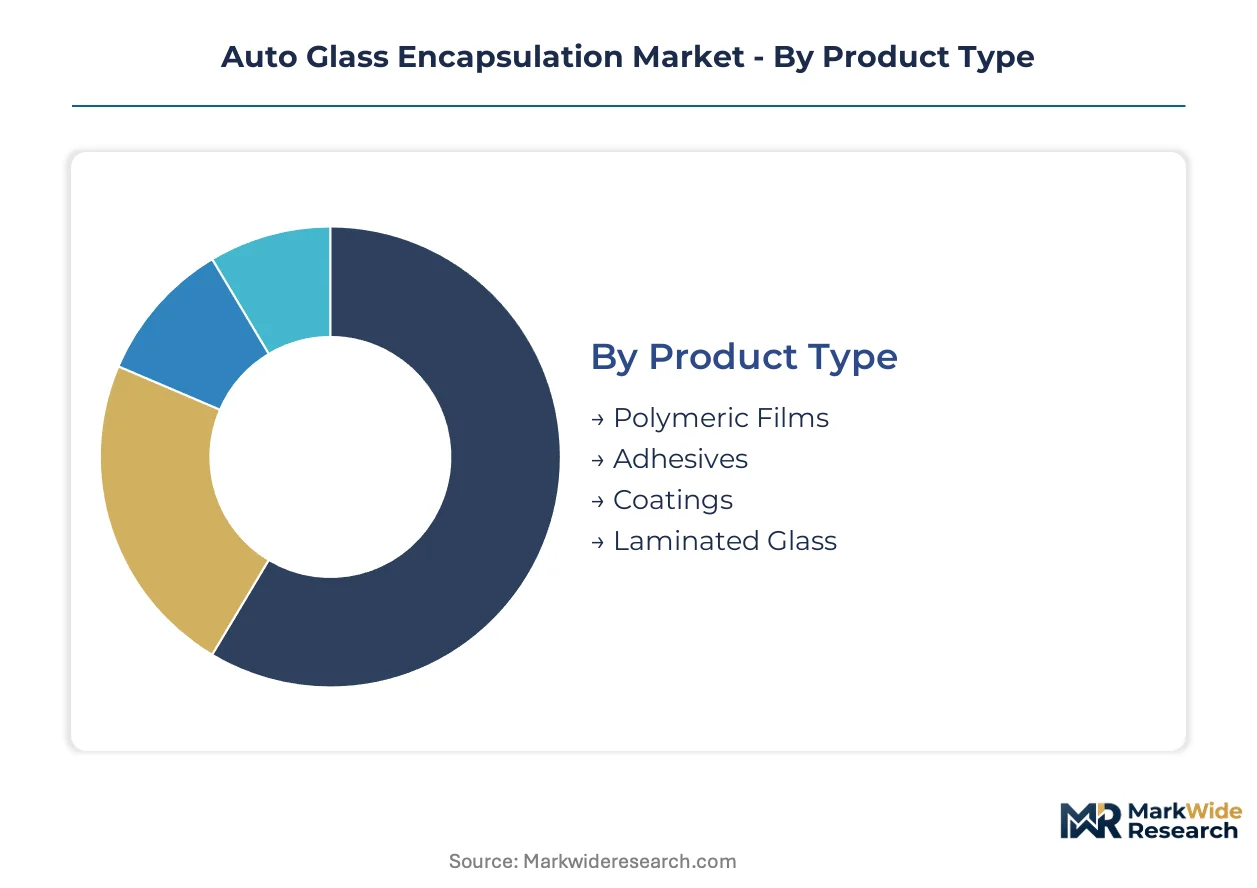
Auto glass encapsulation refers to the process of bonding a polymeric frame or gasket directly to the glass edge during manufacturing, typically using reaction injection molding of polyurethane or extruded EPDM profiles, to create a finished assembly that seals against the vehicle body and accepts hardware attachments. The primary purpose is to eliminate separate installation gaskets, reduce assembly time, and improve water management at the glass-body interface. Polymeric films and adhesives capture the largest share of material value, with polyurethane systems dominating OEM programs due to their adhesion to ceramic frit and paint-like finish. Laminated glass applications are expanding fastest as panoramic roof and head-up display windshields require thicker, stiffer encapsulation profiles to maintain optical alignment.
Federal Motor Vehicle Safety Standard 205 governs glazing materials in the US, while ECE R43 and UN Regulation 43 set optical and mechanical benchmarks across Europe and harmonized markets, collectively pushing suppliers toward higher-strength interlayers and more precise edge finishing. The EPA and NHTSA influence material selection through fuel economy and crashworthiness requirements that favor lighter, structurally bonded glass assemblies. Stakeholders must track how evolving autonomous vehicle sensor integration—lidar and camera cutouts in windshields—will force encapsulation designs to accommodate embedded electronics without compromising seal integrity or optical clarity.
Market Dynamics
Electric vehicle architectures are compressing the traditional windshield-to-roof assembly sequence, forcing encapsulation suppliers to engineer larger bonded modules that integrate directly with stamped body panels. This structural shift eliminates intermediate sealing steps but demands tighter dimensional tolerances across polyurethane reaction injection molding lines.
Growth Catalysts
- Panoramic roof penetration:Premium OEMs in Germany now specify continuous glass panels exceeding 1.5 square meters, requiring thicker encapsulation profiles to maintain structural rigidity during automated assembly.
- ECE R43 harmonization:The UN Regulation 43 optical clarity benchmarks are pushing laminated glass suppliers toward higher-grade PVB interlayers that bond more reliably with polyurethane edge frames.
- Head-up display integration:Windshield HUD compatibility demands wedge-shaped glass with precisely molded encapsulation edges that preserve projection geometry across temperature cycles.
Market Restraints
- Polyol price volatility:MDI and polyether polyol feedstock costs swing with crude oil indices, compressing margins for reaction injection molding compounders serving volume programs.
- Tooling concentration:High-precision RIM molds for curved glass edges concentrate among German and Japanese toolmakers, creating supply bottlenecks for new program launches.
- Ceramic frit adhesion limits:Polyurethane systems struggle to bond reliably to low-emissivity coating edges, restricting design freedom for solar-control windshields.
Strategic Opportunities
- Sensor cutout integration:Lidar and camera mounting bosses molded directly into encapsulation frames eliminate secondary bracket assembly for Level 2+ autonomous vehicles.
- India passenger vehicle expansion:Domestic OEMs are localizing windshield supply chains, creating openings for regional polyurethane compounding operations.
- Repairability mandates:Draft EU end-of-life vehicle regulations favor bonded glass modules designed for clean separation during recycling, rewarding encapsulation designs with defined fracture zones.
Industry Challenges
- Process technician scarcity:Reaction injection molding expertise for automotive glass edges concentrates among aging workforces in the Rhine-Ruhr and Nagoya industrial clusters.
- Optical certification timelines:ECE R43 homologation for new encapsulation formulations requires 18-24 month test cycles, delaying program approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Glass Encapsulation Market |
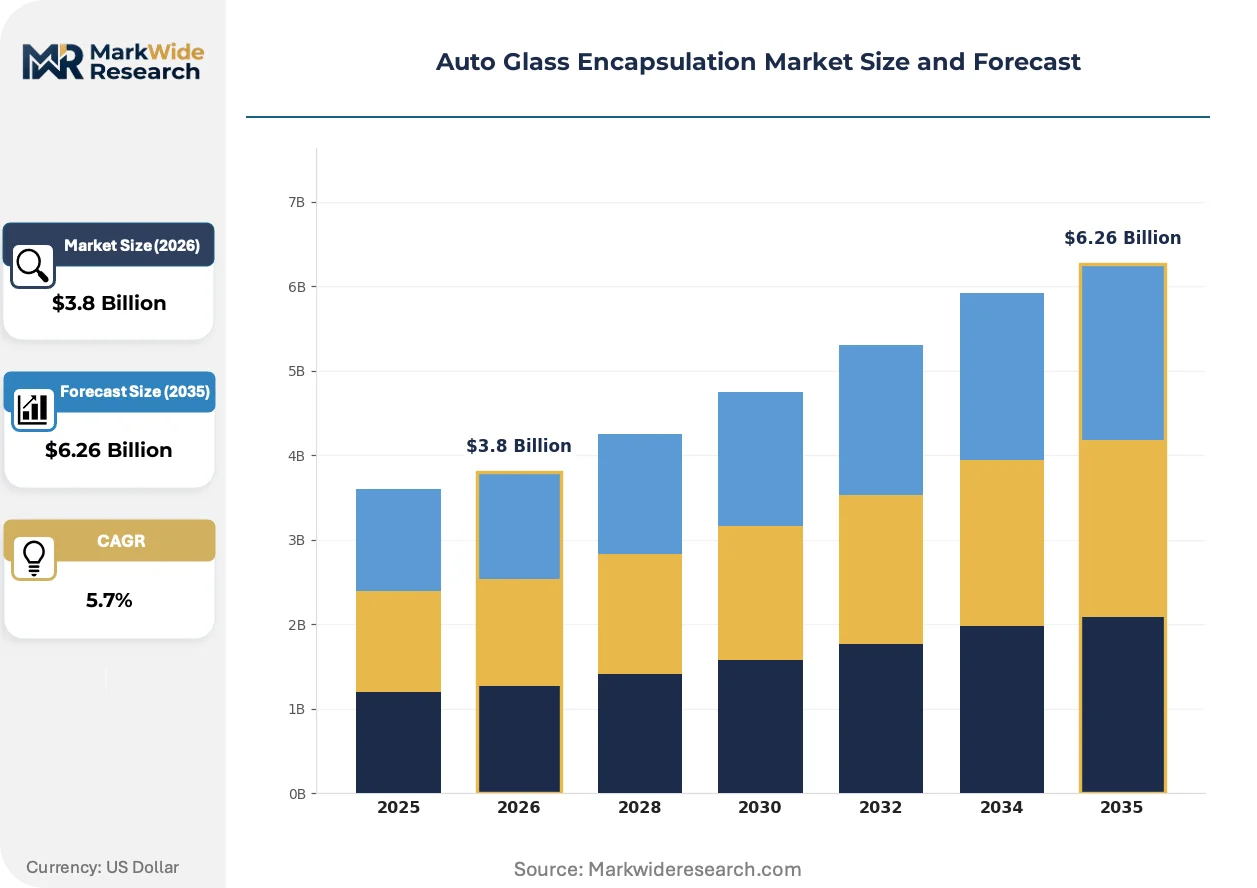
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Films, Adhesives, Coatings, Laminated Glass Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Aftermarket Distribution Channel: OEMs, Retail Stores, Online Platforms, Service Centers End User: Automakers, Fleet Operators, Repair Shops, Consumers |
| Companies Covered | AGC Inc., Saint-Gobain, Fuyao Glass Industry Group, Sika AG, Corning Incorporated, SCHOTT AG, Xinyi Glass Holdings, Pilkington, NSG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Glass Encapsulation Market Trends and Innovations
Material science advances are fragmenting the traditional polyurethane monopoly in glass edge sealing, while regulatory pressure on recyclability and autonomous vehicle integration forces concurrent redesign of encapsulation geometry and chemistry.
Thermoplastic vulcanizate edge profiles are fragmenting established supply relationships in the premium sedan segment. TPV systems permit in-mold coloring and faster cycle times than thermoset polyurethane. BMW and Mercedes-Benz pilot programs in Stuttgart and Munich are validating TPV for fixed quarter glass applications, compressing the addressable market for conventional RIM suppliers.
REACH restrictions on isocyanate workplace exposure are forcing German compounders toward low-monomer polyurethane formulations and closed-loop molding cells. The ECHA 2023 restriction proposal mandates respiratory protection and automated dispensing for MDI concentrations above threshold limits. Suppliers in Bavaria and Baden-Württemberg are responding with capital-intensive enclosed RIM lines that raise entry barriers for mid-tier competitors.
Fleet operators now specify total-cost-of-ownership warranties for glass assemblies rather than component-level procurement. Rental and ride-hail buyers in California and Texas negotiate 10-year seal integrity guarantees covering encapsulation adhesion failure. This contractual shift transfers liability risk from vehicle assemblers to glass system suppliers, favoring compounders with captive weathering test facilities and actuarial data on field performance.
Auto Glass Encapsulation Market Segmentation
Segmentation in auto glass encapsulation reveals how material chemistry, vehicle architecture, and procurement channels create distinct competitive arenas. Each dimension carries unique margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
ECE R43 and UN Regulation 43 impose divergent optical and mechanical benchmarks across material categories, forcing compounders to validate formulations against laminated assembly performance rather than standalone film properties.
- Polymeric Films:PVB and TPU interlayers dominate acoustic and structural bonding applications. German premium OEMs specify thicker calibrations for panoramic roof assemblies where thermal expansion tolerance is critical. REACH restrictions on plasticizer migration are pushing suppliers toward non-phthalate formulations that bond more reliably with polyurethane edge frames.
- Adhesives:Polyurethane systems command the largest share of OEM program value due to paint-like finish and ceramic frit adhesion. MDI feedstock volatility compresses margins for reaction injection molding compounders serving high-volume platforms in Stuttgart and Nagoya industrial clusters.
- Coatings:Low-emissivity and hydrophobic layers applied during float glass production.
- Laminated Glass:Thicker assemblies for head-up display compatibility and sensor integration.
Polymeric films handle the majority of throughput; laminated glass is gaining share fastest as panoramic roof penetration accelerates.
Application:
Vehicle electrification compresses traditional windshield-to-roof assembly sequences, concentrating demand in platforms engineered for bonded modular installation rather than gasket-based sealing.
- Passenger Vehicles:Curved glass panels exceeding 1.5 square meters now specify integrated encapsulation with molded hardware bosses. EV architectures in Germany and Japan eliminate intermediate sealing steps but demand tighter dimensional tolerances across RIM production lines.
- Commercial Vehicles:Fleet operators in California and Texas negotiate total-cost-of-ownership warranties covering 10-year seal integrity, transferring liability risk from assemblers to glass system suppliers with captive weathering facilities.
- Heavy Machinery:Construction and agricultural equipment with exposed cab assemblies.
- Aftermarket:Replacement windshields and repair modules distributed through service networks.
Passenger vehicles absorb the dominant share of encapsulation value; commercial vehicles are expanding most quickly on warranty-driven procurement restructuring.
Distribution Channel:
Direct OEM relationships capture premium pricing through program-specific tooling investments, while aftermarket channels compete on logistics velocity and installation network density.
- OEMs:Tier-1 suppliers like AGC and Saint-Gobain maintain direct supply agreements with Japanese and European vehicle manufacturers. Tooling concentration among German and Japanese moldmakers creates supply bottlenecks for new program launches requiring high-precision RIM cells.
- Retail Stores:Independent automotive parts distributors serving collision repair facilities.
- Online Platforms:E-commerce channels for consumer-direct replacement glass procurement.
- Service Centers:Authorized repair networks with bonded installation capabilities.
OEMs command the steepest pricing tier; service centers are climbing fastest as fleet maintenance contracts consolidate around certified installation networks.
End User:
Procurement authority is fragmenting across vehicle lifecycle stages, with automakers specifying designs, fleet operators negotiating performance warranties, and repair shops managing installation quality.
- Automakers:Design authority resides with vehicle manufacturers who specify encapsulation geometry, material grade, and sensor integration requirements. ECE R43 homologation timelines of 18-24 months delay program approvals for new formulations.
- Fleet Operators:Rental and ride-hail buyers now specify seal integrity guarantees rather than component-level procurement. This contractual shift favors compounders with actuarial data on field performance across temperature and humidity cycles.
- Repair Shops:Independent installers with polyurethane dispensing equipment and primer application training.
- Consumers:Individual vehicle owners purchasing replacement glass through insurance channels.
Automakers retain design control; fleet operators are ascending fastest as warranty terms reshape supplier liability structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized RIM tooling and polyurethane compounding expertise cluster in Germany and Japan, creating supply bottlenecks for new program launches. Demand patterns diverge sharply between premium OEM markets and high-volume EV manufacturing centers.
Germany
Premium OEMs in Stuttgart and Munich specify continuous glass panels exceeding 1.5 square meters with integrated encapsulation profiles. ECE R43 harmonization through UN Regulation 43 drives validation of higher-grade PVB interlayers. The Rhine-Ruhr industrial corridor hosts aging workforces with concentrated reaction injection molding expertise.
Japan
AGC Inc. leverages integrated float glass and chemical strengthening operations to supply complete windshield modules directly to domestic OEMs. METI influences material selection through fuel economy requirements favoring lighter bonded assemblies. The Nagoya industrial cluster concentrates polyurethane RIM expertise for curved glass edges.
United States
Fleet operators in California and Texas negotiate 10-year seal integrity warranties covering encapsulation adhesion failure. NHTSA governs glazing materials through Federal Motor Vehicle Safety Standard 205. The Southeast manufacturing corridor attracts bonded glass module assembly for transplanted Japanese and German OEMs.
China
Domestic EV platforms compress windshield-to-roof assembly sequences, demanding larger bonded modules with tighter dimensional tolerances. GB standards and MIIT regulations shape optical and mechanical benchmarks for laminated assemblies. The Yangtze River Delta concentrates float glass production and emerging polyurethane compounding capacity.
India
Domestic OEMs localize windshield supply chains, creating openings for regional polyurethane compounding operations. BIS standards govern automotive glass performance requirements. The Chennai-Bengaluru industrial corridor attracts encapsulation module assembly for passenger vehicle export programs.
Auto Glass Encapsulation Market Competitive Landscape
Concentration sits with integrated glass manufacturers and specialized chemical compounders. The vendor base splits between float glass producers with captive encapsulation lines and independent polyurethane RIM specialists serving multiple OEMs. Two strategic archetypes dominate: vertically integrated glass-to-module suppliers and focused encapsulation chemistry compounders. Competitive moves center on sensor integration partnerships and regional compounding capacity expansion.
Among integrated glass manufacturers, AGC Inc. and Saint-Gobain occupy positions anchored in proprietary float glass operations and acoustic interlayer formulations. Fuyao Glass Industry Group represents the scale-driven archetype with manufacturing breadth across multiple geographies. Sika AG exemplifies the specialized chemical compounder model, supplying polyurethane systems to OEMs without captive glass production. These four entities span the competitive spectrum from raw material integration to formulated chemistry supply.
| Leading Market Players |
|---|
| AGC Inc. |
| Saint-Gobain |
| Fuyao Glass Industry Group |
| Sika AG |
| Corning Incorporated |
| SCHOTT AG |
| Xinyi Glass Holdings |
| Pilkington |
| NSG Group |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at German and Japanese reaction injection molding lines shapes both supply concentration and price floors across the auto glass encapsulation market. Float glass producers with captive polyurethane compounding operations command premium positioning through integrated cost structures, while independent compounders serving multiple OEMs absorb margin compression from MDI feedstock volatility.
Pricing Analysis
Volume-discount tiering structures separate premium OEM programs from standard fleet contracts and economy aftermarket channels. Pricing stratifies across certification-grade tiers, with ECE R43-validated formulations commanding substantial premiums over non-homologated alternatives. Cost compression in standard-tier polyurethane systems is intensifying because MDI and polyether polyol costs swing with crude oil indices. Fleet operators in North America exhibit the highest price sensitivity due to total-cost-of-ownership procurement models, while German premium OEMs prioritize optical certification and sensor integration over unit economics.
Supply Chain Analysis
High-precision RIM mold availability concentrates among toolmakers in Germany, Japan, and select Austrian suppliers, creating program launch bottlenecks for new entrants. Raw material flows draw from Saudi Arabian MDI producers, Belgian polyol specialists, and Chinese float glass operations. Single-source vulnerability runs through the Rhine-Ruhr and Nagoya industrial clusters where aging workforces hold concentrated reaction injection molding expertise. Distribution runs through direct OEM supply agreements for premium programs, with aftermarket channels competing on logistics velocity and certified installation network density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic vulcanizate edge profiles present a credible substitution threat to established polyurethane reaction injection molding, forcing incumbents to defend their chemistry lock-in through accelerated certification cycles and integrated module supply.
For Market Incumbents: Fortify chemistry differentiation by accelerating low-monomer polyurethane formulations ahead of REACH isocyanate restrictions. Secure captive weathering test facilities to underwrite the 10-year seal integrity warranties fleet operators now demand. Backward integration into float glass operations or exclusive PVB interlayer partnerships creates defensive moats against TPV displacement in fixed quarter glass applications. For New Entrants and Emerging Players: Regional polyurethane compounding gaps in India and the Southeast US represent the most penetrable white-space targets, where domestic OEMs are localizing windshield supply chains. Sensor cutout integration capabilities for Level 2+ autonomous vehicles offer a technical wedge against established compounders lacking embedded electronics expertise. Target fleet maintenance contract consolidation through certified installation network partnerships rather than direct OEM program competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with demonstrated ECE R43 homologation track records and captive automotive glass module assembly. Long-term viability hinges on navigating the transition from thermoset polyurethane toward recyclable encapsulation designs aligned with draft EU end-of-life vehicle regulations. Watch for inflection signals in TPV adoption rates among Stuttgart and Munich premium OEM pilot programs.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | Lidar and camera mounting bosses molded directly into encapsulation frames eliminate secondary bracket assembly for autonomous vehicle programs. |
| Regional Compounding Capacity | Localized polyurethane operations in India and the US Southeast reduce logistics exposure and align with domestic OEM supply chain localization mandates. |
| Low-Monomer Formulation Investment | Closed-loop RIM cells address ECHA respiratory protection mandates while raising entry barriers for mid-tier competitors. |
| Captive Weathering Facilities | In-house seal integrity testing transfers liability risk from vehicle assemblers and supports 10-year warranty underwriting for fleet contracts. |
| TPV Pilot Program Validation | BMW and Mercedes-Benz fixed quarter glass trials determine whether thermoplastic vulcanizate displaces polyurethane in premium sedan segments. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier procurement patterns anchors the qualitative findings in this study. Primary interviews with polyurethane compounding directors, automotive glass module procurement leads, RIM tooling specialists, and fleet maintenance contract negotiators were combined with secondary validation from vehicle production databases, customs trade flows for MDI and polyol feedstocks, ECE R43 homologation registries, and SEC filings from integrated glass manufacturers. Bottom-up demand modeling across vehicle platforms and top-down supply capacity assessments were triangulated to constrain forecast variance.
Sensitivity analysis on MDI price volatility, panoramic roof penetration rates, and REACH regulatory timelines shaped the analytical framework. Segmentation dimensions modeled include material chemistry tier, vehicle propulsion architecture, OEM premium-standard positioning, and regional production cluster. CAGRs were derived from installed base growth, content-per-vehicle expansion for head-up display and sensor integration applications, and replacement cycle dynamics across passenger and commercial vehicle fleets.
Underlying assumptions cover ECE R43 harmonization stability, polyurethane-to-TPV substitution velocity, and German-Japanese tooling capacity availability, with deviation risk concentrated in feedstock cost swings and autonomous vehicle sensor integration timelines. Practitioners should keep alternative scenarios live as thermoplastic vulcanizate validation outcomes and EU end-of-life vehicle regulation finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Automotive Cowl Screen Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Automotive Cowl Panel Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Automotive HVAC Market