
 Asia Pacific Automotive Bearing Market | 2026-2036
Asia Pacific Automotive Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive Bearing Market Outlook
A shift from single-source to multi-source procurement is repositioning how Japanese and Korean automakers manage bearing supply security. NSK Ltd leverages its domestic forging and heat-treatment infrastructure to sustain captive output of tapered roller bearings for commercial vehicle axles. JTEKT Corporation anchors regional competition through integrated steel-making and precision grinding operations in Thailand and India. SKF differentiates by controlling distribution channels across Southeast Asian aftermarket networks.
Automotive bearings are precision-engineered rolling or sliding components, typically fabricated from vacuum-degassed alloy steel with raceway hardness exceeding 58 HRC, designed to reduce friction and support radial or axial loads in powertrain, chassis, and steering assemblies. Roller bearings occupy the largest volume share across passenger and commercial vehicle applications due to their superior load-carrying capacity in wheel hub and transmission modules. Hybrid bearings, combining ceramic rolling elements with steel rings, represent the fastest-expanding technology segment as electrified powertrains impose higher rotational speeds and insulation demands. OEMs capture the dominant value pool through long-term supply agreements, though aftermarket providers are gaining margin traction as vehicle parc ages across Indonesia and Vietnam.
China's SAMR enforces GB/T rolling bearing standards that mandate dimensional accuracy and fatigue life testing for domestic supply eligibility. India's BIS certification scheme and Japan's JIS B 1514 precision standards create layered compliance barriers for imported bearing assemblies. METI's energy-efficiency roadmaps for automotive components are accelerating demand for low-torque bearing designs in hybrid vehicle transmissions. Stakeholders must monitor how China's dual carbon goals and India's PLI scheme for auto components reshape localization incentives and supplier qualification timelines.
Market Dynamics
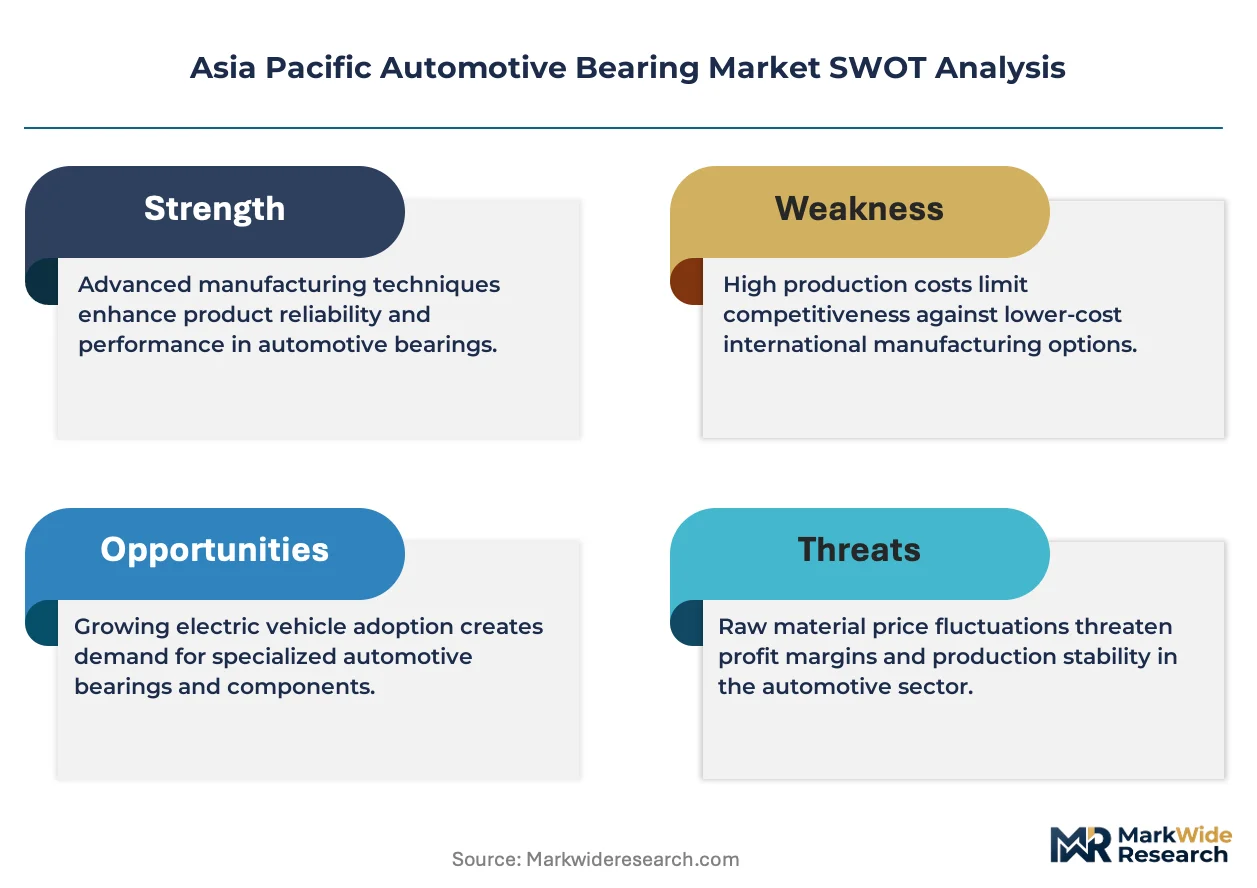
Electrification of powertrains is restructuring bearing procurement across Asia Pacific, as hybrid and battery-electric platforms demand ceramic-insulated rolling elements and sealed-for-life designs that legacy steel architectures cannot satisfy.
Growth Catalysts
- India's PLI scheme for auto components:The production-linked incentive program is accelerating localization of precision bearing manufacturing for electric two-wheelers and passenger vehicles.
- Ceramic rolling element adoption:Silicon nitride balls are penetrating high-speed motor applications in China's NEV sector, driven by rotational speed requirements exceeding 20,000 RPM.
- Thailand's Eastern Economic Corridor:Concentrated EV assembly investments by Japanese and Korean OEMs are pulling bearing procurement volumes into Bangkok-Rayong industrial clusters.
Market Restraints
- Alloy steel price volatility:Vacuum-degassed bearing steel input costs fluctuate with scrap metal and nickel pricing, compressing margin buffers for forged raceway producers.
- Supply concentration in Jiangsu-Zhejiang:China's domestic bearing base controls 60% of regional tapered roller output, creating single-geography exposure for multi-source procurement strategies.
- Hybrid bearing technical limitations:Ceramic-steel thermal expansion coefficient mismatch limits operating temperature ranges in commercial vehicle axle applications.
Strategic Opportunities
- Vietnam's underpenetrated aftermarket:Aging vehicle parc and limited domestic bearing production create import substitution potential for Indonesian and Thai distributors.
- Low-torque bearing designs:METI's energy-efficiency roadmaps for automotive components are opening specification windows for friction-reduced transmission bearings in hybrid powertrains.
- Direct-to-fleet distribution:Ride-hailing and logistics operators in Indonesia are bypassing traditional tiered distribution to negotiate volume bearing contracts directly.
Industry Challenges
- Precision grinding skill scarcity:Raceway superfinishing expertise concentrates in aging workforces across Osaka and Shanghai manufacturing bases.
- GB/T certification timeline compression:China's SAMR is accelerating fatigue life testing protocols, forcing foreign suppliers to duplicate domestic validation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive Bearing Market |
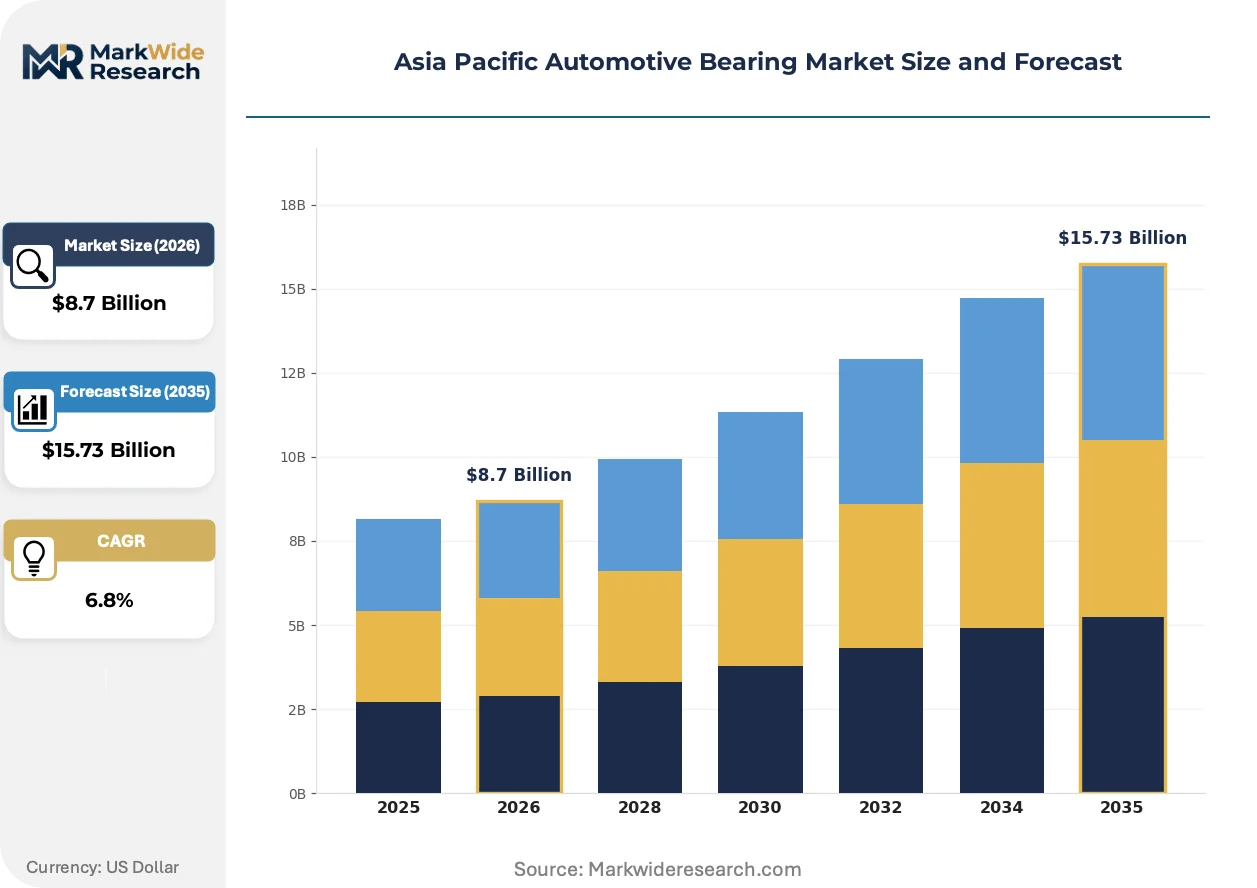
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Tapered Bearings, Spherical Bearings Technology: Hybrid Bearings, Magnetic Bearings, Slewing Bearings, Self-Lubricating Bearings End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Two-Wheelers |
| Companies Covered | NSK Ltd, JTEKT Corporation, NTN Bearing Corporation, SKF, Schaeffler AG, The Timken Company, Myonic GmbH, Minebea Mitsumi Inc., Nachi-Fujikoshi Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive Bearing Market Strategic Shifts
Material science advances and procurement model restructuring are converging to redefine competitive advantage in Asia Pacific bearing supply. Three developments warrant particular attention.
Hybrid bearing architectures combining ceramic rolling elements with steel rings are consolidating technical leadership in electrified powertrain applications. Chinese NEV manufacturers are specifying these configurations for drive motor support bearings. The technology is consolidating procurement decisions around suppliers with captive ceramic ball production.
China's GB/T rolling bearing standards are tightening dimensional accuracy mandates for domestic supply eligibility. SAMR enforcement is disqualifying imported assemblies that lack localized fatigue life documentation. Japanese and Korean Tier-1 suppliers are responding by establishing testing facilities in Jiangsu province.
Multi-source procurement contracts are displacing sole-source legacy agreements among Japanese automakers. Korean OEMs are following this pattern for wheel hub and transmission modules. The shift is most visible in Thailand's Eastern Economic Corridor, where assembly plants now qualify three bearing vendors per platform.
Asia Pacific Automotive Bearing Market Segmentation
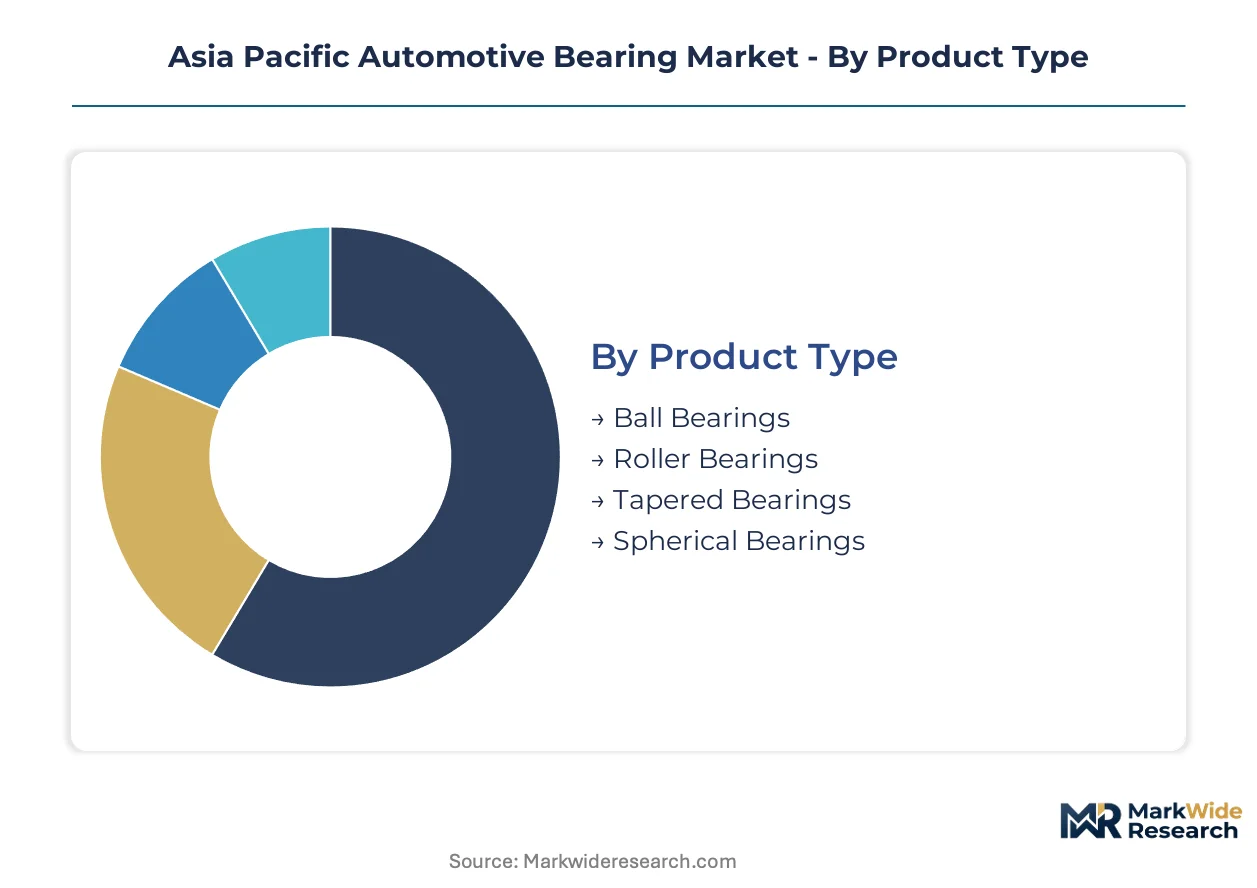
Segmentation in the Asia Pacific automotive bearing market reveals how electrification and localization pressures are redistributing procurement decisions across product architectures and supply tiers. Understanding these divides exposes where margin pools concentrate and which technical specifications are becoming non-negotiable for OEM qualification.
Product Type:
Material composition and raceway geometry determine load-bearing capacity, thermal tolerance, and suitability for electrified versus conventional powertrains.
- Roller Bearings:Cylindrical and needle configurations fabricated from vacuum-degassed alloy steel with case-hardened raceways dominate wheel hub and transmission modules across China's Jiangsu manufacturing clusters. Load distribution across line contact surfaces suits commercial vehicle axle applications where radial forces exceed ball bearing thresholds.
- Ball Bearings:Deep-groove and angular-contact designs with point-contact geometry enable high-speed rotation in electric motor support bearings for China's NEV sector. Point-contact friction characteristics align with METI energy-efficiency roadmaps for hybrid transmission modules.
- Tapered Bearings:Conical raceway geometry manages combined radial and axial loads in commercial vehicle differential assemblies across Thailand's Eastern Economic Corridor.
- Spherical Bearings:Self-aligning outer ring designs accommodate shaft deflection in off-road vehicle suspension linkages operating across Australia's mining corridors.
Roller bearings lead on scale; ball bearings lead on momentum.
Technology:
Functional differentiation in bearing architectures separates suppliers capable of electrification-ready specifications from legacy steel-only producers.
- Hybrid Bearings:Silicon nitride ceramic rolling elements combined with steel rings deliver rotational speeds exceeding 20,000 RPM and electrical insulation for NEV drive motors. Chinese OEMs are consolidating procurement around suppliers with captive ceramic ball production in Zhejiang province.
- Self-Lubricating Bearings:PTFE-impregnated or sintered bronze matrices eliminate grease maintenance in sealed-for-life designs demanded by extended-service EV powertrains. India's PLI scheme for auto components is accelerating domestic capacity for polymer-composite bearing platforms.
- Magnetic Bearings:Electromagnetic levitation eliminates mechanical contact in ultra-high-speed compressor applications for fuel cell vehicle hydrogen circulation systems.
- Slewing Bearings:Large-diameter crossed-roller configurations enable 360-degree rotation in construction equipment and mining truck pivot assemblies across Indonesia's equipment import market.
Hybrid configurations command premium positioning; self-lubricating designs are expanding most quickly into volume EV programs.
End User:
Supply tier positioning determines specification authority, contract duration, and exposure to localization mandates.
- OEMs:Vehicle manufacturers exercise direct procurement authority for powertrain bearings through long-term supply agreements with technical specification control. Japanese and Korean automakers are displacing sole-source contracts with multi-source qualification in Thailand's Eastern Economic Corridor.
- Tier-1 Suppliers:Transmission and axle system integrators aggregate bearing demand across multiple OEM platforms, concentrating volume leverage in India's precision component manufacturing zones.
- Aftermarket Providers:Independent distributors serve aging vehicle parc across Indonesia and Vietnam where domestic production capacity remains underdeveloped.
- Vehicle Assemblers:Contract manufacturers without full design authority source bearings to Tier-1 specifications in emerging ASEAN assembly operations.
OEMs anchor value capture; aftermarket channels are gaining margin traction as regional vehicle parc ages.
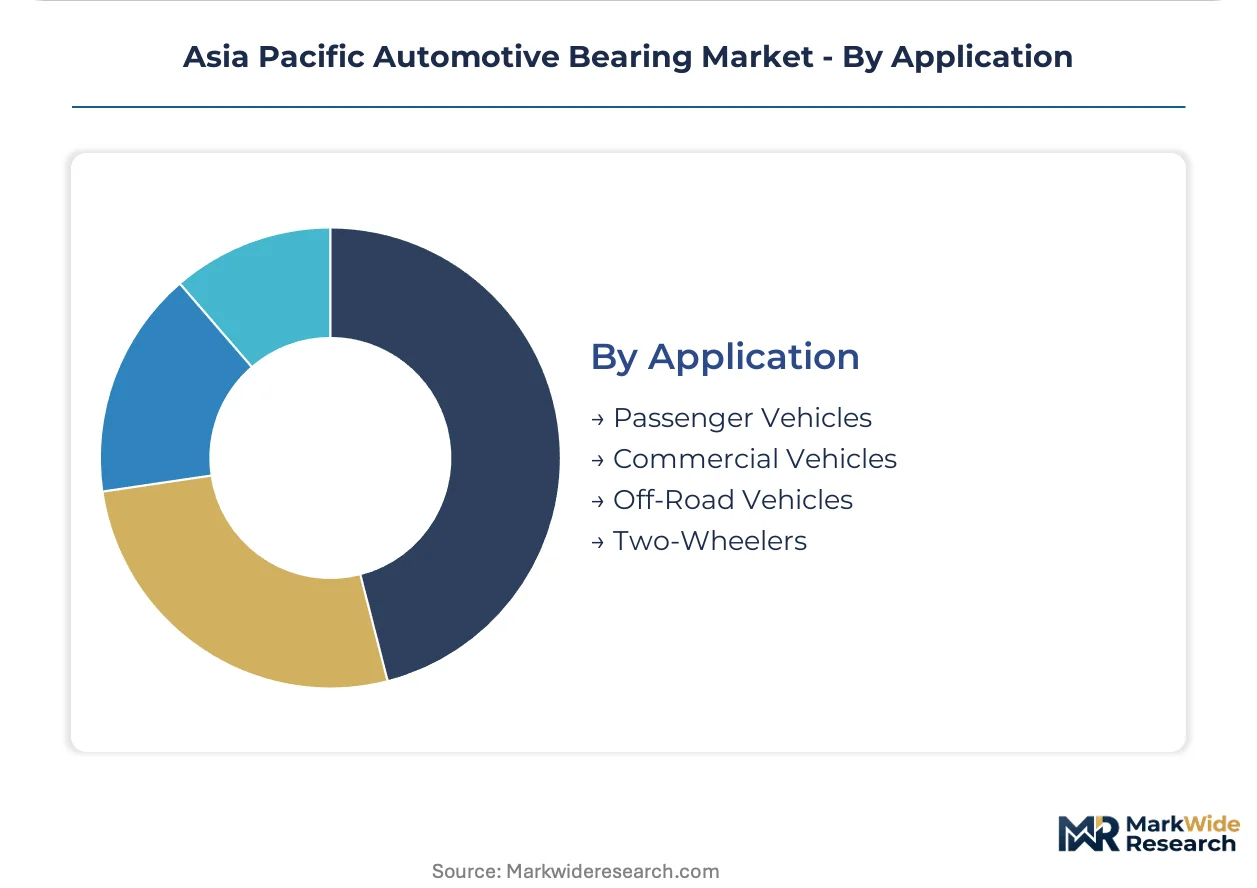
Application:
Vehicle category determines duty cycle severity, bearing specification tier, and replacement frequency economics.
- Passenger Vehicles:Light-duty applications prioritize low-torque bearing designs for hybrid transmission efficiency under METI roadmaps. China's GB/T standards mandate dimensional accuracy certification for domestic supply eligibility in this volume segment.
- Commercial Vehicles:Heavy-duty axle and wheel end applications require tapered roller configurations with superior load capacity. Fleet operators in Indonesia are negotiating direct volume contracts, bypassing traditional distribution tiers.
- Two-Wheelers:High-volume, cost-sensitive wheel hub and engine bearings dominate India's electric scooter localization programs under PLI incentives.
- Off-Road Vehicles:Mining and construction equipment demands sealed spherical bearings with contamination resistance for Australia's remote operation sites.
Passenger vehicles concentrate procurement volume; commercial vehicles drive specification premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting bearing procurement toward jurisdictions with localized certification infrastructure and converging energy-efficiency mandates. Production migration tracks the cost-of-compliance gap between legacy import-dependent markets and jurisdictions with domestic testing capacity.
China
NEV powertrain expansion and dual carbon implementation are accelerating hybrid bearing procurement from Jiangsu and Zhejiang manufacturing clusters. SAMR enforces GB/T rolling bearing standards that mandate localized fatigue life documentation for domestic supply eligibility. Zhejiang province concentrates silicon nitride ceramic ball production for drive motor applications exceeding 20,000 RPM.
Japan
METI energy-efficiency roadmaps for automotive components are specifying low-torque bearing designs in hybrid transmission modules. JIS B 1514 precision standards create compliance barriers for imported assemblies lacking domestic validation infrastructure. Osaka manufacturing bases retain concentrated raceway superfinishing expertise amid aging workforce constraints.
India
PLI scheme incentives for auto components are localizing precision bearing capacity for electric two-wheelers and passenger vehicles. BIS certification requirements disqualify imported assemblies without domestic testing documentation. Tamil Nadu and Maharashtra industrial zones are scaling forged raceway production for Tier-1 transmission integrators.
Thailand
Eastern Economic Corridor EV assembly investments by Japanese and Korean OEMs are pulling bearing procurement volumes into Bangkok-Rayong industrial clusters. Board of Investment incentives prioritize localized component sourcing for battery-electric platform qualification. Rayong province hosts concentrated forging and heat-treatment operations serving regional commercial vehicle axle demand.
Vietnam
Aging vehicle parc and limited domestic bearing production are creating import substitution openings for regional distributors. Ministry of Industry and Trade regulations favor localized assembly operations without mandating full supply chain domestication. Ho Chi Minh City logistics corridors are emerging as aftermarket distribution hubs for Indonesian and Thai bearing providers.
Asia Pacific Automotive Bearing Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue ceramic-insulated configurations for electrified powertrains. The vendor base stratifies across integrated steel-makers with captive forging capacity, precision grinding specialists with superfinishing expertise, and ceramic component providers with silicon nitride ball production. Japanese and Korean conglomerates anchor the integrated tier through backward control over alloy steel input. Strategic moves concentrate on multi-source procurement qualification and localized testing facility establishment.
Within the integrated steel-making tier, NSK Ltd and JTEKT Corporation exemplify producers with captive forging and heat-treatment infrastructure. SKF occupies a position among distributors controlling aftermarket channels across Southeast Asian networks. These three entities represent distinct competitive archetypes: domestic integrated production, regional precision manufacturing, and channel-anchored distribution.
| Leading Market Players |
|---|
| NSK Ltd |
| JTEKT Corporation |
| NTN Bearing Corporation |
| SKF |
| Schaeffler AG |
| The Timken Company |
| Myonic GmbH |
| Minebea Mitsumi Inc. |
| Nachi-Fujikoshi Corp. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between GB/T-validated hybrid bearings and commodity steel configurations manifests in dual pricing architectures and geographically split sourcing strategies across the Asia Pacific automotive bearing market. OEM procurement teams pay premium multiples for ceramic-insulated platforms with localized fatigue life documentation while aftermarket channels absorb margin compression on legacy tapered roller imports from Jiangsu-Zhejiang manufacturing clusters.
Pricing Analysis
Distributor margin layers separate OEM direct contracts from aftermarket retail markups, with Thai and Indonesian logistics operators negotiating volume discounts that bypass traditional tiered channels. Three-tier pricing structure across premium hybrid, standard roller, and economy ball bearing tiers reflects GB/T certification investment, silicon nitride ceramic content, and heat-treatment precision grades. Cost compression in commodity steel bearings intensifies as vacuum-degassed alloy scrap prices fluctuate with nickel markets. Fleet operators in Indonesia exhibit highest price sensitivity, while Japanese OEMs prioritize specification compliance over unit cost in multi-source qualification programs.
Supply Chain Analysis
Regional distribution centers in Bangkok-Rayong and Ho Chi Minh City operate hub-and-spoke patterns feeding ASEAN aftermarket networks. Manufacturing concentrates in China's Jiangsu and Zhejiang provinces, Japan's Osaka industrial corridor, and India's Tamil Nadu precision component zones. Raw material dependencies center on vacuum-degassed bearing steel, silicon nitride ceramic powder, and specialized grinding abrasives. Single-source vulnerability in Jiangsu-Zhejiang tapered roller output exposes multi-source procurement strategies to geographic concentration risk. Distribution runs through Tier-1 system integrators for OEM channels and independent distributors for replacement demand across Vietnam and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific automotive bearing market functions as a regulatory compounder where China's SAMR GB/T enforcement and India's PLI localization mandates continuously escalate compliance investment thresholds for supply eligibility.
For Market Incumbents: Hedge against ceramic ball supply bottlenecks by securing captive silicon nitride production partnerships in Zhejiang province before qualification windows close for NEV platform awards. Defensive consolidation of raceway superfinishing expertise in Osaka and Shanghai manufacturing bases offsets precision grinding skill scarcity threatening output quality. Backward integration into vacuum-degassed steel forging insulates margin buffers from scrap metal price volatility compressing commodity bearing producers. For New Entrants and Emerging Players: Begin with Vietnam's underpenetrated aftermarket where aging vehicle parc and limited domestic production create import substitution openings for Thai and Indonesian distributors. Target electric two-wheeler bearing localization under India's PLI scheme, the most penetrable segment given volume scale and technical specification accessibility. A direct-to-fleet distribution angle bypassing traditional tiered channels captures margin pools from ride-hailing and logistics operators in Jakarta and Ho Chi Minh City. For Investors and Strategic Acquirers: Consolidation pressure builds where precision grinding expertise concentrates in aging workforces across Osaka and Shanghai manufacturing bases without generational knowledge transfer pipelines. Long-term viability across the projection horizon favors targets with captive ceramic ball production and localized GB/T testing infrastructure already operational. The signal to watch is accelerated SAMR fatigue life protocol compression forcing foreign suppliers to duplicate domestic validation facilities or exit China supply eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Localized GB/T Testing Facility Establishment | SAMR enforcement now mandates domestic fatigue life documentation for supply eligibility in China's NEV sector. |
| Captive Silicon Nitride Ceramic Ball Production | Chinese OEMs consolidate procurement around suppliers with in-house ceramic manufacturing for 20,000 RPM motor applications. |
| Multi-Source Procurement Qualification | Japanese and Korean automakers now qualify three bearing vendors per platform in Thailand's Eastern Economic Corridor. |
| Direct-to-Fleet Distribution Partnership | Indonesian ride-hailing operators bypass traditional tiers to negotiate volume contracts for commercial vehicle axle bearings. |
| Precision Grinding Workforce Development | Raceway superfinishing expertise scarcity in aging Osaka and Shanghai workforces threatens output quality and capacity expansion. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and precision grinding operations managers alongside secondary validation. Automotive-specific sources included vehicle production databases, IHS Markit registration data, customs trade records for bearing steel and ceramic powder flows, and SAMR GB/T certification registries. Bottom-up bearing unit demand modeling triangulated against top-down powertrain production forecasts across the analysis window.
Comparable-period anchoring tied projection assumptions to historical reference periods spanning conventional ICE platform demand through electrified powertrain transition phases. Segmentation dimensions modeled encompassed product type, technology architecture, propulsion system, OEM tier positioning, and regional production cluster. CAGRs derived from regression analysis of procurement volume trajectories against NEV penetration curves and localization incentive intensity. Industry-specific inputs included GB/T certification timeline compression rates and PLI scheme localization milestones.
Several conditions sit outside the modeled scope, including abrupt alloy steel commodity price shocks, trade policy discontinuities affecting ASEAN-Japan supply corridors, and unanticipated ceramic ball manufacturing technology breakthroughs. Forecasts reflect documented assumptions around SAMR enforcement continuity and PLI scheme extension. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Torque Vectoring Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
Automotive Refrigerant Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Europe Heat Shrink Tubing for Automotive Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Automotive Carbon Fiber Components Market
Automotive Components
Automotive Axle Market
Automotive Components
Automotive Radiator Fan Market