
 Global Automotive Window Regulator Market | 2026-2036
Global Automotive Window Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Window Regulator Market Foresight
Competitive Landscape
ISO/TS 16949 qualification is bifurcating the supplier base between certified tier-1 incumbents and unqualified challengers. Brose Fahrzeugteile GmbH & Co. KG leverages its captive motor production to anchor European OEM contracts. Robert Bosch GmbH competes through electro-mechanical integration that extends from regulators into full door modules. Magna International dominates North American supply through backward integration into cable extrusion and stamping.
Product Structure
An automotive window regulator is a mechanical or electro-mechanical lifting mechanism that translates rotary motor output into vertical glass travel, typically achieving stroke lengths of 200-400mm and load capacities exceeding 80N to support laminated side glazing. The device serves the primary industrial purpose of enabling occupant-controlled ventilation, toll access, and emergency egress while satisfying FMVSS 118 anti-pinch mandates. Power regulators lead unit volume across passenger vehicle applications where single-touch convenience has become a baseline expectation. Cable regulators represent the fastest-growing product architecture as OEMs pursue mass reduction targets that scissor linkages struggle to meet. Electric motor technology commands the deepest margin pool due to proprietary magnet formulations and controller firmware that tier-1 suppliers protect.
Regulatory Environment
Federal Motor Vehicle Safety Standard 118 in the United States and ECE R21 in Europe govern anti-entrapment force limits and head impact performance, compelling suppliers to embed torque sensing and pinch detection into every power regulator design. China's GB 11552 standard and MIIT new-energy vehicle catalog requirements add local content and electromagnetic compatibility layers that foreign suppliers must navigate through joint ventures or wholly-owned subsidiaries. Stakeholders should monitor how UN R158 rear-visibility mandates and evolving software-defined vehicle architectures reshape the interface between window regulators and centralized body control modules.
Market Dynamics
The automotive window regulator market faces structural pressure from ECE R21 head impact standards, which force redesign cycles toward lighter cable mechanisms and away from legacy scissor architectures. Suppliers must simultaneously satisfy FMVSS 118 anti-pinch mandates while reducing mass to meet fleet efficiency targets.
Growth Catalysts
- Electric vehicle OEM procurement:Battery-electric platforms require power regulators for every door position, expanding the addressable base beyond traditional ICE configurations. Premium EV architectures demand quiet, high-torque motors.
- ECE R21 compliance cycles:European head impact standards accelerate replacement of metal-intensive scissor linkages with polymer-reinforced cable systems that absorb collision energy more predictably.
- China's MIIT new-energy catalog:Local content requirements for NEV subsidies compel foreign suppliers to establish joint ventures or wholly-owned subsidiaries, deepening in-country production capacity.
Market Restraints
- Neodymium magnet cost volatility:Rare-earth price swings compress margins on high-torque DC motors, forcing suppliers to hedge or redesign for ferrite alternatives with performance trade-offs.
- Tier-1 supply concentration:European and North American procurement gravitates toward ISO/TS 16949-certified incumbents with captive motor production, creating barriers for unqualified challengers seeking OEM validation.
- Scissor linkage obsolescence:Traditional metal scissor mechanisms face displacement by cable architectures, stranding capital equipment and specialized stamping tooling at legacy suppliers.
Strategic Opportunities
- Software-defined vehicle integration:Centralized body control modules create openings for smart regulators with CAN/LIN connectivity and over-the-air diagnostic capability, merging mechanical and firmware competencies.
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive parts attract cable extrusion and motor assembly investments serving domestic OEMs and export markets.
- Aftermarket smart retrofits:Bluetooth-enabled regulator kits address aging vehicle fleets in Germany and the United States, bypassing traditional dealer channel dependence through direct-to-installer distribution.
Industry Challenges
- ISO/TS 16949 certification timelines:New entrants face 12-18 month qualification periods before OEMs release production purchase orders, delaying revenue recognition and straining working capital.
- Electro-mechanical firmware integration:Torque sensing and pinch detection algorithms require embedded software competencies foreign to traditional mechanical suppliers, forcing talent acquisition or partnership decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Window Regulator Market |
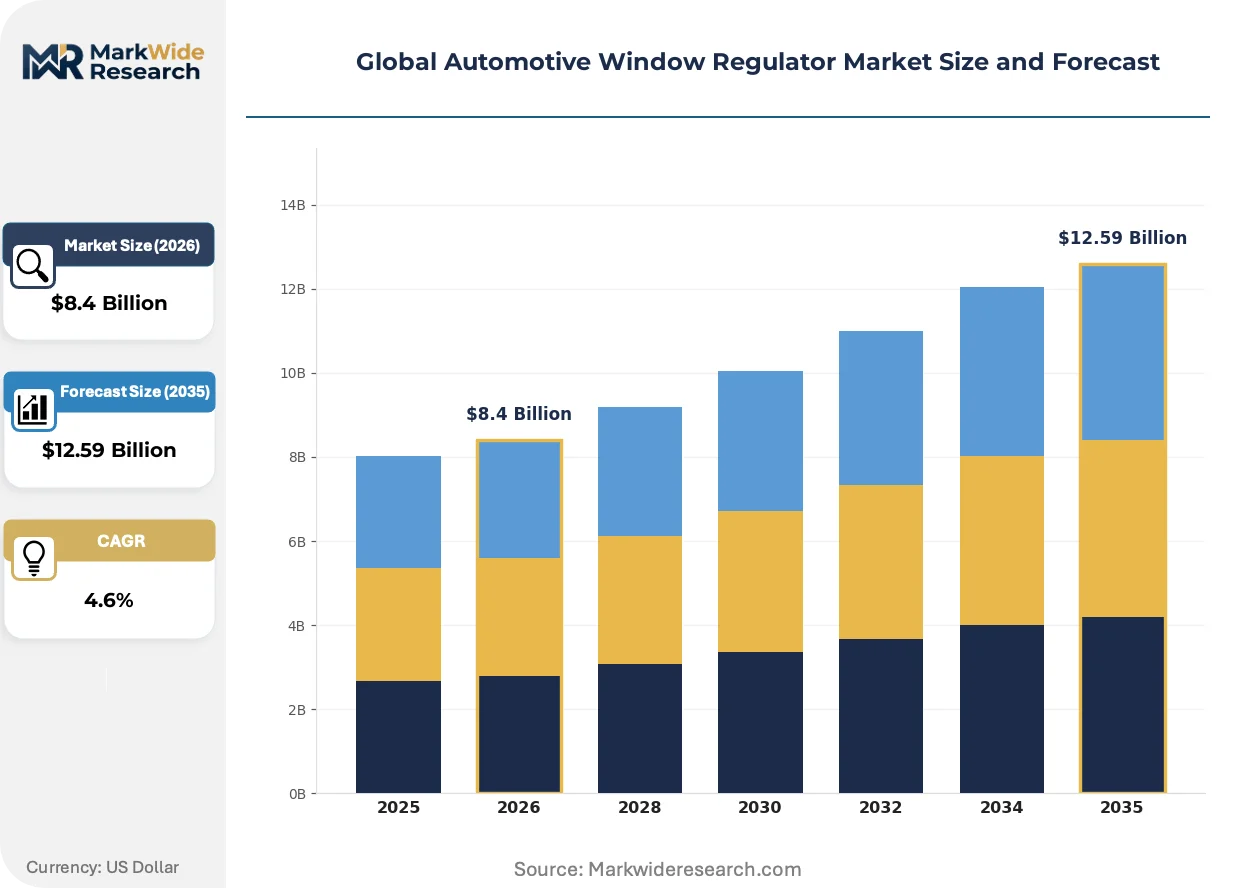
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Regulator, Power Regulator, Electric Motor Regulator, Cable Regulator, Scissor Regulator Technology: Electric Motor, Hydraulic, Mechanical, Electro-Mechanical, Pneumatic Application: Passenger Vehicles, Commercial Vehicles, Specialty Vehicles, Off-Road Vehicles, Two-Wheelers End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Auto Repair Shops, Tier-1 Suppliers |
| Companies Covered | Grupo Antolin, Aisin Seiki Co., Ltd., Continental AG, Denso Corporation, Robert Bosch GmbH, Magna International, Valeo SA, Shiroki Corporation, Brose Fahrzeugteile GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Window Regulator Market Shifts & Advancements
Window regulator technology is converging with centralized vehicle electronics, compressing the boundary between mechanical lifting hardware and software-controlled body systems. Three distinct vectors are reshaping product architecture and competitive positioning.
Magnet wire winding technology is miniaturizing. High-density slot-fill techniques enable smaller DC motor footprints without torque sacrifice. Chinese and Korean OEMs are adopting these compact drives for A-segment electric vehicles where door module packaging space is severely constrained. The technology is miniaturizing motor dimensions while maintaining 80N load capacity, allowing single-platform designs to span multiple vehicle classes.
REACH substance restrictions on hexavalent chromium coatings are forcing suppliers to migrate cable pulleys and guide rails to trivalent chrome or zinc-nickel alternatives. European Tier-1s face 2025 compliance deadlines for new platform approvals, accelerating qualification of corrosion-resistant polymer pulleys in cable regulator architectures. German OEMs are prioritizing suppliers with verified substitution documentation to avoid supply interruption.
Fleet operators and mobility-as-a-service providers are unbundling window regulator replacement from full door module procurement. Rental car companies in the United States now source cable-and-motor kits separately from stamped carriers, compressing repair cycle times and reducing parts inventory. This behavioral shift pressures integrated module suppliers to disaggregate product structures or risk displacement by specialized component vendors.
Global Automotive Window Regulator Market Segmentation
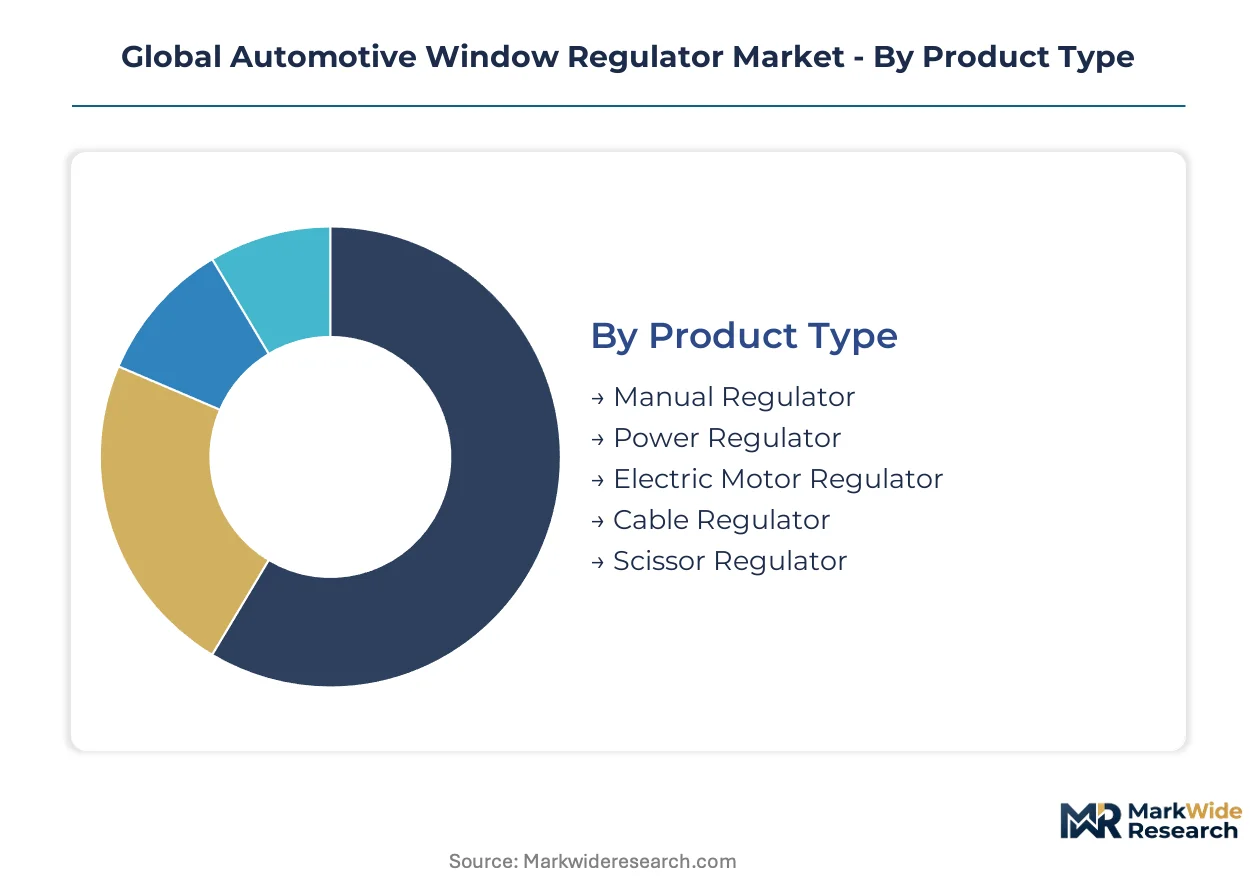
Automotive window regulator segmentation reflects divergent regulatory pressures across safety, emissions, and electromagnetic compatibility domains. Suppliers must align product architectures with FMVSS 118 anti-pinch mandates, ECE R21 head impact standards, and China's GB 11552 local content requirements.
Product Type:
FMVSS 118 force limits and ECE R21 energy absorption standards split the product landscape between compliant power mechanisms and legacy manual systems.
- Power Regulator:Electro-mechanical lifting systems integrate DC motors with torque sensing and pinch detection firmware to satisfy FMVSS 118 mandates. Battery-electric vehicle platforms in China, Germany, and the United States specify these for every door position, expanding procurement volumes beyond traditional ICE configurations.
- Cable Regulator:Polymer-reinforced cable architectures replace metal-intensive scissor linkages to meet ECE R21 head impact standards while achieving mass reduction targets. European OEMs prioritize these designs for new platform approvals, accelerating supplier qualification cycles.
- Manual Regulator:Hand-crank mechanisms persist in entry-level commercial vehicles and certain emerging market segments where cost minimization outweighs convenience expectations.
- Electric Motor Regulator:Integrated motor-and-controller units with proprietary magnet formulations command premium positioning in luxury vehicle architectures.
- Scissor Regulator:Traditional metal linkage systems face displacement by cable alternatives, stranding specialized stamping tooling at legacy suppliers.
Power regulators handle the majority of throughput; cable regulators are gaining share fastest as OEMs redesign for head impact compliance.
Technology:
Cost tier differentiation separates high-margin proprietary motor technologies from commodity mechanical alternatives.
- Electric Motor:High-density slot-fill winding techniques miniaturize DC motor footprints without torque sacrifice. Chinese and Korean OEMs adopt these compact drives for A-segment electric vehicles where door module packaging space is severely constrained.
- Electro-Mechanical:Integrated torque sensing and CAN/LIN connectivity merge mechanical hardware with embedded firmware, creating openings for smart diagnostic capabilities in software-defined vehicle architectures.
- Mechanical:Pure mechanical linkages without motor integration serve cost-sensitive applications in commercial vehicle segments.
- Hydraulic:Fluid-powered lifting systems occupy niche applications in heavy-duty off-road equipment where electrical system reliability is constrained.
- Pneumatic:Compressed-air actuation persists in specialty industrial vehicles with existing pneumatic infrastructure.
Electric motor technology captures the deepest margin pool; electro-mechanical integration is expanding most quickly as centralized body control modules reshape vehicle electronics.
Application:
Volume concentration tracks assembly plant locations and local content requirements in major automotive manufacturing clusters.
- Passenger Vehicles:Light-duty automobiles with single-touch power windows as baseline equipment. Production volumes concentrate in China, Germany, and the United States where OEM assembly operations intersect with tier-1 supplier ecosystems.
- Commercial Vehicles:Medium and heavy-duty trucks with durability-focused regulator specifications. Fleet operators in the United States unbundle window regulator replacement from full door module procurement, compressing repair cycle times.
- Specialty Vehicles:Ambulances, limousines, and modified mobility vehicles with custom glass travel requirements.
- Off-Road Vehicles:Construction and agricultural equipment with sealed-environment durability specifications.
- Two-Wheelers:Motorcycles with minimal or no window mechanisms; negligible addressable market for traditional regulator suppliers.
Passenger vehicles dominate unit volume; commercial vehicles are climbing the fastest on aftermarket disaggregation trends.
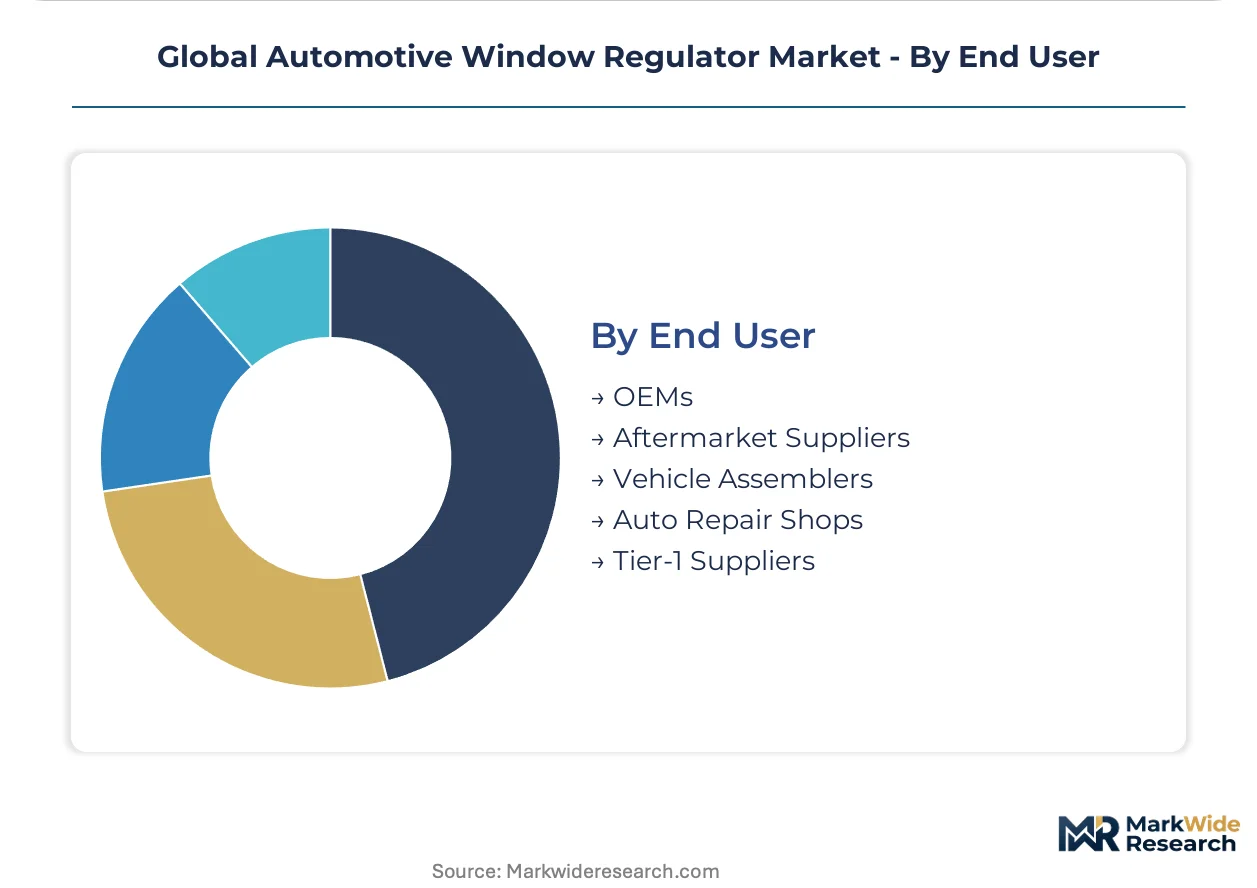
End User:
Customer type determines certification requirements and procurement channel structure.
- OEMs:Original equipment manufacturers with ISO/TS 16949 qualification mandates and 12-18 month supplier validation timelines. Brose, Bosch, and Magna anchor European and North American contracts through captive motor production and backward integration into cable extrusion.
- Aftermarket Suppliers:Independent distributors serving aging vehicle fleets with Bluetooth-enabled retrofit kits. Direct-to-installer distribution channels in Germany and the United States bypass traditional dealer dependence.
- Vehicle Assemblers:Contract manufacturing operations with localized sourcing requirements under China's MIIT new-energy catalog.
- Auto Repair Shops:Service bay operators with demand for rapid-install cable-and-motor kits separate from stamped carriers.
- Tier-1 Suppliers:Integrated module producers facing pressure to disaggregate product structures or risk displacement by specialized component vendors.
OEMs control the majority of value capture; aftermarket suppliers are expanding most quickly on fleet operator behavioral shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT new-energy vehicle catalog requirements are reshaping procurement patterns across major manufacturing clusters. Assembly volumes concentrate where local content mandates intersect with established tier-1 supplier ecosystems.
China
NEV subsidies under MIIT catalog rules compel foreign suppliers to establish joint ventures or wholly-owned subsidiaries. GB 11552 standards add electromagnetic compatibility layers that reshape component sourcing. Yangtze River Delta clusters around Shanghai anchor cable extrusion and motor assembly investments serving domestic OEMs.
Germany
ECE R21 head impact standards accelerate replacement of metal-intensive scissor linkages with polymer-reinforced cable systems. REACH substance restrictions on hexavalent chromium coatings force migration to trivalent chrome alternatives. Bavarian automotive corridors prioritize suppliers with verified substitution documentation to avoid supply interruption.
United States
FMVSS 118 anti-pinch mandates embed torque sensing into every power regulator design. Fleet operators unbundle window regulator replacement from full door module procurement, compressing repair cycle times. Michigan and Ohio assembly corridors concentrate backward integration into cable extrusion and stamping capacity.
Japan
METI industrial policy supports compact motor development for A-segment electric vehicles where door module packaging space is constrained. JIS quality standards maintain high barriers for component qualification. Kanto and Kansai manufacturing belts concentrate high-density slot-fill winding techniques for miniaturized DC drives.
South Korea
MFDS-equivalent automotive component standards align with export market requirements in Europe and North America. Domestic OEMs adopt compact motor architectures for battery-electric platforms. Seoul Capital Area and Busan-Ulsan corridors anchor electro-mechanical integration investments.
Global Automotive Window Regulator Market Competitive Landscape
Player mix skews toward tier-1 incumbents with captive motor production and ISO/TS 16949 certification. European and North American procurement gravitates toward qualified suppliers with 12-18 month validation timelines, creating barriers for unqualified challengers. Two strategic archetypes dominate: integrated module producers with backward integration into cable extrusion, and specialized motor-and-controller units with proprietary magnet formulations. Competitive moves concentrate on electro-mechanical firmware integration and software-defined vehicle connectivity.
Within the integrated module tier, Brose Fahrzeugteile GmbH & Co. KG and Magna International exemplify archetypes with European and North American geographic anchoring respectively. Robert Bosch GmbH occupies a position spanning electro-mechanical integration into full door systems. These three represent the consolidation pattern where captive production capabilities and certification status determine contract access.
| Leading Market Players |
|---|
| Grupo Antolin |
| Aisin Seiki Co., Ltd. |
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Magna International |
| Valeo SA |
| Shiroki Corporation |
| Brose Fahrzeugteile GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month qualification timelines for ISO/TS 16949 certification compress supplier bargaining power and anchor pricing premiums to captive motor production capabilities in Germany, China, and the United States. This lead-time rigidity reinforces tier-1 incumbents' pricing control while forcing unqualified challengers toward aftermarket channels where price competition intensifies.
Pricing Analysis
Certification level creates the primary spread between ISO/TS 16949-qualified tier-1 incumbents and unqualified challengers. Three-tier pricing structure across premium, standard, and economy levels tracks captive motor production, backward integration depth, and firmware sophistication. Pricing pressure stems from neodymium magnet cost volatility compressing margins on high-torque DC motors. Fleet operators and mobility-as-a-service providers exhibit highest price sensitivity through unbundled procurement of cable-and-motor kits separate from stamped carriers.
Supply Chain Analysis
Just-in-time inventory strategies dominate OEM procurement, with tier-1 suppliers maintaining 15-30 days of finished goods to accommodate platform engineering changes. Supply concentrates in China for rare-earth magnet processing, Germany for precision stamping and cable extrusion, and the United States for integrated door module assembly. Raw material dependencies include neodymium-iron-boron magnets, galvanized steel for scissor linkages, and polymer compounds for cable sheaths. Single-source vulnerability in rare-earth supply chains from China feeds into pricing volatility. Distribution runs through captive tier-1 supplier networks directly to OEM assembly plants, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket smart retrofits with Bluetooth-enabled diagnostic capability are expanding faster than hardware-only replacement kits, creating service-attach revenue pools that outpace underlying unit growth in Germany and the United States.
For Market Incumbents: Secure firmware integration capabilities through embedded software talent acquisition or targeted partnerships, as torque sensing and pinch detection algorithms become table stakes for OEM contracts. Defend against specialized component vendors by disaggregating integrated door modules into separable cable-and-motor kits for fleet operator procurement. Deepen backward integration into cable extrusion and magnet wire winding to offset rare-earth price volatility. For New Entrants and Emerging Players: ISO/TS 16949 certification fast-track programs through automotive industry associations in India and South Korea offer the most penetrable entry path. Target aftermarket channels in Germany and the United States with direct-to-installer distribution of smart retrofit kits, bypassing 12-18 month OEM validation timelines. White-space exists in compact motor architectures for A-segment electric vehicles where packaging constraints favor miniaturized high-density slot-fill designs. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because tier-1 supply concentration and certification barriers favor incumbents with captive production capabilities. Target acquisition archetypes include specialized motor-and-controller units with proprietary magnet formulations and verified firmware competencies. Watch for inflection when software-defined vehicle architectures accelerate CAN/LIN connectivity requirements beyond mechanical supplier capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces tooling costs across multiple vehicle classes for OEMs in China and Germany. |
| Battery Supply Agreement | Locks in power regulator volumes for every door position on dedicated EV architectures. |
| Software-Defined Vehicle Investment | Enables over-the-air diagnostic capability and firmware updates through centralized body control modules. |
| Geographic Manufacturing Footprint | Satisfies China's MIIT local content requirements for NEV subsidy eligibility. |
| Charging Infrastructure Partnership | Creates fleet operator touchpoints for aftermarket smart retrofit kit distribution in the United States. |
Research Methodology
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers provided ongoing calibration against vehicle production realities. Primary fieldwork combined structured interviews with secondary validation from IHS Markit registration data, vehicle production databases, customs and trade flow records, and SEC filings from listed automotive component suppliers. Bottom-up unit volume estimates triangulated against top-down market value reconstructions.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from regression analysis of historical production volumes and platform launch schedules. Industry-specific forecast inputs captured ECE R21 compliance cycle timing and MIIT catalog update frequencies.
Decision-makers should treat outputs as directional under assumptions of stable rare-earth supply chains and continued NEV subsidy regimes; material deviation would warrant model refresh. Forecasts reflect documented assumptions about regulatory enforcement timelines and OEM platform consolidation patterns. Revision becomes warranted when neodymium price volatility or software-defined vehicle adoption crosses thresholds that reshape supplier capability requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Automotive Fuel Injection System Market
Automotive Components
Automotive Carbon Fiber Components Market
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Automotive Light Bars Market