
 India Automotive Sunroof Market | 2026-2036
India Automotive Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Sunroof Market Foresight
Gujarat-based automotive glass suppliers is broadening polycarbonate conversion capacity for sunroof modules. Webasto Roof Systems Inc. leverages its technical center in Pune to sustain engineering support for domestic OEM programs. Minda Corporation Limited anchors aftermarket distribution through its nationwide dealer network, while Inalfa Gabriel Sunroof Systems Private Limited competes on localized assembly cost structures.
An automotive sunroof is a movable or fixed transparent panel integrated into a vehicle roof structure, typically constructed from tempered glass, polycarbonate, or acrylic composites with UV-resistant interlayers, designed to admit natural light and ventilation while maintaining structural integrity per AIS-037 crash standards. The product serves both aesthetic differentiation and cabin comfort enhancement for passenger vehicle OEMs and retrofit channels. Panoramic sunroof configurations command the highest value per unit given their multi-panel glass architecture and complex rail mechanisms, while power-operated systems dominate installation rates due to consumer preference for one-touch convenience. Glass material segments retain margin concentration despite polycarbonate's weight advantage, owing to Indian consumer perception of premium tactile quality and optical clarity.
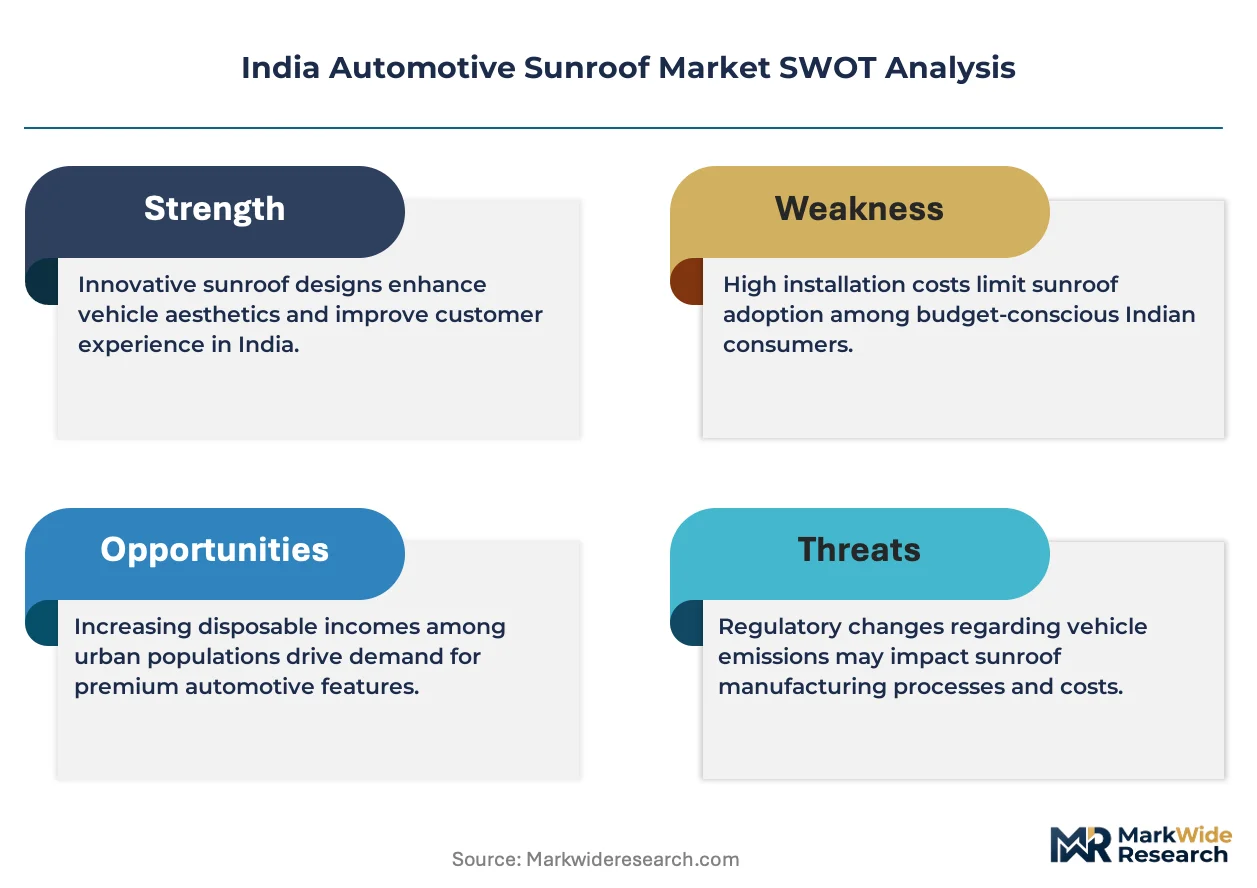
BIS certification requirements for automotive glass and AIS-037 roof crush standards directly shape product design validation timelines and supplier qualification barriers for sunroof manufacturers serving Indian OEMs. The PLI scheme for automotive components and CEA energy-efficiency guidelines for manufacturing facilities further influence capital allocation decisions for domestic production expansion. Stakeholders must monitor evolving AIS safety test protocols and state-level EV manufacturing incentives that could redirect vehicle platform priorities and sunroof specification trajectories.
Market Dynamics
Power-operated panoramic configurations are compressing manual tilt-and-slide variants as Maharashtra and Gujarat OEMs prioritize cabin differentiation for premium SUV platforms. Rail mechanism localization in Pune and Chennai supplier parks is redrawing cost structures for domestic assembly programs.
Growth Catalysts
- PLI Scheme for Automotive Components:Domestic capital subsidies are accelerating polycarbonate conversion line investments across Gujarat-based glass suppliers. Tier-1 vendors are qualifying localized rail actuator assemblies under revised incentive thresholds.
- Maharashtra Premium SUV Demand:Western India dealer networks report elevated take rates for multi-panel glass architectures in vehicles above 4.5-meter wheelbase categories. Consumer preference for one-touch ventilation is displacing fixed glass roof options.
- AIS-037 Roof Crush Standards:Enhanced validation protocols for transparent panel structural integrity are filtering out uncertified aftermarket suppliers. OEM-approved sunroof modules now carry mandatory BIS glass certification marks.
Market Restraints
- Polycarbonate Resin Import Dependency:Specialized optical-grade polymer feedstock concentrates in East Asian chemical complexes, exposing domestic converters to freight and duty volatility. Local petrochemical capacity lacks optical clarity specifications for automotive glazing.
- CEA Energy-Efficiency Compliance:Manufacturing facility power consumption benchmarks add capital burden to vacuum deposition and UV interlayer curing processes. Smaller module assemblers face plant retrofit costs to maintain operating licenses.
- Glass-Weight Penalty in EV Platforms:Battery-electric vehicle range sensitivity favors polycarbonate mass reduction, yet Indian consumer tactile preference for tempered glass resists material substitution in visible cabin surfaces.
Strategic Opportunities
- Southern India Aftermarket Channel:Tamil Nadu and Karnataka independent service centers lack authorized sunroof retrofit capability, creating whitespace for certified installation partnerships. Panoramic module replacement demand from 2018-2022 vehicle cohorts is emerging.
- BIS Modular Certification Pathways:Streamlined type-approval for rail mechanism and glass panel subassemblies separately could reduce OEM program validation timelines. Component-level testing would enable supplier mix-and-match flexibility.
- Smart Glass Electrochromic Convergence:Integration of dimmable interlayers with power-operated rail systems offers cabin thermal management differentiation. Technology licensing from aerospace glazing specialists is penetrating automotive tier-2 supply.
Industry Challenges
- Rail Mechanism Precision Engineering Talent:Domestic vocational pipelines produce insufficient technicians for micron-tolerance actuator calibration and waterproof sealing verification. Foreign-trained specialists command compensation premiums that strain mid-tier assembler margins.
- Multi-Supplier Integration Complexity:Panoramic sunroof programs require synchronized qualification of glass processors, rail manufacturers, and motor control electronics vendors. Program delays cascade when any single subassembly fails AIS-037 crash validation.
- AIS Test Protocol Revision Cycles:Evolving roof crush and projectile impact standards force redesign iterations during active production phases. Validation backlog at government test facilities extends time-to-market for new vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Sunroof Market |
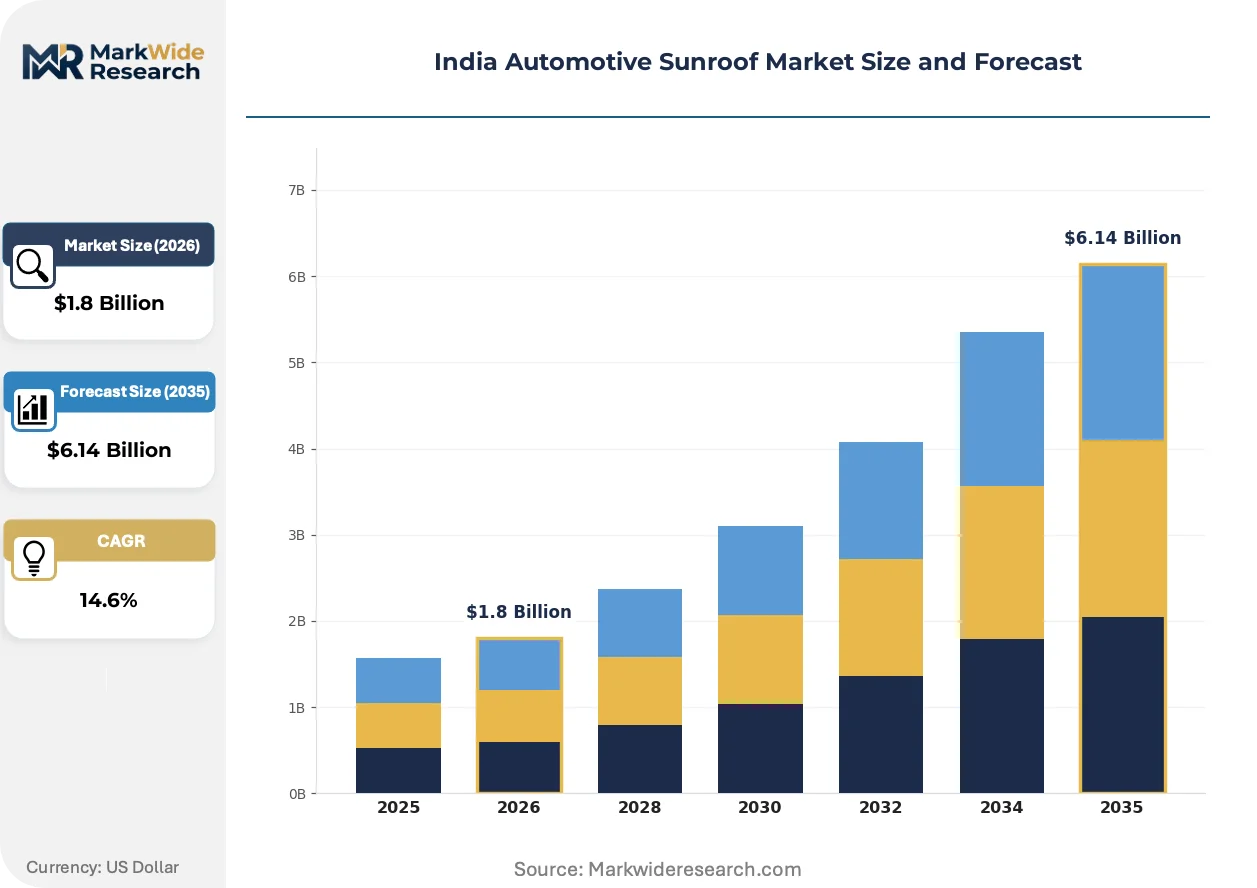
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panoramic Sunroof, Conventional Sunroof, Solar Sunroof, Transparent Sunroof Vehicle Type: SUV, Sedan, Hatchback, Coupe Material: Glass, Polycarbonate, Acrylic, Composite Operating Mechanism: Manual, Power-Operated, Hybrid, None |
| Companies Covered | Inalfa Gabriel Sunroof Systems Private Limited, Inteva Products, Webasto Roof Systems Inc., Gabriel India Limited, CIE Automotive, Inalfa Roof Systems Group, Minda Corporation Limited, Yachiyo Industry Co. Ltd, Motherson Yachiyo Automotive Systems Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Sunroof Market Shifts & Advancements
Transparent panel architectures are bifurcating into fixed panoramic glass for mass-market differentiation and intelligent power-operated systems for premium positioning. Material science advances and regulatory pressure are compressing legacy tilt-and-slide configurations.
Polycarbonate multi-layer composites with UV-stable hardcoat surfaces are consolidating market share in weight-sensitive electric vehicle programs. Webasto and Inalfa Gabriel are qualifying localized optical-grade polymer panels for domestic OEM supply. This material transition is consolidating supplier relationships around integrated glass-polymer hybrid module production rather than discrete component sourcing.
BIS mandatory certification for automotive glazing and AIS-037 structural integrity testing is tightening product validation timelines for sunroof manufacturers. The Bureau of Indian Standards now requires traceable lot documentation for tempered and laminated transparent panels. Premium SUV assemblers in Maharashtra are responding by pre-qualifying dual-source glass suppliers to avoid program delays from single-facility certification bottlenecks.
Dealer network pre-installation of sunroof modules is displacing factory-fit as the dominant channel for mid-size sedan and compact SUV segments. Tamil Nadu and Karnataka aftermarket distributors are building authorized installation capacity with BIS-certified technicians. This channel migration is most visible in sub-15-lakh vehicle price brackets where consumers prioritize post-purchase customization over factory option pricing.
India Automotive Sunroof Market Segmentation
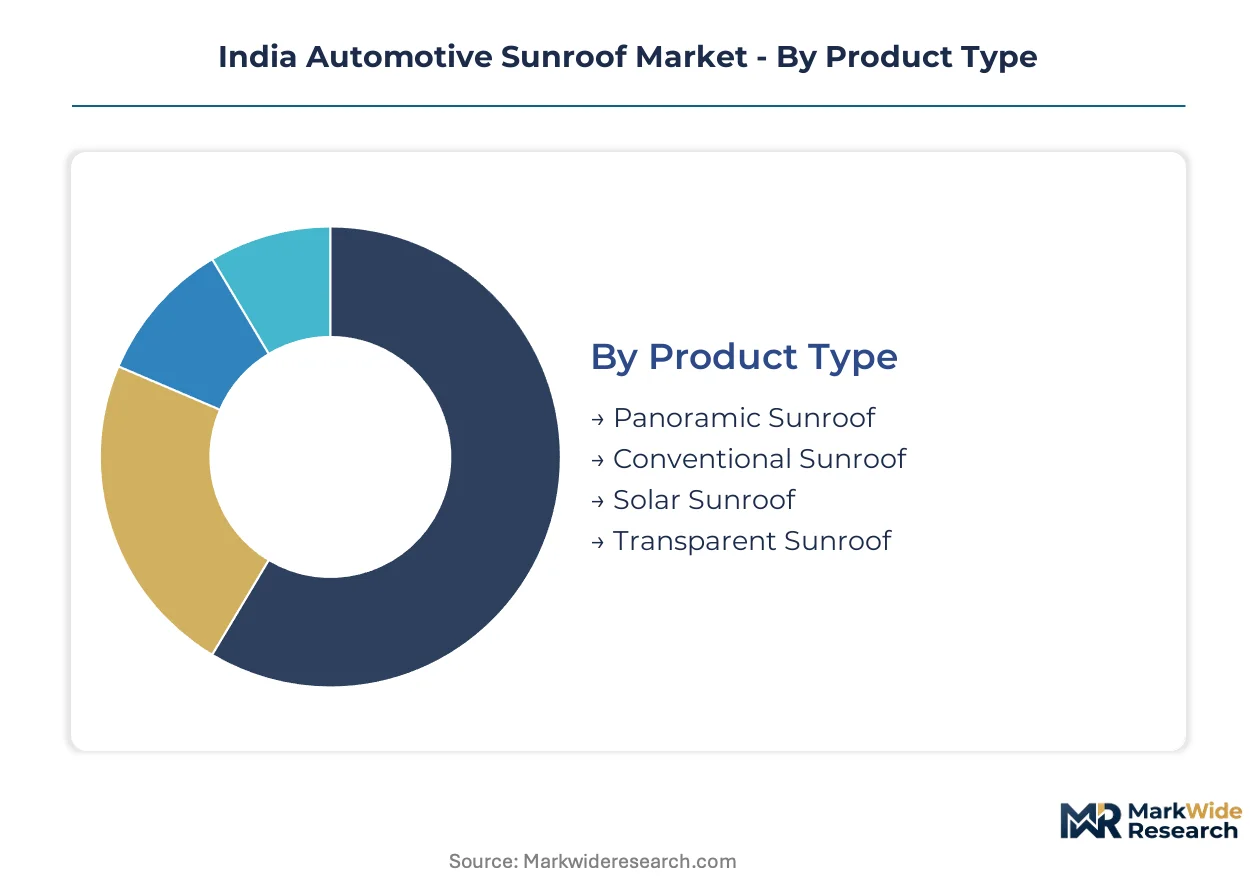
Segmentation in the India Automotive Sunroof Market reveals how capital deployment, regulatory compliance, and consumer preference intersect across distinct technical configurations. Each dimension carries different margin profiles and supplier qualification barriers that shape competitive positioning.
Product Type:
Panoramic configurations demand the heaviest upfront tooling investment for multi-panel glass architecture and precision rail systems, while conventional designs offer faster amortization cycles.
- Panoramic Sunroof:Multi-panel glass architecture spanning front and rear cabin sections requires synchronized rail mechanisms and reinforced roof structure modifications. Maharashtra and Gujarat premium SUV assemblers specify these for vehicles above 4.5-meter wheelbase, where BIS glass certification and AIS-037 roof crush validation create dual qualification hurdles for suppliers.
- Conventional Sunroof:Single-panel tilt-and-slide designs with simpler rail geometries dominate mid-size sedan factory-fit programs. Tamil Nadu and Karnataka dealer networks report rising aftermarket retrofit demand from 2018-2022 vehicle cohorts seeking post-purchase cabin upgrades.
- Solar Sunroof:Photovoltaic-integrated transparent panels with embedded power collection cells serve emerging EV thermal management requirements.
- Transparent Sunroof:Fixed glass roof panels without operable mechanisms offer lowest unit cost for mass-market differentiation.
Panoramic Sunroof absorbs the bulk of installed capacity; Solar Sunroof is expanding most quickly.
Vehicle Type:
Platform engineering constraints and roof structural load specifications create divergent specification intensity across passenger vehicle categories.
- SUV:Higher roof profiles and reinforced body-on-frame or unibody structures accommodate larger aperture dimensions and heavier glass assemblies. Western India OEM programs in Maharashtra prioritize power-operated panoramic configurations for premium positioning above 20-lakh price brackets.
- Sedan:Lower rooflines constrain aperture geometry toward conventional tilt-and-slide or fixed glass options. Compact sedan segments below 15-lakh factory pricing increasingly shift to dealer network pre-installation channels.
- Hatchback:Limited roof real estate restricts sunroof availability to premium variants with structural reinforcement packages.
- Coupe:Aesthetic-driven fixed panoramic glass dominates this low-volume segment with minimal operable mechanism penetration.
SUV commands current specification volume; Sedan aftermarket retrofit activity is climbing fastest.
Material:
Raw material conversion economics and weight-performance tradeoffs segment supplier relationships across domestic and import-dependent supply chains.
- Glass:Tempered and laminated transparent panels with UV-resistant interlayers retain margin concentration despite mass penalties. Indian consumer tactile preference for optical clarity and premium surface finish resists substitution even in EV platforms where range sensitivity favors lighter alternatives.
- Polycarbonate:Multi-layer optical-grade polymer composites with UV-stable hardcoat surfaces consolidate share in weight-sensitive electric vehicle programs. Webasto and Inalfa Gabriel are qualifying localized panels through Gujarat-based conversion capacity to reduce East Asian resin import dependency.
- Acrylic:Lower-cost transparent polymer alternative with reduced optical clarity specifications serves economy aftermarket segments.
- Composite:Hybrid glass-polymer laminates balance weight reduction with surface quality for mid-tier OEM programs.
Glass maintains dominant share in visible cabin surfaces; Polycarbonate is gaining share fastest in EV-focused supply agreements.
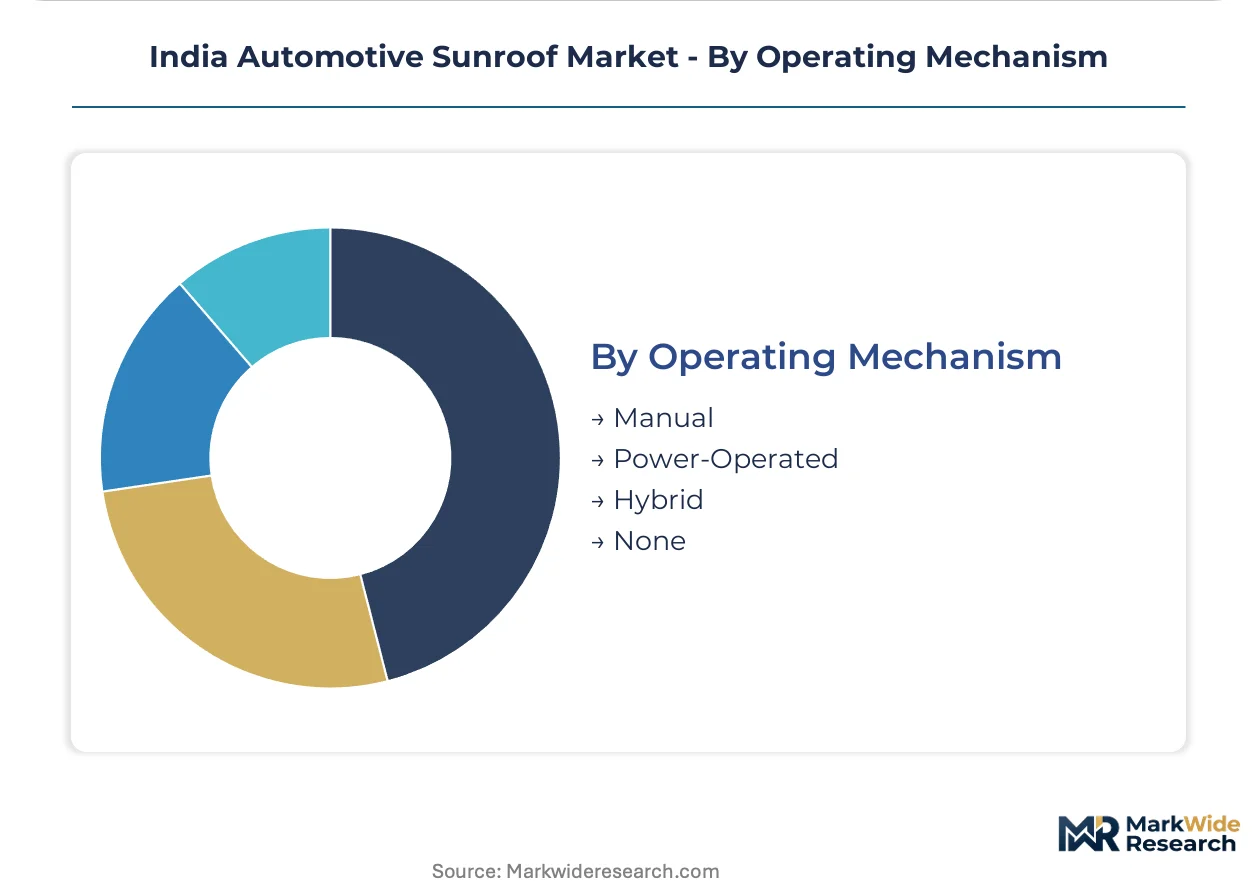
Operating Mechanism:
Actuator system complexity and waterproof sealing requirements create tiered supplier capability thresholds from manual mechanical to intelligent power-operated architectures.
- Power-Operated:One-touch electronic rail actuation with integrated motor control and pinch-protection sensors dominates premium vehicle specifications. Pune and Chennai supplier parks are localizing rail mechanism assembly lines to capture PLI scheme incentives for domestic component qualification.
- Manual:Hand-cranked tilt-and-slide mechanisms with reduced sealing complexity serve economy aftermarket retrofit channels where cost minimization overrides convenience features.
- Hybrid:Dual-mode manual override capability on power-operated systems addresses reliability concerns in high-dust operating environments.
- None:Fixed glass panels without operable functionality eliminate rail mechanism cost entirely for mass-market differentiation.
Power-Operated mechanisms absorb the bulk of OEM program investment; Hybrid configurations are expanding most quickly in reliability-sensitive fleet applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polycarbonate resin conversion capacity in Gujarat anchors western India's sunroof component supply chain. Maharashtra's premium vehicle assembly plants drive specification intensity for multi-panel glass architectures. Tamil Nadu and Karnataka aftermarket channels are expanding certified installation infrastructure for retrofit demand.
Maharashtra
Premium SUV OEM programs above 20-lakh price brackets specify power-operated panoramic configurations with reinforced roof structures. BIS glass certification requirements and AIS-037 roof crush standards filter supplier qualification for transparent panel modules. Pune supplier parks concentrate rail mechanism localization efforts to capture PLI scheme incentives for domestic component assembly.
Gujarat
Optical-grade polycarbonate conversion lines serve weight-sensitive electric vehicle programs seeking mass reduction alternatives to tempered glass. CEA energy-efficiency compliance for manufacturing facilities shapes capital allocation for UV interlayer curing and vacuum deposition processes. Ahmedabad and Vadodara industrial corridors host glass suppliers expanding multi-layer polymer composite capacity for sunroof module feedstock.
Tamil Nadu
Aftermarket retrofit demand from 2018-2022 vehicle cohorts drives authorized installation network expansion for conventional tilt-and-slide systems. Dealer network pre-installation channels displace factory-fit for compact SUV segments below 15-lakh pricing. Chennai supplier parks assemble power-operated rail mechanisms with integrated motor control systems for domestic OEM supply.
Karnataka
Bengaluru metropolitan independent service centers lack certified sunroof retrofit capability, creating whitespace for authorized installation partnerships with BIS-qualified technicians. State-level EV manufacturing incentives redirect vehicle platform priorities toward polycarbonate-weight-reduction specifications. Mysuru and Hubli industrial zones concentrate aftermarket distribution logistics for pan-India module replacement demand.
India Automotive Sunroof Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aftermarket retrofit specialization and localized component assembly. The supplier base consolidates around three strategic archetypes: integrated glass-polymer module manufacturers, rail mechanism specialists, and aftermarket distribution networks. Competitive positioning hinges on BIS certification timelines and PLI scheme qualification for domestic capital subsidies. M&A activity targets rail actuator technology access; capacity expansion concentrates in Pune and Chennai supplier parks.
Among European-origin integrated module suppliers, Webasto Roof Systems Inc. and Inalfa Roof Systems Group exemplify the glass-polymer hybrid manufacturing archetype. Inalfa Gabriel Sunroof Systems Private Limited occupies a position within the localized assembly cost tier, while Minda Corporation Limited anchors aftermarket distribution reach through nationwide dealer network coverage. These three entities represent distinct competitive vectors: technical center engineering support, domestic assembly cost structures, and retrofit channel penetration.
| Leading Market Players |
|---|
| Inalfa Gabriel Sunroof Systems Private Limited |
| Inteva Products |
| Webasto Roof Systems Inc. |
| Gabriel India Limited |
| CIE Automotive |
| Inalfa Roof Systems Group |
| Minda Corporation Limited |
| Yachiyo Industry Co. Ltd |
| Motherson Yachiyo Automotive Systems Co., Ltd. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between BIS-validated OEM modules and uncertified aftermarket alternatives manifests in divergent pricing architectures and supplier network configurations across the Indian sunroof market. OEM-approved panoramic systems command substantial premiums tied to mandatory AIS-037 roof crush testing and traceable glass lot documentation, while dealer-network retrofit channels compete on stripped-down service bundles without factory warranty coverage.
Pricing Analysis
Warranty bundling separates factory-fit programs from aftermarket retrofit channels, with OEM-integrated power-operated panoramic modules carrying comprehensive structural coverage versus dealer-installed conventional systems limited to mechanism-only guarantees. Pricing stratifies across premium, standard, and economy tiers based on glass certification grade and rail mechanism origin, with localized Pune and Chennai assembly capturing PLI scheme subsidies that compress domestic component costs. Cost compression in economy aftermarket segments is intensifying as polycarbonate resin import volatility feeds through to converter margins. Fleet operators and sub-15-lakh compact SUV buyers exhibit highest price sensitivity, while Maharashtra premium SUV purchasers above 20-lakh brackets prioritize one-touch convenience over unit economics.
Supply Chain Analysis
Refurbishment flows for 2018-2022 vehicle cohorts are emerging as a distinct reverse-logistics channel, with Tamil Nadu and Karnataka independent service centers rebuilding rail mechanisms for warranty-expired panoramic modules. Optical-grade polycarbonate resin concentrates in East Asian chemical complexes, while tempered glass feedstock draws from Gujarat-based float lines and European laminated interlayer specialists. Domestic supply rests on micron-tolerance rail actuator imports from Germany and Japan, exposing assemblers to single-source vulnerability for precision-engineered components. Distribution runs through OEM direct-supply agreements for factory-fit programs and Minda Corporation's nationwide dealer network for aftermarket retrofit penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polycarbonate conversion capacity scarcity in Indian petrochemical infrastructure props pricing power for qualified module suppliers, constraining supply elasticity even as Maharashtra and Gujarat OEM demand accelerates.
For Market Incumbents: Anchor BIS certification leadership through accelerated AIS-037 validation pipeline investments at Pune technical centers, while capturing backward integration into Gujarat optical-grade polymer conversion to offset East Asian resin import dependency. Defensive consolidation around rail mechanism localization will blunt emerging entrant cost advantages under revised PLI incentive thresholds. For New Entrants and Emerging Players: Smart glass electrochromic technology offers a technology-first wedge into premium EV thermal management specifications, with Bengaluru metropolitan service centers representing the most penetrable geography for certified installation partnerships. Target southern India aftermarket whitespace through BIS-technician training programs and authorized retrofit channel development. For Investors and Strategic Acquirers: Re-rating potential sits with rail actuator technology specialists given PLI scheme qualification timelines and OEM pre-approval requirements for domestic assembly programs. Long-term viability favors suppliers with captive polycarbonate conversion capacity and dual-source glass qualification relationships. Monitor AIS test protocol revision cycles at government facilities as inflection indicators for validation backlog risk.| Strategic Initiative | Industry Significance |
|---|---|
| Rail Mechanism Localization | Pune and Chennai supplier parks capture PLI scheme capital subsidies for domestic component assembly. |
| Polycarbonate Conversion Capacity Expansion | Gujarat-based glass suppliers reduce East Asian optical-grade resin import dependency for EV programs. |
| BIS Modular Certification Pathway Development | Streamlined type-approval for subassemblies reduces OEM program validation timelines and supplier qualification barriers. |
| Aftermarket Installation Network Authorization | Tamil Nadu and Karnataka certified technician partnerships address 2018-2022 vehicle cohort replacement demand. |
| Smart Glass Technology Licensing | Aerospace-derived electrochromic interlayer integration enables cabin thermal management differentiation for premium platforms. |
Research Methodology
Vehicle production databases, IHS Markit registration data, and BIS certification records formed the secondary backbone, supplemented by primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads across Maharashtra, Gujarat, Tamil Nadu, and Karnataka. Bottom-up triangulation of rail mechanism shipment volumes and top-down validation against OEM sunroof take-rate disclosures ensured cross-verified demand estimation.
Historical trendline analysis of panoramic versus conventional configuration mix, material substitution patterns between glass and polycarbonate, and power-operated mechanism penetration rates informed the projection framework across the analysis window. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from fitted trend extrapolation with PLI scheme incentive phase-in assumptions and AIS-037 regulatory compliance cost curves.
Several conditions sit outside the modeled scope, including unannounced AIS test protocol revisions, state-level EV incentive redirections, and petrochemical capacity investments for optical-grade polymer feedstock. Forecasts reflect documented assumptions regarding localization timelines and certification backlog resolution. Practitioners should monitor CEA energy-efficiency compliance enforcement intensity and DGFT duty structure adjustments for polycarbonate resin imports as early revision signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Torque Vectoring Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Auto Fender Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Global Automotive Structural Sheet Metal Market