
 Argentina Automotive Composites Market | 2026-2036
Argentina Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Automotive Composites Market Outlook
Argentina's adoption of Mercosur energy efficiency protocols for vehicle fleets is consolidating demand around lighter structural materials. Hexcel Corporation leverages its carbon fiber prepreg expertise to serve tier-1 suppliers targeting OEM weight reduction mandates. Mitsubishi Chemical Carbon Fiber and Composites anchors regional supply through its downstream compounding capabilities. SGL Carbon differentiates by controlling carbon fiber precursor quality for high-performance automotive grades.
Argentina automotive composites encompass engineered material systems combining polymer matrices with reinforcing fibers to achieve specific strength-to-weight ratios, typically manufactured through compression molding or injection molding processes at pressures between 7-21 MPa depending on fiber loading and part complexity. These materials primarily enable mass reduction in passenger and commercial vehicles without compromising crashworthiness or durability. Glass fiber dominates volume flows across body panel and interior component applications due to favorable cost-performance positioning against metal alternatives. Carbon fiber concentrates in structural parts where stiffness thresholds justify premium positioning. Hybrid composites are gaining traction among tier-1 suppliers seeking to balance mechanical properties with process economics in electrical enclosure applications.
Argentina's national industrial regulator enforces Mercosur automotive safety and environmental standards that mandate recyclability disclosures for composite components, while the country's standards body oversees material testing protocols for fiber-reinforced plastics used in vehicle construction. These frameworks compel suppliers to maintain certified laboratories and documented supply chain traceability for OEM qualification. Stakeholders must monitor evolving Mercosur emissions harmonization talks and their downstream effects on lightweighting incentives embedded in vehicle certification schemes.
Market Dynamics
Argentina's automotive composites sector pivots on Mercosur lightweighting mandates that force OEMs to shed vehicle mass while maintaining crashworthiness standards, compressing material selection timelines and consolidating supplier relationships around certified fiber systems.
Growth Catalysts
- Mercosur Energy Efficiency Protocols:Regional fleet emission targets accelerate substitution of steel body panels with glass fiber reinforced polymer systems in passenger vehicle platforms assembled across Buenos Aires province.
- Compression Molding Advancement:Automated high-pressure molding cells at 14-21 MPa reduce cycle times for complex geometric parts, enabling tier-1 suppliers to match metal stamping economics at moderate volumes.
- Buenos Aires Supplier Clustering:Proximity of fiber compounders to OEM assembly plants cuts logistics costs and supports just-in-sequence delivery models for interior and exterior component programs.
Market Restraints
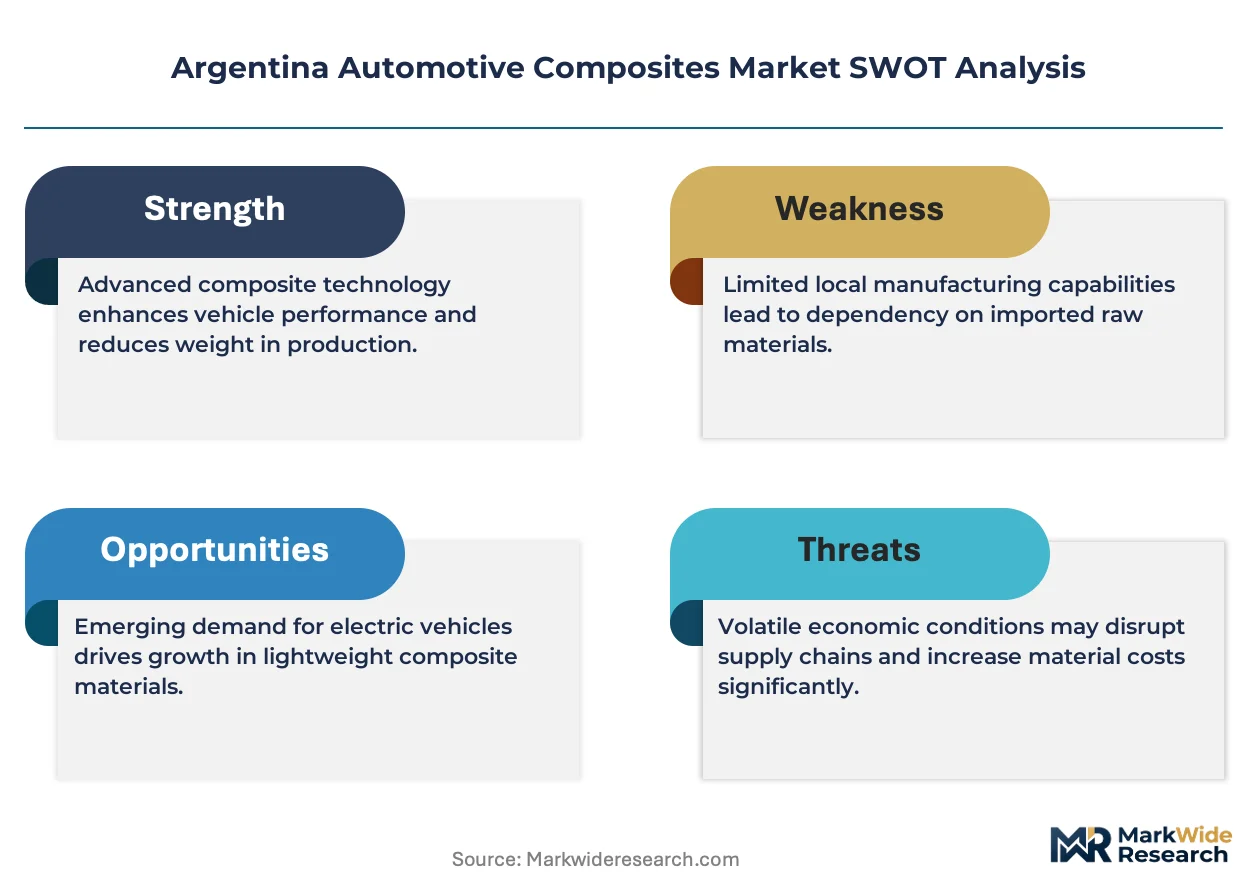
- Carbon Fiber Precursor Volatility:Polyacrylonitrile feedstock prices swing with petroleum derivatives, compressing margins for structural composite grades targeting premium vehicle segments.
- Import Dependency for Epoxy Resins:Argentina's limited domestic epoxy production concentrates supply risk on Brazilian and Asian resin suppliers, exposing molders to currency fluctuation and tariff uncertainty.
- End-of-Life Recycling Mandates:Mercosur recyclability disclosure requirements for thermoset composites lack established industrial-scale recovery infrastructure, adding compliance cost without clear offset mechanisms.
Strategic Opportunities
- Córdoba Industrial Corridor:Underdeveloped automotive supplier density in Argentina's second manufacturing hub offers first-mover positioning for composite stamping and assembly operations serving expanding OEM footprints.
- Hybrid Fiber Systems:Glass-carbon blends in electrical enclosures and battery housings for emerging electric vehicle platforms balance stiffness and cost in applications where full carbon fiber overperforms.
- Mercosur Certification Harmonization:Converging material testing protocols across Brazil, Argentina, Paraguay and Uruguay reduce redundant qualification costs for multi-country vehicle programs.
Industry Challenges
- Composite Design Engineering Talent:Shortage of specialists in fiber orientation simulation and mold flow analysis delays product development cycles for tier-1 suppliers bidding on new OEM platforms.
- ISO 9001/IATF 16949 Certification Timelines:Extended audit and documentation requirements for automotive quality management systems block smaller compounders from qualifying for high-volume production contracts.
- Thermoset-Thermoplastic Integration:Legacy assembly lines optimized for metal joining require capital-intensive retooling to accommodate adhesive bonding and mechanical fastening of composite structural nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Automotive Composites Market |
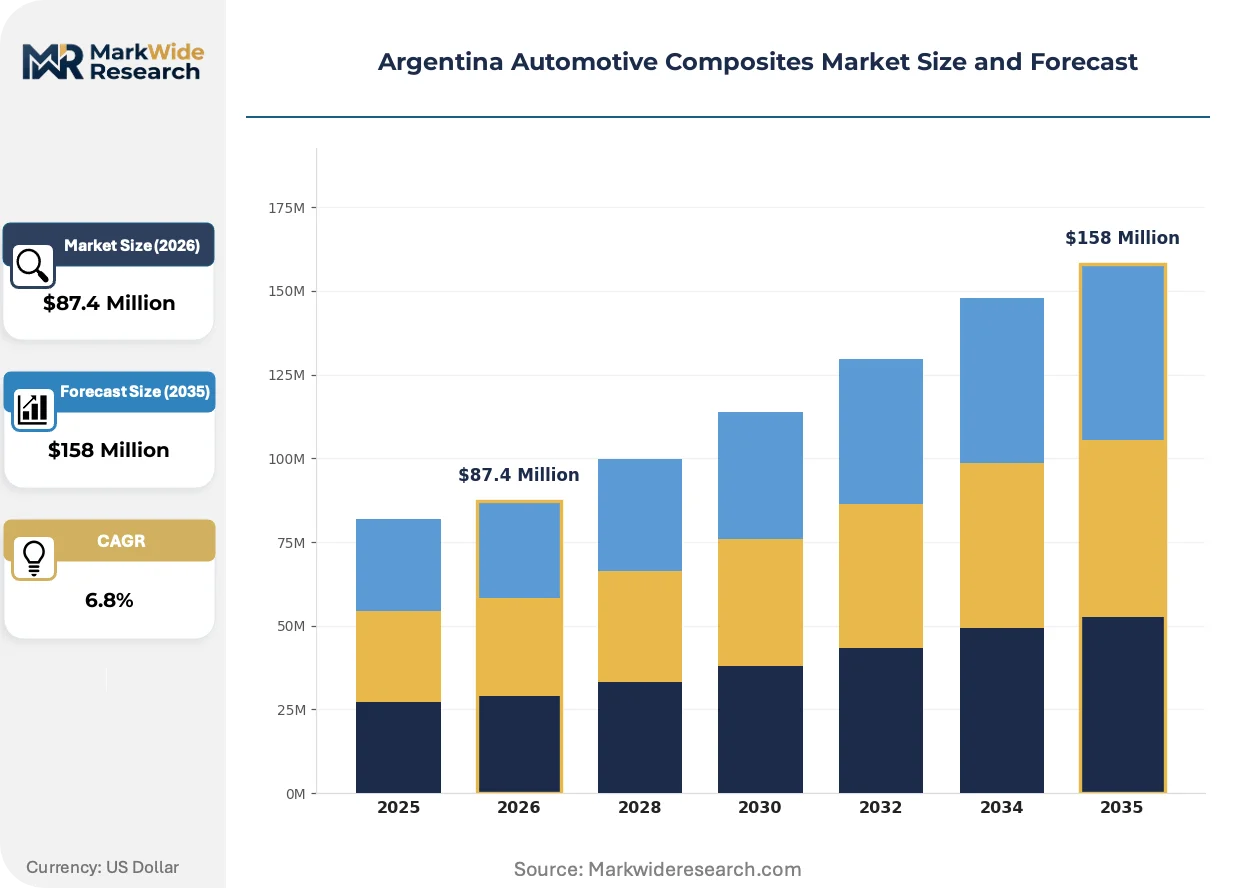
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Hybrid Composites, Natural Fiber Composites End User: Original Equipment Manufacturers, Aftermarket Providers, Tier-1 Suppliers, Dealerships Processing Technology: Injection Molding, Compression Molding, Reinforced Plastics, Thermoforming Application: Body Panels, Interior Components, Structural Parts, Electrical Enclosures |
| Companies Covered | Hexcel Corporation, Mitsubishi Chemical Carbon Fiber and Composites, SGL Carbon, Teijin, Toray Industries, BASF Group, 3B-Fiberglass, Gurit, NSG Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Automotive Composites Market Strategic Shifts
Material science convergence and regulatory compression are redefining how Argentine automotive suppliers engineer, certify, and deliver fiber-reinforced components into OEM assembly sequences.
Hybrid composite formulations are unifying glass and carbon fiber load paths within single molding operations, allowing tier-1 suppliers to tune stiffness gradients across body panel sections. BMW Group and Stellantis assembly programs in Buenos Aires province specify these hybrid systems for hood and decklid inner structures. The technology is unifying previously separate glass-dominated exterior and carbon-dominated structural supply chains into consolidated single-source relationships.
Mercosur's alignment with UN ECE vehicle safety regulations is forcing Argentina's national industrial regulator to adopt fiber-reinforced plastic testing protocols equivalent to European CE-marked material standards. Compounders must now maintain ISO 17025-accredited laboratories for mechanical property validation. High-performance structural grades face the steepest compliance ramps as OEMs demand traceable batch certification for crash-critical applications.
Buyer concentration among Stellantis, Toyota, and Ford Argentina compresses composite supplier negotiation leverage and extends payment terms toward 90-day cycles. Tier-1 molders respond by consolidating secondary operations and pushing volume commitments onto raw material distributors. This procurement compression is most visible in Buenos Aires province where three OEM final assembly plants account for over seventy percent of composite component demand.
Argentina Automotive Composites Market Segmentation
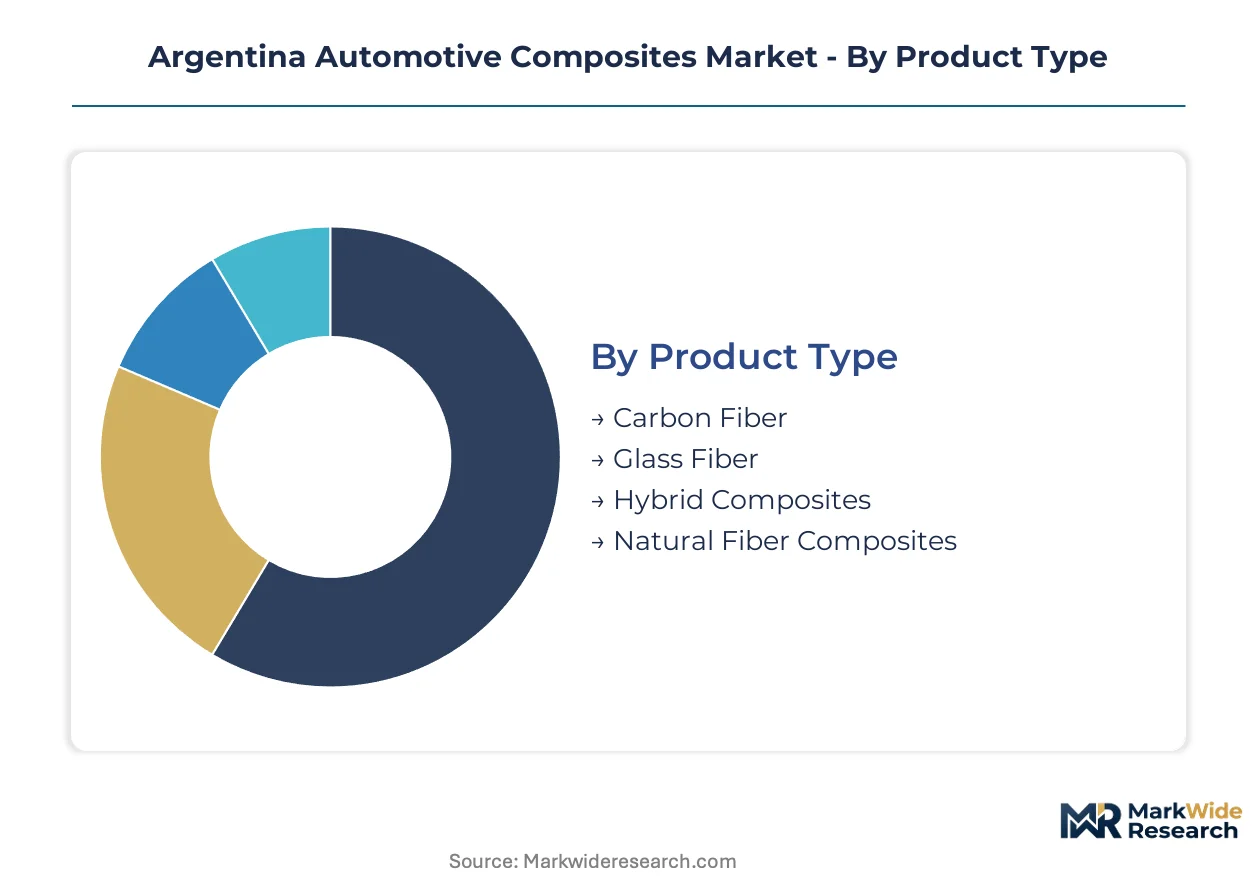
Argentina's automotive composites market fragments across four distinct classification schemes, each governing different procurement workflows and certification burdens for suppliers serving Buenos Aires-based OEM assembly plants. Understanding these segment boundaries clarifies where Mercosur material standards apply most stringently and which processing routes offer path-dependent competitive advantages.
Product Type:
Carbon fiber grades demand IATF 16949 batch traceability and ISO 17025 mechanical validation, while glass fiber systems face lighter documentation loads under Mercosur recyclability disclosure rules. Natural fiber composites trigger additional biodegradability certification through Argentina's national standards body.
- Carbon Fiber:Polyacrylonitrile-based precursors deliver stiffness-to-weight ratios exceeding 150 GPa specific modulus, qualifying for crash-critical structural nodes in Stellantis and Toyota Argentina platforms. Buenos Aires tier-1 suppliers concentrate procurement of aerospace-graded prepregs for hood inner reinforcements where OEM weight mandates bite deepest.
- Glass Fiber:E-glass and S-glass rovings dominate exterior body panel volumes through chopped strand mat and woven fabric formats processed at 7-14 MPa compression pressures. Demand clusters around fender and door skin applications where cost parity with steel stamping drives substitution decisions.
- Hybrid Composites:Glass-carbon fiber blends balance process economics with performance thresholds in electrical enclosure applications for emerging electric vehicle platforms.
- Natural Fiber Composites:Jute and flax fiber reinforcements target interior trim components where Mercosur sustainability scoring creates procurement preference.
Leading the category by volume: Glass Fiber. Growing fastest: Hybrid Composites.
End User:
Procurement authority concentrates differently across this dimension, with OEM direct buying power compressing supplier margins while tier-1 intermediaries aggregate fragmented aftermarket demand.
- Original Equipment Manufacturers:Stellantis, Toyota, and Ford Argentina specify composite grades directly for platform engineering, driving 90-day payment terms and locked volume commitments onto tier-1 molders.
- Tier-1 Suppliers:Multimatic and Magna Argentina operations manage just-in-sequence delivery of body-in-white composite assemblies, bridging OEM specification with raw material compounder execution.
- Aftermarket Providers:Collision repair specialists source glass fiber replacement panels where Argentine import tariffs on finished goods shape sourcing geography toward Brazilian suppliers.
- Dealerships:Authorized service networks access OEM-certified composite components through captive distribution channels maintaining warranty compliance.
Dominant procurement authority: Original Equipment Manufacturers. Expanding most quickly: Tier-1 Suppliers.
Processing Technology:
Capital intensity and cycle time economics sort suppliers across these four process categories, with high-pressure molding cells requiring distinct facility footprints from lower-pressure thermoforming operations.
- Compression Molding:Automated cells operating at 14-21 MPa process sheet molding compound for complex geometric parts, enabling Buenos Aires suppliers to match metal stamping economics at 50,000-unit annual volumes.
- Injection Molding:Long-fiber reinforced thermoplastic systems feed interior component production where dimensional stability and surface finish requirements dominate specification sheets.
- Reinforced Plastics:Hand lay-up and spray-up techniques persist in low-volume commercial vehicle applications where tooling amortization constraints block hard mold investment.
- Thermoforming:Vacuum and pressure forming of glass fiber thermoplastic composites serves secondary structural applications with moderate mechanical load requirements.
Highest installed capacity: Compression Molding. Steepest expansion trajectory: Injection Molding.
Application:
Crashworthiness certification intensity varies sharply across these four use cases, with structural parts facing the steepest Mercosur homologation burdens and interior components qualifying through lighter self-certification pathways.
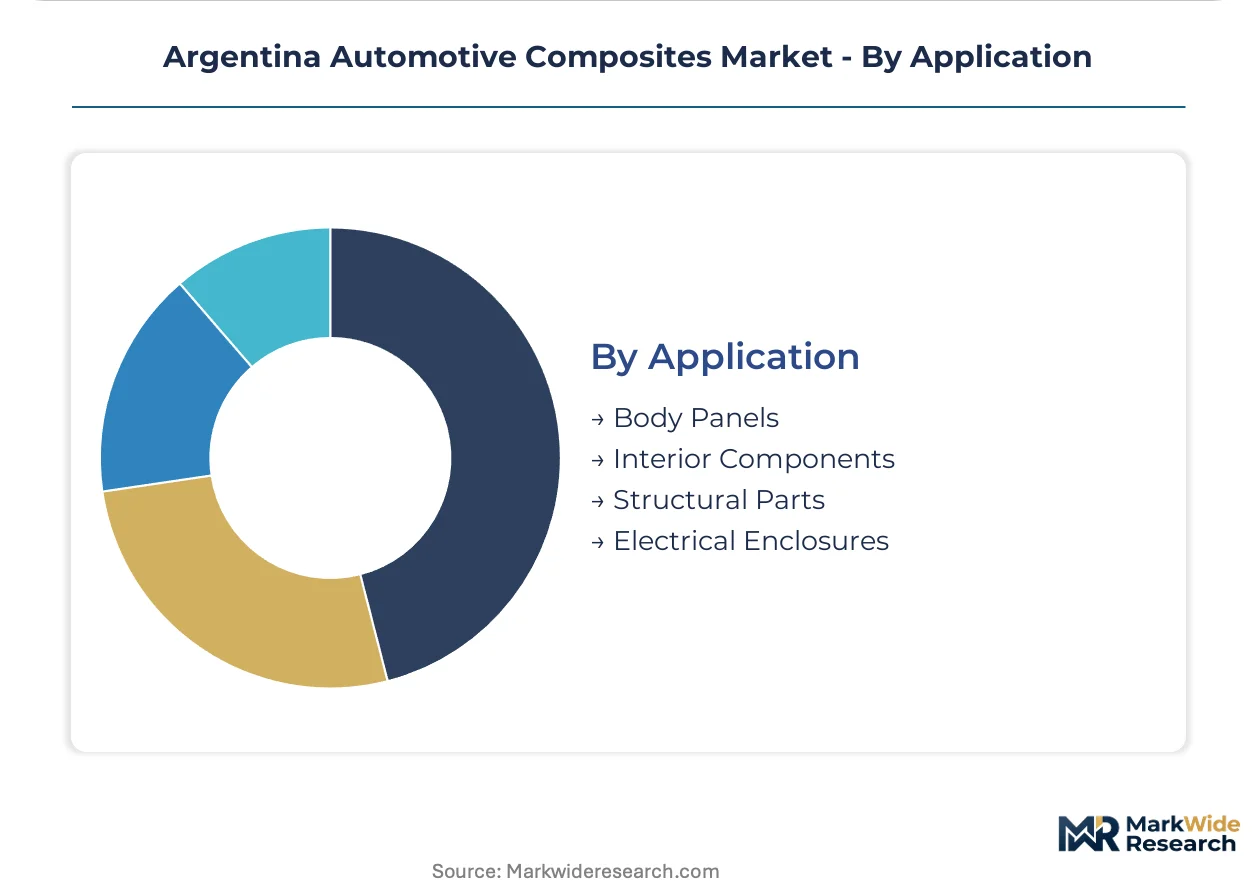
- Body Panels:Hoods, fenders, and decklids in glass fiber sheet molding compound deliver 25-40% mass reduction against steel equivalents, with Stellantis Argentina specifying these materials for platform-wide exterior applications.
- Structural Parts:Carbon fiber reinforced polymer subframes and crash boxes demand full-batch mechanical testing and traceable fiber orientation documentation for UN ECE alignment.
- Interior Components:Door panels, instrument carriers, and seat structures in glass fiber polypropylene prioritize acoustic damping and thermal insulation over structural load-bearing.
- Electrical Enclosures:Battery housings and inverter shields for electric vehicle platforms specify hybrid glass-carbon systems balancing electromagnetic shielding with flame retardancy.
Current revenue concentration: Body Panels. Gaining share fastest: Electrical Enclosures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's automotive composites production concentrates in Buenos Aires province while provincial demand spreads across Córdoba, Santa Fe, and Mendoza manufacturing corridors. This geographic split between supply concentration and dispersed consumption shapes logistics costs and supplier qualification workflows.
Buenos Aires Province
Tier-1 composite molders cluster around Stellantis, Toyota, and Ford final assembly plants in Pacheco and General Pacheco industrial zones. Argentina's national industrial regulator enforces Mercosur automotive safety standards requiring ISO 17025-accredited laboratories for mechanical property validation. Just-in-sequence delivery models dominate, with fiber compounders operating within 50 kilometers of OEM stamping facilities.
Córdoba
Argentina's second manufacturing hub hosts expanding automotive supplier operations targeting underpenetrated composite component demand. The provincial government maintains industrial promotion programs for automotive parts manufacturers establishing operations in the Córdoba Industrial Corridor. Renault-Nissan supplier parks in Santa Isabel drive glass fiber sheet molding compound consumption for exterior body panels.
Santa Fe
Rosario's port infrastructure enables epoxy resin and carbon fiber precursor imports from Brazilian and Asian suppliers. The city's customs zone offers temporary admission regimes reducing working capital requirements for composite raw material distributors. Regional molders serve commercial vehicle manufacturers operating along the Paraná River logistics corridor.
Mendoza
Specialized composite repair facilities support mining fleet maintenance, creating aftermarket demand distinct from OEM supply chains. Provincial environmental regulations mandate recyclability disclosures for thermoset composite waste streams. Mendoza's isolation from Buenos Aires supplier networks forces longer procurement lead times for certified automotive grades.
Argentina Automotive Composites Market Competitive Environment
The competitive structure tilts toward multinational material suppliers with established Mercosur certification pathways. Tier-1 molders occupy intermediate positions between raw fiber producers and OEM assembly plants, compressing margins through volume commitments and extended payment terms. Three archetypes dominate: aerospace-grade carbon fiber specialists, glass fiber compounders with compression molding expertise, and hybrid system integrators bridging stiffness and cost requirements. Consolidation pressure manifests through supplier qualification consolidation around certified laboratories and locked volume agreements.
Among carbon fiber specialists, Hexcel Corporation, Mitsubishi Chemical Carbon Fiber and Composites, and SGL Carbon occupy positions anchoring high-performance structural grades for crash-critical applications. These companies exemplify the premium-tier archetype where batch traceability and precursor quality control justify positioning above commodity glass fiber alternatives. Their presence in Buenos Aires supplier networks reflects OEM weight reduction mandates pulling aerospace-graded materials into automotive platforms.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Mitsubishi Chemical Carbon Fiber and Composites |
| SGL Carbon |
| Teijin |
| Toray Industries |
| BASF Group |
| 3B-Fiberglass |
| Gurit |
| NSG Group |
| Others |
Value Chain & Pricing Dynamics
Polyacrylonitrile feedstock price volatility cascades through Argentina's automotive composites supply chain, compressing margins for carbon fiber structural grades while glass fiber compounders absorb resin cost swings through volume-locked contracts with Buenos Aires tier-1 suppliers.
Pricing Analysis
Crashworthiness certification value anchors pricing tiers across Argentina's automotive composites market, with IATF 16949-accredited batches commanding premiums over standard glass fiber grades. Three-tier pricing structure across premium aerospace-graded carbon fiber, standard automotive structural grades, and economy glass fiber exterior panels reflects certification burden and fiber precursor quality. Pricing pressure stems from OEM consolidation around Stellantis, Toyota, and Ford Argentina extending payment terms toward 90-day cycles. Aftermarket collision repair specialists exhibit highest price sensitivity, while OEM platform engineers prioritize batch traceability over unit cost.
Supply Chain Analysis
Epoxy resin supply rests on Brazilian and Asian specialty chemical producers, exposing Argentine molders to currency fluctuation and import tariff uncertainty. Raw material flows draw from Japanese carbon fiber precursor manufacturers, Chinese glass fiber roving suppliers, and German compounding equipment providers. Single-source vulnerability concentrates in aerospace-graded prepreg channels where Hexcel Corporation and Mitsubishi Chemical Carbon Fiber and Composites control qualified supply. Distribution runs through Buenos Aires-based compounders operating just-in-sequence delivery models within 50 kilometers of OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's automotive composites sector sits in a technology-transition phase as hybrid glass-carbon fiber systems displace legacy pure-glass formulations in electrical enclosure and battery housing applications.
For Market Incumbents: Anchor defensive positioning through backward integration into carbon fiber precursor compounding and ISO 17025 laboratory accreditation investments. Threat from emerging hybrid composite specialists demands locked volume agreements with Stellantis and Toyota Argentina platform engineers. Certification control serves as the priority lever for margin defense against price-aggressive glass fiber compounders.
For New Entrants and Emerging Players: Begin with Córdoba Industrial Corridor manufacturing footprint targeting underpenetrated exterior body panel demand from Renault-Nissan supplier parks. White-space opportunity concentrates in hybrid composite electrical enclosures for emerging electric vehicle platforms where incumbent certification timelines create entry windows. Go-to-market angle should emphasize Mercosur harmonization readiness and compressed qualification pathways.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap glass fiber compounders with compression molding expertise and existing IATF 16949 certification in Buenos Aires province. Long-term viability hinges on electric vehicle platform penetration rates and hybrid composite adoption curves. Signal to watch is Mercosur emissions harmonization timeline and downstream lightweighting incentive embedding in vehicle certification schemes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Compounding | Captive polyacrylonitrile supply insulates margins from petroleum derivative volatility. |
| ISO 17025 Laboratory Accreditation | UN ECE alignment mandates traceable batch certification for crash-critical structural grades. |
| Córdoba Industrial Corridor Expansion | First-mover positioning captures Renault-Nissan exterior panel demand outside Buenos Aires cluster. |
| Hybrid Composite Formulation Development | Glass-carbon blends balance electromagnetic shielding with flame retardancy for battery housings. |
| Mercosur Certification Harmonization Investment | Converging Brazil-Argentina-Paraguay-Uruguay protocols reduce redundant qualification costs. |
Study Parameters
Multi-period observation of polyacrylonitrile feedstock indices, compression molding capacity utilization, and OEM platform engineering specifications anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from vehicle production databases, Mercosur regulatory filings, customs trade records, and IHS Markit registration data. Bottom-up fiber volume estimates triangulated against top-down OEM content-per-vehicle assumptions.
Segment-weighting across product type, processing technology, and application dimensions shaped the analytical framework, with carbon fiber, glass fiber, hybrid composites, and natural fiber categories receiving distinct growth trajectory assumptions. Vehicle class, propulsion architecture, and content per vehicle inputs informed projection modeling across the analysis window. CAGR derivation incorporated fiber substitution elasticity against steel and aluminum, as well as Mercosur energy efficiency protocol compliance deadlines.
Underlying measurement precision varies by segment; carbon fiber structural grades carry tighter precision than natural fiber interior components due to established batch traceability documentation. Forecasts reflect assumptions regarding OEM weight reduction mandate enforcement, epoxy resin import tariff stability, and hybrid composite qualification timelines. Mercosur emissions harmonization progress, electric vehicle platform rollout schedules, and end-of-life recycling infrastructure development warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Metal Timing Chain Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Resonator Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
Automotive Retarders Market
Automotive Components
Automotive Emblem Market
Automotive Components
France Automotive Market
Automotive Components
Automotive Catalyst Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Automotive Active Suspension System Market