
 3D Printing Technology in Pharmaceutical Market | 2026-2036
3D Printing Technology in Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Technology in Pharmaceutical Market Insights
FDA guidance on additive manufacturing is consolidating the cost-of-entry calculus for pharmaceutical 3D printing, forcing newcomers to invest in validation infrastructure before commercialization. Aprecia Pharmaceuticals LLC leverages its binder-jetting expertise to dominate the production of levetiracetam formulations. Merck KGaA sustains R&D intensity across powder-bed fusion platforms for clinical trial materials. FabRx Ltd specializes in personalized polypill architectures that combine multiple APIs into single dosage forms.
3D printing in pharmaceuticals refers to layer-by-layer additive fabrication of drug products with precise control over geometry, porosity, and release kinetics, typically achieving layer resolutions of 50–300 micrometers using pharmaceutically approved excipients and active pharmaceutical ingredients. The primary purpose is to manufacture personalized medicines with tailored dosing, complex drug-release profiles, and geometries impossible through conventional tableting or capsule-filling. Powder-based systems lead current installed capacity due to their compatibility with established pharmaceutical excipient libraries, while liquid-based platforms represent the fastest-growing segment as inkjet and stereolithography methods enable higher-resolution deposition for specialized implants. Oncology applications command significant margin pools because tumor-targeted therapies demand precise dose personalization that 3D printing uniquely delivers.
The FDA, EMA, and WHO collectively shape this market through divergent validation requirements for additive-manufactured pharmaceuticals, with the FDA's 2017 technical guidance on 3D-printed medical devices extending into drug-product oversight and the EMA's quality working parties scrutinizing batch-to-batch consistency of printed dosage forms. These frameworks create compliance moats that favor established players with dedicated regulatory affairs teams and documented quality management systems. Stakeholders must monitor evolving pharmacopeial monographs for printed drug products and decide whether to build in-house GMP-grade 3D printing capacity or partner with specialized contract manufacturers.
Market Dynamics
FDA validation protocols for additive-manufactured pharmaceuticals are compressing commercialization timelines for new entrants while consolidating advantage among established players with documented quality management systems. The structural force reshaping competitive positioning centers on regulatory compliance infrastructure as the primary barrier to market participation.
Growth Catalysts
- Oncology dose personalization:Tumor-targeted therapies require precise dosing that 3D printing uniquely delivers, driving hospital network investment in patient-specific fabrication capabilities.
- EMA quality working party scrutiny:Batch-to-batch consistency standards for printed dosage forms are elevating manufacturing rigor, creating compliance moats that favor sophisticated operators.
- Polypill architectures:Inkjet deposition methods enable single-tablet combinations of multiple APIs, addressing polypharmacy burdens in aging populations.
Market Restraints
- GMP-grade equipment costs:Powder-bed fusion and binder-jetting systems require specialized pharmaceutical-grade hardware with extended validation cycles.
- Excipient library limitations:Current powder-based platforms remain constrained to established excipient compatibilities, limiting formulation innovation.
- WHO pharmacopeial gaps:Absence of harmonized monographs for printed drug products creates regulatory uncertainty across export markets.
Strategic Opportunities
- Pediatric dosing markets:Germany and France present underpenetrated demand for weight-adjusted dosage forms in academic medical centers.
- Clinical trial materials:Powder-bed fusion platforms enable rapid small-batch production for adaptive trial designs, compressing development timelines.
- Dual carbon alignment:China's NMPA green manufacturing incentives favor additive processes with reduced material waste versus conventional tableting.
Industry Challenges
- Formulation scientist scarcity:The intersection of pharmaceutics and additive manufacturing expertise remains concentrated in a handful of academic programs.
- Legacy MES integration:Printed dosage form production requires reconfiguration of existing manufacturing execution systems for batch record traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Technology in Pharmaceutical Market |
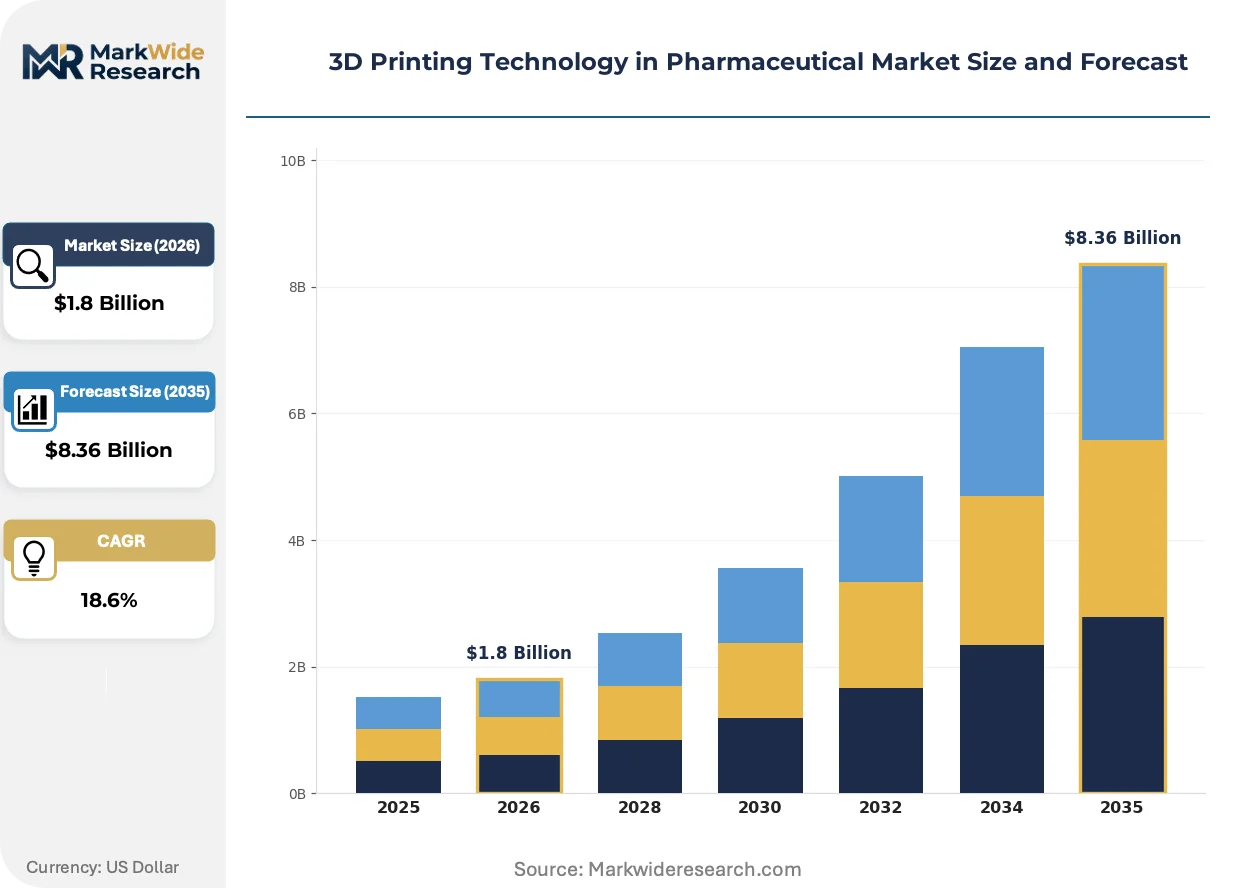
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament-based, Powder-based, Liquid-based, Binder jetting Therapy Area: Oncology, Cardiology, Pediatrics, Neurology Form: Tablets, Capsules, Injections, Implants Delivery Mode: Oral, Subcutaneous, Intravenous, Transdermal |
| Companies Covered | Cycle Pharmaceuticals, Hewlett Packard Caribe, Aprecia Pharmaceuticals LLC, Merck KGaA, Teva Pharmaceuticals, FabRx Ltd, Osmotica Pharmaceuticals, Affinity Therapeutics, Triastek Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Technology in Pharmaceutical Market Trends and Innovations
Layer-resolution capabilities and regulatory harmonization efforts are converging to reshape how pharmaceutical manufacturers approach personalized medicine production. The market is witnessing active transformation across three distinct vectors.
Continuous liquid interface production is unifying high-resolution deposition with scalable throughput for specialized implant geometries. Academic medical centers in Switzerland and the Netherlands are piloting these systems for orodispersible films. The technology is unifying previously separate formulation and manufacturing workflows into single-step production.
REACH substance restrictions on certain photoinitiators are forcing reformulation of stereolithography resins used in pharmaceutical applications. European contract manufacturers are accelerating substitution programs ahead of compliance deadlines. Oncology implant producers face the steepest transition costs due to validated release kinetics tied to existing chemistries.
Hospital procurement committees are consolidating vendor relationships around full-service platform providers rather than equipment-only suppliers. United States academic medical centers now require embedded regulatory affairs support and validation documentation packages. This concentration is most visible in the Northeast corridor, where major health systems are standardizing on single-platform deployments.
3D Printing Technology in Pharmaceutical Market Segmentation
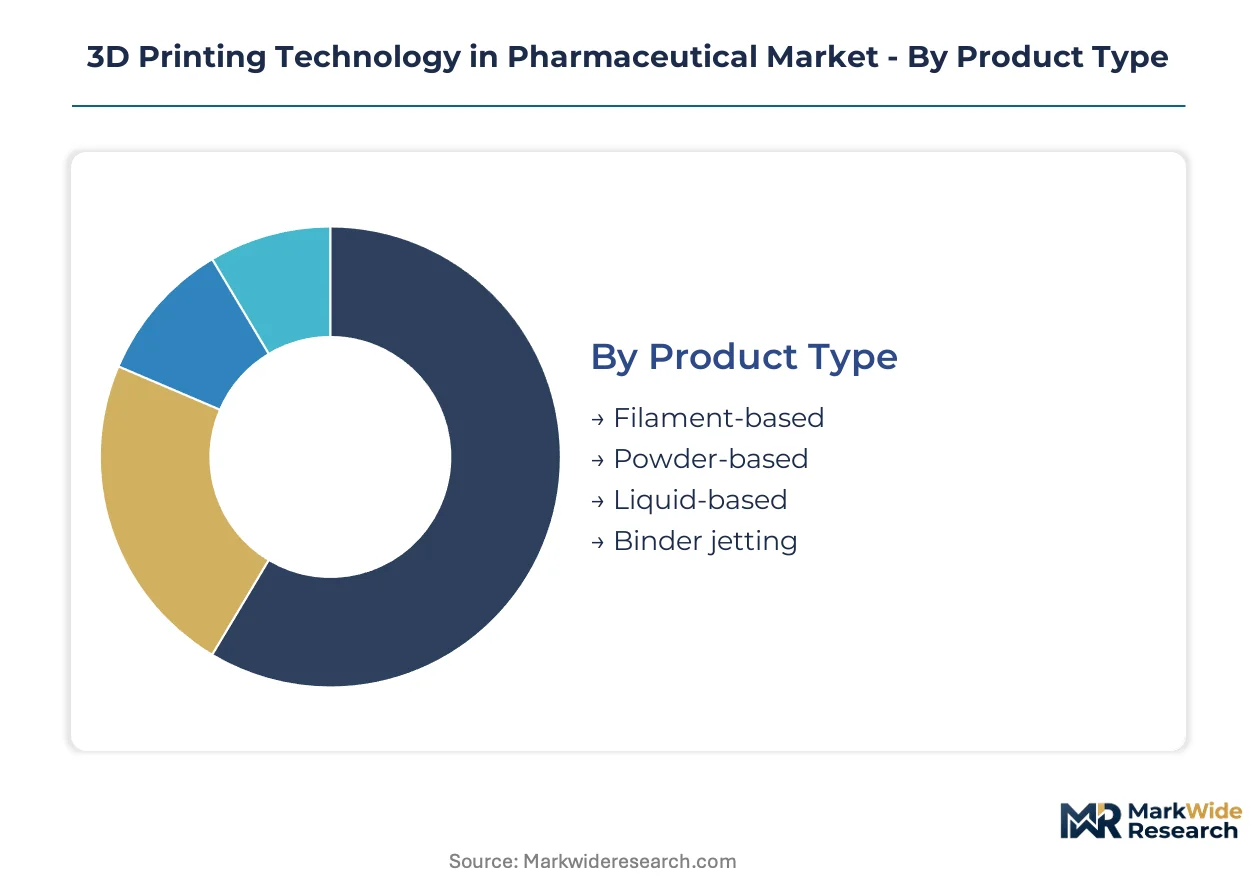
Segmentation in pharmaceutical 3D printing reveals how technology choices cascade through regulatory pathways, therapeutic applications, and patient administration requirements. Each dimension captures distinct buyer priorities that reshape vendor competitive strategy.
Product Type:
Technology selection separates buyers by validation burden and excipient flexibility.
- Powder-based:Systems deposit pharmaceutical-grade powders in precise layers using selective laser sintering or binder activation. United States contract manufacturers concentrate demand here due to compatibility with established excipient libraries and FDA-validated workflows for immediate-release tablets.
- Liquid-based:Inkjet and stereolithography platforms achieve 50-100 micrometer resolution for complex implant geometries. Academic medical centers in Switzerland and the Netherlands are expanding installed capacity for orodispersible films and personalized polypill architectures.
- Filament-based:Fused deposition modeling extrudes drug-loaded thermoplastic filaments for prototype dosing studies. Research institutions leverage lower capital costs for early-stage formulation screening.
- Binder jetting:Aprecia Pharmaceuticals dominates this segment with water-based binding agents for high-throughput production of porous, rapidly disintegrating tablets.
Volume sits with powder-based systems; growth tilts toward liquid-based platforms.
Therapy Area:
Therapeutic focus determines reimbursement pathways and dose personalization intensity.
- Oncology:Tumor-targeted therapies demand precise milligram-level dose adjustments based on patient pharmacokinetics. Major hospital networks in the United States are building dedicated fabrication capacity for patient-specific dosing regimens.
- Pediatrics:Weight-adjusted formulations require flexible manufacturing for non-standard strengths. Germany and France present underpenetrated demand in academic medical centers seeking alternatives to compounding pharmacies.
- Neurology:Controlled-release profiles for antiepileptic drugs leverage 3D-printed geometries for pulsatile delivery. Levetiracetam formulations exemplify validated commercial applications.
- Cardiology:Polypill combinations address polypharmacy in aging populations through single-tablet delivery of multiple cardiovascular APIs.
Revenue concentrates in oncology; pediatric applications are expanding most quickly.
Form:
Dosage form selection constrains geometry complexity and release kinetics engineering.
- Tablets:Layer-by-layer fabrication enables internal lattice structures for tunable dissolution profiles. Binder-jetting and powder-bed fusion dominate current commercial production.
- Implants:Stereolithography produces patient-specific geometries for localized drug delivery with zero-order release kinetics. REACH substance restrictions on photoinitiators are forcing resin reformulation programs.
- Capsules:Shell-based delivery systems accommodate moisture-sensitive APIs through protective encapsulation of printed cores.
- Injections:Biodegradable microneedle arrays and implantable depots represent emerging applications with specialized sterility requirements.
Tablets anchor current volume; implants follow the steepest expansion trajectory.
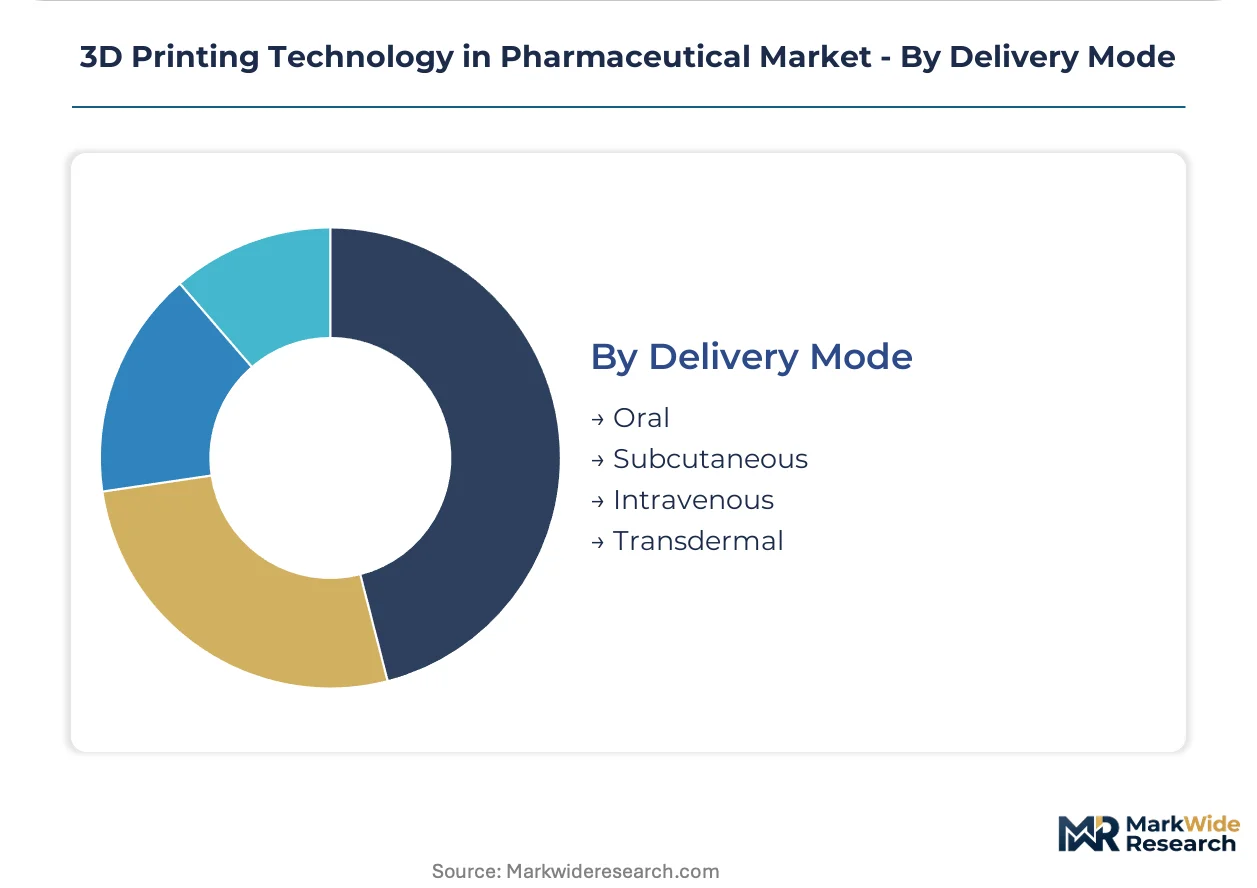
Delivery Mode:
Administration route shapes sterility requirements and manufacturing scale economics.
- Oral:Direct compression alternatives dominate installed capacity with established bioequivalence pathways and patient acceptance.
- Transdermal:Microneedle patches and topical films leverage high-resolution deposition for precise API distribution across skin contact surfaces.
- Subcutaneous:Biodegradable implantable depots require aseptic processing capabilities that constrain supplier qualification.
- Intravenous:Parenteral applications remain limited by sterility assurance and particulate matter validation challenges for layered fabrication.
Oral delivery commands manufacturing volume; transdermal modalities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special pharmaceutical manufacturing zones in the United States and Switzerland concentrate 3D printing investment through targeted tax incentives and accelerated regulatory pathways. Academic medical centers in Boston and Basel anchor demand for patient-specific fabrication capabilities. National regulators in Germany, Japan, and China are constructing divergent compliance frameworks that reshape cross-border equipment procurement.
United States
FDA validation protocols and hospital network consolidation drive demand for GMP-grade powder-bed systems. The 21st Century Cures Act provisions accelerate breakthrough therapy designations for personalized dosage forms. Massachusetts General Hospital and Mayo Clinic anchor dedicated fabrication facilities in Greater Boston and Rochester.
Germany
Pediatric weight-adjusted formulations and academic medical center procurement create underpenetrated demand for flexible manufacturing. EMA quality working party scrutiny elevates batch-to-batch consistency standards for printed dosage forms. Heidelberg University Hospital and Charité Berlin lead pilot programs for patient-specific polypill production.
Switzerland
Swissmedic's progressive stance on additive manufacturing attracts contract manufacturers seeking regulatory clarity for complex implant geometries. REACH substance restrictions force reformulation of stereolithography resins ahead of compliance deadlines. Basel's pharmaceutical cluster concentrates continuous liquid interface production pilots for orodispersible films.
China
NMPA green manufacturing incentives favor additive processes with reduced material waste versus conventional tableting. Dual carbon alignment policies accelerate hospital procurement of energy-efficient fabrication systems. Shanghai and Suzhou pharmaceutical parks host domestic equipment manufacturers building GMP-compatible powder-bed platforms.
Japan
PMDA consultation programs for innovative manufacturing technologies reduce validation timelines for 3D-printed clinical trial materials. METI funding for smart factory initiatives supports integration of additive systems into existing pharmaceutical production lines. Kansai region universities partner with Osaka-based manufacturers on stereolithography research for controlled-release implants.
3D Printing Technology in Pharmaceutical Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology platforms and therapeutic applications. The vendor base separates into three tiers: multinational pharmaceutical companies with captive R&D programs, dedicated 3D printing equipment manufacturers, and contract development organizations offering fabrication-as-a-service. Strategic moves concentrate on regulatory affairs capacity building and hospital network partnerships rather than price competition.
Within the pharmaceutical pure-play tier, Aprecia Pharmaceuticals LLC and FabRx Ltd exemplify divergent specialization strategies—binder-jetting expertise versus personalized polypill architectures. Merck KGaA occupies a position bridging diversified conglomerate and dedicated additive manufacturing investor through sustained R&D intensity across powder-bed fusion platforms.
| Leading Market Players |
|---|
| Cycle Pharmaceuticals |
| Hewlett Packard Caribe |
| Aprecia Pharmaceuticals LLC |
| Merck KGaA |
| Teva Pharmaceuticals |
| FabRx Ltd |
| Osmotica Pharmaceuticals |
| Affinity Therapeutics |
| Triastek Inc |
| Others |
Pricing and Supply Chain Analysis
Academic medical center procurement committees, increasingly consolidated into multi-hospital networks, exercise collective bargaining power over equipment vendors while demanding embedded regulatory affairs support that reshapes supplier cost structures and margin allocation across GMP-grade system tiers.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent validation timelines from standard procurement cycles, with academic medical centers paying premiums for expedited FDA documentation packages while contract manufacturers capture volume discounts through multi-year platform commitments. Price differentiation hinges on GMP certification tier and after-sales service bundling, with FDA-validated workflows commanding substantial premiums over research-grade equivalents. Pricing pressure stems from hospital procurement consolidation in the United States Northeast corridor, where standardization on single-platform deployments compresses vendor margins. Contract manufacturers exhibit highest price sensitivity due to capital intensity of powder-bed fusion installations, while research institutions prioritize customization flexibility over unit economics.
Supply Chain Analysis
Domestic-content mandates in China's NMPA green manufacturing incentives and the United States Inflation Reduction Act localization provisions are reshaping sourcing patterns for pharmaceutical-grade hardware components and excipient feedstocks. Supply concentration centers on Germany for precision laser systems, Japan for high-resolution deposition heads, and the United States for FDA-validated quality management software. Raw material dependencies include pharmaceutical-grade titanium powders, photopolymer resins, and tailored excipient blends. Single-source vulnerability runs through specialized optical component suppliers for powder-bed fusion platforms. Distribution runs through direct vendor relationships with hospital procurement committees rather than traditional pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where FDA validation protocol complexity forces weaker entrants without documented quality management systems toward acquisition or exit.
For Market Incumbents: Deploy regulatory affairs capacity expansion to capture hospital network standardization mandates, particularly in the United States Northeast corridor where procurement committees now require embedded validation documentation. Acquire specialized contract manufacturers in Germany and Switzerland to preempt EMA quality working party compliance moats. Counter emerging liquid-based platform specialists by accelerating binder-jetting throughput improvements for immediate-release tablet volumes.
For New Entrants and Emerging Players: Launch via fabrication-as-a-service models targeting pediatric weight-adjusted formulations in underpenetrated German and French academic medical centers. Exploit white space in clinical trial materials production for adaptive oncology study designs, where rapid small-batch capabilities command premium positioning. Establish initial credibility through Swissmedic consultation pathways for complex implant geometries before scaling toward FDA submissions.
For Investors and Strategic Acquirers: Distressed-cycle entries favor contract development organizations with existing GMP-grade powder-bed capacity in Switzerland and the Netherlands, where regulatory clarity and REACH reformulation transition costs strain undercapitalized operators. Long-term viability over the next decade hinges on hospital network partnership density rather than equipment innovation alone. Monitor FDA draft guidance publication timing as the critical inflection signal for valuation step-ups in regulatory affairs-heavy targets.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Validation Documentation Investment | Embedded regulatory packages now required by United States academic medical center procurement committees. |
| Hospital Network Partnership Consolidation | Single-platform standardization across Northeast corridor health systems reduces vendor switching costs. |
| REACH-Compliant Resin Reformulation | European contract manufacturers face transition costs for stereolithography photoinitiator substitutions. |
| Pediatric Formulation Capability Buildout | German and French academic centers seek alternatives to compounding pharmacy dependence. |
| Continuous Liquid Interface Production Piloting | Swiss and Dutch medical centers advance orodispersible film manufacturing integration. |
Research Methodology
Multi-period observation of FDA guidance evolution, EMA quality working party deliberations, and hospital procurement committee vendor consolidation anchored the trend analysis, supplemented by interviews with regulatory affairs directors at contract manufacturers, formulation scientists at academic medical centers, GMP equipment procurement leads, and pharmaceutical quality assurance executives. Secondary validation drew from FDA technical guidance documents, EMA quality working party position papers, Swissmedic consultation outcome summaries, and hospital capital expenditure disclosures. Bottom-up equipment installation tracking and top-down pharmaceutical manufacturing investment flow analysis were triangulated against patient-specific dosage form adoption metrics.
Input-output matrices modeled technology platform adoption, therapy area penetration, and regional regulatory cluster dynamics across the projection horizon. Segmentation dimensions included product type, therapeutic application, dosage form geometry, and delivery mode complexity. CAGRs were derived from equipment shipment trajectories, hospital facility buildout announcements, and validated commercial product launch timelines. Forecast inputs incorporated binder-jetting throughput improvements and liquid-based platform resolution advances as technology-specific variables.
Regulatory guidance publication delays, excipient library expansion failures, and hospital procurement budget freezes are the dominant revision risks for pharmaceutical 3D printing market trajectories. Forecasts reflect assumptions regarding FDA draft guidance finalization and EMA harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Global 4D Printing in Healthcare Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
3D Printer Market
3D Printing Technology
Global 3D Printing in Medical Applications Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Global 3D Pens Market