
 PEEK Filament Market | 2026-2036
PEEK Filament Market Size, Share, and Industry Trends Forecast 2026-2036
PEEK Filament Market Analytics
Medical device OEMs is unwinding the historical dominance of industrial prototyping shops as the primary buyer archetype in PEEK filament consumption. Ensinger leverages its European compounding infrastructure to supply certified medical-grade feedstock with batch-level documentation. Victrex anchors the high-purity segment through its Invibio biomaterials division, which dominates implantable-grade PEEK supply chains. 3DXTech competes on price-accessible industrial grades, serving automotive and general engineering customers with broader tolerance specifications.
PEEK filament consists of extruded polyetheretherketone polymer with melt temperatures near 343°C, delivering chemical resistance and mechanical strength for load-bearing printed parts in continuous-use environments above 150°C. Medical Devices and Aerospace applications command the deepest margin pools due to certification burdens and lot-traceability requirements that filter out commodity suppliers. Fused Deposition Modeling occupies the largest installed base for PEEK processing, though Selective Laser Sintering captures premium aerospace work requiring isotropic mechanical properties without layer adhesion weaknesses.
FDA's 510(k) clearance pathway for implantable PEEK devices and the EU MDR's reinforced biocompatibility testing under EMA oversight are elevating entry barriers for uncertified filament producers. REACH compliance through ECHA registration now extends to PEEK oligomer content, forcing reformulation of legacy extrusion grades. Stakeholders must monitor how FDA and EMA convergence on polymer degradation testing protocols reshapes supplier qualification timelines and capital deployment decisions.
Market Dynamics
Medical-grade certification requirements are compressing supplier margins while concentrating volume among vertically integrated compounders capable of batch-level traceability documentation.
Growth Catalysts
- EU MDR biocompatibility mandates:Implantable device manufacturers must source certified feedstock with full polymer chain documentation, disqualifying uncertified extruders and consolidating demand around qualified suppliers.
- Aerospace lightweighting protocols:FAA airworthiness directives for fuel efficiency are accelerating fused deposition modeling adoption for non-critical structural brackets and ducting components in narrow-body retrofit programs.
- Frankfurt-Stuttgart industrial clustering:Proximity between automotive engineering centers and medical device OEMs creates shared service infrastructure for high-temperature polymer processing expertise.
Market Restraints
- Feedstock concentration:Virgin PEEK resin supply concentrates among three European compounders, exposing filament extruders to input cost volatility and allocation priority disputes during capacity crunches.
- Technical ceiling:Fused deposition modeling layer adhesion weakness prevents load-bearing aerospace applications from qualifying for primary structure certification, capping addressable market scope.
- REACH oligomer thresholds:ECHA registration requirements for low-molecular-weight PEEK fractions are forcing reformulation of legacy extrusion grades, raising compliance costs for mid-tier producers.
Strategic Opportunities
- India CDSCO pathway expansion:Domestic medical device manufacturing incentives under the PLI scheme are creating first-mover advantage for certified filament suppliers establishing local compounding partnerships.
- Continuous fiber reinforcement convergence:Hybrid extrusion systems combining PEEK matrix with carbon fiber tow are enabling isotropic mechanical properties previously exclusive to selective laser sintering.
- Direct-to-OEM distribution:Bypassing industrial distributors through qualified supplier programs with tier-one aerospace contractors captures margin and locks in multi-year volume commitments.
Industry Challenges
- Thermal processing expertise scarcity:Qualified technicians capable of maintaining 343°C melt zones with moisture-controlled environments command premium wages, constraining extruder capacity expansion.
- FDA 510(k) timeline compression:Implantable device submissions require polymer degradation testing protocols that extend qualification cycles, delaying revenue recognition for new filament grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PEEK Filament Market |
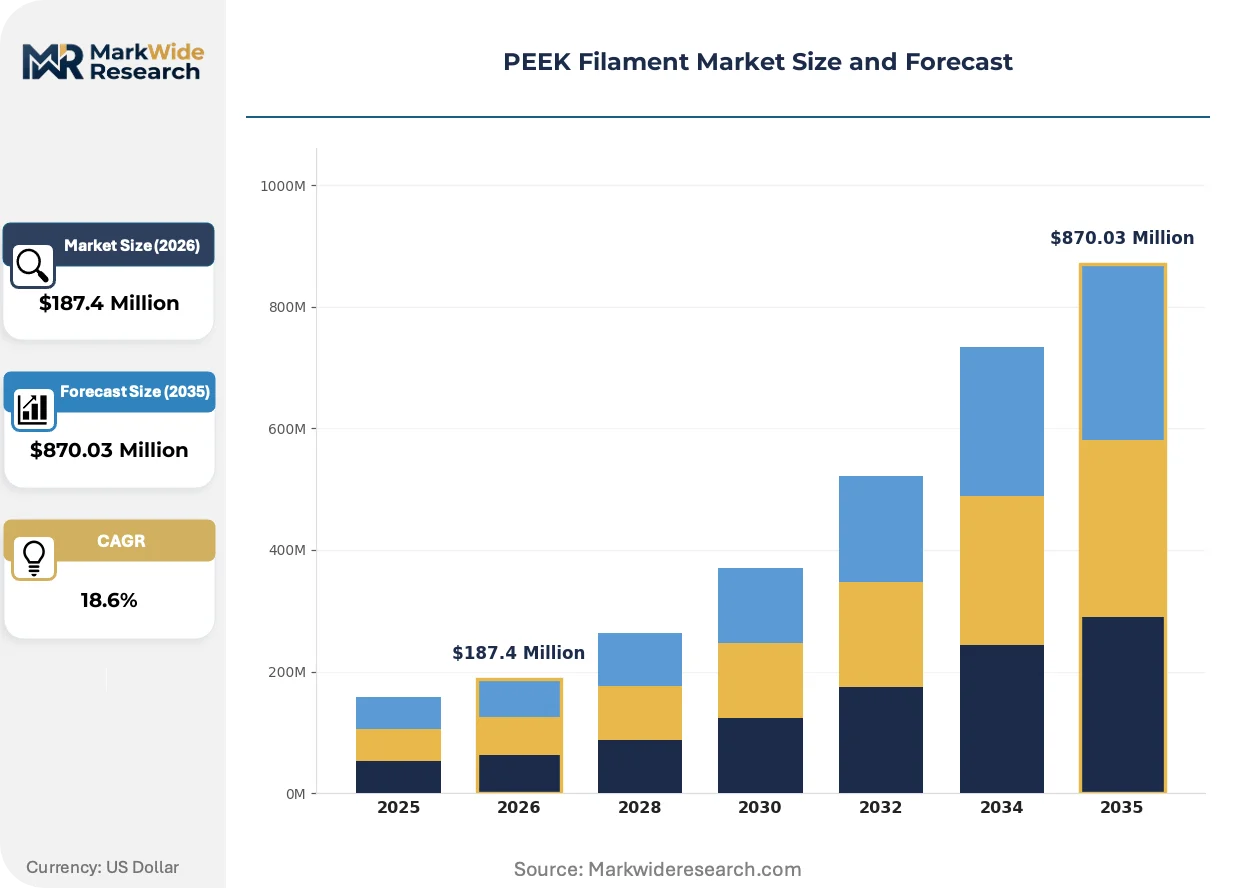
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament, Fiber, Composite, Reinforced Form: Filament Spools, Filament Rods, Filament Sheets, Filament Pellets Application: Aerospace, Automotive, Medical Devices, Industrial Equipment Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Binder Jetting |
| Companies Covered | Ensinger, 3D4Makers, Evonik, SABIC, Lehvoss, Solvay, 3DXTech, Zyppeek, Victrex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PEEK Filament Market Evolving Landscape
High-temperature polymer processing capabilities are fragmenting along certification-grade lines, separating medical-device-qualified suppliers from industrial-grade competitors.
Multi-material extrusion systems capable of depositing PEEK alongside soluble support structures are decomposing the historical barrier between prototyping and production-grade additive manufacturing. Aerospace contractors are adopting these platforms for flight-ready ducting and bracketry. The technology is decomposing the market segmentation between prototype shops and certified production facilities.
EMA and FDA convergence on polymer degradation testing protocols is harmonizing submission requirements across transatlantic markets. Device OEMs can now leverage single qualification datasets for dual regulatory filings. Implantable spine and orthopedic segments are consolidating supplier rosters around dual-certified compounders capable of supporting unified documentation packages.
Certification-driven procurement is displacing price-first sourcing among tier-one medical device manufacturers. Supplier qualification programs now prioritize batch traceability and regulatory file support over unit cost. German industrial clusters exhibit the most advanced buyer consolidation, with Frankfurt-area OEMs pooling vendor audit resources to accelerate supplier onboarding timelines.
PEEK Filament Market Segmentation
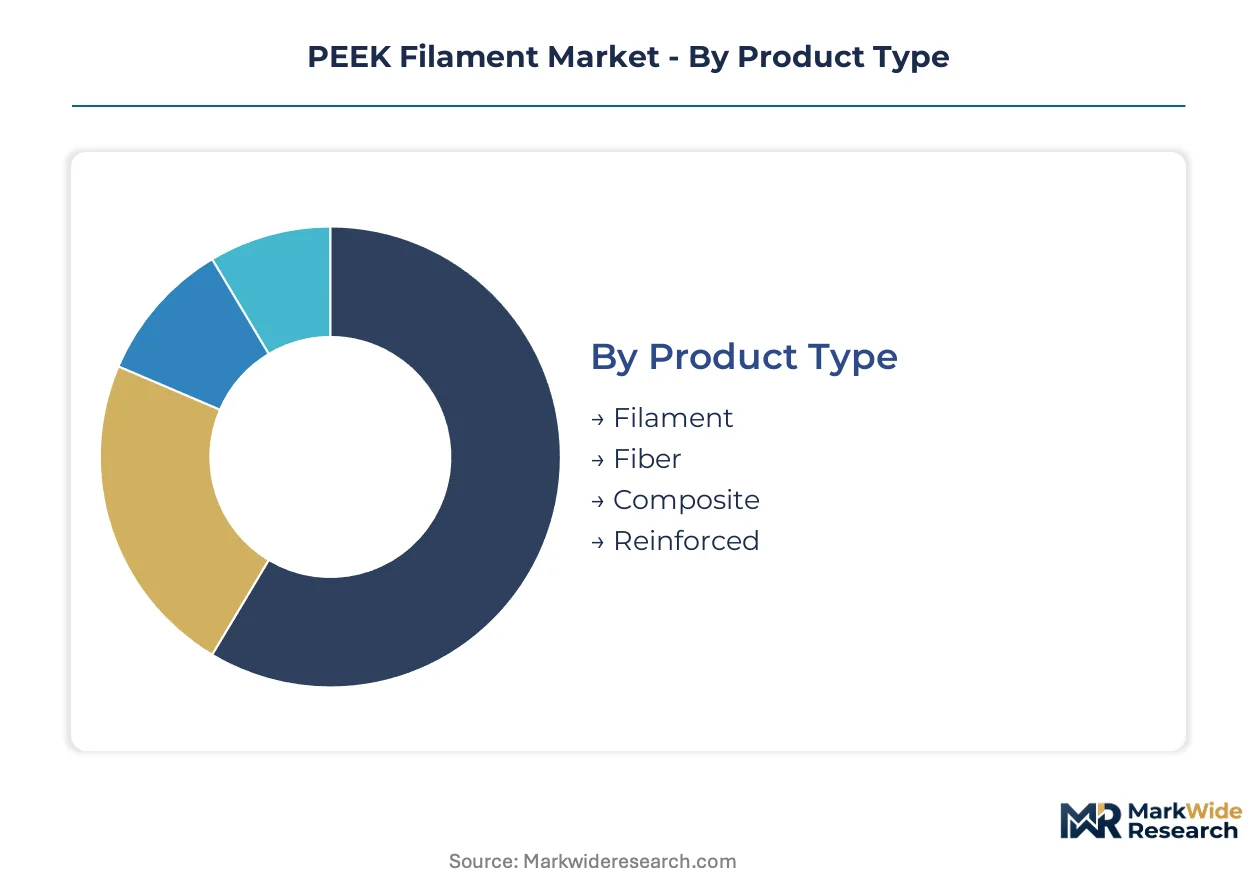
PEEK filament segmentation reveals how certification requirements and processing constraints fragment margin pools across distinct technical specifications. Each dimension—product chemistry, physical form, end-use application, and manufacturing technology—carries unique entry barriers that reshape supplier competitive position.
Product Type:
Pure filament commands the deepest margin pools due to medical-grade certification burdens and batch-traceability documentation requirements that filter out commodity producers.
- Filament:Extruded polyetheretherketone polymer with melt temperatures near 343°C, forming the standard feedstock for fused deposition modeling systems. Demand concentrates in Germany's Frankfurt-Stuttgart industrial corridor where medical device and automotive engineering ecosystems overlap, driven by EU MDR biocompatibility mandates requiring full polymer chain documentation.
- Composite:PEEK matrix combined with carbon fiber or glass fiber reinforcement, delivering isotropic mechanical properties previously exclusive to selective laser sintering. Aerospace contractors in the United States and Germany are adopting hybrid extrusion systems for flight-ready ducting and bracketry, displacing pure filament in load-bearing applications.
- Fiber:Continuous filament tow for textile and braided applications requiring high tensile strength.
- Reinforced:Discontinuous fiber-filled grades for enhanced stiffness in general industrial tooling.
The dominant share belongs to Filament, while Composite is closing the gap fastest as continuous fiber reinforcement convergence enables new aerospace qualifications.
Form:
Physical configuration determines processing infrastructure requirements and directly shapes customer switching costs between additive and subtractive manufacturing workflows.
- Filament Spools:Wound polymer feedstock for fused deposition modeling systems, requiring moisture-controlled storage and precision diameter tolerance. Automotive prototyping shops in Stuttgart industrial clusters represent concentrated demand, constrained by thermal processing expertise scarcity that limits qualified extruder capacity expansion.
- Filament Pellets:Granular resin for compounding and custom extrusion operations, serving medical device OEMs with proprietary formulation requirements. India's CDSCO pathway expansion under PLI scheme incentives is creating first-mover advantage for certified suppliers establishing local compounding partnerships.
- Filament Rods:Solid cylindrical stock for machining and subtractive manufacturing of precision components.
- Filament Sheets:Flat stock for thermoforming and compression molding of structural panels.
Spools retain the largest installed base, though Pellets are expanding most quickly as OEMs seek backward integration into captive compounding operations.
Application:
End-use verticals separate by certification burden intensity, with implantable medical and primary aerospace structures commanding premium pricing over industrial prototyping.
- Medical Devices:Implantable spine and orthopedic segments requiring FDA 510(k) clearance and EU MDR biocompatibility testing under EMA oversight. Supplier rosters are consolidating around dual-certified compounders capable of supporting unified documentation packages for transatlantic market access.
- Aerospace:Non-critical structural brackets and ducting components in narrow-body retrofit programs, accelerated by FAA airworthiness directives for fuel efficiency. Fused deposition modeling adoption is climbing the fastest here as multi-material extrusion systems decompose barriers between prototyping and production-grade additive manufacturing.
- Automotive:Underhood components and lightweight structural elements for electric vehicle thermal management.
- Industrial Equipment:General engineering applications with broader tolerance specifications and price-sensitive procurement.
Medical Devices holds the steepest expansion trajectory in value terms, while Aerospace is gaining share fastest in volume as qualification timelines compress for non-critical components.
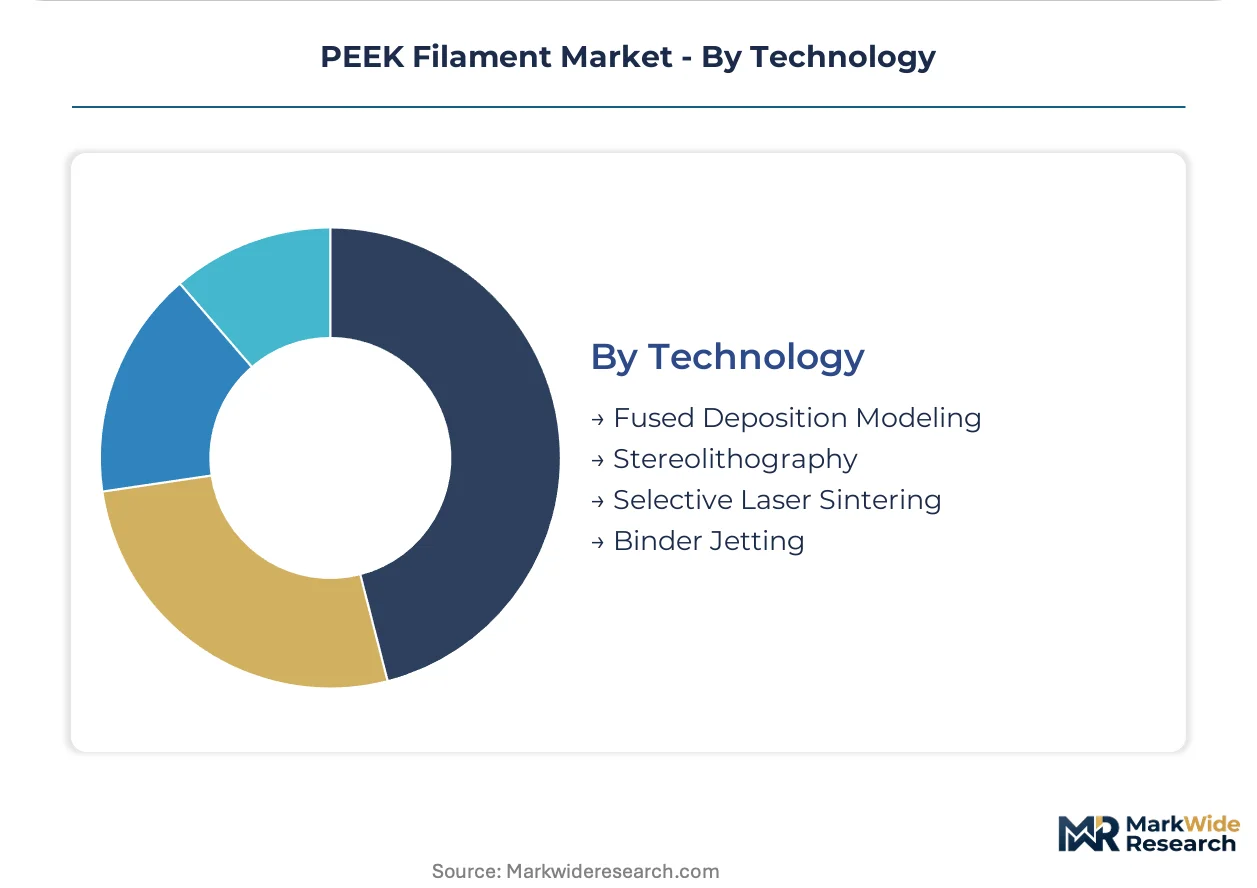
Technology:
Processing method selection locks in mechanical property profiles and determines addressable application scope through layer adhesion characteristics.
- Fused Deposition Modeling:Thermoplastic extrusion through heated nozzles, occupying the largest installed base for PEEK processing. Technical ceiling from layer adhesion weakness prevents primary structure aerospace certification, capping addressable market scope despite cost accessibility.
- Selective Laser Sintering:Powder bed fusion delivering isotropic mechanical properties without layer adhesion weaknesses, capturing premium aerospace work. Equipment and material costs restrict adoption to qualified production facilities with capital-intensive infrastructure.
- Stereolithography:Photopolymerization-based processing with limited PEEK compatibility due to resin formulation constraints.
- Binder Jetting:Powder-based deposition with post-processing sintering, emerging for complex geometries in metal-polymer hybrid workflows.
Fused Deposition Modeling dominates current throughput, though Selective Laser Sintering is climbing the fastest as aerospace contractors prioritize isotropic qualification data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders supply certified medical-grade feedstock to device manufacturers in the United States and Switzerland, establishing the primary transatlantic trade corridor for implantable-grade PEEK filament.
United States
FAA airworthiness directives for narrow-body fuel efficiency are accelerating FDM adoption for non-critical aerospace brackets and ducting. FDA's 510(k) pathway for implantable devices maintains stringent polymer degradation testing requirements. The Greater Boston medical device corridor concentrates demand for spine and orthopedic applications with full batch traceability documentation.
Germany
Frankfurt-Stuttgart industrial clustering creates shared infrastructure for high-temperature polymer processing across automotive and medical device ecosystems. EU MDR biocompatibility mandates under EMA oversight require full polymer chain documentation for implantable applications. Baden-Württemberg engineering centers are pooling vendor audit resources to compress supplier qualification timelines for certified feedstock procurement.
Switzerland
Swissmedic oversight of implantable devices reinforces demand for high-purity PEEK grades with dual-certified documentation packages. Proximity to German compounding infrastructure reduces lead times for medical-grade feedstock. The Basel-Zurich corridor anchors European demand for spine and orthopedic implant materials with transatlantic regulatory file compatibility.
China
Domestic medical device manufacturing expansion under NMPA oversight is creating captive demand for certified filament supply chains. MIIT industrial upgrading programs prioritize high-performance polymer localization for aerospace and automotive applications. Yangtze River Delta manufacturing clusters are developing compounding partnerships to reduce import dependency for medical-grade feedstock.
India
CDSCO pathway expansion under PLI scheme incentives is attracting certified filament suppliers to establish local compounding partnerships. Domestic medical device manufacturing targets are concentrating demand in Maharashtra and Gujarat industrial zones. Bangalore-Telangana medical technology corridors are emerging as qualification hubs for implantable-grade polymer processing expertise.
PEEK Filament Market Competitive Landscape
Player mix skews toward European compounders with vertically integrated resin-to-filament operations. Market structure concentrates volume among three archetypes: medical-grade specialists with batch-level documentation capabilities, industrial-grade price competitors serving automotive prototyping, and aerospace-focused suppliers pursuing isotropic mechanical property qualifications. Dominant competitive moves include backward integration into captive resin compounding and direct-to-OEM distribution partnerships that bypass industrial distributors.
Within the medical-grade specialist tier, Ensinger and Victrex exemplify archetypes differentiated by European compounding infrastructure depth and biomaterials division focus respectively. 3DXTech occupies a position on the industrial-grade vector, representing price-accessible competitors with broader tolerance specifications for general engineering customers. These three anchors illustrate how certification burdens and traceability requirements stratify competitive position across end-use verticals.
| Leading Market Players |
|---|
| Ensinger |
| 3D4Makers |
| Evonik |
| SABIC |
| Lehvoss |
| Solvay |
| 3DXTech |
| Zyppeek |
| Victrex |
| Others |
Value Network & Pricing Analysis
Scale economies in high-temperature extrusion infrastructure concentrate production among three European compounders, creating asymmetric pricing power where batch-traceability documentation commands premium spreads over commodity grades. Virgin PEEK resin allocation priority during capacity crunches feeds directly into filament price floors, compressing margins for non-integrated extruders while reinforcing the dominance of backward-integrated suppliers.
Pricing Analysis
Current-generation FDM filament pricing diverges sharply from prior-generation industrial grades and emerging next-generation continuous fiber-reinforced composites. Contract-based long-term offtake agreements dominate medical-grade procurement, with price differentiation driven by certification tier (FDA 510(k) vs. industrial prototyping) and volume scale. Cost compression in standard industrial grades is intensifying as automotive prototyping shops consolidate purchasing, while implantable-device OEMs exhibit the lowest price sensitivity due to regulatory file substitution costs.
Supply Chain Analysis
Strait of Hormuz transit exposure for specialty chemical precursors underwrites supply vulnerability in European PEEK resin production, though the primary chokepoint sits upstream in German and Swiss compounding capacity. Virgin resin supply concentrates in Germany, Switzerland, and the United Kingdom, with fluorinated monomer feedstock drawing from Belgian and French chemical infrastructure. Single-source vulnerability in medical-grade certification documentation creates qualification bottlenecks that extend lead times. Distribution runs through qualified supplier programs with tier-one aerospace contractors and pooled vendor audit consortia in the Frankfurt-Stuttgart corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PEEK filament market sits in early-cycle recovery following the post-MDR implementation supply chain reorganization, with aerospace lightweighting protocols and India PLI scheme incentives providing cyclical uplift through sustained capital deployment.
For Market Incumbents: Fortify batch-level traceability documentation systems against emerging entrants with carbon fiber composite hybrid capabilities. Deepen captive resin compounding in Baden-Württemberg to secure allocation priority during European capacity crunches. Lock in multi-year direct-to-OEM distribution partnerships with tier-one aerospace contractors before qualification timelines compress further. For New Entrants and Emerging Players: Differentiate on continuous fiber reinforcement convergence for aerospace bracketry applications where FDM technical ceilings have ceded share to selective laser sintering. Target India's CDSCO pathway expansion under PLI scheme incentives as the most penetrable geography, with Maharashtra industrial zones offering shared high-temperature processing infrastructure. Pursue hospital system partnership go-to-market angles for spine implant filament supply. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dual-certified compounders capable of unified FDA-EMA documentation packages for transatlantic medical device OEMs. Long-term viability hinges on regulatory file support capabilities rather than unit cost position, with five-to-ten year windows favoring upstream integration into virgin resin production. Watch FDA-EMA convergence on polymer degradation testing protocols as the inflection indicator for supplier roster consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Virgin Resin Compounding | Ensinger and Victrex anchor supply security through captive European production infrastructure. |
| Continuous Fiber Reinforcement Convergence | Hybrid extrusion systems enable isotropic mechanical properties for FAA-qualifiable aerospace brackets. |
| Direct-to-OEM Distribution Partnership | Bypassing industrial distributors captures margin and locks multi-year volume with tier-one contractors. |
| Dual Certification Investment (FDA-EMA) | Unified documentation packages accelerate supplier onboarding for transatlantic implantable device OEMs. |
| India CDSCO Pathway Localization | PLI scheme incentives create first-mover advantage for certified filament compounding partnerships. |
Research Methodology
Initial hypotheses were tested against primary input from medical device procurement managers, aerospace tier-one supplier quality engineers, high-temperature extrusion plant managers, and regulatory affairs specialists at EMA-notified bodies, then refined against secondary validation from FDA 510(k) filings, EMA MDR technical documentation, EU customs trade data for PEEK resin imports, and SEC 10-K disclosures from listed compounders. Bottom-up filament demand estimates triangulated with top-down aerospace and medical device production forecasts.
Variance in projected outcomes decomposes across certification-grade segmentation, processing technology adoption curves, and regional regulatory pathway timelines. The analytical framework models pure filament, composite, and reinforced product chemistry dimensions alongside FDM, SLS, and emerging binder jetting technology splits throughout the forecast period. CAGRs derive from installed base expansion in aerospace retrofit programs and EU MDR-driven supplier consolidation in implantable orthopedics, with continuous fiber reinforcement penetration and India domestic manufacturing incentives as key sensitivity inputs.
Material uncertainties — REACH oligomer threshold revisions, FDA polymer degradation testing protocol updates, and virgin resin allocation disputes during European capacity crunches — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EMA-FDA regulatory convergence and aerospace qualification timeline compression evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Additive Manufacturing Platform Market
3D Printing Technology
Online 3D Printing Service Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
3D Printing Market
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
Global 3D Printing in Medical Applications Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
3D Printing Service Bureaus Market