
 Aluminum Alloy 3D Printing Service Market | 2026-2036
Aluminum Alloy 3D Printing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Alloy 3D Printing Service Market Insights
REACH is broadening the cost-of-entry calculus for aluminum alloy 3D printing service providers by mandating full material traceability and substance disclosure across European supply chains. EOS GmbH Electro Optical Systems leverages its integrated powder-to-part workflow to sustain certification continuity across multiple regulatory jurisdictions. SLM Solutions Group AG anchors its competitive position through proprietary multi-laser platform architecture optimized for aluminum alloy density requirements.
Aluminum alloy 3D printing service denotes contract manufacturing of parts from AlSi10Mg, AlSi7Mg, or Scalmalloy feedstocks using powder-bed fusion or directed energy deposition, typically achieving tensile strengths of 310-400 MPa with densities near 99.5% theoretical. The primary commercial purpose centers on producing topology-optimized structural components that replace machined or cast aluminum assemblies in weight-critical applications. Prototyping still occupies the largest revenue share among service types, though mass customization is accelerating fastest as digital inventory models displace conventional tooling economics. Selective laser melting dominates printing technology revenue due to its established qualification pathway with aerospace OEMs, while wire arc additive manufacturing is extending into larger structural grades where deposition rates offset surface finish limitations.
FAA airworthiness directives, EASA Part 21 certification frameworks, and ISO/ASTM 52900 additive manufacturing standards collectively shape market access by defining allowable build parameters and post-processing protocols for flight-critical aluminum components. China's GB standards and NMPA oversight for medical device applications further fragment compliance requirements for multinational service bureaus. Stakeholders must monitor evolving alloy qualification timelines at major aviation regulators, as certification bottlenecks present greater near-term constraint than raw printer capacity expansion.
Market Dynamics
Multi-laser powder-bed fusion architectures are compressing build times for aluminum alloy components while REACH substance disclosure mandates force service bureaus to reconfigure material traceability systems across European supply chains.
Growth Catalysts
- FAA Airworthiness Pathways:Established qualification frameworks for selective laser melting of AlSi10Mg enable aerospace OEMs to certify flight-critical brackets and manifolds without full requalification cycles.
- Topology Optimization Software:Generative design tools now export build-ready lattice structures that reduce component mass by 40-60 percent versus conventional machined assemblies in motorsport and satellite applications.
- German Industrial Cluster Density:Concentrated equipment manufacturers, powder suppliers, and post-processing specialists in Bavaria and Baden-Württemberg shorten development iterations for aluminum alloy service contracts.
Market Restraints
- Argon and Helium Supply Volatility:Inert gas consumption of 50-200 liters per build hour exposes service margins to rare gas price spikes from Qatar and Algeria export disruptions.
- Build Chamber Size Constraints:Standard 400x400x400 mm powder-bed platforms cannot accommodate single-piece aerospace structural members exceeding one meter, forcing segment welding.
- Titanium Substitution in High-Temp Zones:Ti-6Al-4V maintains dominance in engine-adjacent brackets above 150°C operating temperatures, capping aluminum alloy addressable market in propulsion systems.
Strategic Opportunities
- Wire Arc Additive Manufacturing:WAAM deposition rates of 2-4 kg/hour enable near-net-shape production of aluminum alloy tooling and marine propellers that powder-bed systems cannot scale economically.
- India Defense Indigenization:DRDO mandates for domestic sourcing of aerospace structures create captive demand for certified aluminum additive capacity under BIS and CEMILAC oversight.
- Digital Inventory Models:Spare part catalog digitization by industrial OEMs is displacing physical warehousing economics, favoring distributed aluminum alloy print nodes over centralized casting foundries.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:Simultaneous FAA, EASA, and CAAC qualification for identical AlSi10Mg build parameters requires redundant testing campaigns that extend program schedules by 18-24 months.
- Post-Processing Skill Scarcity:Hot isostatic pressing and precision machining of thin-walled aluminum lattice structures demand technicians trained in both metallurgy and CNC programming, a combination rarely found in traditional job shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Alloy 3D Printing Service Market |
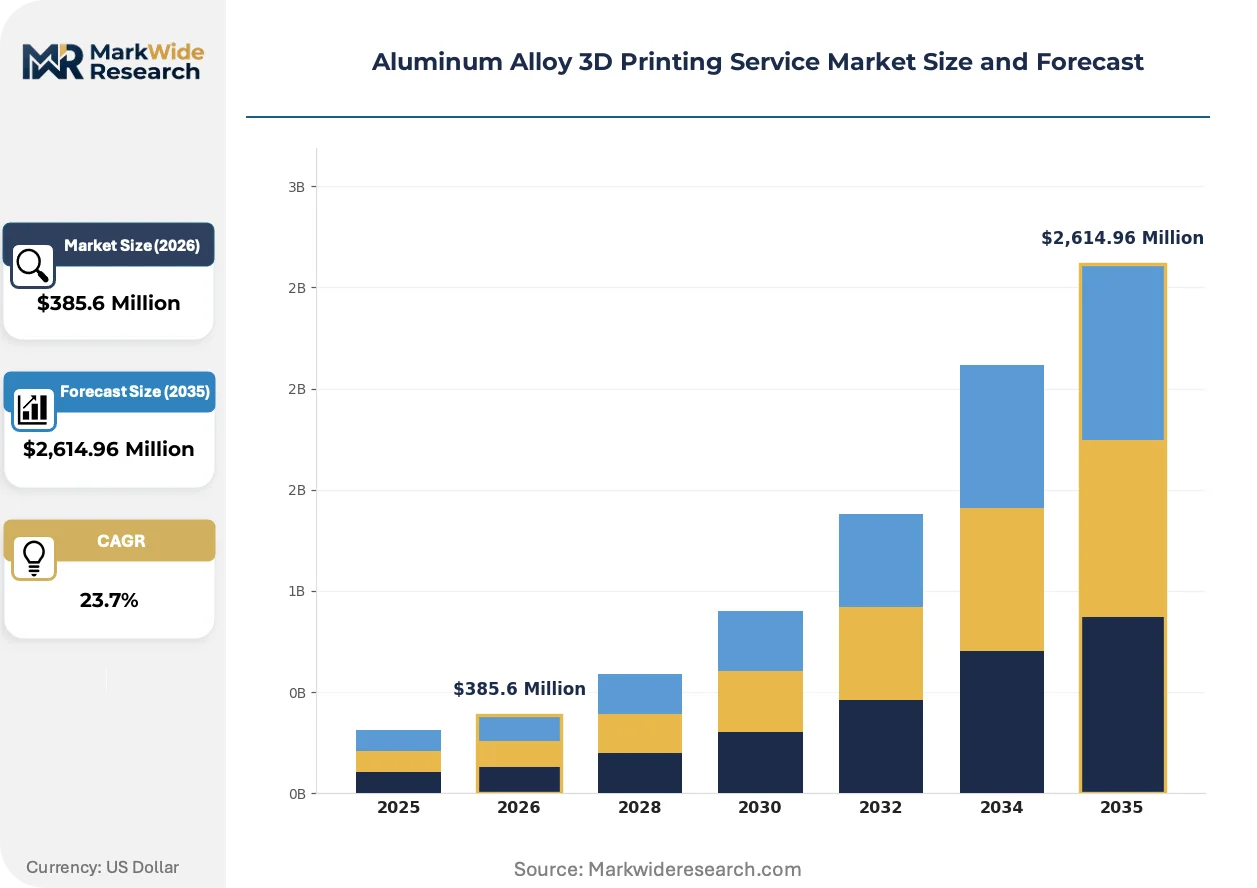
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $2,614.96 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Prototyping, Low Volume Production, Rapid Tooling, Mass Customization, Design Validation Printing Technology: Selective Laser Melting, Direct Metal Laser Sintering, Electron Beam Melting, Binder Jetting, Wire Arc Additive Manufacturing End User Industry: Aerospace, Electronics Manufacturing, Consumer Goods, Energy Equipment, Precision Engineering Material Grade: Marine Grade, Aerospace Grade, Automotive Grade, Structural Grade, Heat Treatable |
| Companies Covered | 3D Systems Corporation, EOS GmbH Electro Optical Systems, Renishaw plc, Materialise NV, SLM Solutions Group AG, GE Additive, BeamIT Group, IN3DTEC, MET3DP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Alloy 3D Printing Service Market Trends and Innovations
Process monitoring systems and in-situ metrology are converging to enable real-time defect detection during aluminum alloy builds, shifting quality assurance from post-build inspection to layer-by-layer intervention.
Scalmalloy feedstock formulations are integrating scandium and zirconium additions to achieve 520 MPa tensile strength in as-built conditions. Motorsport chassis manufacturers in Italy and the United Kingdom are adopting these alloys for suspension uprights previously machined from 7075 aluminum billets. The material is integrating high-performance aluminum into load-bearing applications once reserved for titanium or steel.
REACH Article 33 disclosure obligations now mandate full substance declaration for aluminum alloy powders containing trace alloying elements above 0.1 percent concentration. European service bureaus must requalify supply chains or face market exclusion from aerospace and medical device contracts. German powder producers are responding by certifying virgin and recycled feedstocks under identical material data sheets to preserve customer flexibility.
Spare parts procurement for aging aircraft fleets is migrating from forecast-based stocking to on-demand digital manufacturing. MRO providers in the United States and France are establishing captive aluminum additive cells to eliminate minimum order quantities and tooling lead times for obsolete brackets and ducting. This pattern concentrates in platforms with 20-plus year service lives where original tooling no longer exists.
Aluminum Alloy 3D Printing Service Market Segmentation
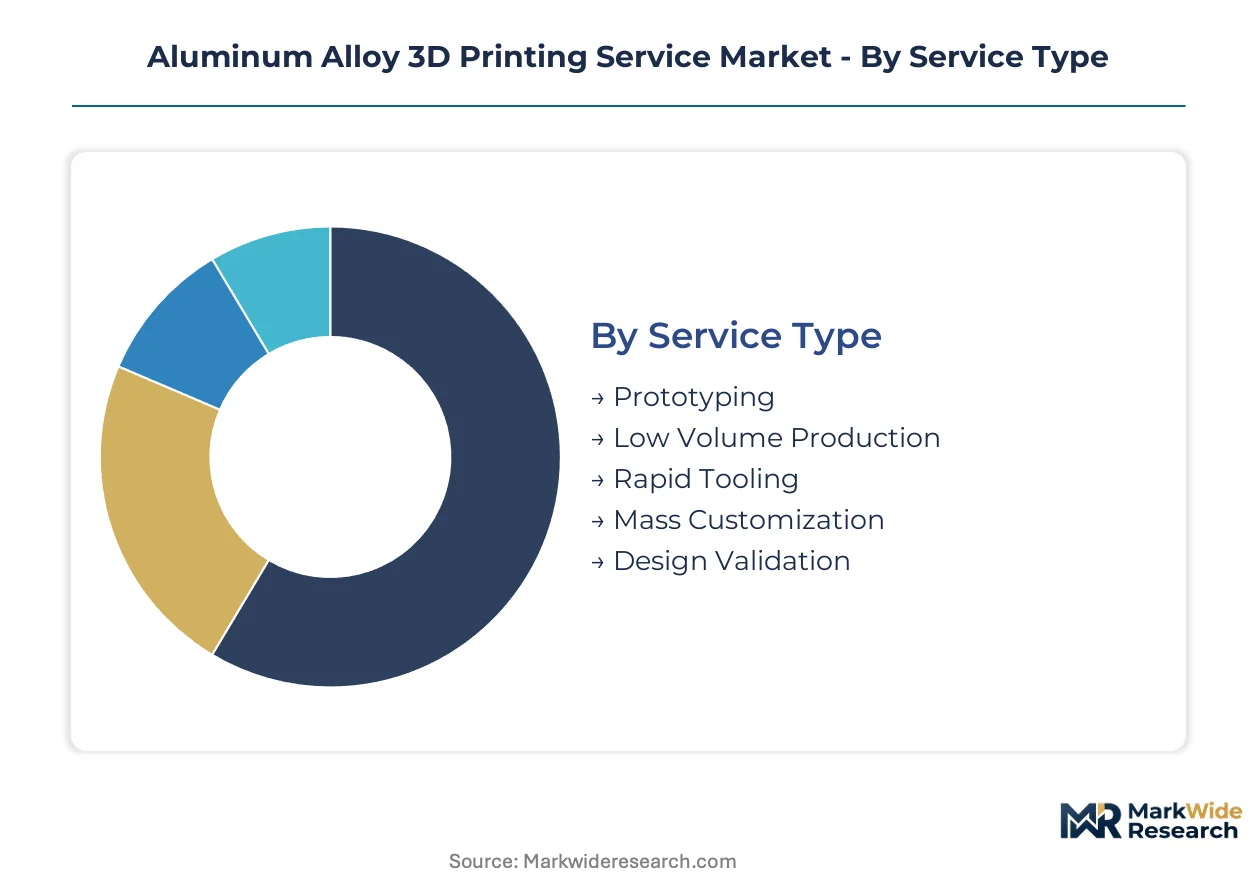
Service differentiation in aluminum alloy 3D printing hinges on certification depth, build volume economics, and post-processing complexity. Buyers select providers based on whether their application demands flight-critical qualification or rapid iteration without formal material traceability.
Service Type:
Cost tier separates buyers seeking one-off validation from those requiring production-grade material certification and lot traceability.
- Prototyping:Iterative design validation using AlSi10Mg or AlSi7Mg without full mechanical certification. Aerospace OEMs in Germany and the United States dominate demand for topology-optimized bracket iterations prior to formal qualification.
- Low Volume Production:Certified batch manufacturing of 10-500 units with full material data sheets and REACH-compliant powder genealogy. Satellite manufacturers in France leverage this tier for flight-qualified structural nodes where casting tooling proves uneconomical.
- Rapid Tooling:Conformally cooled mold inserts and die casting cores printed in aluminum alloys for thermal management. Tool and die shops in Bavaria shorten injection molding lead times by eliminating conventional machining.
- Mass Customization:Patient-specific medical fixtures and bespoke motorsport components produced from digital inventories. Italian chassis manufacturers print suspension uprights matched to individual driver biomechanics.
- Design Validation:Form and fit testing using non-certified builds to verify assembly interfaces before committing to production tooling. Electronics contract manufacturers in Shenzhen accelerate product development cycles.
Prototyping leads volumes today; mass customization is gaining share fastest.
Printing Technology:
Application temperature and surface finish requirements dictate process selection, with aerospace qualification pathways favoring established powder-bed methods.
- Selective Laser Melting:Multi-laser powder-bed fusion achieving 99.5% density in AlSi10Mg with layer thicknesses of 20-60 microns. FAA and EASA qualification frameworks center on this technology for flight-critical brackets and manifolds.
- Direct Metal Laser Sintering:Single-laser or dual-laser systems with comparable material properties to SLM but distinct parameter sets requiring separate certification campaigns. German service bureaus maintain both capabilities to preserve customer flexibility.
- Electron Beam Melting:Vacuum-based powder-bed process minimizing residual stress in thick aluminum sections through preheated build plates. Limited adoption outside Sweden and the United Kingdom due to slower build rates and surface roughness.
- Binder Jetting:Green-state printing with subsequent sintering enabling higher throughput for non-critical components. Post-processing complexity limits penetration in structural aerospace applications.
- Wire Arc Additive Manufacturing:Deposition rates of 2-4 kg/hour producing near-net-shape marine propellers and tooling exceeding one meter in dimension. Norwegian shipyards and Dutch offshore fabricators adopt WAAM where powder-bed platforms face build envelope constraints.
Selective laser melting dominates certified aerospace work; wire arc additive manufacturing is climbing the fastest in industrial tooling.
End User Industry:
Margin structure and certification burden vary sharply across sectors, with flight-critical applications commanding premium pricing for full material genealogy.
- Aerospace:Airframe brackets, engine manifolds, and satellite structural nodes requiring EASA Part 21G supplier status or FAA delegated production authority. Airbus and Boeing tier-1 suppliers in France and the United States anchor demand for qualified AlSi10Mg builds.
- Electronics Manufacturing:Thermal management housings, RF waveguides, and lightweight chassis for telecommunications infrastructure. 5G base station deployments in China drive demand for complex geometries unachievable through extrusion.
- Consumer Goods:Premium bicycle frames, camera bodies, and sporting equipment where aesthetic surface finish and weight reduction justify additive economics. Italian and British manufacturers lead adoption in high-end cycling components.
- Energy Equipment:Heat exchangers, turbine vanes, and offshore platform components exposed to corrosive environments. Norwegian and UK North Sea operators specify marine-grade aluminum alloys for subsea hardware.
- Precision Engineering:Jigs, fixtures, and robotic end-effectors requiring rapid turnaround without tooling investment. German automotive suppliers print aluminum gripper fingers for assembly line automation.
Aerospace leads volumes today; electronics manufacturing is expanding most quickly.
Material Grade:
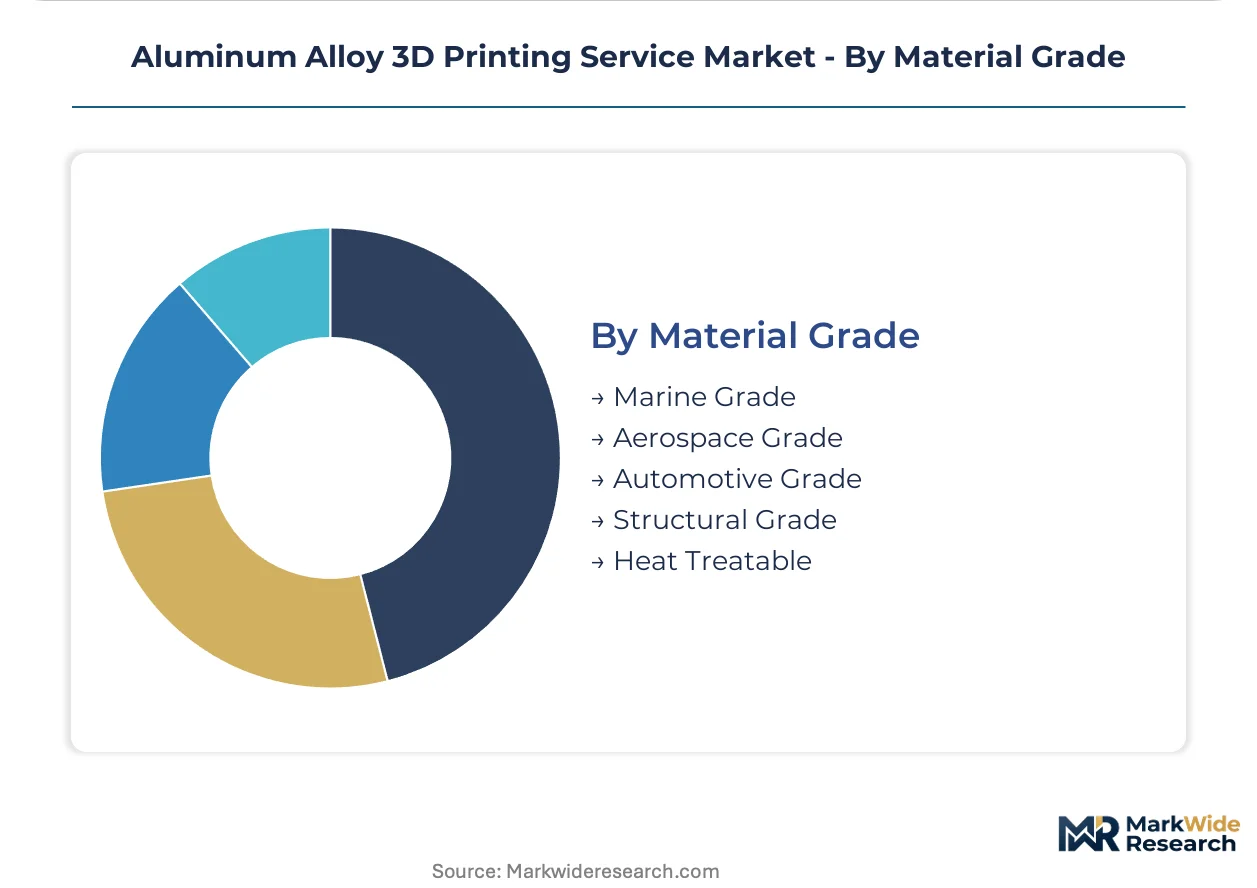
Performance tier and corrosion resistance specifications determine alloy selection, with scandium-bearing formulations commanding substantial feedstock premiums.
- Aerospace Grade:AlSi10Mg and Scalmalloy meeting AMS specifications for tensile strength, elongation, and fatigue life. Scandium additions achieving 520 MPa as-built strength enable titanium substitution in motorsport uprights.
- Marine Grade:AlMgSi alloys with enhanced salt spray resistance for offshore and naval applications. Norwegian classification society DNV rules govern additive manufacturing acceptance for shipboard structures.
- Automotive Grade:AlSi7Mg and AlSi10Mg variants optimized for crash energy absorption and cast-like mechanical properties. German OEMs qualify printed structural nodes for electric vehicle battery enclosures.
- Structural Grade:General-purpose aluminum alloys for non-critical load-bearing applications where weight reduction alone drives adoption. Construction and architectural sectors in the United Arab Emirates specify printed facade elements.
- Heat Treatable:2xxx and 7xxx series alloys requiring solution treatment and artificial aging to achieve wrought-equivalent properties. Limited commercial availability due to cracking susceptibility during thermal cycles.
Aerospace grade leads volumes today; marine grade is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled metallurgical technicians and certified additive manufacturing engineers concentrate in Germany, the United States, and China, anchoring the three dominant supply zones for aluminum alloy printing services. These talent clusters support regulatory-compliant production for aerospace and medical device applications.
Germany
Airbus tier-1 suppliers in Bavaria and Baden-Württemberg drive demand for flight-critical AlSi10Mg brackets and satellite nodes. EASA Part 21G supplier certification requirements filter market access, favoring established bureaus with delegated production authority. The Munich-Stuttgart industrial corridor hosts concentrated powder suppliers, equipment manufacturers, and post-processing specialists that compress development cycles.
United States
Boeing supply chain mandates and NASA small satellite initiatives sustain demand for topology-optimized structural components. FAA delegated authority frameworks enable direct OEM qualification of selective laser melting parameters without redundant testing. Greater Los Angeles and Pacific Northwest clusters anchor commercial space and defense additive capacity.
China
5G telecommunications infrastructure deployment and electric vehicle battery enclosure programs scale demand for complex aluminum thermal management geometries. GB standards and NMPA oversight for medical device applications fragment compliance requirements for multinational service bureaus. Yangtze River Delta industrial zones concentrate domestic equipment manufacturers and certified powder production.
France
Safran and Thales satellite manufacturing programs in Toulouse and Paris-Saclay qualify printed aluminum structural nodes for geostationary platforms. ANSM oversight for medical device applications extends material traceability requirements beyond aerospace baselines. The Île-de-France and Occitanie regions host specialized bureaus with dual EASA-ANSM certification.
United Kingdom
BAE Systems and Rolls-Royce defense programs sustain demand for rapid tooling and low-volume production of aluminum alloy brackets. The UK Space Agency funding for satellite constellations expands addressable market for printed structural components. Midlands and South East England clusters concentrate wire arc additive manufacturing capacity for large marine and defense structures.
Aluminum Alloy 3D Printing Service Market Competitive Landscape
The competitive structure tilts toward equipment-integrated service bureaus with multi-jurisdictional certification depth. Market access concentrates among players with established FAA and EASA qualification pathways, while smaller regional fabricators compete on rapid turnaround without formal material genealogy. Three archetypes dominate: powder-to-part integrated providers, multi-laser platform operators, and specialized aerospace certification houses. Capacity expansion and strategic technology licensing represent the dominant competitive moves, with players securing exclusive parameter sets from equipment OEMs.
Among German-integrated providers, EOS GmbH Electro Optical Systems and SLM Solutions Group AG exemplify the equipment-to-service archetype with captive powder and platform ecosystems. Materialise NV occupies a position within the software-anchored tier, bridging design optimization and certified production workflows. These three entities represent contrasting pathways to market access: hardware integration, multi-laser scale, and digital thread control.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| EOS GmbH Electro Optical Systems |
| Renishaw plc |
| Materialise NV |
| SLM Solutions Group AG |
| GE Additive |
| BeamIT Group |
| IN3DTEC |
| MET3DP |
| Others |
Pricing and Supply Chain Analysis
Airbus and Boeing tier-1 suppliers concentrate procurement authority for flight-critical aluminum alloy components, anchoring a project-based pricing model where certification depth commands substantial premiums over rapid prototyping tiers. This buyer concentration creates asymmetric negotiating power that compresses margins for service bureaus lacking delegated production authority from FAA or EASA.
Pricing Analysis
Bundled full-service contracts covering design optimization, build execution, and post-processing dominate aerospace procurement, while unbundled print-only pricing prevails in prototyping and consumer applications. Three-tier pricing structure across flight-certified, industrial-grade, and non-certified economy levels reflects the cost of material genealogy documentation and regulatory compliance. Cost compression in the economy tier is intensifying because Chinese equipment manufacturers are flooding the market with lower-cost powder-bed systems. Electronics manufacturers and consumer goods brands exhibit highest price sensitivity, whereas satellite OEMs and defense contractors prioritize qualification continuity over unit cost.
Supply Chain Analysis
Argon and helium supply rests on Qatari and Algerian export infrastructure, with German and Chinese gas distributors controlling downstream allocation to European and Asian additive manufacturing clusters. Aluminum powder feedstock draws from atomization facilities concentrated in Germany, the United States, and China, while scandium-bearing Scalmalloy formulations hinge on limited Australian and Russian rare earth processing. Single-source vulnerability in specialty inert gas supply exposes service margins to geopolitical disruption and energy price volatility. Distribution runs through equipment-integrated service bureaus with captive powder supply agreements, supplemented by independent job shops sourcing feedstock through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where aerospace OEMs are shifting procurement specifications toward full material traceability and multi-jurisdictional certification, disqualifying lower-tier competitors.
For Market Incumbents: Extend certification coverage across FAA, EASA, and CAAC jurisdictions simultaneously to capture sole-source contracts from multinational aerospace programs. EOS GmbH and SLM Solutions Group AG demonstrate how backward integration into powder atomization defends margin position against feedstock cost volatility. Incumbents must also expand hot isostatic pressing capacity in Germany and the United States to address post-processing skill scarcity. For New Entrants and Emerging Players: Equipment OEMs represent the most accessible channel partner category for market entry, offering parameter licensing and co-marketing support that accelerates qualification timelines. White-space concentration in Indian defense indigenization programs and Norwegian offshore wire arc additive manufacturing offers penetrable entry points without direct competition from established aerospace certification houses. New entrants should target rapid tooling applications in automotive supply chains where build volume requirements fall below incumbent minimum order thresholds. For Investors and Strategic Acquirers: Tier-1 aerospace suppliers are the most active acquirer in this space, seeking captive additive capacity to secure supply chain resilience and reduce dependency on external service bureaus. Long-term viability favors vertically integrated platforms combining powder production, multi-laser printing, and post-processing under unified quality systems. The signal to watch is EASA and FAA publication of harmonized qualification protocols for scandium-bearing aluminum alloys, which would unlock titanium substitution opportunities in motorsport and satellite applications.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Certification Investment | EASA Part 21G and FAA delegated authority unlock sole-source aerospace contracts. |
| Captive Powder Atomization Capacity | German producers certifying virgin and recycled feedstocks preserve customer flexibility under REACH. |
| Wire Arc Additive Manufacturing Scale-Up | Norwegian shipyards adopt WAAM for marine propellers exceeding powder-bed build envelopes. |
| Digital Inventory Platform Development | Industrial OEMs eliminate physical warehousing through distributed print node networks. |
| Post-Processing Skill Pipeline Investment | Combined metallurgy and CNC programming training addresses technician scarcity in Bavaria and Baden-Württemberg. |
Research Methodology
Bottom-up aerospace and electronics manufacturing modeling reconciled against top-down powder supply and equipment shipment tracking forms the analytical core of this study. Primary interviews with additive manufacturing service bureau executives, powder metallurgy specialists, EASA certification auditors, and Tier-1 aerospace procurement managers combined with secondary validation from FAA airworthiness directives, EASA Part 21G supplier databases, ISO/ASTM 52900 standards documentation, and customs trade data for aluminum alloy powder flows.
Historical trendline analysis of selective laser melting adoption rates across German, United States, and Chinese industrial clusters established baseline penetration patterns. The projection framework segments by service type, printing technology, end-user industry, and material grade, with CAGRs derived from equipment capacity expansion announcements and aerospace OEM sourcing commitments. Forecast inputs include scandium feedstock availability projections and evolving multi-jurisdictional certification timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare gas supply disruptions, harmonization delays between FAA and EASA qualification protocols, and substitution acceleration from titanium alloys in high-temperature applications. A small set of named triggers—including REACH substance disclosure enforcement actions and CAAC aluminum alloy certification pathway announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
Saudi Arabia and Egypt Healthcare 3D Printing Market
3D Printing Technology
Selective Laser Sintering Market
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
Additive Manufacturing Platform Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
3D Printer Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market