
 Hardcopy Peripherals and Printing Consumables Market | 2026-2036
Hardcopy Peripherals and Printing Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Hardcopy Peripherals and Printing Consumables Market Foresight
Specialized print-system engineering talent is rotating away from legacy mechanical design toward firmware and IoT integration, tightening supply for analog-era expertise. HP Inc. leverages its vertical control over ink formulation chemistry to sustain margin pools in the consumables segment. Canon Inc. anchors Asia-Pacific manufacturing scale through captive production of printheads and precision optics. Seiko Epson Corporation differentiates via proprietary MicroPiezo inkjet architecture that dominates photo and wide-format niches.
Hardcopy peripherals and printing consumables encompass electromechanical devices and expendable media that transfer digital images onto physical substrates, typically operating at resolutions from 300 to 2400 dots per inch and page speeds of 20–70 ppm in office configurations. Laser technology leads enterprise fleet deployments due to lower per-page economics and toner stability, while inkjet systems capture home and educational institution growth through compact footprint and color versatility at entry price points. Consumable type segmentation concentrates margin pools in inks and toners, where replacement cycles generate recurring revenue streams that exceed hardware profitability.
EPA Energy Star specifications and EU Ecodesign requirements constrain standby power and cartridge recyclability, compelling redesign of fuser assemblies and toner chemistry. China's SAMR enforces GB standards for electromagnetic compatibility and electrical safety in domestic-manufactured devices. India's BIS certification mandates ISI marking for imported printing equipment, creating procedural friction for non-local vendors. Stakeholders must monitor how regulatory divergence across these jurisdictions fragments testing protocols and whether consolidation toward universal efficiency benchmarks reshapes competitive access.
Market Dynamics
The hardcopy peripherals sector faces a structural squeeze between China's dual carbon mandates tightening energy-efficiency requirements and the persistent analog-to-digital transition draining legacy mechanical engineering talent pools.
Growth Catalysts
- Healthcare documentation workflows:Hospital information systems in the United States and Germany still require paper-based audit trails for patient records, sustaining institutional print volumes despite digitization elsewhere.
- India's tier-two commercial corridors:Digitization lags in secondary Indian cities such as Jaipur and Lucknow, concentrating demand for office printing equipment in expanding commercial districts.
- EPA Energy Star 3.0 specifications:Updated standby power thresholds for imaging equipment are accelerating replacement cycles among US federal procurement fleets.
Market Restraints
- Toner resin feedstock volatility:Styrene-acrylic copolymer prices fluctuate with crude oil derivatives, compressing consumables margin predictability for manufacturers.
- Printhead supply concentration:Precision MEMS fabrication for thermal inkjet arrays clusters in Taiwanese and South Korean foundries, creating single-source vulnerability.
- Document digitization substitution:Cloud-native collaboration platforms in Nordic enterprise sectors are displacing interoffice hardcopy distribution.
Strategic Opportunities
- India's BIS certification friction:Complex ISI marking procedures for imported equipment create white space for domestic assembly partnerships with local electronics manufacturers.
- Wide-format technical printing convergence:GIS mapping and architectural CAD output is merging with traditional photo reproduction, expanding addressable substrate versatility.
- EU Ecodesign circularity mandates:Cartridge take-back and recyclability requirements are opening remanufacturing service revenue streams.
Industry Challenges
- Firmware engineering scarcity:Embedded systems talent is migrating toward automotive and IoT sectors, leaving print controller development understaffed.
- GB standard electromagnetic compliance:China's SAMR testing protocols for domestic-manufactured devices extend product launch timelines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardcopy Peripherals and Printing Consumables Market |
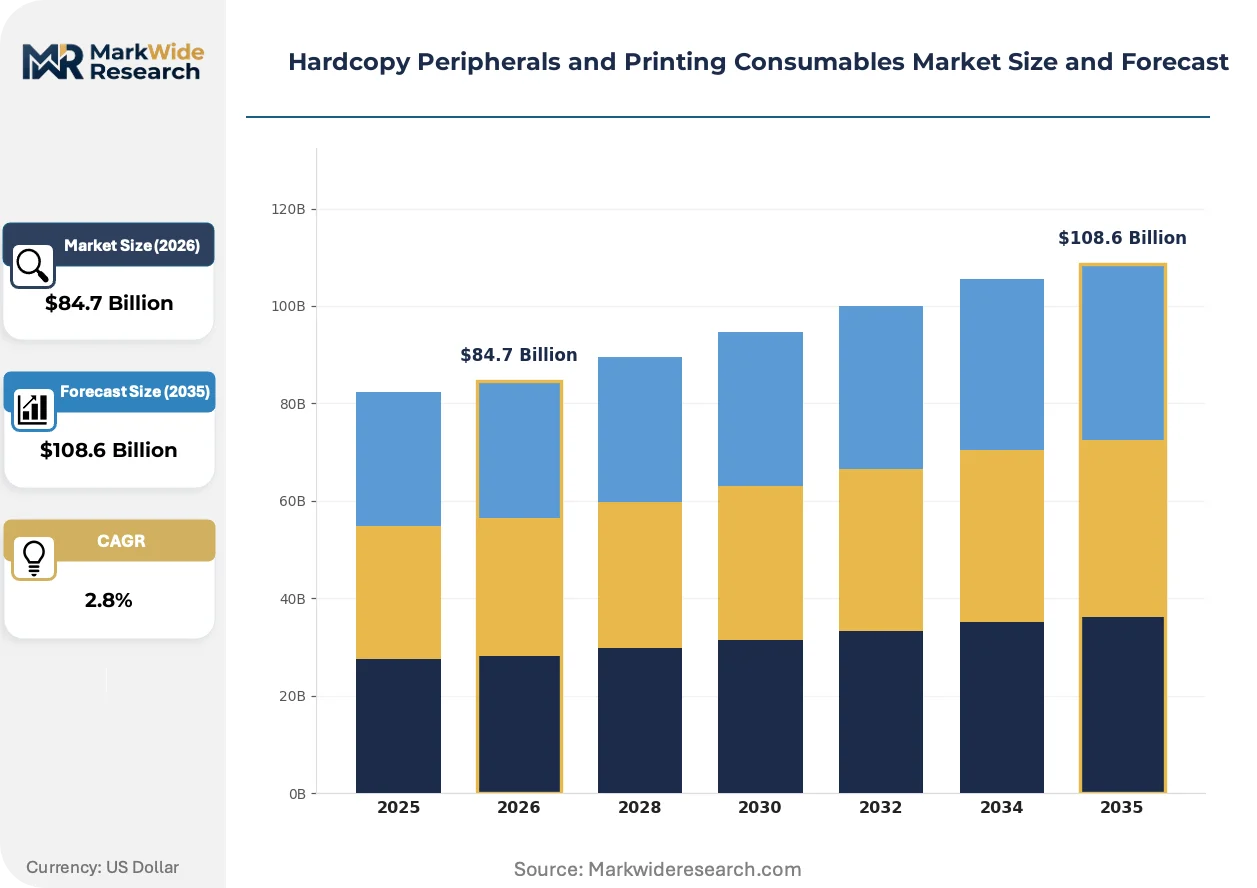
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $108.6 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printers, Scanners, Copiers, Fax Machines Consumable Type: Inks, Toners, Paper, Ribbons Technology: Inkjet, Laser, Solid Ink, Thermal End User: Office, Home, Educational Institution, Retail |
| Companies Covered | Brother Industries, Lexmark International, HP Inc., Samsung Electronics, Ricoh Company, Canon Inc., Xerox Corporation, Sharp Corporation, Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardcopy Peripherals and Printing Consumables Market Shifts & Advancements
Active technology and policy currents are compressing hardware footprints while tightening environmental compliance, forcing simultaneous investment in miniaturization and circular design.
MicroPiezo printhead architecture is miniaturizing. Seiko Epson's piezoelectric actuator technology enables picoliter droplet precision without thermal cycling degradation. Photo studios and fine-art reproduction houses in Japan and Italy are adopting these systems for archival pigment output. The technology is miniaturizing wide-format equipment dimensions while expanding color gamut depth, compressing studio floor space requirements.
China's GB 21521-2024 energy efficiency standards for imaging equipment took effect in early 2024. The regulations mandate maximum standby power consumption below 1.0 watt for laser devices and introduce tiered efficiency labeling. Domestic manufacturers in Dongguan and Suzhou are reengineering fuser assemblies and power management circuits to meet these thresholds, while importers face additional conformity assessment costs.
Managed print services contracts are unbundling hardware from consumables procurement. German Mittelstand firms and US healthcare systems are separating device leasing from per-page service agreements, enabling competitive sourcing of third-party toner and ink. This disintermediation is most pronounced in the United Kingdom's National Health Service trusts, where framework agreements now permit mixed-vendor fleet configurations.
Hardcopy Peripherals and Printing Consumables Market Segmentation
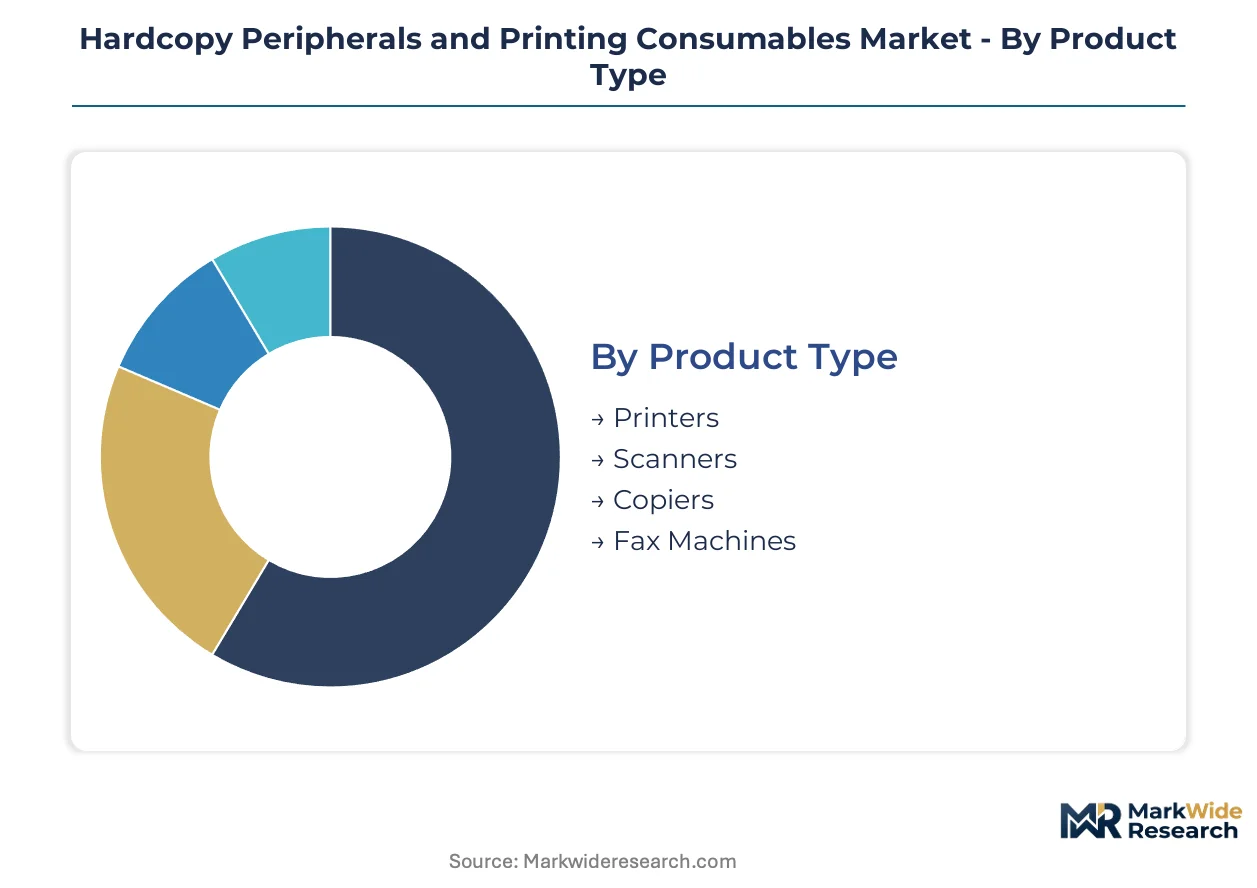
Segmentation in hardcopy peripherals reveals where digital substitution pressure concentrates most intensely. Hardware categories face divergent replacement cycles while consumables generate recurring revenue streams that resist obsolescence. Understanding these fault lines clarifies where manufacturers must defend installed bases versus pursue new volume.
Product Type:
Substitution pressure from document digitization falls unevenly across device categories, with standalone fax machines facing existential threat while multifunction systems absorb displaced demand.
- Printers:Electromechanical devices executing digital-to-physical image transfer at 300–2400 dpi resolution, spanning desktop inkjet units to production digital presses. Demand concentrates in United States healthcare systems where HIPAA audit trails mandate paper documentation, though cloud-native workflows erode volume in Nordic enterprise sectors.
- Scanners:Image capture peripherals converting physical documents to digital formats through CCD or CIS sensor arrays. Archive digitization projects in German Mittelstand firms sustain procurement, while AI-powered document classification accelerates replacement cycles in legal services.
- Copiers:Standalone duplication equipment without network connectivity, rapidly ceding ground to multifunction devices. Remaining demand clusters in India's tier-two commercial corridors where digitization lags in Jaipur and Lucknow office districts.
- Fax Machines:Analog transmission devices using PSTN infrastructure for document exchange. Regulatory requirements in Japanese healthcare and legal sectors preserve niche demand despite universal obsolescence elsewhere.
Printers retain volume leadership; scanners hold the steepest expansion curve as digitization accelerates.
Consumable Type:
Margin concentration varies sharply by chemistry and replacement frequency, with liquid formulations commanding premium pricing over commodity substrates.
- Inks:Aqueous or solvent-based liquid colorants formulated for piezoelectric or thermal inkjet deposition. Photo studios in Japan and Italy drive pigment ink adoption for archival output, while HP Inc. leverages vertical control over formulation chemistry to sustain margin pools.
- Toners:Dry powdered polymer mixtures fused to substrate via heat and pressure in laser systems. Styrene-acrylic copolymer feedstock volatility compresses margin predictability, though lower per-page economics sustain enterprise fleet preference.
- Paper:Cellulose-based substrates spanning office bond to coated photo media. Commoditization pressure intensifies as digital workflows reduce per-capita consumption in cloud-advanced markets.
- Ribbons:Fabric or film strips impregnated with ink for impact or thermal transfer printing. Point-of-sale and industrial labeling applications in legacy manufacturing sectors preserve residual demand.
Toners dominate revenue contribution; inks gain share fastest as photo and wide-format applications expand.
Technology:
Customer acquisition cost structures diverge dramatically by print mechanism, with thermal systems offering lowest entry pricing and laser technology locking in lifetime value through consumables.
- Inkjet:Non-contact deposition using thermal bubble or piezoelectric actuation to eject picoliter droplets. Seiko Epson's proprietary MicroPiezo architecture dominates photo and wide-format niches through superior color gamut depth without thermal cycling degradation.
- Laser:Electrophotographic imaging using photoconductive drums and dry toner fusion. Enterprise fleet deployments in United States federal procurement favor this technology for toner stability and EPA Energy Star 3.0 standby compliance.
- Solid Ink:Wax-based blocks melted and jet-deposited before cooling to bond with substrate. Niche adoption persists in graphic arts where dimensional texture and environmental claims differentiate output.
- Thermal:Direct heat-activated imaging on chemically treated substrates. Receipt printing and portable photo output exploit compact footprint and minimal moving parts for reliability-critical applications.
Laser technology anchors installed base value; inkjet systems climb fastest in home and educational penetration.
End User:
Procurement authority and total cost sensitivity fragment sharply across customer types, with institutional buyers emphasizing service contracts and residential purchasers prioritizing hardware acquisition cost.
- Office:Corporate and government workspaces requiring fleet management, security features, and volume scalability. United Kingdom National Health Service trusts now permit mixed-vendor configurations under framework agreements, disintermediating traditional single-source contracts.
- Home:Individual consumers prioritizing compact footprint, wireless connectivity, and low entry price points. Color versatility drives inkjet preference despite higher per-page economics versus laser alternatives.
- Educational Institution:K-12 and university environments balancing procurement budgets against curriculum-mandated hardcopy output. India's expanding commercial office corridors in tier-two cities concentrate demand where digitization infrastructure remains underdeveloped.
- Retail:Customer-facing environments including photo kiosks, receipt printing, and point-of-sale documentation. GIS mapping and architectural CAD convergence expands substrate versatility requirements in technical printing segments.
Office segments command revenue concentration; educational institutions expand most quickly as emerging market infrastructure catches up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB standards for electromagnetic compatibility and electrical safety, anchoring regulatory gravity in the Asia-Pacific manufacturing corridor.
United States
Healthcare documentation workflows sustain institutional print volumes across hospital information systems. EPA Energy Star 3.0 specifications accelerate replacement cycles among federal procurement fleets. Office equipment demand concentrates in metropolitan corridors from Boston to Dallas.
Germany
German Mittelstand firms drive scanner procurement for archive digitization projects. EU Ecodesign requirements constrain standby power and cartridge recyclability. Industrial clusters in Baden-Württemberg and Bavaria house precision optics manufacturing for printhead components.
China
Dual carbon goals tighten energy-efficiency mandates for imaging equipment manufactured in Dongguan and Suzhou. GB 21521-2024 standards mandate maximum standby power below 1.0 watt for laser devices. Domestic manufacturers reengineer fuser assemblies to meet tiered efficiency labeling.
India
Digitization lags in tier-two commercial corridors such as Jaipur and Lucknow, concentrating office printing equipment demand. BIS certification mandates ISI marking for imported printing equipment. Expanding commercial districts in secondary cities create white space for domestic assembly partnerships.
Japan
Regulatory requirements in healthcare and legal sectors preserve niche fax machine demand despite obsolescence elsewhere. METI oversees industrial standards for precision manufacturing. Photo studios and fine-art reproduction houses in Tokyo and Osaka adopt archival pigment output systems.
Hardcopy Peripherals and Printing Consumables Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with ink formulation chemistry and printhead fabrication anchoring competitive differentiation. The structure rewards vertical control over consumables margin pools and captive production of precision components. Three archetypes dominate: chemistry-integrated conglomerates, MEMS fabrication specialists, and managed print services operators. Competitive moves center on firmware engineering talent acquisition and circular design certification for EU market access.
Within the integrated conglomerate tier, HP Inc. and Canon Inc. represent chemistry-forward positioning through in-house ink formulation and printhead production. Seiko Epson Corporation exemplifies MEMS-driven specialization via proprietary piezoelectric actuator architecture. These three anchors demonstrate how control over consumables chemistry or precision fabrication creates defensive moats against third-party disintermediation.
| Leading Market Players |
|---|
| Brother Industries |
| Lexmark International |
| HP Inc. |
| Samsung Electronics |
| Ricoh Company |
| Canon Inc. |
| Xerox Corporation |
| Sharp Corporation |
| Seiko Epson Corporation |
| Others |
Supply & Pricing Matrix
Six-to-eight month lead times for precision MEMS printhead arrays from Taiwanese foundries concentrate upstream pricing power among thermal inkjet array fabricators, compressing margin flexibility for downstream OEMs assembling finished peripherals. This inventory-to-pricing linkage intensifies as China's GB 21521-2024 energy-efficiency mandates force redesign cycles that extend procurement planning horizons.
Pricing Analysis
Geographic price spreads between North American and Asia-Pacific consumables markets exceed thirty percent for equivalent toner formulations, reflecting tariff exposure and localized cartridge take-back compliance costs. The market operates on a contract-based long-term offtake structure bundling hardware leasing with per-page service agreements, though German healthcare systems and UK NHS trusts are unbundling these components. Price differentiation separates EPA Energy Star 3.0-certified fleets from uncertified legacy equipment, with certification tier and volume scale as primary drivers. Pricing pressure stems from styrene-acrylic copolymer feedstock volatility, with enterprise procurement offices least price-sensitive and educational institutions in emerging markets most sensitive.
Supply Chain Analysis
Taiwan and South Korea anchor precision MEMS fabrication for thermal inkjet printheads, while China and Japan dominate fuser assembly and precision optics production. Raw material dependencies draw from crude oil derivatives for toner resin, rare earth elements for photoconductive drums, and specialized substrates for coated photo media. Single-source vulnerability clusters in Taiwanese foundry capacity for MEMS arrays. Distribution runs through authorized dealer networks for enterprise fleets, direct e-commerce for home segments, and domestic assembly partnerships for India BIS-certified equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence across EPA Energy Star 3.0, EU Ecodesign circularity mandates, and China's GB standards is compressing product development cycles while fragmenting testing protocols, creating high-growth disruption for agile supply chain architects.
For Market Incumbents: Consolidate captive production of printhead components and ink formulation chemistry to defend consumables margin pools against third-party toner disintermediation. Deepen firmware engineering capabilities through targeted acquisition of embedded systems talent pools migrating from automotive sectors. Priority investment centers on circular design certification for EU market access.
For New Entrants and Emerging Players: Anchor in India's tier-two commercial corridors where BIS certification friction creates white space for domestic assembly partnerships with local electronics manufacturers. Target wide-format technical printing convergence spanning GIS mapping and architectural CAD output. Go-to-market angle emphasizes substrate versatility and per-page service unbundling.
For Investors and Strategic Acquirers: Long-term, this sits as a consumables-recurring-revenue play because replacement cycles for inks and toners exceed hardware profitability while resisting digital substitution in regulated documentation workflows. Acquisition targets include MEMS fabrication specialists with thermal inkjet array expertise and managed print services operators with NHS trust framework agreements. Signal to watch is firmware engineering salary inflation indicating talent scarcity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Printhead Fabrication | Captive MEMS production insulates against Taiwanese foundry single-source vulnerability. |
| EU Ecodesign Circularity Certification | Cartridge take-back compliance unlocks remanufacturing service revenue in German markets. |
| Domestic Assembly Partnership in India | BIS certification compliance through local electronics manufacturers reduces ISI marking friction. |
| Firmware Engineering Talent Acquisition | Embedded systems capability defends against automotive sector talent migration. |
| Managed Print Services Unbundling | Per-page service separation enables mixed-vendor fleet configurations in UK healthcare. |
Research Methodology
Desk research of SEC 10-K filings, EU Ecodesign regulatory databases, and China SAMR GB standard publications preceded structured interviews with OEM procurement directors, managed print services operators, and BIS certification consultants. Primary fieldwork with precision optics manufacturers in Baden-Württemberg and fuser assembly engineers in Dongguan validated secondary data on energy-efficiency redesign cycles. Bottom-up unit economics modeling triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across product type, consumable chemistry, technology architecture, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs derived from installed base replacement cycles, emerging market infrastructure buildout curves, and regulatory compliance-driven hardware refresh patterns. Industry-specific forecast inputs incorporated EPA Energy Star 3.0 federal procurement mandates and India's tier-two commercial corridor expansion trajectories.
Material uncertainties — styrene-acrylic copolymer price volatility, Taiwanese foundry capacity constraints, and document digitization substitution rates in Nordic enterprise sectors — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and healthcare documentation workflow persistence. Recalibration cycles align with material shifts in China's dual carbon goal implementation and MEMS fabrication capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Digital Pattern Generator Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Global Wireless Printers Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Large Format Printer Market
Printing Technology
Print on Demand Software Market
Printing Technology
Global Cloud Printing Services Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Web to Print Market
Printing Technology
Digital Paper System Market
Printing Technology
GCC Digital Printing Market
Printing Technology
RFID Printer Market
Printing Technology
Book Printing Service Market
Printing Technology
Industrial Printer Market