
 Vacuum Therapy Devices Market | 2026-2036
Vacuum Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Therapy Devices Market Analytics
The capital-intensity divergence between integrated wound-care conglomerates and specialized pump manufacturers is rotating competitive dynamics in vacuum therapy. Smith & Nephew leverages its global distribution infrastructure to sustain hospital contract dominance. Mölnlycke Health Care anchors Nordic procurement networks with advanced dressing portfolios. Cardinal Health competes through private-label flexibility and acute-care logistics scale.
Vacuum therapy devices apply controlled negative pressure to wound beds, dermal tissue, or vascular structures, typically operating at negative pressures between 50 and 125 mmHg to promote perfusion, granulation, or fluid extraction. Negative Pressure Wound Therapy occupies the largest revenue pool among product types due to established reimbursement and surgical volume correlation. Portable Systems within the technology dimension are expanding fastest as home care settings displace institutional recovery days. Electric Devices command premium positioning where continuous pressure modulation improves clinical outcomes in complex wounds.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for vacuum therapy manufacturers. Health Canada and TGA alignment with ISO 13485 quality management standards further conditions international expansion feasibility. Stakeholders must monitor reimbursement recalibration in home care channels as payors weigh cost-shifting against readmission risk metrics.
Market Dynamics
Portable electric systems are supplanting institutional stationary units as home care reimbursement expands and patients demand mobility during extended wound treatment protocols.
Growth Catalysts
- EU MDR compliance timelines:German hospitals are accelerating NPWT procurement ahead of 2027 certification deadlines, creating concentrated demand for validated pump systems.
- Home care infrastructure:Japan's Ministry of Health has expanded at-home wound care coverage, directly stimulating portable device deployment by regional distributors.
- Polyurethane foam dressing integration:Advanced interface materials now enable seven-day wear cycles, reducing nursing visit frequency and total episode costs.
Market Restraints
- Silicone pressure sensor volatility:Input costs for precision transducers fluctuate with semiconductor foundry capacity, squeezing margins on mid-tier electric pumps.
- Single-source canister supply:Molded plastic waste collection systems concentrate among three Southeast Asian contract manufacturers, exposing OEMs to port congestion risk.
- Antibiotic-impregnated dressing substitution:Silver sulfadiazine alternatives compete for chronic wound cases where infection control outweighs exudate management.
Strategic Opportunities
- Australian remote care networks:Outback telehealth infrastructure lacks wound specialist coverage, creating whitespace for connected NPWT systems with remote pressure monitoring.
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import duty exposure for pump assembly operations targeting price-sensitive institutional buyers.
- Sensor-embedded dressing convergence:Integration of pH and temperature microsensors with negative pressure platforms enables predictive debridement scheduling.
Industry Challenges
- Bioengineered tissue interface expertise:Scarce talent in hydrogel-chemistry formulation delays next-generation dressing launches by 18-24 months.
- ISO 13485 certification backlog:Notified body queue congestion extends quality management audits, freezing product registrations for emerging manufacturers.
- Legacy EMR integration complexity:Proprietary pump data protocols require middleware development for hospital network connectivity, raising deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Therapy Devices Market |
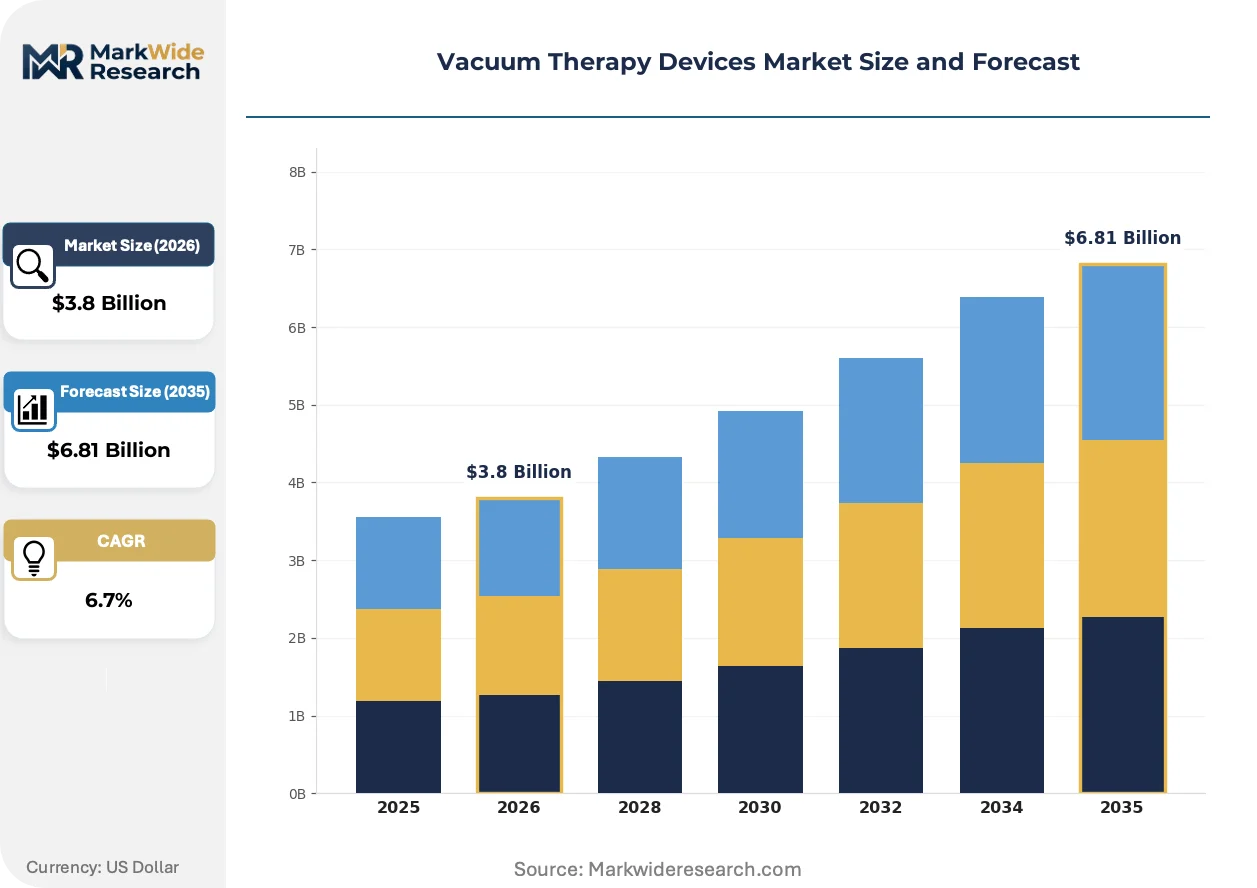
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Negative Pressure Wound Therapy, Erectile Dysfunction Devices, Autologous Blood Therapy, Lymphedema Pumps End User: Hospitals, Home Care Settings, Rehabilitation Centers, Clinics Application: Wound Care, Sexual Health, Oncology, Physiotherapy Technology: Mechanical Devices, Electric Devices, Disposable Units, Portable Systems |
| Companies Covered | Smith & Nephew PLC, 3M Company (Acelity), Mölnlycke Health Care, Cardinal Health, Coloplast Corp, Boston Scientific Corporation, ConvaTec Group Plc, DeRoyal Industries Inc., Medela AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Therapy Devices Market Evolving Landscape
Device miniaturization and wireless connectivity are compressing the boundary between acute and post-acute care settings, enabling continuous therapy across fragmented care journeys.
Battery chemistry advances are supplanting tethered power dependence in NPWT systems. Lithium-polymer cells now sustain 72-hour negative pressure delivery in canister-integrated dressings. Home health agencies in Scandinavia are adopting these untethered configurations for mobility-dependent patients. The technology is supplanting rental-based pump economics with single-use disposable models that eliminate reverse logistics.
EU MDR technical documentation requirements are forcing systematic clinical evidence regeneration for legacy pump portfolios. Manufacturers must resubmit biological safety and electromagnetic compatibility data under str notified body scrutiny. German wound care suppliers are absorbing 15-20% regulatory affairs cost inflation to maintain CE marking, compressing R&D budgets for feature innovation.
Hospital procurement committees are unbundling device acquisition from consumable supply contracts. IDN sourcing teams now negotiate pump hardware separately from dressing and canister replenishment, reversing decade-old bundled pricing structures. This disintermediation is most visible in US academic medical centers where GPO leverage has fragmented vendor lock-in strategies.
Vacuum Therapy Devices Market Segmentation
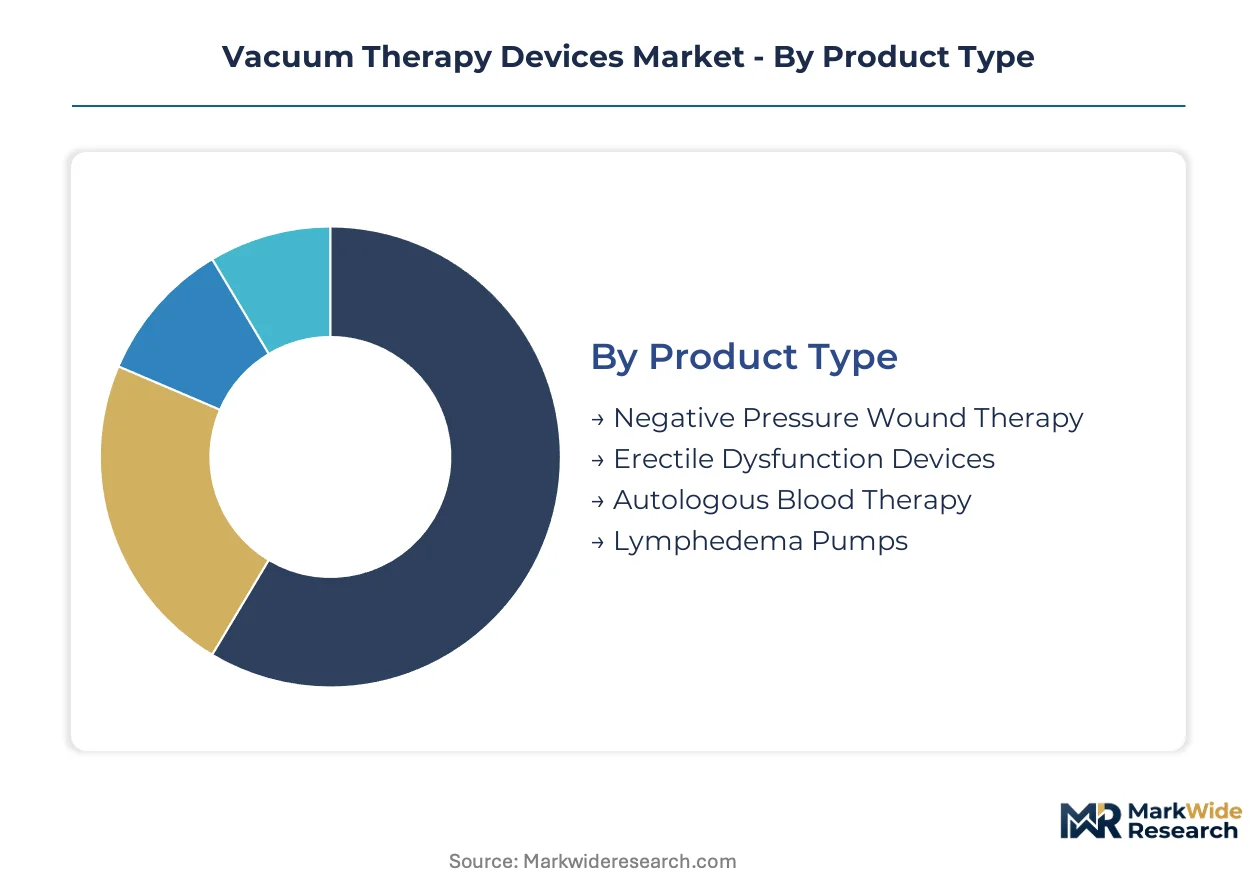
Segmentation in vacuum therapy devices reveals divergent margin profiles across clinical applications and care settings. Product architecture, power source, and reimbursement eligibility create distinct competitive battlegrounds for manufacturers and distributors.
Product Type:
Premium margin pools concentrate in segments with consumable attachment rates and chronic use protocols.
- Negative Pressure Wound Therapy:Systems apply sustained sub-atmospheric pressure to wound beds through sealed foam or gauze interfaces, typically operating between 50-125 mmHg. German hospitals under EU MDR compliance deadlines are accelerating procurement of validated NPWT pumps, while Japan's expanded home care coverage drives portable system demand. The dominant share belongs to Negative Pressure Wound Therapy, while Erectile Dysfunction Devices are closing the gap fastest.
- Erectile Dysfunction Devices:Vacuum constriction systems draw blood into penile tissue via cylindrical chambers with constriction ring transfer. Direct-to-consumer channels and telehealth prescribing in Australia and North America are displacing traditional urology clinic distribution.
- Autologous Blood Therapy:Platelet-rich plasma extraction systems concentrate autologous growth factors for orthopedic and aesthetic reinjection.
- Lymphedema Pumps:Sequential pneumatic compression devices mobilize interstitial fluid in extremity lymphedema management.
NPWT hardware generates recurring revenue through proprietary canister and dressing lock-in, while sexual health devices compete on upfront price transparency.
End User:
Procurement authority and reimbursement pathways determine pricing power across institutional and decentralized care nodes.
- Hospitals:Integrated delivery networks negotiate multi-year pump fleet contracts with bundled consumable replenishment, though disintermediation trends are separating hardware from supply purchasing.
- Home Care Settings:Battery-integrated portable systems eliminate rental reverse logistics and enable patient mobility during extended treatment. Scandinavian home health agencies are adopting single-use disposable NPWT configurations for mobility-dependent patients, with lithium-polymer cells now sustaining 72-hour pressure delivery.
- Rehabilitation Centers:Outpatient lymphedema and wound programs require durable equipment with high duty cycles.
- Clinics:Physician office-based procedures favor compact tabletop units with minimal training requirements.
Home Care Settings command the steepest expansion trajectory as payors shift recovery days from institutional to residential environments.
Application:
Clinical evidence density and regulatory clearance complexity shape market access economics across therapeutic domains.
- Wound Care:Chronic diabetic foot ulcers, pressure injuries, and surgical site management drive the majority of installed pump base. FDA 510(k) clearance pathways and EU MDR technical documentation requirements extend development timelines for novel dressing interfaces.
- Sexual Health:Erectile dysfunction treatment competes with pharmaceutical alternatives on convenience and side-effect profiles.
- Oncology:Head and neck surgical reconstruction and radiation-induced wound complications create specialized NPWT protocols.
- Physiotherapy:Cupping and myofascial decompression applications utilize lower-pressure mechanical systems with minimal regulatory burden.
Wound Care maintains the largest addressable patient population, while Sexual Health applications are gaining share through direct-channel consumerization.
Technology:
Power architecture and disposability determine unit economics and competitive moat durability.
- Portable Systems:Miniaturized negative pressure pumps with integrated canisters and battery power enable ambulatory therapy across care transitions. Australian remote care networks lacking wound specialist coverage present whitespace for connected NPWT with remote pressure monitoring capabilities.
- Electric Devices:Microprocessor-controlled pressure modulation with continuous or intermittent algorithms improves perfusion in complex wounds. Silicone pressure sensor input cost volatility from semiconductor foundry capacity constraints squeezes margins on mid-tier pump models.
- Mechanical Devices:Hand-powered or spring-loaded vacuum generation serves cost-sensitive markets with minimal infrastructure.
- Disposable Units:Single-use negative pressure systems eliminate cross-contamination risk and capital equipment depreciation.
Electric Devices retain the dominant technology position, though Portable Systems are expanding most quickly through home care reimbursement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German hospital procurement networks while Australian home care channels absorb margin compression from portable device commoditization. This asymmetry reflects divergent reimbursement architectures and regulatory compliance cost allocation across developed markets.
Germany
EU MDR compliance deadlines through 2027 are accelerating NPWT pump procurement in university hospitals across Bavaria and North Rhine-Westphalia. The Federal Institute for Drugs and Medical Devices (BfArM) mandates renewed technical documentation for legacy devices, compressing supplier margins by 15-20% while validating market access. Berlin-Brandenburg clusters host notified body audit queues that freeze product registrations for emerging manufacturers seeking CE marking.
United States
Academic medical centers in the Northeast Corridor and California are disintermediating bundled device-consumable contracts through GPO leverage. FDA 510(k) clearance pathways shape development timelines for novel dressing interfaces. The Pacific Northwest and Greater Boston regions concentrate telehealth-integrated NPWT deployment for rural wound specialist coverage.
Japan
Metropolitan Tokyo and Osaka prefectures drive portable electric system demand as the Ministry of Health expands at-home wound care reimbursement. PMDA alignment with ISO 13485 quality management standards conditions international expansion feasibility for domestic manufacturers. Kansai region distributors are capturing preference in home care segments through battery-integrated disposable configurations.
Australia
Remote care networks across Western Australia and Queensland lack wound specialist coverage, creating whitespace for connected NPWT systems with remote pressure monitoring. TGA regulatory alignment with ISO standards enables faster market entry for validated pump systems. New South Wales and Victoria home health agencies are adopting single-use disposable models that eliminate reverse logistics.
India
Maharashtra and Gujarat medical device clusters are leveraging PLI scheme incentives to reduce import duty exposure for pump assembly operations targeting price-sensitive institutional buyers. CDSCO regulatory pathways extend development timelines for novel interfaces. Karnataka and Tamil Nadu distribution networks are capturing regional hospital procurement through cost-competitive mechanical device portfolios.
Vacuum Therapy Devices Market Competitive Landscape
Concentration sits with integrated wound-care conglomerates that leverage global distribution infrastructure and advanced dressing portfolios to sustain hospital contract dominance. Specialized pump manufacturers compete through private-label flexibility and acute-care logistics scale. Three archetypes define competitive positioning: diversified medical technology conglomerates with NPWT as a vertical within broader wound care portfolios; specialized negative pressure device manufacturers with concentrated R&D in pressure modulation algorithms; and contract manufacturing organizations supplying molded plastic canisters and sensor components to branded OEMs. M&A activity targets sensor-embedded dressing convergence capabilities, while geographic expansion focuses on India's PLI scheme manufacturing incentives.
Among UK-based diversified medical technology conglomerates, Smith & Nephew PLC exemplifies the integrated wound-care archetype with global distribution infrastructure. Within the specialized pump manufacturer tier, Mölnlycke Health Care and Cardinal Health occupy positions defined by Nordic procurement network anchoring and private-label flexibility respectively. These three entities represent the competitive tension between bundled portfolio depth and unbundled hardware sourcing that hospital procurement committees now exploit.
| Leading Market Players |
|---|
| Smith & Nephew PLC |
| 3M Company (Acelity) |
| Mölnlycke Health Care |
| Cardinal Health |
| Coloplast Corp |
| Boston Scientific Corporation |
| ConvaTec Group Plc |
| DeRoyal Industries Inc. |
| Medela AG |
| Others |
Value Network & Pricing Analysis
Ninety-day silicone pressure sensor lead times from semiconductor foundries compress margin buffers on mid-tier electric pumps while amplifying pricing power for integrated manufacturers with captive component stocks. This inventory tension feeds directly into procurement committee leverage during German hospital contract renewals.
Pricing Analysis
Configured-to-order pricing for EU MDR-validated pump systems commands spreads against standard portable units, with premium tiers anchored by FDA 510(k) clearance status and ISO 13485 certification grade. Contract-based long-term offtake dominates hospital IDN procurement, while spot purchasing persists in Australian home care channels. Price differentiation stems from electromagnetic compatibility documentation depth and after-sales service bundling. Cost compression in mechanical device tiers is intensifying because India's PLI scheme enables domestic assembly price competition. Price sensitivity concentrates among Maharashtra district hospital buyers, while German university hospitals prioritize compliance validation over unit economics.
Supply Chain Analysis
Malaysia, Vietnam, and Thailand anchor molded plastic canister production for Southeast Asian contract manufacturers serving branded OEMs. Silicone pressure sensors, lithium-polymer battery cells, and polyurethane foam dressings constitute critical input dependencies. Single-source vulnerability concentrates in three canister molders exposed to port congestion risk. Distribution runs through regional distributors in Kansai and Nordic procurement networks, with GPO intermediation fragmenting in US academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in bioengineered hydrogel-chemistry formulation talent delays next-generation dressing launches, constraining competitive response velocity for specialized pump manufacturers against integrated wound-care conglomerates.
For Market Incumbents: Fortify CE marking validation investments ahead of BfArM audit queue congestion, while deepening backward integration into polyurethane foam dressing production to offset proprietary canister supply concentration. Antibiotic-impregnated dressing substitution threats from silver sulfadiazine alternatives demand accelerated sensor-embedded interface R&D to sustain consumable attachment rates. For New Entrants and Emerging Players: Health Canada ISO 13485 alignment fast-tracks market entry for validated portable systems targeting Australian remote care networks lacking wound specialist coverage. India's PLI scheme manufacturing incentives present the most penetrable white-space for price-sensitive institutional buyers in Gujarat and Tamil Nadu. Telehealth-integrated remote pressure monitoring capabilities offer differentiated go-to-market positioning against legacy pump protocols. For Investors and Strategic Acquirers: Long-term, this sits as a reimbursement-arc play because home care infrastructure expansion across Japan and Australia structurally shifts episode economics toward portable disposable configurations. Acquisition targets should concentrate on sensor-embedded dressing convergence capabilities with pH and temperature microsensor integration. The signal to watch is EU MDR technical documentation cost absorption rates among mid-tier specialized manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance deadlines through BfArM validation secure German hospital contract renewals. |
| Hospital System Partnership | IDN procurement committee disintermediation demands unbundled hardware-consumable negotiation strategies. |
| Software Companion Development | Remote pressure monitoring integration addresses Australian Outback telehealth infrastructure gaps. |
| Reimbursement Strategy | Japan Ministry of Health at-home coverage expansion directly stimulates portable device deployment. |
| FDA Submission | 510(k) clearance pathways shape development timelines for novel dressing interface innovations. |
Research Methodology
Two parallel data streams informed the analysis: structured dialogues with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists; and secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up installed base modeling triangulated against top-down wound care episode volume projections.
Across the projection horizon, the analytical framework segmented by product architecture, power source technology, reimbursement eligibility tier, and regional regulatory cluster. CAGRs derived from surgical volume correlation analysis and home care day-shift elasticities. Forecast inputs incorporated silicone pressure sensor foundry capacity constraints and lithium-polymer cell chemistry advancement trajectories.
Underlying assumptions cover EU MDR certification timeline adherence and home care reimbursement stability, with deviation risk concentrated in notified body audit queue extensions and semiconductor foundry allocation shocks. Recalibration cycles align with material shifts in regulatory compliance cost structures and portable device commoditization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Global Therapeutic Plasma Exchange Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Therapeutic Bed Market