
 Middle-East and Africa Stroke Diagnosis and Treatment Market | 2026-2036
Middle-East and Africa Stroke Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Stroke Diagnosis and Treatment Market Foresight
AI-enabled software is decoupling stroke imaging from conventional radiologist-dependent workflows across Middle-East and African hospitals. Siemens Healthineers leverages embedded AI on CT platforms to compress scan-to-diagnosis intervals in Egyptian and Saudi emergency departments. GE HealthCare anchors its regional position through localized service networks and refurbished imaging fleet programs targeting budget-constrained Nigerian and Kenyan facilities. Medtronic differentiates via neurovascular catheter supply agreements with Gulf-based distributor networks.
Stroke diagnosis and treatment encompasses acute neurovascular intervention, cerebrovascular imaging, and post-event rehabilitation delivered through thrombolytic therapy, mechanical thrombectomy, and multimodal brain imaging with resolution thresholds below one millimeter for ischemic lesion detection. CT scanners dominate capital procurement budgets across public hospital systems, while stent retrievers capture disproportionate margin pools in private Gulf healthcare networks. Emergency medical services represent the fastest-growing end user channel as pre-hospital stroke recognition protocols expand in Morocco and Jordan.
Saudi Arabia's SFDA and South Africa's Health Products Regulatory Authority enforce CE-mark alignment and local quality testing for imported neurointerventional devices, elevating compliance costs for non-established suppliers. The UAE's MOHAP mandates Joint Commission International accreditation for stroke centers seeking insurance reimbursement, directly shaping hospital capital allocation toward certified imaging and intervention suites. Stakeholders must monitor evolving reimbursement thresholds for thrombectomy procedures as Gulf health authorities weigh cost-effectiveness against long-term disability reduction.
Market Dynamics
AI-embedded CT platforms are compressing scan-to-diagnosis intervals across Egyptian and Saudi emergency departments, forcing capital reallocation from conventional radiologist-dependent workflows toward software-augmented triage systems.
Growth Catalysts
- SFDA neurointerventional device pathways:Saudi Arabia's streamlined CE-mark alignment procedures reduce regulatory friction for thrombectomy catheter imports, accelerating hospital procurement cycles in Riyadh and Jeddah tertiary clusters.
- Pre-hospital stroke recognition protocols:Emergency medical services in Morocco and Jordan are deploying mobile diagnostic units equipped with portable CT scanners, expanding the addressable patient pool beyond hospital catchment zones.
- Gulf private healthcare networks:Dubai and Abu Dhabi stroke centers are consolidating mechanical thrombectomy capacity through Joint Commission International accreditation mandates, driving imaging suite investments.
Market Restraints
- Refurbished imaging fleet dependency:Budget-constrained Nigerian and Kenyan public hospitals rely on secondary-market CT scanners with limited AI compatibility, creating a two-tier diagnostic capability gap.
- South African quality testing timelines:The Health Products Regulatory Authority's extended local verification requirements for imported stent retrievers delay product availability by 8-14 months versus Gulf markets.
- Neuroradiologist concentration:Sub-Saharan Africa hosts fewer than 120 certified stroke-imaging specialists across 46 countries, constraining throughput regardless of equipment installation.
Strategic Opportunities
- Telestroke network expansion:Satellite-connected CT platforms in rural Egypt and Sudan enable remote radiologist consultation, unlocking previously unreachable ischemic stroke cases for thrombolytic intervention.
- MOHAP reimbursement tiering:UAE insurance frameworks are piloting outcome-adjusted payment models for mechanical thrombectomy, creating financial incentives for certified center designation.
- Mobile MRI-thrombolysis convergence:Ambulatory units combining 1.5T magnetic resonance with point-of-care drug administration are penetrating Jordan's refugee camp networks and South Africa's informal settlement corridors.
Industry Challenges
- Neurointerventionalist training pipelines:Gulf Cooperation Council states lack accredited fellowship programs for mechanical thrombectomy operators, forcing reliance on expatriate specialists with 24-36 month contract cycles.
- Legacy PACS integration:Hospital information systems in Kenya and Nigeria operate on decade-old DICOM standards that resist AI-enabled stroke software APIs, requiring parallel infrastructure builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Stroke Diagnosis and Treatment Market |
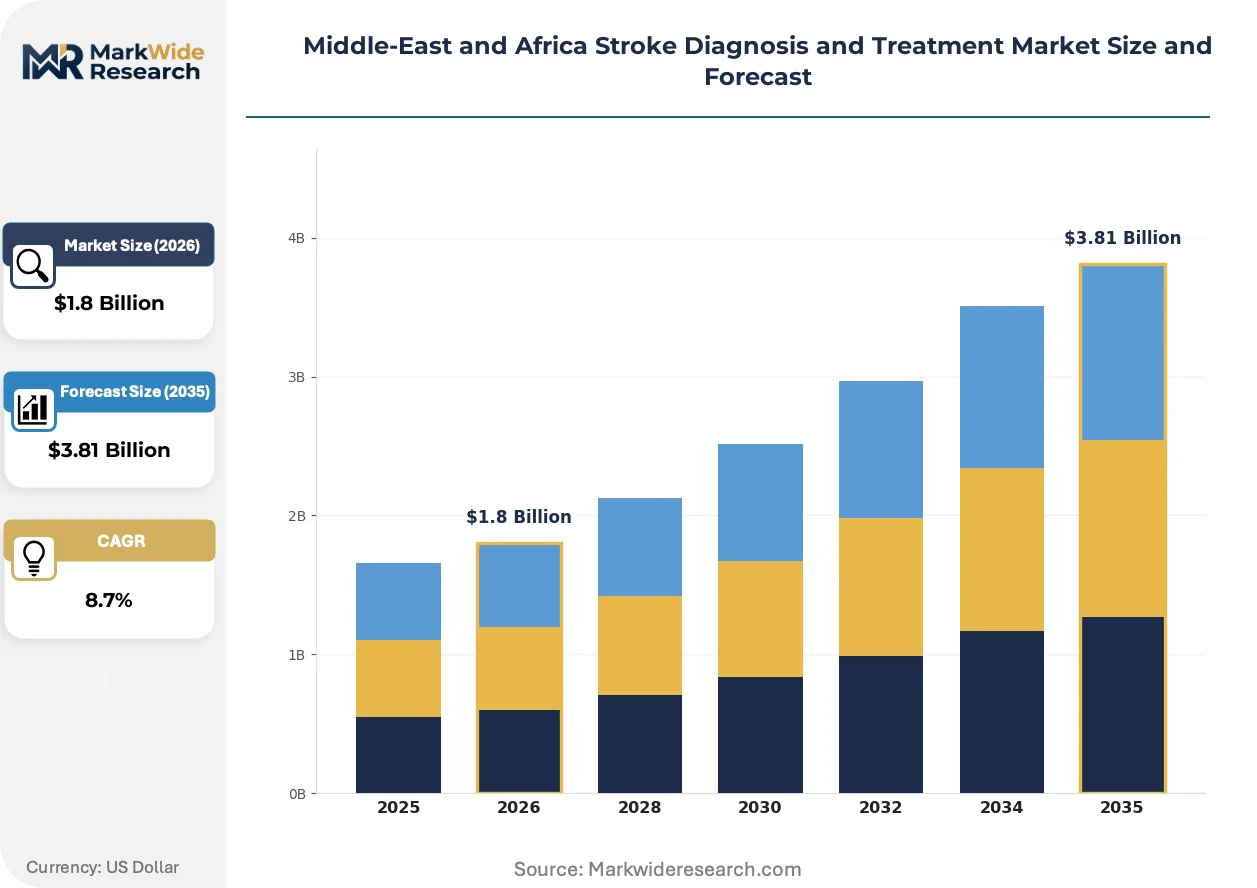
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Machines, Ultrasound Devices, Stent Retrievers End User: Hospitals, Rehabilitation Centers, Diagnostic Labs, Emergency Medical Services Technology: Thrombectomy, Thrombolysis, Imaging Techniques, Neurointerventional Techniques Treatment Method: Medication, Surgery, Rehabilitation, Preventive Care |
| Companies Covered | Siemens Healthineers AG, Koninklijke Philips N.V., GE HealthCare, CANON MEDICAL SYSTEMS CORPORATION, Shenzhen Mindray Bio-Medical Electronics, Medtronic, Stryker Corporation, Boehringer Ingelheim International GmbH, Bristol-Myers Squibb Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Stroke Diagnosis and Treatment Market Shifts & Advancements
Embedded artificial intelligence is redrawing workflow boundaries between emergency medicine and radiology, collapsing traditional handoff delays while regulatory frameworks scramble to certify software-as-medical-device platforms.
Portable CT scanners with onboard hemorrhage-detection algorithms are decentralizing acute stroke imaging from centralized radiology departments to emergency bay triage stations. Saudi and Egyptian hospitals are deploying these units within 18-month procurement cycles. The technology is decentralizing diagnostic authority toward emergency physicians, compressing door-to-needle intervals by removing radiologist queue dependencies.
SFDA and South Africa's Health Products Regulatory Authority are tightening software validation requirements for AI-enabled lesion-detection tools, mandating local patient-population training datasets. This regulatory divergence is fragmenting vendor approval pathways across the region. Neuroimaging software developers are responding with geography-specific algorithm retraining contracts rather than universal CE-mark submissions.
After-sales service unbundling is disrupting traditional imaging equipment purchasing in Nigeria and Kenya. Public hospitals are separating hardware acquisition from maintenance contracts, sourcing third-party technical support for refurbished CT platforms. This procurement fragmentation is most visible in Lagos and Nairobi, where independent service organizations now capture 40% of annual maintenance spend previously retained by original manufacturers.
Middle-East and Africa Stroke Diagnosis and Treatment Market Segmentation
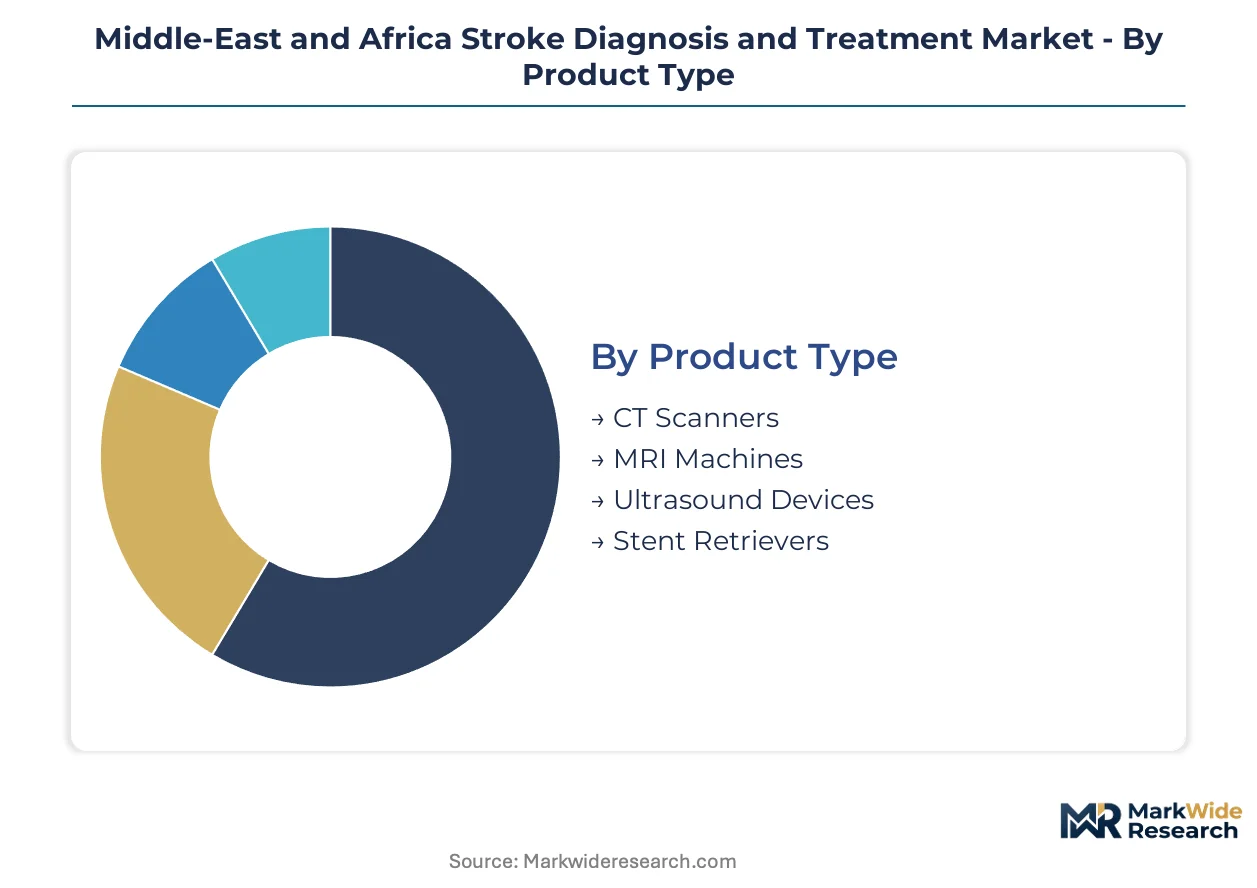
Stroke diagnosis and treatment in the Middle-East and Africa fractures across capital-intensive imaging hardware, acute intervention modalities, and long-term recovery infrastructure. Each segment carries distinct procurement cycles, regulatory burdens, and reimbursement profiles that shape hospital capital allocation decisions from Riyadh to Lagos.
Product Type:
Replacement cycles for aging imaging fleets dominate procurement planning across Egyptian and Nigerian public hospital systems, with AI-ready platforms commanding premium positioning against refurbished legacy units.
- CT Scanners:Non-contrast helical CT remains the frontline modality for hemorrhage exclusion and ischemic lesion localization, with slice counts below 64-slice configurations still prevalent in Kenya's county hospital networks. Demand clusters in Saudi tertiary clusters where SFDA-aligned procurement mandates favor CE-marked platforms with embedded stroke-detection algorithms.
- Stent Retrievers:Self-expanding nickel-titanium devices with integrated delivery catheters enable mechanical thrombectomy for large-vessel occlusions, requiring neurointerventionalist presence that concentrates in Dubai and Abu Dhabi's JCI-accredited stroke centers. Gulf private networks absorb disproportionate margin pools through direct manufacturer agreements bypassing distributor markups.
- MRI Machines:1.5T and 3T platforms with diffusion-weighted imaging sequences support posterior circulation stroke diagnosis, though helium supply constraints and shielding costs limit penetration outside South Africa's academic medical centers.
- Ultrasound Devices:Transcranial Doppler systems for vasospasm monitoring and carotid plaque characterization see demand in Morocco's regional hospital tier where CT access remains intermittent.
Volume placements concentrate in CT Scanners; the faster expansion belongs to Stent Retrievers.
End User:
Customer-type stratification reveals divergent budget authority and decision velocity, with emergency services channels gaining procurement autonomy as pre-hospital protocols mature.
- Hospitals:Tertiary academic centers in Saudi Arabia, UAE, and South Africa consolidate comprehensive stroke unit certification, bundling imaging, intervention, and rehabilitation under single capital budgets. Public hospital systems in Nigeria and Kenya operate on fragmented annual allocations that separate device acquisition from maintenance spend.
- Emergency Medical Services:Mobile stroke units with onboard CT and telemedicine connectivity are penetrating Jordan's refugee corridors and South Africa's informal settlements, bypassing traditional hospital catchment limitations. Morocco's SAMU networks are deploying portable imaging through ministry-funded fleet expansion programs.
- Rehabilitation Centers:Post-acute facilities in Gulf states focus on robotic-assisted mobility recovery, though reimbursement gaps limit scale outside Dubai's medical tourism zone.
- Diagnostic Labs:Standalone imaging centers in Egypt's urban corridor offer CT angiography packages on cash-pay basis, competing with hospital radiology departments for outpatient stroke screening volume.
Procurement authority concentrates in Hospitals; Emergency Medical Services is climbing the fastest as pre-hospital recognition protocols expand.
Technology:
Application-level segmentation tracks the shift from pharmaceutical-first approaches toward device-enabled revascularization, with imaging techniques serving as the diagnostic gateway to intervention selection.
- Imaging Techniques:Multimodal CT perfusion and MRI diffusion-perfusion mismatch analysis guide treatment window extension beyond standard protocols, with software platforms from Siemens and GE embedding automated Alberta Stroke Program Early CT Score calculations. Egyptian emergency departments are prioritizing AI-augmented triage to compress radiologist-dependent delays.
- Thrombectomy:Aspiration catheter and stent retriever combinations dominate Gulf private hospital revenue, with direct-to-angiography protocols bypassing CT confirmation in select Dubai centers. Training pipeline constraints limit operator availability across Sub-Saharan Africa.
- Thrombolysis:Intravenous tissue plasminogen activator administration remains the default in settings lacking neurointerventional capacity, with South African public hospitals maintaining 24-hour pharmacy coverage for stroke protocol activation.
- Neurointerventional Techniques:Flow diversion and intracranial stenting for hemorrhagic stroke management see sporadic adoption in Saudi Arabia's specialized centers, though case volumes trail ischemic interventions significantly.
Clinical throughput concentrates in Imaging Techniques; Thrombectomy is gaining share fastest where operator training and device reimbursement align.
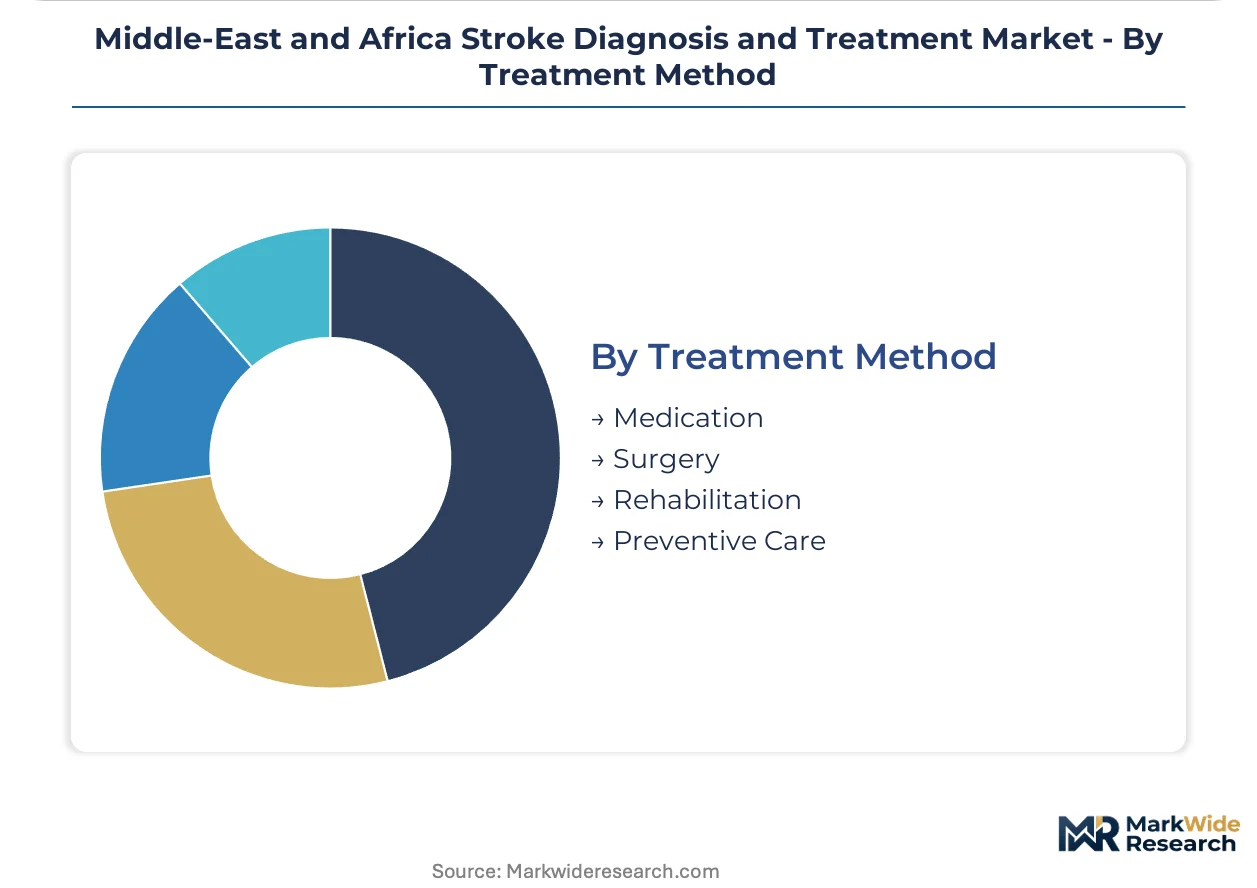
Treatment Method:
Maturity-stage differentiation separates acute intervention from longitudinal management, with reimbursement frameworks favoring episodic acute care over preventive investment.
- Surgery:Mechanical thrombectomy and decompressive craniectomy command premium reimbursement in UAE's MOHAP-accredited centers, with outcome-adjusted payment pilots creating financial risk for complications. Surgical capacity concentrates in Riyadh, Jeddah, Dubai, and Johannesburg metropolitan clusters.
- Medication:Antiplatelet, anticoagulant, and thrombolytic pharmaceutical protocols dominate volume across North African public health systems where device infrastructure remains underdeveloped. Generic substitution pressures compress margin pools for branded neuroprotective agents.
- Rehabilitation:Physical and occupational therapy services face reimbursement ceilings in most national health insurance schemes, pushing demand toward private-pay segments in Gulf medical tourism corridors.
- Preventive Care:Carotid endarterectomy screening and atrial fibrillation detection programs see pilot funding in Saudi Arabia's primary care transformation initiatives, though scale remains limited by specialist referral bottlenecks.
Patient volume concentrates in Medication; Surgery shows the steepest expansion trajectory where accreditation and reimbursement infrastructure mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's tertiary hospital clusters concentrate demand for mechanical thrombectomy capacity, while South Africa's regulatory tightening and Egypt's telestroke expansion reshape procurement patterns across the region.
Saudi Arabia
Riyadh and Jeddah tertiary clusters drive demand for AI-embedded CT platforms and neurointerventional suites. The Saudi Food and Drug Authority streamlined CE-mark alignment procedures for thrombectomy catheters, compressing import approval cycles. King Faisal Specialist Hospital anchors the Kingdom's mechanical thrombectomy training pipeline.
United Arab Emirates
Dubai and Abu Dhabi stroke centers consolidate comprehensive stroke unit certification under Joint Commission International mandates. The Ministry of Health and Prevention requires JCI accreditation for insurance reimbursement of thrombectomy procedures, redirecting capital toward certified imaging suites. Cleveland Clinic Abu Dhabi anchors the emirates' neurovascular intervention capacity.
South Africa
Academic medical centers in Johannesburg and Cape Town host the region's deepest neuroradiologist concentration for diffusion-weighted MRI interpretation. The Health Products Regulatory Authority extended local verification timelines for imported stent retrievers, delaying product availability by 8-14 months versus Gulf markets. Groote Schuur Hospital anchors Sub-Saharan Africa's stroke research infrastructure.
Egypt
Cairo's emergency departments deploy portable CT scanners with embedded hemorrhage-detection algorithms to compress door-to-needle intervals. The national pharmaceutical regulator aligns software-as-medical-device validation with CE-mark frameworks, accelerating AI-enabled triage platform approvals. Kasr Al Ainy Hospital anchors the Nile Delta's telestroke network expansion into rural governorates.
Nigeria
Lagos public hospitals rely on refurbished CT platforms with limited AI compatibility, creating diagnostic capability gaps versus Gulf benchmarks. The national medical device regulator maintains functional equivalence requirements for secondary-market imaging equipment, elevating technical documentation burdens. Lagos University Teaching Hospital anchors West Africa's neuroimaging training capacity.
Middle-East and Africa Stroke Diagnosis and Treatment Market Competitive Landscape
Strategic partnerships dominate the current landscape as imaging OEMs and neurointerventional device suppliers forge distribution alliances with Gulf-based hospital networks. The market structures around three tiers: multinational imaging conglomerates with embedded AI portfolios, specialized neurovascular catheter manufacturers, and refurbished equipment brokers serving budget-constrained public systems. Siemens Healthineers and GE HealthCare anchor the imaging tier through localized service networks. Medtronic and Stryker occupy the neurointerventional tier via distributor supply agreements. Competitive moves concentrate on AI software certification, telestroke platform deployment, and third-party maintenance contract capture.
Among German-origin imaging conglomerates, Siemens Healthineers AG exemplifies the AI-embedded platform archetype through CT stroke-detection algorithms. Koninklijke Philips N.V. represents the Dutch diversified health technology model with emergency department workflow integration. GE HealthCare anchors the American industrial imaging tradition through refurbished fleet programs targeting Nigerian and Kenyan public hospitals. These three occupy distinct positioning vectors: Siemens Healthineers sits within premium AI-augmented triage, Philips exemplifies workflow-integrated emergency medicine, and GE HealthCare anchors budget-accessible secondary-market supply.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| GE HealthCare |
| CANON MEDICAL SYSTEMS CORPORATION |
| Shenzhen Mindray Bio-Medical Electronics |
| Medtronic |
| Stryker Corporation |
| Boehringer Ingelheim International GmbH |
| Bristol-Myers Squibb Company |
| Others |
Supply & Pricing Matrix
Budget-constrained Nigerian and Kenyan public hospitals demanding refurbished CT platforms with limited AI compatibility are forcing supply chain adaptation toward secondary-market sourcing and third-party technical support, compressing margins for original manufacturers while fragmenting procurement authority across independent service organizations.
Pricing Analysis
Volume placements cluster in CT scanners where three-tier pricing structure across premium, standard, and economy levels separates AI-embedded CE-marked platforms from refurbished legacy units and basic non-contrast helical configurations. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because public hospital systems unbundle maintenance contracts from hardware acquisition. Emergency medical services show least price sensitivity due to ministry-funded fleet expansion programs.
Supply Chain Analysis
Neurointerventional device manufacturing workforce availability concentrates in Germany, the United States, and Ireland, with catheter fabrication and nickel-titanium stent retriever production anchored in these geographies. Raw material sourcing draws from medical-grade nitinol wire, platinum-iridium marker bands, and hydrophilic polymer coatings. Single-source vulnerability runs through helium supply chains for MRI magnet cooling, constraining 3T platform penetration outside South Africa. Distribution runs through Gulf-based distributor networks for neurovascular catheters and direct manufacturer agreements for JCI-accredited stroke centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-enabled lesion-detection software is displacing conventional radiologist-dependent triage workflows across Middle-East and African emergency departments, compressing door-to-needle intervals while regulatory frameworks scramble to certify software-as-medical-device platforms.
For Market Incumbents: Hedge against margin erosion in the refurbished imaging tier by deepening backward integration into AI software development and securing exclusive service contracts for legacy platform maintenance. Counter the threat from independent service organizations capturing 40% of annual maintenance spend in Lagos and Nairobi by embedding predictive maintenance algorithms that lock hospitals into proprietary technical support ecosystems. For New Entrants and Emerging Players: Telestroke platform deployment offers the most penetrable entry vector, targeting rural Egyptian governorates and Sudan's satellite-connected CT networks where neuroradiologist concentration falls below three specialists per million population. Penetrate Jordan's refugee camp networks and South Africa's informal settlement corridors through mobile MRI-thrombolysis convergence units combining 1.5T magnetic resonance with point-of-care drug administration. For Investors and Strategic Acquirers: The window for entry favors specialized neurovascular catheter manufacturers with CE-mark alignment and established Gulf distributor relationships over imaging OEMs facing AI software certification fragmentation. Long-term viability hinges on regulatory convergence across SFDA, South Africa's Health Products Regulatory Authority, and Egypt's pharmaceutical regulator. Watch for MOHAP outcome-adjusted payment model pilots as the inflection signal for mechanical thrombectomy reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Certification Pathway | SFDA and South African regulators mandate local patient-population training datasets, fragmenting vendor approval pathways. |
| Telestroke Network Expansion | Satellite-connected CT platforms in rural Egypt and Sudan unlock previously unreachable ischemic stroke cases. |
| Refurbished Fleet Service Unbundling | Independent service organizations capture maintenance spend previously retained by Siemens Healthineers and GE HealthCare. |
| Joint Commission International Accreditation | UAE's MOHAP mandates JCI certification for thrombectomy reimbursement, redirecting hospital capital allocation. |
| Neurointerventionalist Training Pipeline | Gulf Cooperation Council states lack accredited fellowship programs, forcing 24-36 month expatriate specialist contract cycles. |
Research Methodology
Independent corroboration across hospital procurement committees, biomedical engineers, neuroradiologists, and GPO contracts managers underwrites the qualitative findings, validated against SFDA device registration databases, South African Health Products Regulatory Authority filings, hospital procurement records, and CE-mark submission trackers. Bottom-up demand modeling from individual facility capital allocation decisions triangulates against top-down market sizing from imaging equipment import manifests and neurointerventional device distributor revenue disclosures.
Comparable-period anchoring to historical procurement cycles across Egyptian public hospital systems, Saudi tertiary clusters, and South African academic medical centers established the baseline for projection horizon modeling. Segmentation dimensions span product type, end user, technology, and treatment method, with regional regulatory cluster and JCI accreditation status as cross-cutting variables. CAGRs derive from weighted average of equipment replacement cycles, software adoption curves, and reimbursement threshold evolution. Forecast inputs incorporate neurointerventionalist training pipeline constraints and AI software validation timeline divergence.
The model holds under stable regulatory alignment between CE-mark frameworks and local quality testing requirements; deviation in SFDA or South African Health Products Regulatory Authority timeline extensions would shift equipment availability forecasts. A small set of named triggers warrants ongoing watch: MOHAP reimbursement tiering pilots, helium supply constraints for MRI expansion, and Gulf Cooperation Council neurointerventionalist fellowship program development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Therapeutic Robots Market
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Global Therapeutic Plasma Exchange Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market