
 Hospital Stretchers Market | 2026-2036
Hospital Stretchers Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Stretchers Market Intelligence
Ambulance services are rotating toward higher-specification stretcher procurement as pre-hospital care protocols tighten. Stryker Corporation leverages its integrated manufacturing scale across North American distribution networks. Hill-Rom Holdings Inc. anchors premium positioning through intensive R&D in powered transport systems. Narang Medical Limited competes on cost-engineered manual platforms for emerging market tenders.
Hospital stretchers are wheeled patient support platforms, typically constructed from aluminum or steel frames with polyurethane or vinyl-coated surfaces, designed to transport immobilized patients across clinical environments. Electric stretchers now command the fastest expansion within product type segmentation as hospitals automate workflow and reduce staff injury exposure. In application terms, emergency care absorbs disproportionate capital allocation due to throughput intensity and regulatory scrutiny, while intensive care stretchers concentrate margin pools through specialized monitoring integration and extended dwell-time design.
The US FDA enforces 510(k) clearance pathways for powered stretcher mechanisms, while the EU Medical Device Regulation mandates post-market surveillance and traceability systems that elevate compliance costs for exporters. ISO 13485 quality management certification functions as a de facto market access threshold across OECD procurement frameworks. Stakeholders must monitor how reimbursement policy shifts toward outpatient and home-based care reshape volume allocation between hospital capital budgets and mobile service fleet operators.
Market Dynamics
Electric stretcher mechanisms are compressing replacement cycles as hospitals automate patient transport workflows and reduce nursing staff injury claims. The EU MDR's post-market surveillance mandates and US FDA 510(k) clearance pathways are simultaneously elevating compliance costs and accelerating platform consolidation among mid-tier manufacturers.
Growth Catalysts
- EU MDR traceability mandates:Post-market surveillance requirements are forcing fleet renewals across German and French acute care networks as legacy manual platforms lose certification eligibility.
- Aluminum-lithium alloy frames:Lighter structural materials are expanding deployable inventory per ambulance unit, letting emergency medical services carry specialized bariatric and pediatric configurations without payload penalties.
- China's hospital infrastructure modernization:Tier-2 and Tier-3 city hospital construction is absorbing high volumes of cost-optimized powered stretchers as provincial health bureaus standardize equipment procurement.
Market Restraints
- Lithium-ion battery supply concentration:Cell production clustering in East Asia is exposing stretcher manufacturers to raw material volatility and forced technology transfer requirements in Chinese joint ventures.
- EU MDR technical documentation burdens:Small and mid-sized manufacturers face 18-24 month certification timelines that freeze product pipelines and exhaust liquidity reserves.
- Reconditioned equipment substitution:Certified pre-owned stretcher programs in North American Group Purchasing Organizations are capturing budget-conscious hospital segments with 40-60 percent cost discounts.
Strategic Opportunities
- India's Ayushman Bharat expansion:The public health insurance scheme is funding new district hospital construction where manual stretcher demand outstrips domestic manufacturing capacity.
- Pediatric-neonatal transport integration:Incubator-stretcher hybrid platforms for neonatal intensive care units represent an underserved premium segment with limited incumbent specialization.
- ISO 13485 certification arbitrage:Manufacturers achieving quality management certification can access OECD procurement frameworks that exclude uncertified competitors from tender participation.
Industry Challenges
- Electromechanical technician scarcity:Powered stretcher maintenance requires hybrid mechanical-electrical competencies that vocational training programs have not scaled to match installed base growth.
- Legacy fleet integration complexity:Hospital information systems and building infrastructure often lack power outlets, data ports, and elevator dimensions compatible with new electric stretcher specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Stretchers Market |
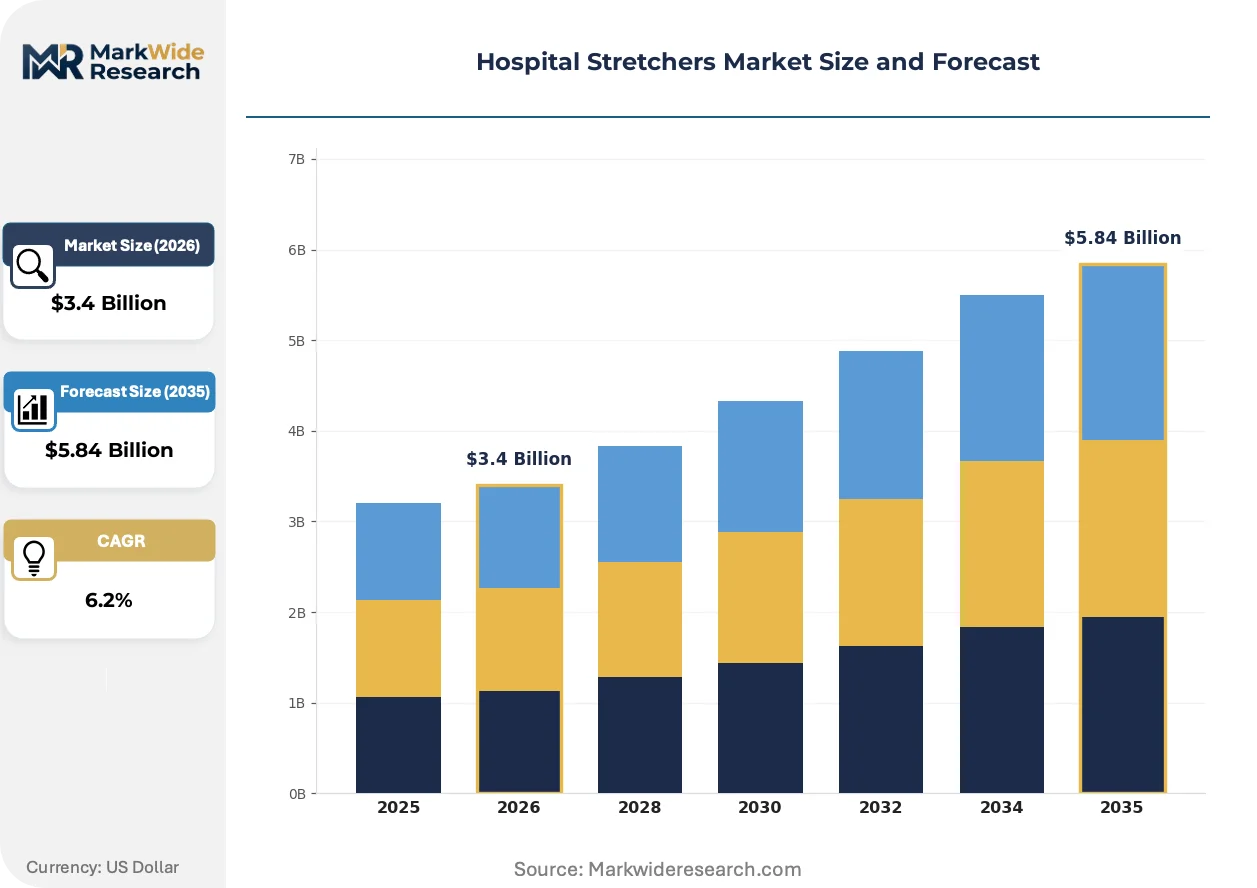
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Stretchers, Electric Stretchers, Bariatric Stretchers, Pediatric Stretchers Application: Emergency Care, Surgical Procedures, Patient Transport, Intensive Care End User: Hospitals, Outpatient Clinics, Ambulance Services, Home Healthcare Technology: Hydraulic Systems, Weight Sensors, Adjustable Frames, Safety Restraints |
| Companies Covered | Medline Industries Inc., Mac Medical Inc., Stryker Corporation, Joerns Healthcare LLC, Anetic Aid Ltd., Hill-Rom Holdings Inc., Narang Medical Limited, Paramount Bed Co. Ltd., Arjo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Stretchers Market Strategic Shifts & Innovations
Sensor-embedded stretcher platforms are compressing the gap between transport equipment and patient monitoring infrastructure. Three developments are restructuring competitive positioning and procurement criteria.
Lithium-polymer battery systems with integrated wireless charging coils are miniaturizing power storage without sacrificing duty cycles. Emergency departments in US academic medical centers are adopting these platforms to eliminate cord-tripping hazards and enable continuous cardiac monitoring during intra-hospital transfers. The technology is compressing form-factor constraints that previously forced trade-offs between powered adjustability and corridor maneuverability.
The EU MDR's Unique Device Identification requirements are mandating serialized traceability across stretcher component supply chains. Manufacturers must now maintain technical documentation for 10-15 years post-market, elevating quality management system investments and disqualifying suppliers with paper-based record systems. German hospital procurement consortiums are prioritizing vendors with demonstrated post-market surveillance capabilities.
Hospital capital equipment leasing is displacing outright purchase for stretcher fleets in US health systems facing Medicare reimbursement compression. Third-party equipment finance firms are bundling maintenance and upgrade clauses that shift obsolescence risk from clinical operations to lessors. This pattern is most visible in California and Texas integrated delivery networks where real estate constraints limit on-site storage for redundant inventory.
Hospital Stretchers Market Segmentation
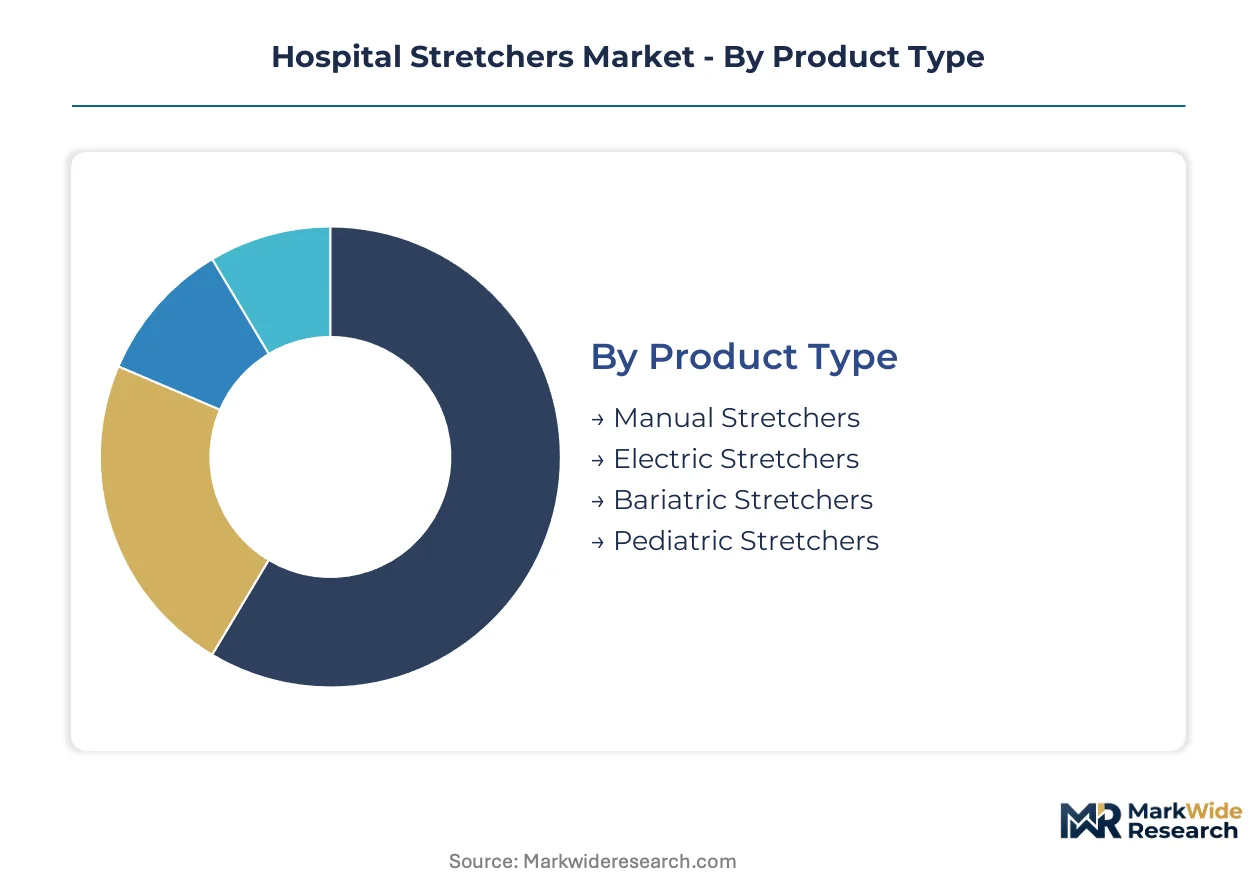
Hospital stretcher procurement splits across technical specifications, clinical workflows, and facility infrastructure requirements. Understanding these segment boundaries clarifies where capital budgets concentrate and which technology investments reshape competitive positioning.
Product Type:
US FDA 510(k) clearance pathways and EU MDR traceability mandates create divergent compliance burdens across powered versus manual platforms, compressing manufacturer margins unevenly.
- Manual Stretchers:Aluminum or steel-framed platforms with polyurethane surfaces requiring no electrical certification. Demand concentrates in India's district hospital construction under Ayushman Bharat, where procurement prioritizes cost-engineered platforms over powered functionality.
- Electric Stretchers:Motorized height-adjustment and Trendelenburg positioning systems with lithium-polymer battery packs. German and French acute care networks are absorbing premium units as EU MDR fleet renewals accelerate and nursing injury claims drive automation investment.
- Bariatric Stretchers:Reinforced frames rated for higher patient weight capacities with wider mattress surfaces.
- Pediatric Stretchers:Scaled-down platforms with integrated safety rails and specialized restraint systems.
Manual stretchers handle the majority of throughput across emerging market tenders; electric stretchers are climbing the fastest on share as OECD hospital infrastructure modernizes.
Application:
Clinical throughput intensity and dwell-time economics segment capital allocation, with emergency departments commanding disproportionate equipment density per square meter.
- Emergency Care:High-frequency transfer platforms with rapid-deployment side rails and oxygen tank mounts. US academic medical centers prioritize sensor-embedded units for continuous cardiac monitoring during intra-hospital transport, compressing replacement cycles.
- Surgical Procedures:Radiolucent carbon-fiber decks compatible with intraoperative imaging and C-arm access. Demand clusters in German university hospitals where hybrid operating room construction elevates specification requirements.
- Patient Transport:Lightweight corridor-optimized designs with tight turning radius specifications.
- Intensive Care:Integrated monitoring mount points and extended battery duty cycles for prolonged immobilization.
Emergency care deploys the highest equipment density; intensive care stretchers capture the steepest margin premiums through specialized configuration.
End User:
Capital ownership structures and reimbursement frameworks fragment procurement authority across facility types and mobile service operators.
- Hospitals:Integrated fleet management with centralized biomedical engineering support and ISO 13485 quality system requirements. China's Tier-2 and Tier-3 city hospital construction absorbs cost-optimized powered units as provincial health bureaus standardize procurement.
- Outpatient Clinics:Limited-space environments favoring collapsible or wall-mounted stretcher solutions with minimal storage footprints.
- Ambulance Services:Payload-constrained platforms requiring aluminum-lithium alloy construction for bariatric and pediatric configuration flexibility without weight penalties.
- Home Healthcare:Lightweight manual platforms for residential setting transfers with narrow doorway compatibility.
Hospitals anchor absolute volume demand; ambulance services are expanding fleet specifications fastest as pre-hospital care protocols tighten.
Technology:
Electromechanical integration depth separates premium positioning from commodity substitution risk in procurement evaluations.
- Hydraulic Systems:Fluid-powered height adjustment without electrical certification requirements. Cost-optimized hospital construction in China's provincial cities absorbs these units where electrical infrastructure reliability varies.
- Weight Sensors:Load-cell integrated decks transmitting patient mass data to electronic health records. US emergency departments adopt these platforms to automate triage documentation and reduce manual data entry errors.
- Adjustable Frames:Mechanical or powered articulation for Trendelenburg, reverse Trendelenburg, and Fowler positioning.
- Safety Restraints:Three-point and five-point harness systems with quick-release mechanisms for rapid patient access.
Adjustable frames represent the installed base majority; weight sensors are gaining share fastest as digital health integration requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German stretcher manufacturers export powered platforms to French and Dutch acute care networks as EU MDR compliance deadlines compress replacement timelines. Cross-border procurement consortiums in the Rhine-Ruhr corridor coordinate fleet standardization across hospital systems.
United States
Academic medical centers in Boston and Houston deploy sensor-embedded stretchers for continuous cardiac monitoring during intra-hospital transfers. The FDA enforces 510(k) clearance pathways for powered mechanisms that elevate documentation burdens. California integrated delivery networks pioneer capital equipment leasing models that shift obsolescence risk to third-party lessors.
Germany
University hospitals in Munich and Berlin absorb premium electric stretchers as EU MDR traceability mandates force legacy manual platform retirements. The country's national medical device regulator enforces post-market surveillance requirements that disqualify paper-based record systems. The Baden-Württemberg industrial cluster concentrates precision electromechanical component fabrication for powered height-adjustment systems.
China
Tier-2 and Tier-3 city hospital construction in Sichuan and Shandong provinces absorbs cost-optimized powered stretchers as provincial health bureaus standardize procurement. The NMPA harmonizes technical documentation requirements with international standards to accelerate market access for domestic manufacturers. The Yangtze River Delta anchors aluminum-lithium alloy frame production for weight-constrained ambulance configurations.
India
District hospital construction under Ayushman Bharat in Maharashtra and Karnataka outstrips domestic manual stretcher manufacturing capacity. The CDSCO streamlines import clearance for powered platforms while requiring ISO 13485 certification for tender participation. The Delhi-NCR corridor hosts regional distribution hubs serving northern state health departments.
France
Paris and Lyon acute care networks accelerate fleet renewals ahead of EU MDR certification deadlines for legacy equipment. The ANSM coordinates with hospital procurement consortiums to prioritize vendors with demonstrated post-market surveillance capabilities. The Île-de-France region concentrates specialized bariatric stretcher demand as obesity rates reshape clinical transport requirements.
Hospital Stretchers Market Key Industry Players
Listed leaders compete with private specialists across capital structure and geographic reach, producing a tiered competitive structure where scale advantages concentrate in North American and European headquarters while cost-engineered specialists dominate emerging market tenders. Three archetypes define positioning: integrated manufacturing conglomerates with captive distribution networks, mid-tier specialists focused on powered transport automation, and regional fabricators competing on procurement price points. Consolidation pressures manifest through strategic partnerships between component suppliers and final assemblers, plus selective technology licensing agreements that transfer electromechanical expertise across regulatory jurisdictions.
Within the integrated manufacturing tier, Stryker Corporation and Hill-Rom Holdings Inc. occupy positions defined by North American distribution density and intensive R&D commitments to powered systems. Narang Medical Limited exemplifies the cost-engineered specialist archetype targeting manual platform demand in emerging market tenders. Joerns Healthcare LLC represents the private mid-tier segment with focused positioning in long-term care and rehabilitation transport workflows.
| Leading Market Players |
|---|
| Medline Industries Inc. |
| Mac Medical Inc. |
| Stryker Corporation |
| Joerns Healthcare LLC |
| Anetic Aid Ltd. |
| Hill-Rom Holdings Inc. |
| Narang Medical Limited |
| Paramount Bed Co. Ltd. |
| Arjo |
| Others |
Cost & Logistics Intelligence
Aluminum-lithium alloy frame production at scale anchors supply concentration in the Yangtze River Delta, compressing unit economics for powered stretcher manufacturers while establishing price floors that manual platform specialists in South Asia struggle to match. EU MDR compliance investments and lithium-ion battery sourcing costs transmit upward through electric stretcher tiers, widening spreads against hydraulic alternatives.
Pricing Analysis
Next-generation sensor-embedded electric stretchers command substantial premiums over current-generation powered platforms, while prior-generation manual frames face accelerating price erosion in emerging market tenders. Three-tier pricing structure across premium electric, standard hydraulic, and economy manual levels stratifies procurement pools, with ISO 13485 certification and FDA 510(k) clearance functioning as the primary price differentiation drivers. Cost compression in the manual tier intensifies because India's Ayushman Bharat district hospital construction absorbs volume at aggressive tender pricing. Ambulance services exhibit the highest price sensitivity due to fleet-scale procurement and payload-constrained specification trade-offs.
Supply Chain Analysis
Strategic stockpiling of lithium-polymer battery cells distinguishes stretcher manufacturers with supply security from those running lean inventory exposed to East Asian production volatility. Component sourcing concentrates in China for aluminum-lithium alloy frames, Germany for precision electromechanical actuators, and South Korea for battery cell supply. Raw material dependencies span lithium carbonate, medical-grade aluminum alloys, and polyurethane coating formulations. Single-source vulnerability in East Asian battery cell production exposes manufacturers to forced technology transfer requirements and raw material volatility. Distribution runs through hospital procurement consortiums in OECD markets and provincial health bureau tenders in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical technician scarcity constrains powered stretcher maintenance capacity, creating competitive advantage for manufacturers who embed predictive diagnostics and remote service architectures into platform design.
For Market Incumbents: Secure backward integration into lithium-polymer battery pack assembly to reduce exposure to East Asian cell supply concentration and capture margin pools currently leaking to third-party power system suppliers. Defend installed base positions by embedding ISO 13485-certified predictive maintenance software that locks hospital biomedical engineering teams into proprietary service ecosystems, neutralizing reconditioned equipment substitution threats from certified pre-owned stretcher programs. For New Entrants and Emerging Players: Lead with pediatric-neonatal incubator-stretcher hybrid platforms where incumbent specialization remains thin and premium pricing tolerance runs highest in academic medical center NICUs. India's district hospital construction under Ayushman Bharat represents the most penetrable geography, with manual stretcher demand outstripping domestic manufacturing capacity and CDSCO import clearance pathways streamlining market access for ISO 13485-certified foreign suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical component specialists with demonstrated FDA 510(k) clearance track records and established hospital GPO contract relationships over pure-play manual fabricators facing commodity substitution. Long-term viability hinges on software-enabled service revenue attachment and regulatory compliance infrastructure that survives EU MDR documentation burdens. Watch lithium-ion battery supply contract renegotiation cycles as inflection indicators for margin compression or expansion across powered stretcher portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates US market access for powered height-adjustment mechanisms against manual platform competitors. |
| CE Marking Pathway | Unlocks EU MDR-compliant fleet renewal contracts across German and French acute care networks. |
| Hospital System Partnership | Secures multi-year fleet management agreements with integrated delivery networks in California and Texas. |
| Software Companion Development | Enables predictive maintenance revenue streams that offset hardware margin compression in competitive tenders. |
| Reimbursement Strategy | Aligns stretcher automation investments with Medicare outpatient payment shifts affecting capital equipment leasing adoption. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating hospital purchasing committee members, ambulance fleet managers, biomedical engineering directors, and GPO contracts specialists alongside stretcher manufacturing executives and electromechanical component suppliers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement consortium contract awards, and CMS Medicare reimbursement policy releases. Bottom-up unit shipment estimates triangulated against top-down capital expenditure projections across acute care infrastructure.
Across the analysis window, the forecasting framework modeled volume and value outputs through product type segmentation spanning manual, electric, and specialized bariatric platforms; application segmentation across emergency care, surgical, and intensive care workflows; and end-user segmentation distinguishing hospital systems from ambulance services and outpatient clinics. CAGRs were derived from installed base replacement cycle compression analysis and automation penetration curve fitting, with specific inputs including nursing staff injury claim cost trajectories and EU MDR compliance deadline impacts on fleet renewal timing.
The analysis sits within stated boundaries; outcomes outside sustained hospital infrastructure modernization spending and stable lithium-ion battery supply conditions would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and reimbursement policy continuity. Practitioners should keep alternative scenarios live as EU MDR post-market surveillance requirements and Medicare payment model shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical CO2 Carboxytherapy Machine Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
North America Nuclear Medicine Equipment Market